
 Medical Nutrition Market | 2026-2036
Medical Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Nutrition Market Intelligence
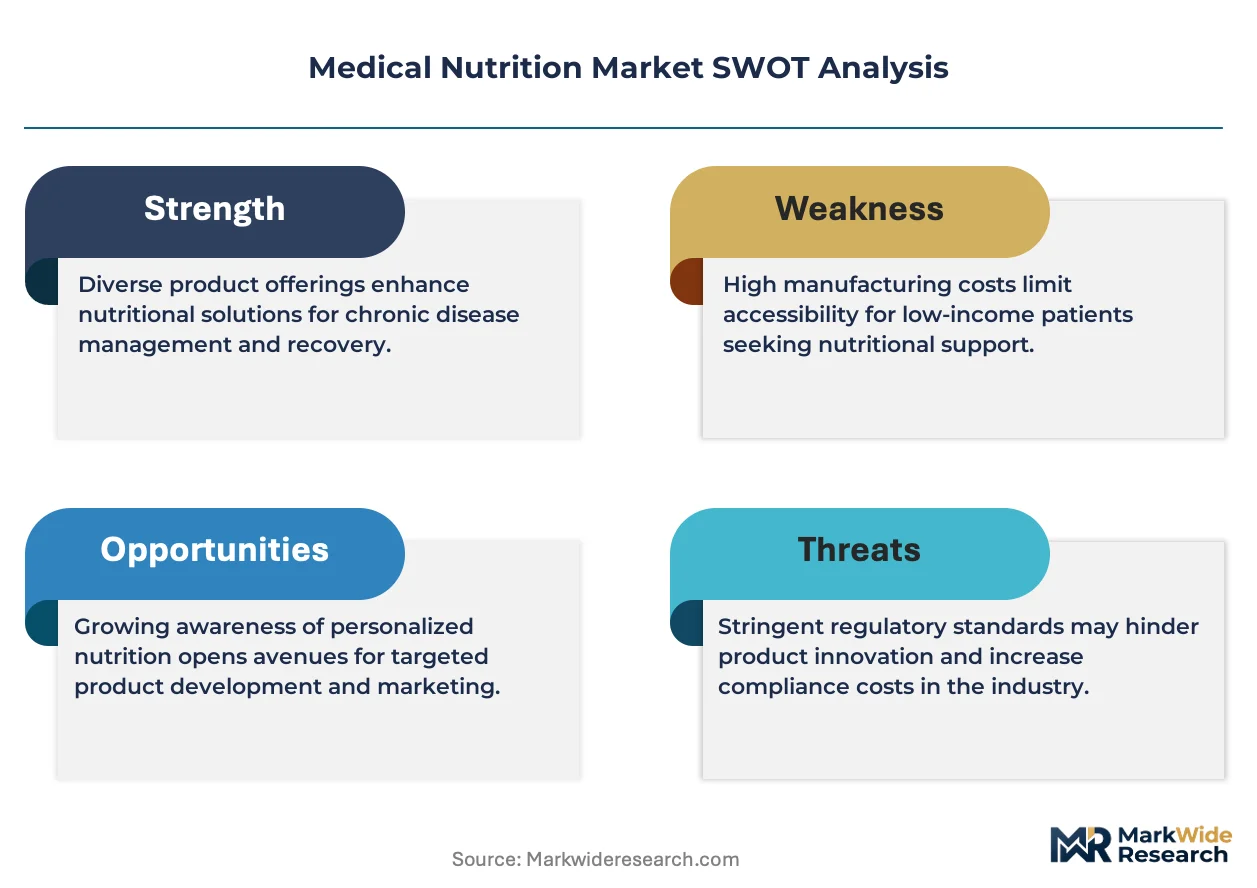
Precision fermentation and enzymatic protein modification is tilting formulation pipelines toward bioactive peptide-enriched medical nutrition. Abbott Laboratories leverages its vertically integrated enteral platform to sustain manufacturing scale across North American and European hospital networks. Nestlé Health Science anchors its portfolio in disease-specific oral supplements, while Fresenius Kabi AG dominates parenteral lipid emulsion supply to intensive care units worldwide.
Medical nutrition encompasses clinically formulated substrates—amino acid solutions, structured lipids, fiber-modified enteral blends, and micronutrient modules—engineered to manage metabolic stress, malabsorption, or disease-induced catabolism under healthcare supervision. Oral nutritional supplements now capture the broadest patient touchpoints, though parenteral nutrition retains the highest per-patient value concentration in critical care settings. Among application areas, chronic disease support is expanding fastest as diabetes, oncology, and renal protocols integrate nutrition as a standard-of-care pillar.
The FDA exercises premarket oversight through its medical food distinction under the Orphan Drug Act, while the EMA and national European regulators enforce compositional standards through the Food for Special Medical Purposes framework. These dual regulatory architectures elevate barriers for new entrants lacking clinical validation infrastructure. Stakeholders must monitor evolving reimbursement codes for home-based nutrition therapy as payers recalibrate cost-of-care models away from institutional settings.
Market Dynamics
Hospital-at-home reimbursement expansion is compressing institutional purchasing volumes while forcing manufacturers to reconfigure distribution networks for direct-to-patient fulfillment. This structural shift demands new cold-chain logistics, specialized compounding partnerships, and regulatory compliance across decentralized care settings.
Growth Catalysts
- Orphan Drug Act medical food pathway:The FDA's distinct regulatory channel accelerates commercialization timelines for disease-specific formulations targeting inborn errors of metabolism.
- Enzymatic protein hydrolysis:This bioprocessing technology enables cost-efficient production of hypoallergenic peptide-based enteral formulas for pediatric and geriatric populations.
- Germany:Hospital-at-home policies and statutory health insurance reimbursement expansion for parenteral nutrition are accelerating patient discharge protocols.
Market Restraints
- Fish oil and soybean lipid input volatility:Structured lipid emulsions depend on marine and agricultural commodities subject to climate-driven supply fluctuations and trade restrictions.
- European manufacturing concentration:Parenteral nutrition compounding facilities cluster in Germany, Switzerland, and France, creating single-source vulnerability for critical care supply.
- EMA Food for Special Medical Purpose compositional rigidity:Fixed nutrient ratio requirements limit formulation innovation for rare disease subpopulations.
Strategic Opportunities
- India:CDSCO's streamlined medical food registration pathway and expanding private hospital networks create entry points for oral nutritional supplement localization.
- Continuous glucose monitoring-nutrition algorithm convergence:Integrated metabolic sensing and automated enteral delivery systems enable real-time glycemic management in diabetes and critical care protocols.
- Direct-to-patient pharmacy channels:Specialty pharmacy networks bypass traditional hospital procurement, capturing margin from reimbursed home-based parenteral nutrition.
Industry Challenges
- Clinical nutrition specialist workforce gaps:Certified nutrition support clinicians remain scarce relative to expanding home infusion service demand.
- Multi-jurisdiction pharmacovigilance reporting:Divergent FDA, EMA, and national European adverse event documentation requirements strain regulatory affairs capacity.
- Legacy hospital electronic health record integration:Nutrition ordering modules require costly customization to interface with automated compounder safety systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Nutrition Market |
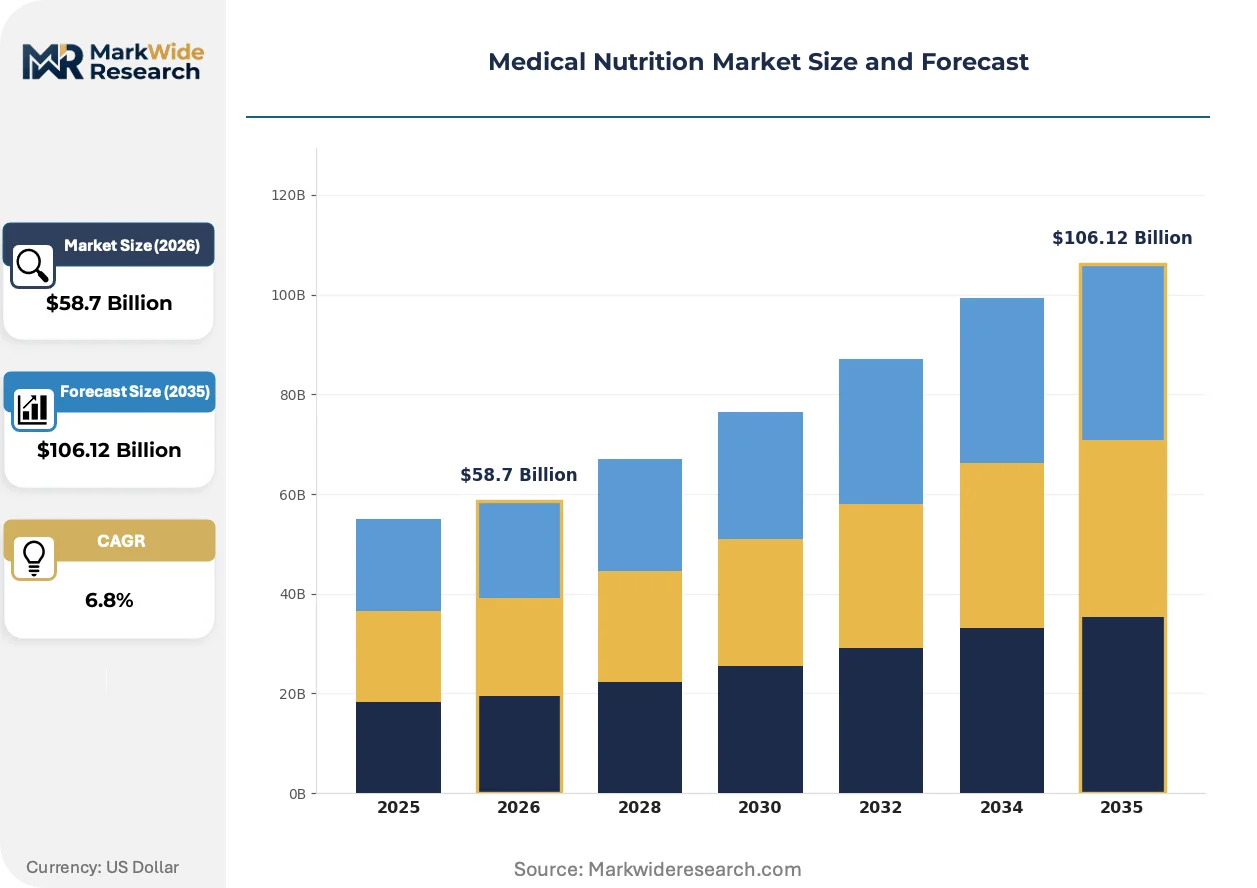
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enteral Nutrition, Parenteral Nutrition, Oral Nutritional Supplements, Modular Nutrients Application Area: Malnutrition Management, Chronic Disease Support, Critical Care Nutrition, Immunonutrition, Geriatric Nutrition End User: Hospitals, Home Healthcare, Rehabilitation Centers, Long-term Care Facilities Delivery Mode: Tube Feeding, Intravenous Feeding, Oral Consumption, Fortified Foods |
| Companies Covered | Abbott Laboratories, Nestlé Health Science, Danone (Nutricia), Fresenius Kabi AG, Baxter International, B. Braun SE, Reckitt Benckiser Group PLC, Ajinomoto Co., Inc., Arla Foods Ingredients Group P/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Nutrition Market Strategic Shifts & Innovations
Precision fermentation platforms and AI-driven metabolic modeling are converging to reshape how bioactive peptides and condition-specific micronutrient matrices enter clinical formulation pipelines. These technologies compress development cycles while enabling patient stratification at previously impossible granularity.
Precision fermentation is hybridizing microbial strain engineering with continuous bioprocessing to produce bioactive milk oligosaccharides and human milk-equivalent proteins for neonatal and immunocompromised patient formulas. Pediatric intensive care units and neonatal networks in the Netherlands and Denmark are piloting these substrates at scale. The technology is hybridizing cost structures, collapsing the premium pricing gap between synthetic and bovine-derived bioactives.
The EU's Corporate Sustainability Reporting Directive now mandates supply chain due diligence disclosures for medical food manufacturers operating across member states. This compels ingredient traceability investments and carbon footprint auditing from lipid suppliers through finished goods distribution. Parenteral nutrition producers with European manufacturing footprints face the steepest compliance cost escalation.
Home infusion providers are consolidating purchasing power through group purchasing organizations, displacing fragmented hospital-based procurement for parenteral nutrition. Specialty pharmacy networks in the United States and Germany now negotiate directly with lipid emulsion and amino acid solution manufacturers. This concentration is most visible in diabetes and oncology nutrition protocols where payers mandate site-of-care cost neutrality.
Medical Nutrition Market Segmentation
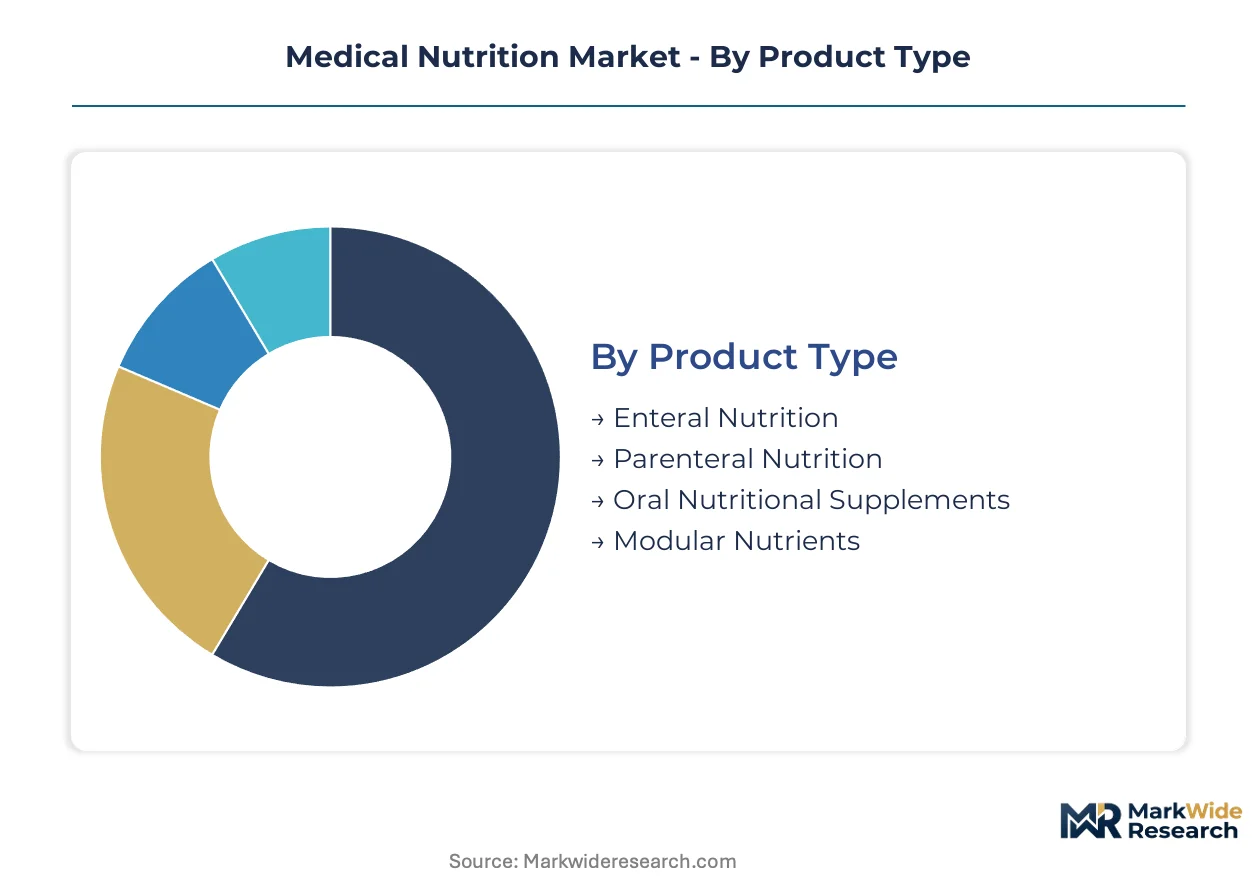
Medical nutrition segmentation reveals divergent inventory velocities across product categories. Enteral and parenteral formulations rotate slowly due to compounding lead times and cold-chain requirements. Oral supplements and modular nutrients turn faster, responding to direct-to-patient pharmacy demand and home healthcare procurement cycles.
Product Type:
Cycle times vary dramatically across formulation complexity, from sterile compounding to shelf-stable powders.
- Enteral Nutrition:Polymeric and peptide-based liquid formulas delivered via nasogastric or gastrostomy tubes. Demand concentrates in US and German hospital-at-home networks where CMS and statutory health insurance reimbursement expansion accelerates patient discharge. Abbott Laboratories and Nestlé Health Science dominate institutional supply contracts.
- Parenteral Nutrition:Sterile amino acid-glucose-lipid emulsions for patients with non-functional gastrointestinal tracts. Fresenius Kabi AG controls lipid emulsion supply to intensive care units across Switzerland, Germany, and France, with manufacturing concentration creating single-source vulnerability.
- Oral Nutritional Supplements:Disease-specific beverages and powders for ambulatory patients.
- Modular Nutrients:Single-nutrient additives including protein, fiber, or electrolyte modules.
Oral Nutritional Supplements anchors the volume base while Parenteral Nutrition gains share at the steepest rate.
Application Area:
Margin profiles stratify sharply between acute intervention protocols and chronic maintenance regimens.
- Chronic Disease Support:Diabetes, oncology, and renal disease protocols integrating nutrition as standard-of-care pillars. Germany's hospital-at-home policies and expanded statutory reimbursement accelerate adoption. Continuous glucose monitoring-nutrition algorithm convergence enables real-time metabolic management.
- Critical Care Nutrition:Immune-modulating and organ-specific substrates for mechanically ventilated patients. Demand clusters in Swiss and French tertiary intensive care units where EMA Food for Special Medical Purpose standards enforce compositional rigidity.
- Malnutrition Management:Screening-triggered intervention protocols in acute and post-acute settings.
- Immunonutrition:Arginine, omega-3, and nucleotide-enriched formulas for surgical and trauma patients.
- Geriatric Nutrition:Texture-modified and micronutrient-dense products for sarcopenia and frailty prevention.
Malnutrition Management generates the highest patient touchpoint volume, though Chronic Disease Support climbs fastest as payers mandate nutrition integration into diabetes and oncology pathways.
End User:
Procurement authority is shifting from centralized hospital purchasing to fragmented home infusion and specialty pharmacy channels.
- Home Healthcare:Home infusion providers and visiting nurse services administering enteral and parenteral nutrition. US and German group purchasing organizations consolidate buying power, displacing fragmented hospital procurement. Cold-chain logistics and specialized compounding partnerships dominate operational requirements.
- Hospitals:Acute care institutions with centralized pharmacy and nutrition support teams. Volumes compress as reimbursement expansion accelerates discharge to home settings.
- Rehabilitation Centers:Post-acute facilities managing transition from institutional to home-based feeding.
- Long-term Care Facilities:Nursing homes and skilled nursing facilities with texture-modified diet protocols.
Hospitals retain the highest per-patient value concentration, yet Home Healthcare expands most quickly as site-of-care economics favor decentralized administration.
Delivery Mode:
Technology integration separates automated safety systems from conventional administration methods.
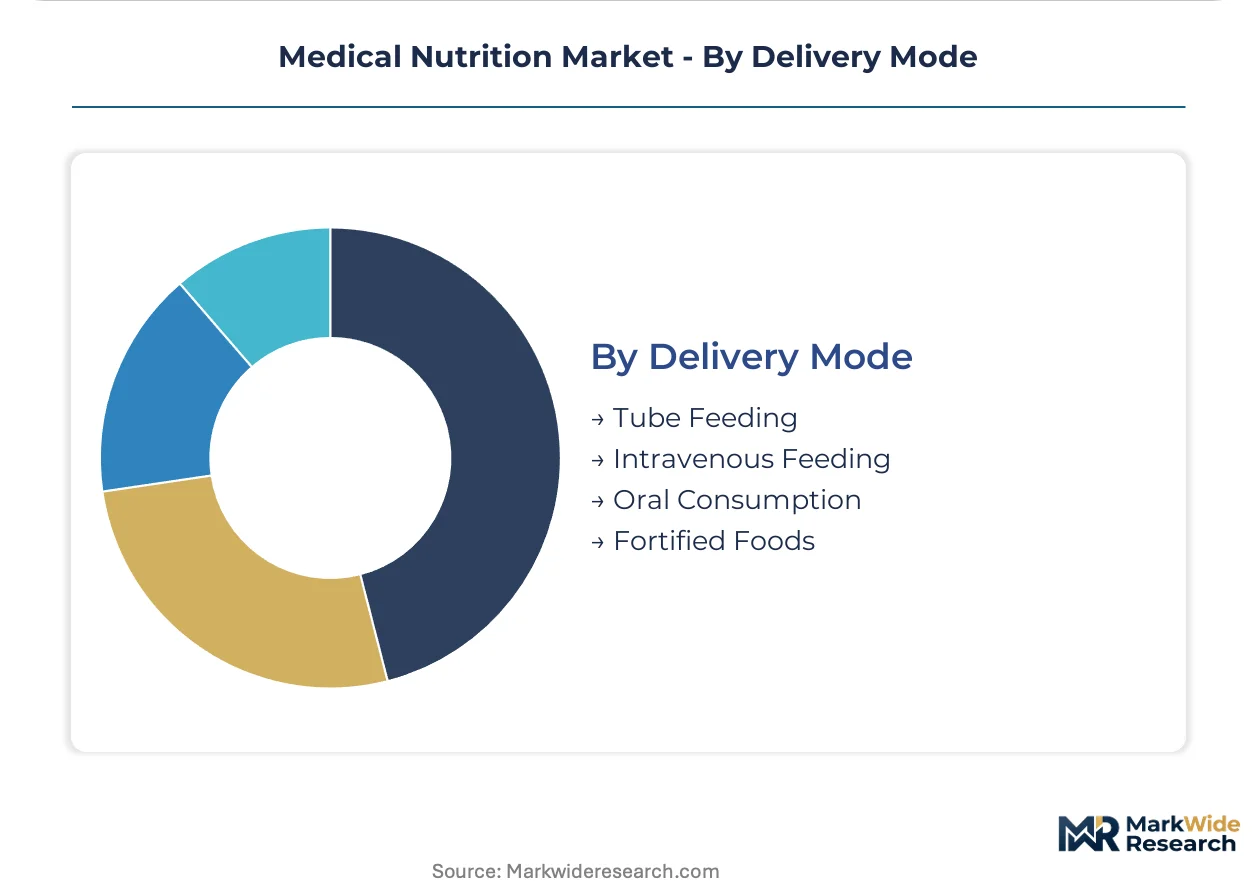
- Tube Feeding:Enteral delivery via nasogastric, nasoduodenal, or percutaneous endoscopic gastrostomy tubes. Pump technology and connectivity modules integrate with electronic health record ordering systems, requiring costly customization for automated compounder safety interfaces.
- Intravenous Feeding:Central venous catheter administration of parenteral formulations. Manufacturing concentrates in German, Swiss, and French compounding facilities with EMA oversight.
- Oral Consumption:Standard beverage and powder reconstitution for ambulatory patients.
- Fortified Foods:Commercial food products with added micronutrients and macronutrients.
Oral Consumption captures the broadest patient population, while Intravenous Feeding commands premium positioning in critical care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in medical nutrition tilt toward net-import dependence in emerging markets while established manufacturing clusters in Germany, Switzerland, and the United States anchor export supply. Raw material sourcing for lipid emulsions and amino acid solutions concentrates in agricultural and marine commodity regions, creating price transmission volatility across finished formulation costs.
United States
Hospital-at-home reimbursement expansion through CMS accelerates demand for enteral and parenteral nutrition in decentralized settings. The FDA maintains premarket oversight through its medical food distinction under the Orphan Drug Act, tightening formulation transparency mandates. Manufacturing and distribution clusters concentrate in Illinois and Massachusetts, where Abbott Laboratories anchors vertically integrated enteral production for North American hospital networks.
Germany
Aging demographics and statutory health insurance reimbursement expansion for home-based parenteral nutrition compress acute care lengths of stay. The country's national pharmaceutical regulator enforces compositional standards through the Food for Special Medical Purposes framework alongside EMA oversight. Parenteral nutrition compounding facilities cluster in Hesse and Baden-Württemberg, with Fresenius Kabi AG dominating lipid emulsion supply to intensive care units.
Switzerland
Precision fermentation platforms for bioactive peptide production attract bioprocessing investment from neonatal and immunocompromised patient formula developers. Swissmedic maintains stringent manufacturing standards for sterile parenteral formulations. The Basel-Zurich corridor hosts specialized lipid emulsion and amino acid solution production, serving as a critical supply node for European critical care networks.
India
Expanding private hospital networks and rising chronic disease prevalence drive oral nutritional supplement localization opportunities. CDSCO's streamlined medical food registration pathway reduces entry barriers for multinational entrants. Manufacturing investment concentrates in Maharashtra and Gujarat, where domestic formulators seek partnerships to capture share in diabetes and oncology nutrition protocols.
Japan
Geriatric nutrition demand intensifies as sarcopenia and frailty prevention protocols integrate into standard elderly care. METI and PMDA coordinate on functional food and medical food regulatory convergence. Industrial activity clusters in the Kansai region around Osaka, where Ajinomoto Co., Inc. anchors amino acid solution production for parenteral and enteral applications.
Medical Nutrition Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated nutrition platforms and specialized compounding networks. Tiered competitive positioning separates multinational healthcare conglomerates with captive hospital contracts from regional specialists serving home infusion channels. Strategic archetypes include disease-specific oral supplement developers, sterile parenteral compounders, and precision fermentation bioactive producers. Dominant competitive moves encompass backward integration into lipid and protein raw material sourcing, plus specialty pharmacy partnership networks for direct-to-patient fulfillment.
Among diversified healthcare conglomerates, Abbott Laboratories and Nestlé Health Science exemplify the vertically integrated platform archetype, while Fresenius Kabi AG occupies a specialized position in sterile parenteral compounding. These three entities represent distinct strategic postures: Abbott anchors enteral manufacturing scale across hospital networks, Nestlé concentrates disease-specific oral supplement portfolios, and Fresenius Kabi dominates critical care lipid emulsion supply chains. Their collective positioning illustrates how scale, specialization, and therapeutic focus segment competitive terrain.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé Health Science |
| Danone (Nutricia) |
| Fresenius Kabi AG |
| Baxter International |
| B. Braun SE |
| Reckitt Benckiser Group PLC |
| Ajinomoto Co., Inc. |
| Arla Foods Ingredients Group P/S |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Antwerp pharmaceutical corridor channels lipid emulsion and amino acid solution freight costs directly into parenteral nutrition price differentiation, with German and Swiss manufacturing concentration amplifying procurement leverage for hospital networks against home healthcare buyers facing distribution surcharges.
Pricing Analysis
Home healthcare agencies anchor three-tier pricing structure across premium, standard, and economy levels in medical nutrition procurement. Price differentiation separates CMS-reimbursed hospital-at-home formulations from institutional volume contracts and cash-pay ambulatory supplements. Pricing pressure stems from group purchasing organization consolidation among US and German home infusion providers. Hospital procurement committees demonstrate lowest price sensitivity due to captive reimbursement pathways, while direct-to-patient pharmacy channels face acute margin compression from cold-chain logistics costs.
Supply Chain Analysis
Sterile compounding capacity concentrates at Fresenius Kabi AG facilities in Hesse and Baden-Württemberg, with Baxter International and B. Braun SE anchoring secondary production nodes in Switzerland and France. Raw material sourcing draws from marine lipid fisheries in Peru and Norway, plus agricultural soy processing in the United States and Brazil. Single-source vulnerability in European parenteral lipid emulsion manufacturing creates supply chain risk from regulatory inspection delays. Distribution runs through specialty pharmacy networks bypassing traditional hospital procurement for reimbursed home-based nutrition therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical nutrition sits in early-cycle expansion as hospital-at-home reimbursement policies penetrate chronic disease protocols, with diabetes and oncology nutrition integration representing the primary adoption tailwind.
For Market Incumbents: Harden enteral manufacturing scale through backward integration into peptide hydrolysis capacity and precision fermentation bioactives. Abbott Laboratories and Nestlé Health Science must defend against specialty pharmacy disintermediation by embedding direct-to-patient fulfillment partnerships. Certification investment in FDA medical food pathway infrastructure preserves orphan disease formulation exclusivity against enzymatic protein modification entrants.
For New Entrants and Emerging Players: Mid-market oral nutritional supplements in India's Maharashtra and Gujarat private hospital networks represent the most penetrable entry point for multinational localization. CDSCO streamlined registration reduces regulatory lag versus European Food for Special Medical Purpose compliance burden. Continuous glucose monitoring-nutrition algorithm convergence offers partnership leverage with diabetes device manufacturers seeking metabolic management software companions.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core nutrition assets amid portfolio rationalization. Long-term viability across the projection horizon rests on reimbursement code expansion for home-based parenteral therapy. Watch CMS site-of-care cost neutrality mandates as the signal for accelerated specialty pharmacy consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioactive peptide production collapses synthetic-bovine pricing gaps for neonatal formulas in Dutch and Danish pediatric networks. |
| Specialty Pharmacy Partnership | Direct-to-patient fulfillment captures margin from CMS-reimbursed home parenteral nutrition bypassing hospital procurement. |
| FDA Medical Food Pathway Investment | Orphan Drug Act regulatory infrastructure accelerates commercialization timelines for inborn error of metabolism formulations. |
| Backward Integration into Lipid Sourcing | Upstream control over fish oil and soybean supply buffers structured emulsion producers from climate-driven commodity volatility. |
| Continuous Glucose Monitoring Integration | Real-time metabolic sensing partnerships with diabetes device manufacturers enable automated enteral delivery algorithm development. |
Research Approach
The analysis maps enteral nutrition, parenteral nutrition, oral supplements, and modular nutrient sub-sectors, each validated through nutrition support clinicians, hospital pharmacy directors, home infusion procurement managers, and specialty pharmacy network executives. Primary interview findings triangulate against FDA medical food registrations, EMA Food for Special Medical Purpose submissions, CMS reimbursement code databases, and GPO contract repositories. Bottom-up patient population modeling and top-down manufacturer revenue aggregation converge across the analysis window.
Assumptions held reimbursement policy expansion and regulatory framework stability constant while varying chronic disease prevalence projections and hospital-at-home adoption curves. Segmentation dimensions span product type complexity, application area acuity, end-user procurement authority, and delivery mode technology integration. CAGRs derive from patient volume extrapolation against per-patient value concentration trends, with precision fermentation cost curves and lipid commodity indices feeding sensitivity testing.
Stress conditions across CMS site-of-care neutrality implementation speed, EMA compositional rigidity enforcement, and marine lipid supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with revision triggers tied to regulatory filing milestones and reimbursement code updates. Quarterly review of hospital-at-home discharge protocol adoption and specialty pharmacy GPO contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
US Clinical Nutrition Market