
 North America Clinical Nutrition Market | 2026-2036
North America Clinical Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
North America Clinical Nutrition Market Analytics
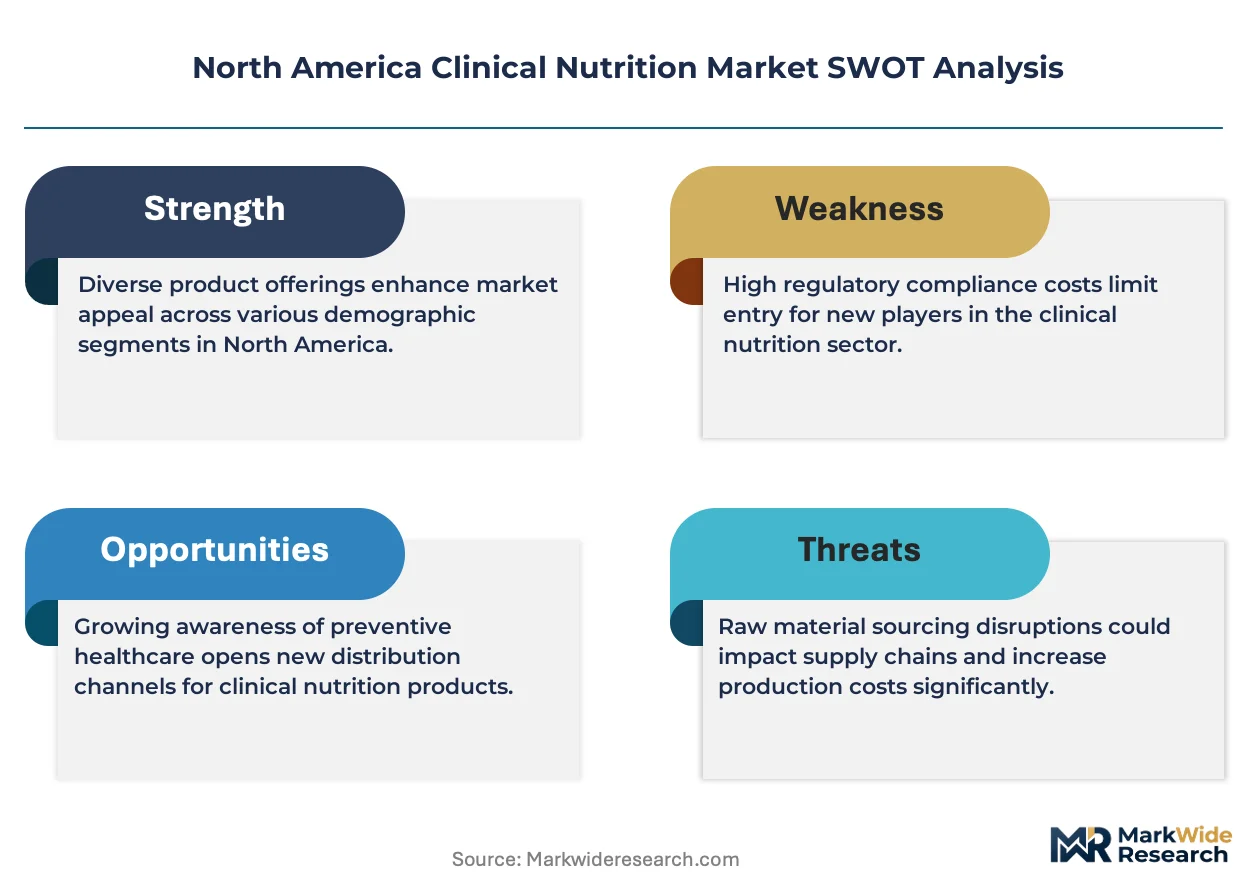
The U.S. EPA's sustainable packaging directives and hospital green-procurement mandates is repositioning clinical nutrition supply chains toward reduced-plastic delivery formats. Abbott Laboratories leverages its vertically integrated manufacturing footprint to control enteral formula production from raw ingredient sourcing through sterile filling. Nestlé Health Science anchors its North American position through specialized metabolic nutrition platforms targeting rare disease states. Fresenius Kabi competes aggressively in parenteral nutrition bags and compounding services for acute care settings.
Clinical nutrition encompasses medically formulated nutrients delivered enterally, parenterally, or orally to patients unable to meet metabolic requirements through conventional diet, with formulations typically specifying protein density, caloric concentration, osmolality, and micronutrient completeness against disease-specific metabolic demands. Enteral nutrition leads product type volume as hospitals standardize tube-feeding protocols for ICU and post-surgical recovery, while specialty nutrition commands premium positioning in metabolic and inherited-disorder management. Homecare dominates end-user growth trajectory as payors shift reimbursement toward outpatient management of chronic conditions including cancer, diabetes, and kidney disorders.
The FDA regulates medical foods and enteral formulas under distinct compliance pathways, while Health Canada and the USDA jointly influence cross-border ingredient standards and nutritional content claims. Medicare and Medicaid reimbursement policies determine market access velocity for oral nutritional supplements and parenteral feeding services across U.S. care settings. Stakeholders must monitor evolving CMS coverage determinations and state-level scope-of-practice rules for home infusion nutrition as these frameworks reshape provider economics and patient access models.
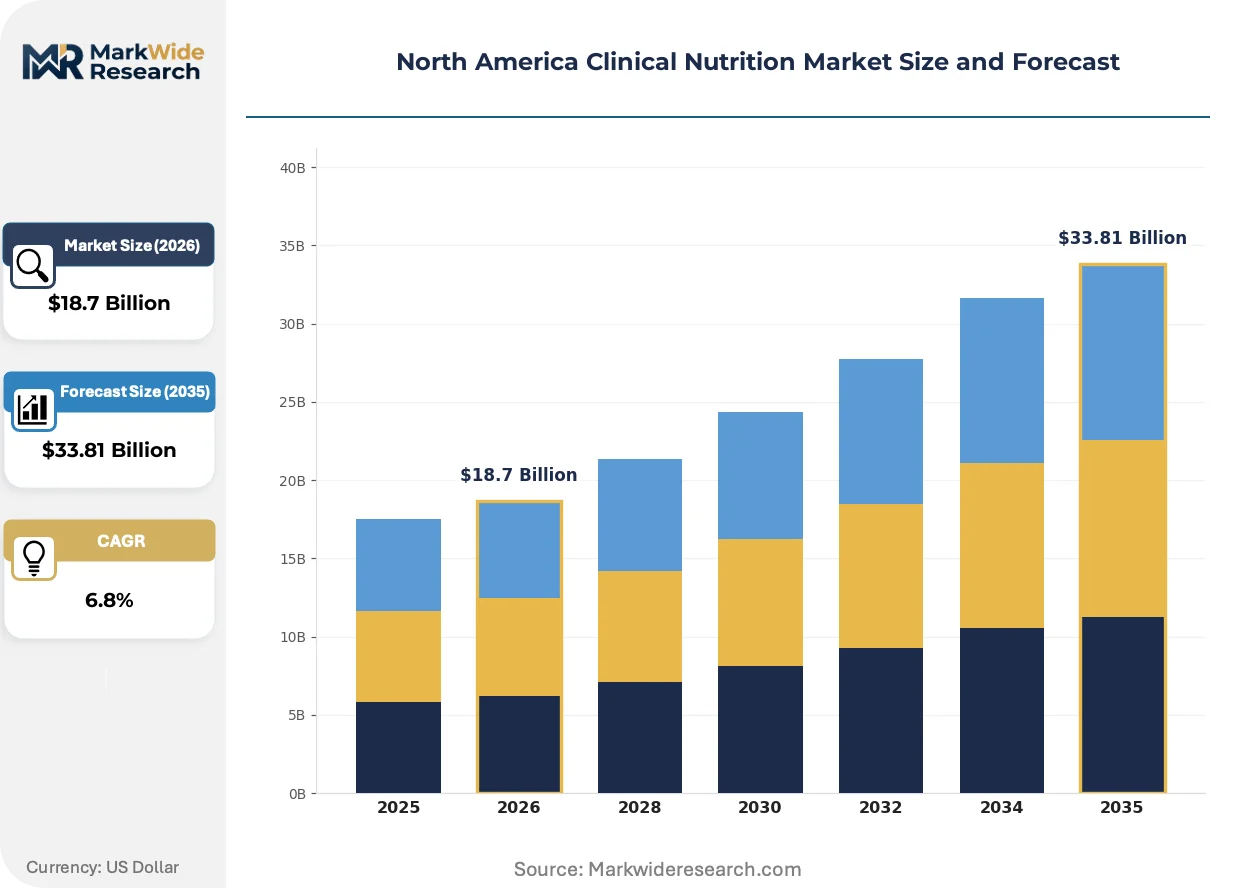
Market Dynamics
CMS reimbursement shifts toward home-based enteral and parenteral nutrition are rewiring provider economics across U.S. and Canadian care networks, compressing acute-care margins while expanding outpatient service infrastructure.
Growth Catalysts
- Medicare Part B Home Infusion Coverage:Expanded reimbursement for parenteral nutrition administered outside hospital settings is accelerating patient discharge protocols and homecare provider capacity investments across the United States.
- Canada's aging demographic concentration:Ontario and British Columbia long-term care facilities are building dedicated nutrition support teams to manage dysphagia and malnutrition in geriatric populations.
- Enteral feeding standardization:ICU protocols adopting early enteral nutrition within 24-48 hours post-surgery are driving formula volume through hospital purchasing cooperatives.
Market Restraints
- Aluminum contamination thresholds:FDA guidance on parenteral nutrition aluminum content is forcing reformulation of multi-chamber bags and trace mineral additives.
- Specialty amino acid supply concentration:Three manufacturers control crystalline L-amino acid production for metabolic formulas, creating single-source vulnerability.
- Home infusion nursing shortages:Licensed practical nurse availability constraints in Texas and Florida are capping patient enrollment in outpatient parenteral programs.
Strategic Opportunities
- Pediatric metabolic rare diseases:U.S. state newborn screening expansions for disorders like phenylketonuria and maple syrup urine disease are creating captive demand for disease-specific formulas.
- Plant-based protein enteral formulations:Pea and rice protein isolates meeting renal and diabetic macronutrient profiles are penetrating the premium formula segment.
- Remote patient monitoring integration:Bluetooth-enabled feeding pumps transmitting intake data to hospital command centers are enabling proactive intervention and reducing emergency readmissions.
Industry Challenges
- Compounding pharmacy 503B compliance:FDA facility inspections and sterility testing requirements are extending lead times for customized parenteral admixtures.
- Electronic health record interoperability:Nutrition assessment documentation across Epic, Cerner, and Meditech systems lacks standardized data fields, complicating care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Clinical Nutrition Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enteral Nutrition, Parenteral Nutrition, Specialty Nutrition, Oral Nutritional Supplements End User: Hospitals, Homecare, Nursing Facilities, Outpatient Clinics Application: Cancer, Liver Disease, Diabetes, Kidney Disorders Delivery Mode: Liquid, Powder, Ready-to-Drink, Soft Chew |
| Companies Covered | Abbott Laboratories, Nestlé Health Science, Fresenius Kabi, Baxter International, Danone Nutricia, B. Braun Melsungen, Ajinomoto Cambrooke, Medtrition Inc., Perrigo Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Clinical Nutrition Market Evolving Landscape
Artificial intelligence and connected device ecosystems are transforming how clinical nutrition is prescribed, monitored, and reimbursed across North American healthcare networks.
Smart enteral feeding pumps equipped with load cells and flow sensors are automating real-time occlusion detection and residual volume monitoring. Hospital systems in California and New York are deploying these devices in step-down units to reduce nursing documentation burden. This automation is compressing adverse event response times from hours to minutes while generating structured data streams for quality improvement initiatives.
Health Canada's updated Food and Drug Regulations for medical foods, effective 2023, are mandating premarket notification for novel enteral formulas claiming disease-specific benefits. Manufacturers must now submit clinical evidence packages demonstrating efficacy in target patient populations. The specialty metabolic nutrition segment faces the steepest compliance burden, with several U.S. exporters pausing Canadian market entry pending regulatory clarity.
Hospital purchasing coalitions are consolidating formula procurement through single-source agreements with price protection clauses. These arrangements displace traditional distributor relationships and shift inventory risk to manufacturers. The Southeast United States—particularly Georgia and North Carolina—exhibits the most concentrated buying power, with regional health systems negotiating direct contracts bypassing group purchasing organizations entirely.
North America Clinical Nutrition Market Segmentation
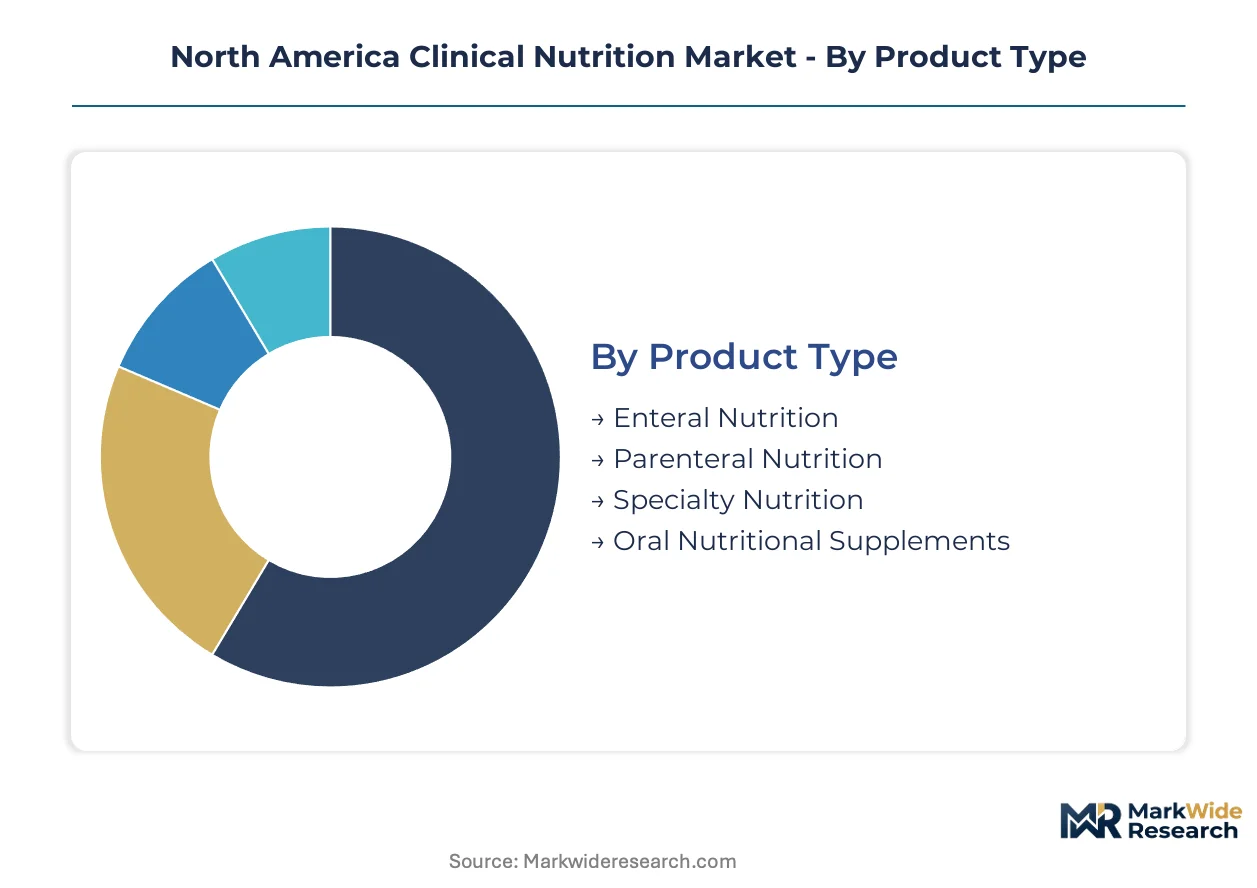
Clinical nutrition segmentation reveals distinct procurement patterns across North American care settings. Product specifications, reimbursement pathways, and patient acuity levels create divergent margin structures and competitive dynamics within each category.
Product Type:
Hospital purchasing cooperatives and homecare providers select formulations based on delivery route compatibility and metabolic precision requirements.
- Enteral Nutrition:Tube-delivered formulas specifying protein density, caloric concentration, and osmolality for patients with functional gastrointestinal tracts. ICU standardization protocols in U.S. Southeast hospital networks are driving volume through 24-48 hour post-surgical feeding initiation mandates.
- Specialty Nutrition:Disease-specific formulations targeting rare metabolic disorders with precise amino acid profiles and restricted micronutrient content. U.S. state newborn screening expansions for phenylketonuria and maple syrup urine disease are generating captive demand in pediatric segments.
- Parenteral Nutrition:Intravenous formulations for patients with non-functional GI tracts, requiring sterile compounding and aluminum content compliance under FDA guidance.
- Oral Nutritional Supplements:Ambulatory formulations for patients maintaining partial oral intake, positioned between medical foods and dietary supplements under distinct regulatory pathways.
Enteral nutrition leads volumes today; specialty nutrition is gaining share fastest.
End User:
Reimbursement velocity and care coordination complexity separate institutional buyers from decentralized home-based providers.
- Homecare:Medicare Part B reimbursement expansion for outpatient enteral and parenteral administration is accelerating patient discharge velocity. Licensed practical nurse shortages in Texas and Florida are constraining enrollment growth in parenteral programs.
- Hospitals:Acute care facilities standardizing early enteral nutrition protocols are consolidating formula procurement through single-source agreements with price protection clauses.
- Nursing Facilities:Long-term care operators in Ontario and British Columbia are building dedicated nutrition support teams for dysphagia and malnutrition management in aging populations.
- Outpatient Clinics:Dialysis centers and oncology infusion suites managing chronic disease nutrition through scheduled monitoring appointments.
Homecare segments command the steepest expansion trajectory; hospitals retain the largest absolute spend.
Application:
Metabolic derangement severity and intervention duration determine formula customization depth and prescriber specialization requirements.
- Cancer:High-protein, immune-modulating formulations addressing cachexia and treatment-related mucositis. Outpatient chemotherapy protocols are shifting administration sites from infusion centers to home settings.
- Kidney Disorders:Protein-restricted, electrolyte-modified formulations for dialysis patients. Renal-specific enteral formulas are penetrating hospital purchasing cooperatives in Georgia and North Carolina.
- Diabetes:Glycemic control formulations with modified carbohydrate profiles and enhanced fiber content for glucose management.
- Liver Disease:Branched-chain amino acid-enriched formulations addressing hepatic encephalopathy and protein metabolism dysfunction.
Cancer applications dominate current volumes; kidney disorder segments show the strongest upward momentum.
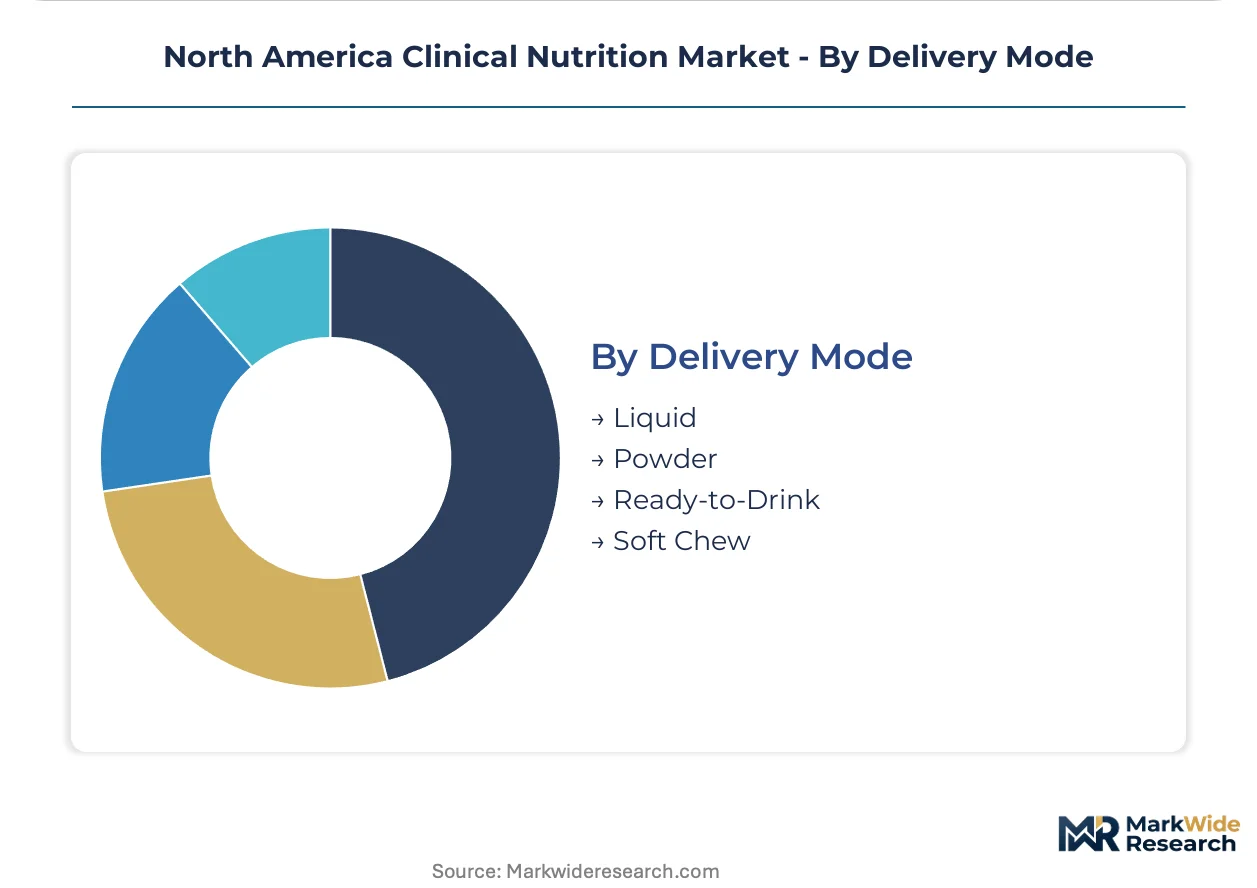
Delivery Mode:
Packaging format selection reflects administration setting constraints, patient mobility status, and EPA sustainable packaging directive compliance pressures.
- Liquid:Pre-mixed enteral formulas in reduced-plastic delivery formats meeting hospital green-procurement mandates. Sterile filling requirements and shelf stability specifications favor manufacturer vertical integration.
- Ready-to-Drink:Ambulatory oral supplements in single-serve packaging for outpatient cancer and diabetes management. Bluetooth-enabled pumps in California and New York step-down units are automating intake monitoring.
- Powder:Reconstitutable formulations offering shipping efficiency and extended shelf life for homecare inventory management.
- Soft Chew:Palatable formats for pediatric metabolic disorders and geriatric patients with dysphagia avoiding tube placement.
Liquid formats capture the largest volume share; ready-to-drink packaging is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Registered dietitians and certified nutrition support clinicians concentrate in the U.S. Southeast and Ontario corridor, anchoring regional capacity for enteral and parenteral program administration. Hospital networks in Georgia and North Carolina recruit specialized talent through academic partnerships with Emory and Duke nutrition programs. Canadian long-term care operators compete for the same credential pool as U.S. homecare agencies expand.
United States
Medicare Part B reimbursement expansion for home infusion nutrition is accelerating patient discharge velocity from acute care facilities. FDA aluminum contamination thresholds for parenteral formulations are forcing multi-chamber bag reformulation across compounding networks. Hospital purchasing coalitions in Georgia and North Carolina negotiate direct manufacturer contracts, bypassing traditional distributor relationships entirely.
Canada
Ontario and British Columbia long-term care facilities are building dedicated nutrition support teams for dysphagia and malnutrition management in aging populations. Health Canada's updated Food and Drug Regulations for medical foods mandate premarket notification for novel enteral formulas claiming disease-specific benefits. Toronto-area health systems are consolidating metabolic formula procurement through provincial purchasing collaboratives.
Mexico
Private hospital chains in Mexico City and Monterrey are adopting U.S.-style early enteral nutrition protocols for post-surgical recovery. COFEPRIS regulatory alignment with FDA nutritional labeling standards is streamlining cross-border formula registration for multinational manufacturers. Guadalajara's medical device cluster is expanding production capacity for enteral feeding pumps serving domestic and Central American markets.
North America Clinical Nutrition Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and delivery device segments. The market structure concentrates around vertically integrated nutrition conglomerates with captive manufacturing, mid-scale metabolic specialists, and regional compounding pharmacies. Three archetypes dominate: diversified health science conglomerates controlling raw ingredient through sterile filling, rare disease formula specialists leveraging regulatory exclusivity, and hospital-focused device manufacturers bundling pumps with disposable sets. Competitive moves center on backward integration into amino acid production and strategic partnerships with newborn screening program administrators.
Within the diversified conglomerate tier, Abbott Laboratories and Nestlé Health Science exemplify vertically integrated operators with control over enteral formula production from ingredient sourcing through sterile filling. Fresenius Kabi occupies a distinct position in parenteral nutrition bags and compounding services for acute care settings. These three anchors represent contrasting strategic postures: manufacturing depth versus metabolic specialization versus hospital supply chain integration.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé Health Science |
| Fresenius Kabi |
| Baxter International |
| Danone Nutricia |
| B. Braun Melsungen |
| Ajinomoto Cambrooke |
| Medtrition Inc. |
| Perrigo Company |
| Others |
Value Network & Pricing Analysis
Hospital purchasing coalitions in Georgia and North Carolina consolidating formula procurement through direct manufacturer contracts are forcing supply chain restructuring toward captive production and inventory risk absorption by producers. This buyer concentration is compressing distributor margins while rewarding vertically integrated manufacturers with price protection mechanisms and volume guarantees.
Pricing Analysis
Service bundling separates enteral formula supply from parenteral compounding and home infusion nursing in distinct pricing architectures. Three-tier pricing structure across premium metabolic formulas, standard ICU enteral products, and economy oral supplements reflects certification burden and amino acid sourcing complexity. Cost compression in standard enteral formulas is intensifying because hospital GPOs are extracting annual price concessions through sole-source agreements. Long-term care facilities exhibit the highest price sensitivity due to fixed per-diem reimbursement, while pediatric metabolic specialists accept premium pricing for disease-specific formulations with regulatory exclusivity.
Supply Chain Analysis
Domestic-content mandates under the U.S. EPA sustainable packaging directives and hospital green-procurement standards are reshaping sourcing toward North American sterile filling capacity and reduced-plastic delivery formats. Crystalline L-amino acid production concentrates in the United States, Switzerland, and Japan, creating geographic dependency for metabolic formula inputs. Aluminum contamination compliance for parenteral nutrition rests on trace mineral additive sourcing from qualified suppliers. Single-source vulnerability in specialty amino acid supply creates formulation disruption risk. Distribution runs through manufacturer-direct contracts with regional health systems, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA aluminum contamination thresholds and CMS reimbursement expansions for home infusion are structurally expanding addressable demand for compliant formulations.
For Market Incumbents: Extend manufacturing depth into crystalline amino acid production to secure supply against single-source concentration in metabolic inputs. Build captive sterile filling capacity in the U.S. Southeast to capture Georgia and North Carolina hospital direct-contracting momentum. Defend against plant-based protein entrants by locking pea and rice isolate supply through long-term offtake agreements with ingredient processors. For New Entrants and Emerging Players: Begin with Bluetooth-enabled feeding pump software and remote monitoring platforms serving California and New York step-down units where nursing documentation burden creates immediate adoption pull. Target pediatric metabolic rare diseases in states with newborn screening expansion programs, where disease-specific formula demand is captive and pricing power is protected. Pursue hospital system partnerships that bundle device placement with formula supply contracts. For Investors and Strategic Acquirers: Asymmetric upside sits with regional compounding pharmacies achieving 503B compliance for customized parenteral admixtures, as FDA inspection backlogs create scarcity value in sterile formulation capability. Five-to-ten-year viability favors operators with backward integration into amino acid production and direct hospital contracting relationships. Monitor CMS coverage determinations for home infusion nutrition as the inflection signal for outpatient service infrastructure investment.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | Health Canada's medical food regulations require clinical evidence packages for disease-specific formula claims. |
| Hospital System Partnership | Southeast U.S. networks negotiate direct contracts bypassing GPOs entirely. |
| Backward Integration into Amino Acids | Crystalline L-amino acid supply concentration creates single-source vulnerability for metabolic formulas. |
| Reimbursement Strategy | Medicare Part B home infusion coverage expansion accelerates patient discharge velocity. |
| Software Companion Development | Bluetooth-enabled pumps transmitting intake data to hospital command centers reduce emergency readmissions. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market's stakeholder ecosystem. Interviews with registered dietitians, hospital procurement managers, GPO contracts specialists, and home infusion nursing directors combined with secondary validation from FDA guidance documents, Health Canada Food and Drug Regulations, CMS Medicare reimbursement databases, and hospital purchasing cooperative records. Bottom-up formula volume modeling and top-down market sizing triangulate across enteral, parenteral, specialty, and oral supplement segments.
Granularity-level modeling distinguishes product type, end-user setting, application, and delivery mode dimensions across the projection horizon. CAGRs derive from patient discharge velocity trends, newborn screening expansion rates, and ICU protocol standardization adoption curves. The analytical framework incorporates Medicare Part B reimbursement policy trajectories, FDA aluminum contamination threshold compliance costs, and licensed practical nurse availability constraints in Texas and Florida.
Caveats apply where CMS coverage determinations, FDA facility inspection backlogs, or specialty amino acid supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding reimbursement policy continuity, regulatory compliance cost trajectories, and homecare nursing workforce expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Weight Loss Market