
 Parenteral Nutrition Market | 2026-2036
Parenteral Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Parenteral Nutrition Market Analysis
REACH compliance is shifting the cost-of-entry calculus for European manufacturers of lipid emulsion components. Baxter leverages its integrated supply chain to sustain multi-chamber bag production across North American and European facilities. Fresenius Kabi anchors its position through R&D intensity in standardized amino acid formulations. B. Braun Melsungen differentiates via automated compounding technology that reduces pharmacy labor.
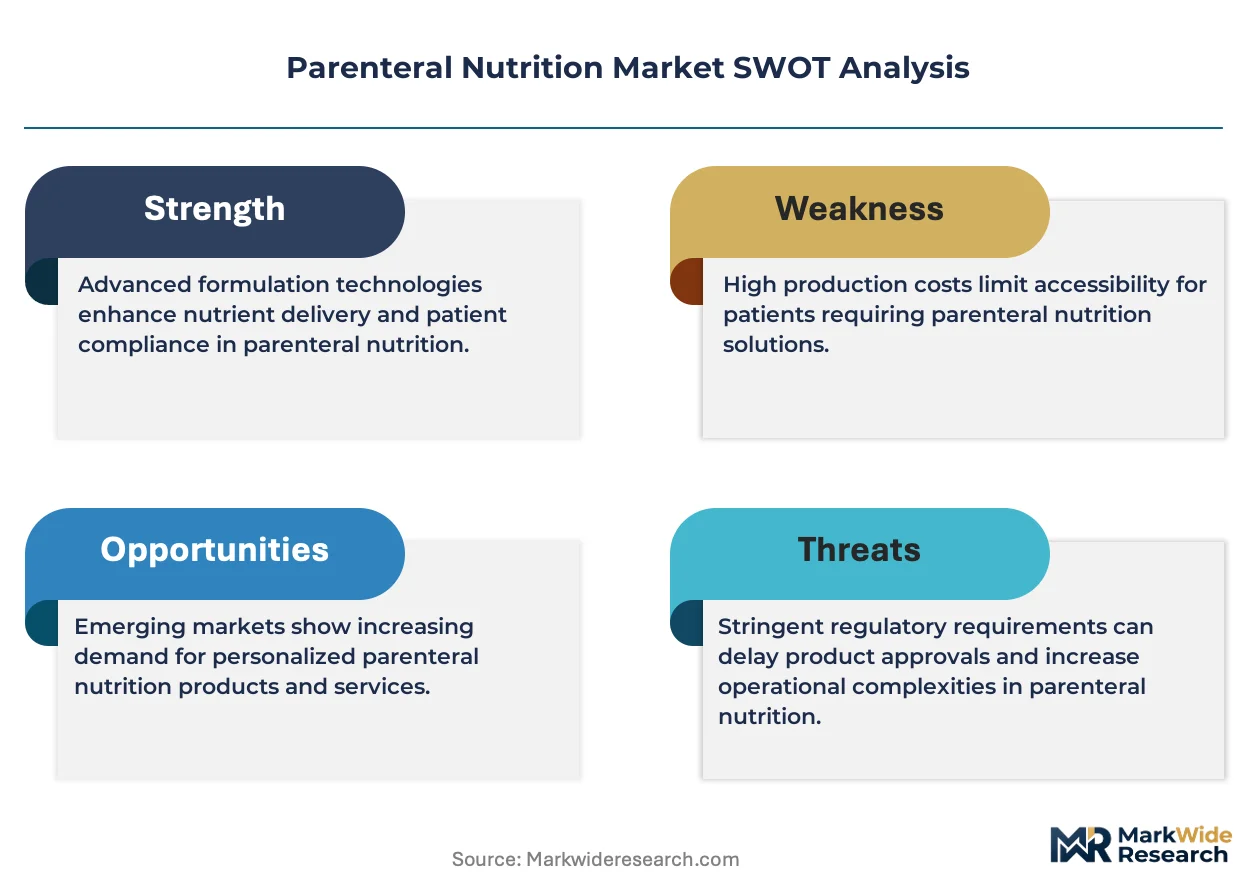
Parenteral nutrition refers to the intravenous administration of nutrients—including carbohydrates, amino acids, lipids, electrolytes, vitamins, and trace elements—directly into the bloodstream when enteral feeding is contraindicated, typically formulated as emulsions with osmolarity ranging from 600 to 900 mOsm/L for peripheral delivery and exceeding 900 mOsm/L for central venous access. TPN Solutions dominate hospital procurement due to their complete nutritional profile, while Additives command margin pools from micronutrient customization for metabolic disorders. Homecare Settings represent the fastest-growing end-user channel as infusion pump portability improves and reimbursement frameworks adapt to outpatient parenteral nutrition protocols.
The FDA enforces cGMP standards for sterile compounding under 503B outsourcing facility rules, while the EMA's MDR requirements impose clinical evidence thresholds for legacy delivery devices. Japan's PMDA maintains distinct pharmacopeial standards for amino acid ratios that constrain import substitution. Stakeholders must monitor evolving USP chapter revisions on sterility assurance and trace element stability as these will determine which formulation portfolios retain market access without costly reformulation.
Market Dynamics
Hospital procurement of ready-to-use TPN solutions is rewriting supply relationships as clinicians prioritize error reduction over cost minimization, concentrating purchasing power among integrated health systems that can enforce formulation standardization across their networks.
Growth Catalysts
- EU MDR sterility mandates:Revised medical device regulations are forcing upgrades to multi-chamber bag manufacturing lines, creating replacement demand for compliant infrastructure.
- Homecare infusion pump portability:Lighter ambulatory devices are enabling outpatient parenteral nutrition protocols, extending therapy duration beyond acute hospital stays.
- Aging surgical populations in the United States:Demographic shifts toward older patients with compromised gastrointestinal function are expanding the addressable patient base for central venous nutrition.
Market Restraints
- Soybean oil price volatility:Lipid emulsion feedstock costs fluctuate with agricultural commodity markets, compressing margin predictability for formulation manufacturers.
- Single-source API concentration:Amino acid active pharmaceutical ingredients cluster among Chinese and Indian suppliers, exposing formulators to geopolitical supply interruptions.
- Revised USP sterility assurance standards:Upcoming chapter revisions on trace element stability will require costly reformulation of legacy micronutrient portfolios.
Strategic Opportunities
- Underpenetrated Japanese homecare protocols:PMDA reimbursement frameworks are adapting to outpatient parenteral nutrition, opening volume expansion in an aging population.
- Automated compounding technology convergence:Integration of gravimetric verification with barcode medication administration is reducing pharmacy labor intensity.
- REACH compliance cost barriers:European manufacturers face elevated entry costs for lipid emulsion components, advantaging incumbents with established substance dossiers.
Industry Challenges
- Pharmaceutical compounding technician shortages:Specialized sterile preparation skills are scarce, limiting pharmacy throughput for customized additive formulations.
- Multi-chamber bag validation timelines:EMA clinical evidence thresholds for legacy delivery devices extend certification cycles, delaying portfolio refresh.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parenteral Nutrition Market |
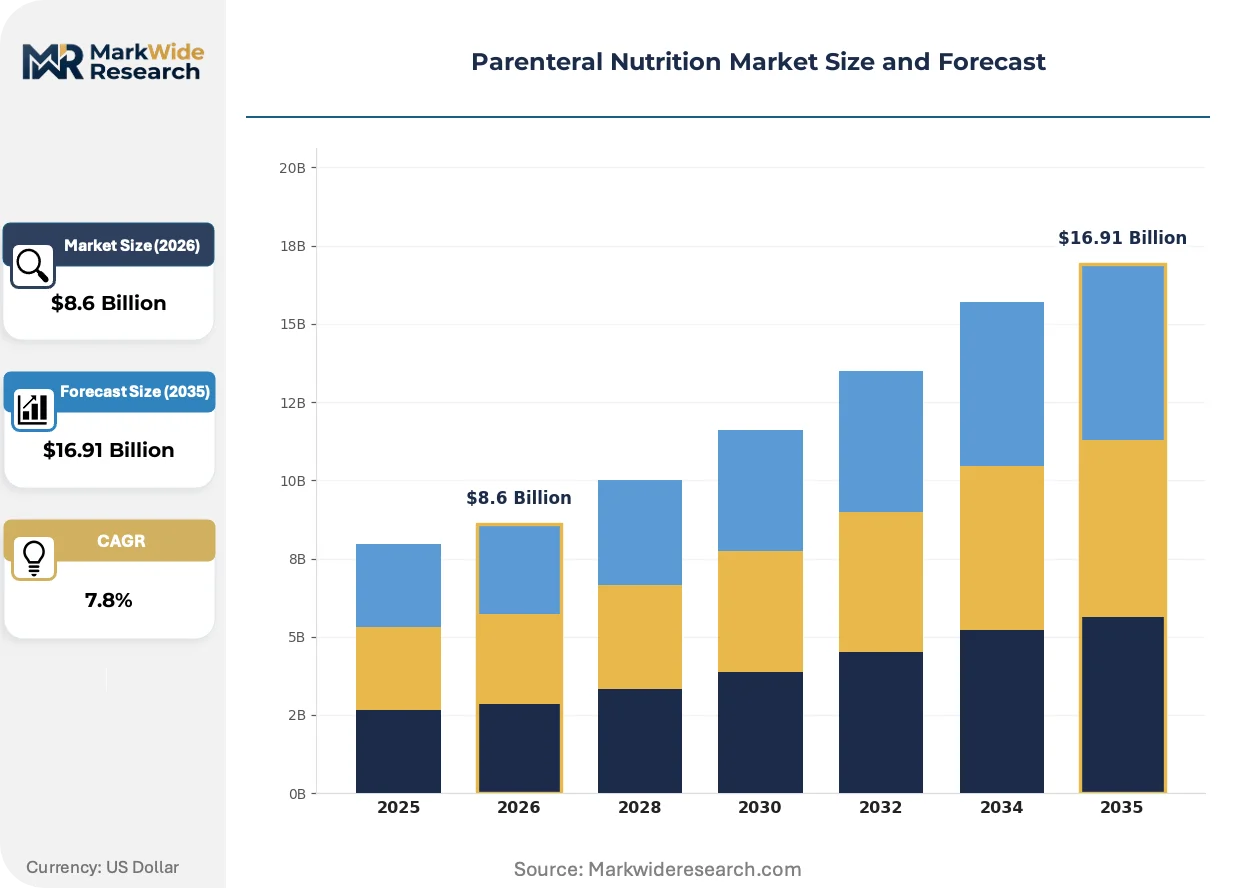
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $16.91 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TPN Solutions, PPN Solutions, Additives, Devices Application: Cancer Care, Gastrointestinal Disorders, Surgical Recovery, Critical Care End User: Hospitals, Homecare Settings, Long-term Care Facilities, Clinics Delivery Mode: Infusion Pump, Gravity Feed, Syringe Pump, Catheter |
| Companies Covered | Grifols, Sichuan Kelun Pharmaceutical, Baxter, ICU Medical, JW Pharmaceutical, Fresenius Kabi, Otsuka Pharmaceutical Factory, Allergan, B. Braun Melsungen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parenteral Nutrition Market Emerging Trajectories
Formulation science and delivery device engineering are converging to reduce clinical intervention frequency while improving metabolic safety profiles for long-term parenteral nutrition patients.
Multi-chamber bag technology is rewriting hospital pharmacy workflows by separating macronutrients into physically isolated compartments that mix immediately before infusion. Large integrated health systems in the United States are adopting these systems at accelerated pace to reduce compounding labor. The technology is compressing demand for traditional pharmacy-based admixture preparation, shifting value capture toward bag manufacturers with validated sterilization processes.
REACH compliance requirements are restructuring European lipid emulsion supply chains by imposing substance registration burdens on imported raw materials. Manufacturers must demonstrate environmental and human health safety profiles for legacy excipients. Small and mid-sized formulators in Germany and France are responding by consolidating supplier relationships and qualifying domestic fatty acid sources.
Buyer concentration among group purchasing organizations is consolidating procurement leverage in the United States, displacing fragmented hospital-level contracting. Three-tier pricing structures across premium, standard, and economy formulation grades are emerging as the dominant commercial model. This concentration is most visible in academic medical centers and Catholic health systems, where standardization committees now mandate preferred vendor lists for TPN solutions.
Parenteral Nutrition Market Segmentation
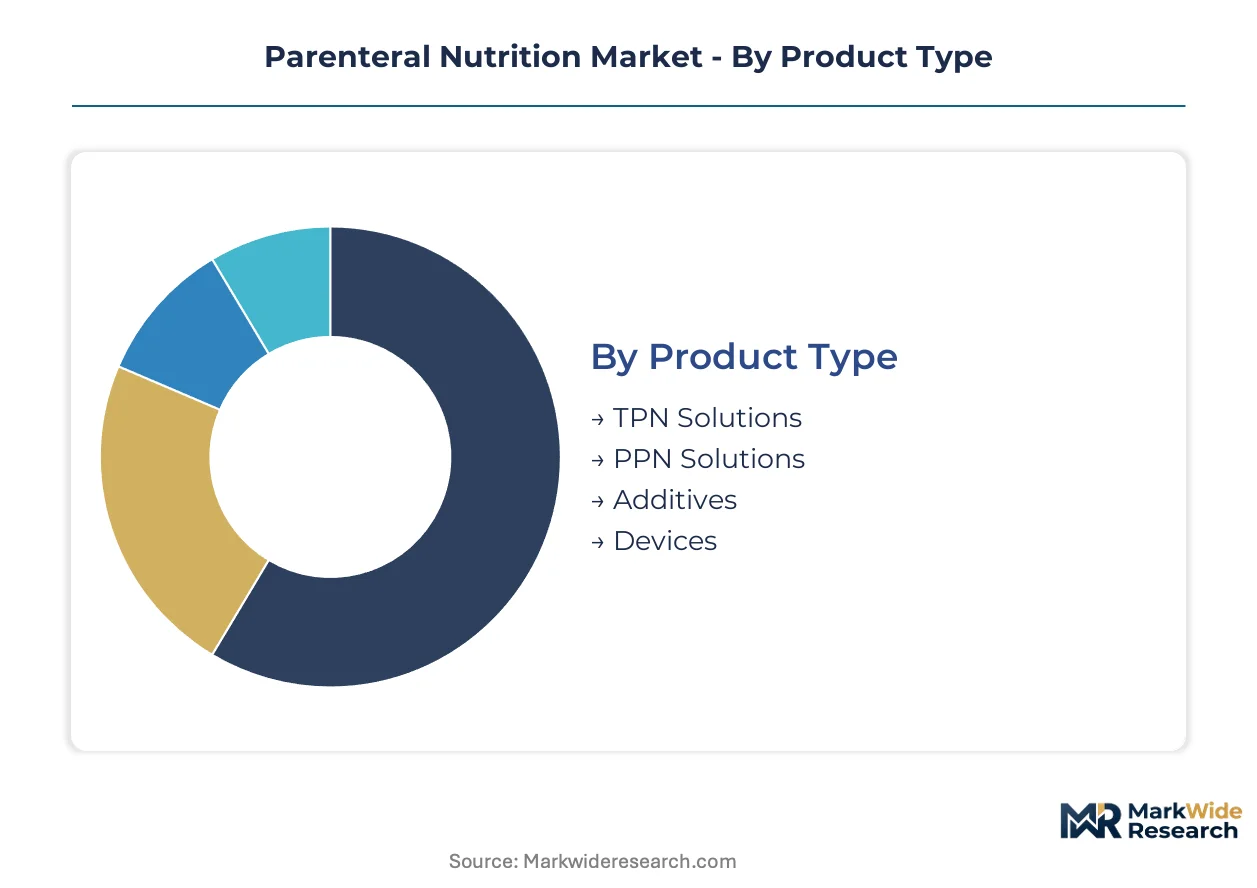
Parenteral nutrition segmentation reveals how regulatory requirements, clinical settings, and delivery technologies partition market value. Each category carries distinct certification burdens that shape manufacturer entry costs and margin structures across hospital and homecare channels.
Product Type:
FDA 503B outsourcing rules and EMA MDR sterility mandates apply differentially across these formulation classes, with complete nutrition solutions facing the heaviest compliance load.
- TPN Solutions:Complete macronutrient formulations combining dextrose, amino acids, and lipids in concentrations exceeding 900 mOsm/L for central venous delivery. Hospital procurement concentrates among integrated health systems in the United States seeking error reduction through standardized ready-to-use bags.
- Additives:Micronutrient concentrates including electrolytes, vitamins, and trace elements requiring customization for metabolic disorders. Demand clusters in academic medical centers managing complex liver and renal failure protocols.
- PPN Solutions:Peripheral-appropriate formulations with osmolarity below 900 mOsm/L for short-term nutritional support.
- Devices:Multi-chamber bags and infusion administration sets subject to EMA clinical evidence thresholds.
Leading the category by volume: TPN Solutions. Growing fastest: Additives.
Application:
Reimbursement intensity varies sharply across these clinical indications, with oncology and critical care commanding premium pricing tiers.
- Cancer Care:Chemotherapy-induced mucositis and bowel obstruction create sustained demand for central venous nutrition in outpatient oncology units. Volume concentrates in United States cancer centers adapting to homecare reimbursement.
- Surgical Recovery:Post-operative ileus and gastrointestinal anastomosis failure drive acute hospital consumption. Aging surgical populations in the United States expand addressable cases for prolonged parenteral support.
- Gastrointestinal Disorders:Short bowel syndrome and Crohn's disease complications requiring chronic nutritional intervention.
- Critical Care:ICU patients with enteral feeding contraindications due to hemodynamic instability or mechanical ventilation.
Volume leadership sits with Surgical Recovery. Steepest expansion trajectory: Cancer Care.
End User:
Channel economics diverge on labor intensity, with hospital pharmacy compounding yielding to manufacturer-ready formulations as homecare scales.
- Hospitals:Inpatient wards and emergency departments consuming standardized TPN bags through group purchasing organization contracts. Three-tier pricing structures across premium, standard, and economy formulation grades dominate procurement.
- Homecare Settings:Ambulatory infusion pump portability enables outpatient protocols, extending therapy duration beyond acute stays. PMDA reimbursement frameworks in Japan are adapting to support this channel expansion.
- Long-term Care Facilities:Skilled nursing environments managing stable patients on prolonged parenteral regimens.
- Clinics:Outpatient infusion centers handling cancer care and gastrointestinal disorder maintenance.
Hospitals retain volume dominance. Homecare Settings gain share fastest.
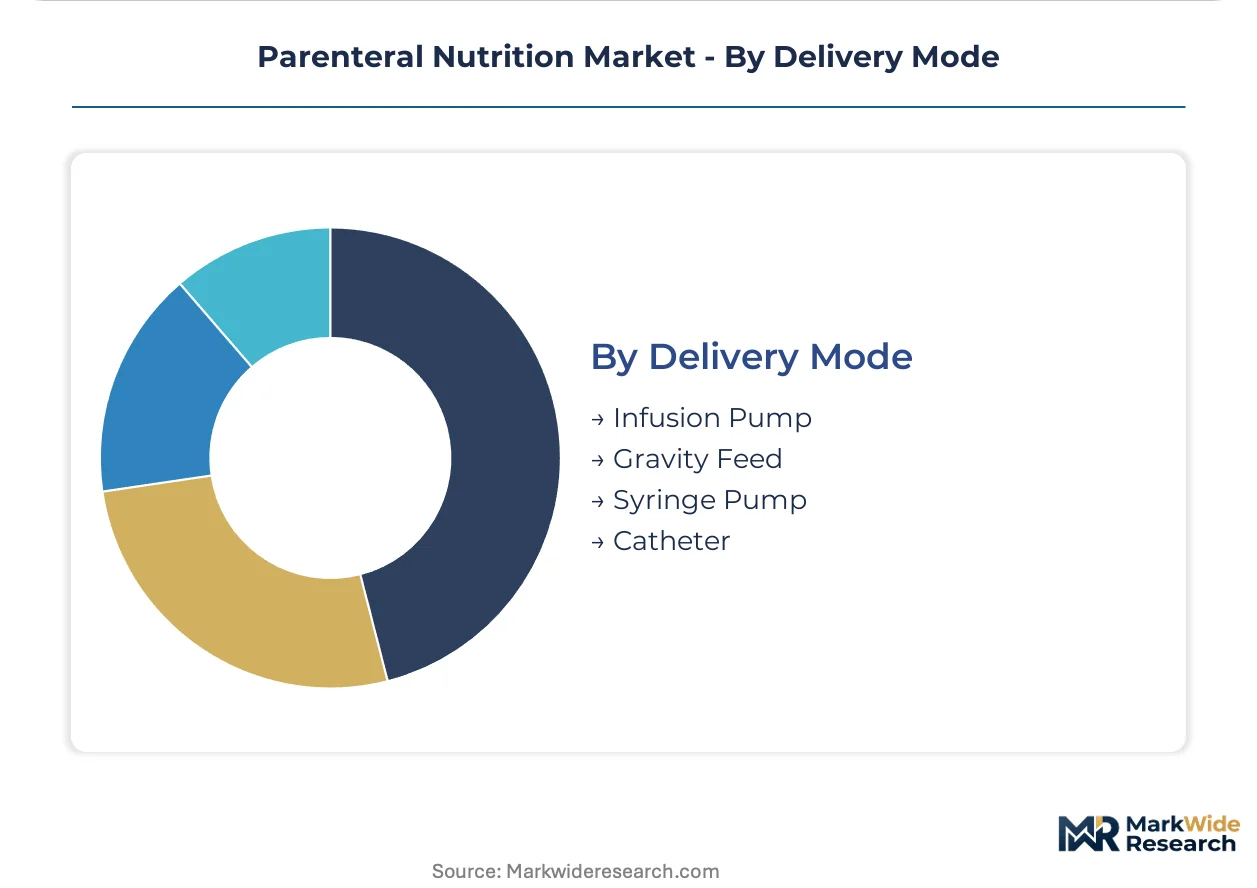
Delivery Mode:
Device selection determines pharmacy workflow design and patient mobility constraints across acute and ambulatory settings.
- Infusion Pump:Programmable volumetric devices enabling precise macronutrient delivery rates with alarm capabilities for occlusion or air detection. Lighter ambulatory models are displacing gravity systems in United States homecare transitions.
- Catheter:Central venous access devices including peripherally inserted central catheters and implanted ports. EMA MDR sterility mandates are forcing upgrades to multi-chamber bag-compatible infusion sets.
- Gravity Feed:Simple drip-rate systems for resource-limited settings without pump infrastructure.
- Syringe Pump:Precision devices for neonatal and pediatric parenteral nutrition requiring micro-volume delivery.
Infusion Pumps lead by installed base. Catheter systems expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Ireland and Singapore concentrate sterile manufacturing for multinational pharmaceutical firms serving parenteral nutrition markets. These jurisdictions attract investment through accelerated regulatory pathways and intellectual property protections. The resulting production clusters supply hospital networks across multiple continents.
United States
Aging surgical populations and homecare reimbursement expansion drive sustained volume growth for central venous nutrition. FDA 503B outsourcing facility rules enforce cGMP standards that favor integrated health systems with captive compounding capabilities. The Research Triangle Park corridor in North Carolina anchors sterile formulation R&D for multi-chamber bag technologies.
Germany
REACH compliance costs for lipid emulsion components elevate entry barriers for European manufacturers. EMA MDR sterility mandates force upgrades to multi-chamber bag production lines across Baden-Württemberg and Bavaria. The Rhine-Main cluster around Frankfurt sustains automated compounding technology development for pharmacy labor reduction.
Japan
PMDA reimbursement frameworks are adapting to outpatient parenteral nutrition protocols in an aging population. Distinct pharmacopeial standards for amino acid ratios constrain import substitution and protect domestic formulation manufacturers. The Kanto region surrounding Tokyo concentrates homecare infusion pump distribution networks.
China
Domestic amino acid API production clusters in Jiangsu and Zhejiang provinces supply regional formulators while reducing import dependence. NMPA oversight of sterile compounding facilities intensifies as hospital procurement shifts toward ready-to-use solutions. The Yangtze River Delta anchors multi-chamber bag assembly for both domestic consumption and export markets.
India
CDSCO regulatory harmonization efforts attract contract manufacturing for sterile parenteral formulations targeting export markets. Cost-competitive amino acid synthesis capabilities in Gujarat and Maharashtra position domestic suppliers for regional volume growth. The Hyderabad-Visakhapatnam corridor specializes in trace element additive production for metabolic disorder protocols.
Parenteral Nutrition Market Vendor Landscape
North American producers anchor one tier; European specialists hold formulation standardization advantages through integrated supply chains. The vendor base splits between diversified healthcare conglomerates with multi-chamber bag capabilities and focused additive manufacturers serving metabolic customization niches. Three archetypes dominate: integrated sterile solution suppliers, automated compounding technology providers, and regional API-to-formulation integrators. Capacity expansion and backward integration into lipid emulsion feedstocks constitute the primary competitive moves.
Among diversified healthcare conglomerates, Baxter and Fresenius Kabi exemplify integrated supply chain operators with validated sterilization processes across multiple geographies. B. Braun Melsungen occupies a position within the automated compounding tier, representing pharmacy workflow convergence between gravimetric verification and medication safety systems. Sichuan Kelun Pharmaceutical anchors the Asia-Pacific specialist archetype, reflecting regional API integration strategies for amino acid and electrolyte formulations.
| Leading Market Players |
|---|
| Grifols |
| Sichuan Kelun Pharmaceutical |
| Baxter |
| ICU Medical |
| JW Pharmaceutical |
| Fresenius Kabi |
| Otsuka Pharmaceutical Factory |
| Allergan |
| B. Braun Melsungen |
| Others |
Supply Flow & Price Mechanics
Soybean oil futures volatility on the Chicago Board of Trade cascades through parenteral nutrition manufacturing into tiered pricing structures, as lipid emulsion feedstock costs determine margin allocation across premium ready-to-use formulations and economy admixture components.
Pricing Analysis
Lead-time compression commands premium positioning for multi-chamber bags with validated sterility documentation, while spot inventory of legacy micronutrient additives trades at discounted tiers. Pricing stratifies across premium, standard, and economy tiers based on USP certification grade and volume commitment scale. Cost compression in the additives segment is intensifying because of single-source API concentration among Asian suppliers. Academic medical centers demonstrate lowest price sensitivity due to metabolic customization requirements, while long-term care facilities exhibit highest sensitivity to per-unit bag costs.
Supply Chain Analysis
Direct-to-hospital channels handle integrated health system demand through group purchasing organization contracts, bypassing wholesale distribution for high-volume TPN procurement. Manufacturing concentrates in the United States, Germany, and China, with sterile compounding facilities clustering around regulatory inspection jurisdictions. Formulators draw from soybean oil derivatives, amino acid APIs, and electrolyte salts as core inputs. Single-source vulnerability in Chinese and Indian amino acid supply exposes formulators to geopolitical interruption. Distribution runs through three-tier wholesaler networks for smaller hospital accounts and homecare pharmacies lacking GPO affiliation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH compliance costs and EMA MDR sterility mandates force sub-scale European manufacturers toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through backward integration into lipid emulsion feedstocks and captive amino acid API sourcing, neutralizing soybean price volatility and supply interruption threats from Chinese suppliers. Prioritize certification investment for USP chapter revisions on trace element stability to maintain portfolio access without costly reformulation cycles. Capacity addition in the Research Triangle Park corridor secures proximity to integrated health system procurement headquarters. For New Entrants and Emerging Players: PMDA reimbursement framework adaptation in Japan opens a window for homecare infusion pump portability specialists to capture outpatient parenteral nutrition volume in an aging demographic. Target underpenetrated Japanese homecare protocols as the most penetrable geography, leveraging automated compounding technology convergence as the go-to-market angle for pharmacy labor reduction value propositions. For Investors and Strategic Acquirers: The window for entry favors automated compounding technology providers with gravimetric verification capabilities and barcode medication administration integration. Mid-cap specialists with established REACH substance dossiers for lipid emulsion components offer acquisition appeal. Watch FDA 503B outsourcing facility enforcement intensity as the signal indicating whether captive hospital compounding or outsourced manufacturer-ready formulations will dominate channel economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lipid Emulsion Feedstocks | Captive soybean oil sourcing neutralizes agricultural commodity margin compression for formulation manufacturers. |
| EMA MDR Sterility Certification Investment | Upgraded multi-chamber bag production lines secure market access under revised clinical evidence thresholds. |
| Automated Compounding Technology Development | Gravimetric verification integration reduces pharmacy labor intensity for hospital network customers. |
| Japanese Homecare Reimbursement Strategy | PMDA framework adaptation captures outpatient parenteral nutrition volume in aging population segments. |
| USP Chapter Revision Compliance Program | Trace element stability validation preserves micronutrient portfolio access without reformulation costs. |
Methodological Framework
Independent corroboration across hospital pharmacy directors, sterile compounding technicians, GPO contracts managers, and biomedical engineers underwrites the qualitative findings. Primary interviews with formulary committee members and regulatory affairs specialists at multi-chamber bag manufacturers combined with secondary validation from FDA 503B facility inspection records, EMA MDR submission databases, USP chapter revision dockets, and hospital procurement contract repositories. Bottom-up patient-volume modeling and top-down manufacturer revenue triangulation anchored segmentation outputs.
Comparable-period anchoring to historical TPN solution shipment data and amino acid API trade flows established baseline trajectories across the projection horizon. The analytical framework modeled product type, application, end user, and delivery mode dimensions alongside regulatory certification tier as an industry-specific stratification. CAGRs derived from segment-level volume elasticity coefficients applied to demographic and reimbursement scenario inputs, with homecare infusion pump adoption curves and surgical population aging as primary forecast drivers.
Caveats apply where soybean oil commodity shocks, geopolitical API supply interruption, or accelerated USP sterility standard implementation could materially shift the outlook. Forecasts reflect documented assumptions on reimbursement adaptation timelines and regulatory enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Canada Clinical Nutrition Market