
 GCC Intravenous Solutions Market | 2026-2036
GCC Intravenous Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Intravenous Solutions Market Intelligence
Ready-to-mix compounding technology is fragmenting traditional centralized manufacturing models across the GCC, enabling hospital pharmacies to produce patient-specific formulations on-site. Baxter International leverages backward integration into active pharmaceutical ingredient sourcing to sustain margin control across its regional distribution network. Fresenius Kabi AG anchors its position through dedicated parenteral nutrition manufacturing facilities serving Gulf health systems. Grifols S.A. competes on plasma-derived albumin solutions, differentiating its portfolio from synthetic electrolyte competitors.
Intravenous solutions are sterile, pyrogen-free aqueous preparations administered directly into the venous circulation, typically formulated with electrolytes such as sodium chloride, potassium, or calcium in concentrations calibrated to plasma osmolality, and manufactured through aseptic filling into flexible plastic containers or glass bottles for fluid resuscitation, medication delivery, or nutritional support. Electrolyte solutions dominate current procurement volumes across Gulf hospital systems given their role in perioperative care and sepsis management, while nutritional solutions represent the fastest-expanding category as parenteral feeding protocols advance in oncology and critical care units. Peripheral IV delivery occupies the largest installed base across regional clinics and ambulatory surgical centers, though central IV access is gaining traction in tertiary hospitals managing prolonged chemotherapy and intensive care regimens.
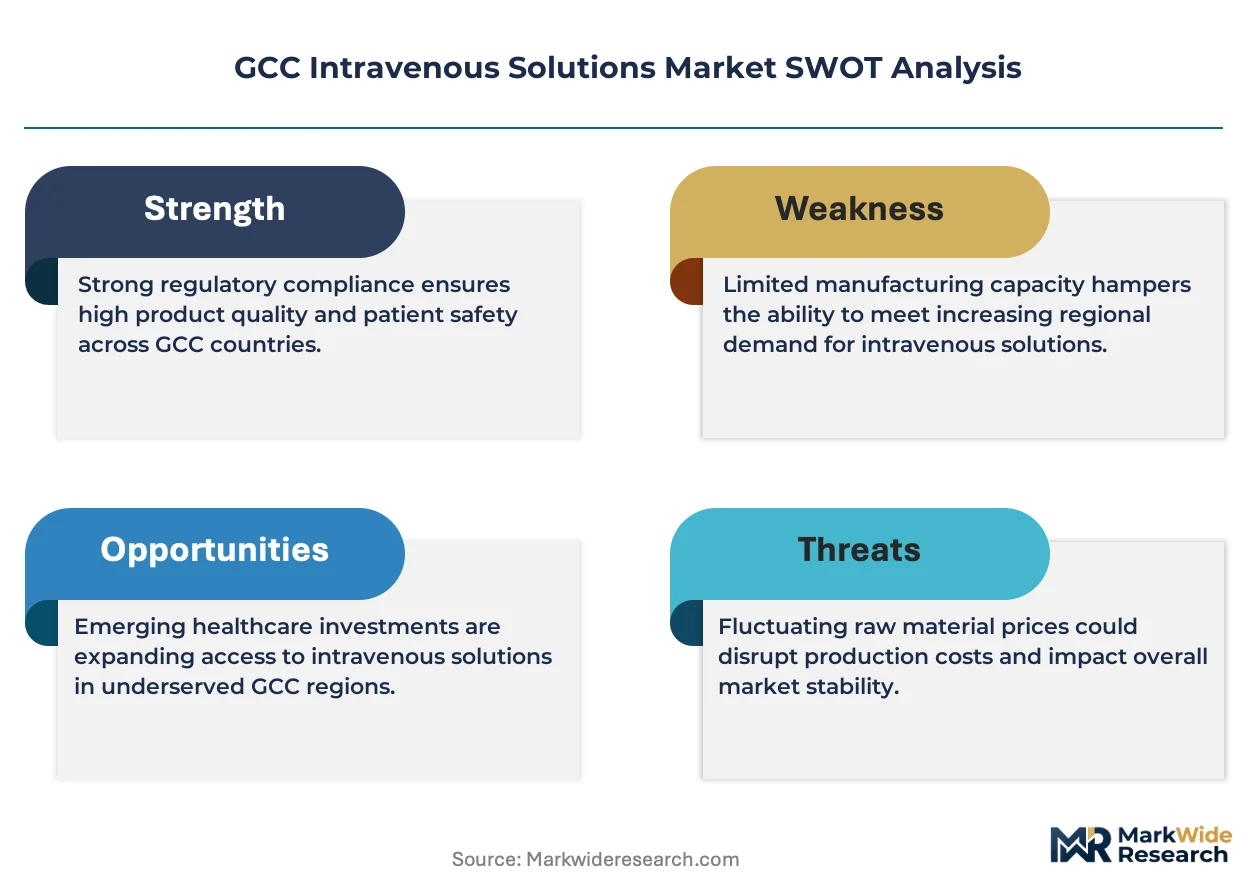
Saudi Food and Drug Authority and UAE Ministry of Health and Prevention enforce Gulf Central Committee for Drug Registration technical guidelines, requiring endotoxin testing and container integrity validation that elevate compliance costs for new entrants. SFDA batch release protocols and MOHAP facility inspection cycles shape product registration timelines and supply security planning for multinational manufacturers. Stakeholders must monitor evolving pharmacovigilance reporting requirements and local content mandates as Gulf governments advance healthcare self-sufficiency agendas.
Market Dynamics
Ready-to-mix compounding technology is fragmenting centralized manufacturing models across Saudi Arabia and the UAE, enabling hospital pharmacies to produce patient-specific formulations on-site and reducing dependency on bulk shipments from distant production facilities.
Growth Catalysts
- Surgical Volume Expansion:Tertiary care centers in Riyadh, Jeddah, and Dubai are scaling perioperative fluid protocols as oncology and trauma caseloads accelerate, directly expanding electrolyte solution procurement.
- Gulf Central Committee for Drug Registration Alignment:SFDA harmonization with GCC technical standards is compressing product approval timelines and accelerating multinational manufacturer entry into Saudi distribution networks.
- Parenteral Nutrition Protocol Advancement:Critical care units across the Emirates are adopting standardized feeding regimens for prolonged ICU stays, generating specialized nutritional solution demand distinct from generic hydration therapy.
Market Restraints
- API Import Dependency:Active pharmaceutical ingredient sourcing concentrates in European and Indian supplier bases, exposing GCC manufacturers to currency volatility and shipping disruptions.
- Endotoxin Testing Mandates:SFDA batch release protocols require validated container integrity and pyrogen testing that elevate compliance costs and extend registration timelines for new market entrants.
- Glass-to-Plastic Container Transition:Legacy glass bottle infrastructure in older Saudi hospital systems creates formulation compatibility constraints and supply chain bifurcation costs.
Strategic Opportunities
- Kuwait and Bahrain Penetration:Underdeveloped tertiary care infrastructure in these markets presents first-mover advantages for manufacturers establishing direct hospital contracts before competitor saturation.
- Plasma-Derived Albumin Substitution:Synthetic electrolyte competitors face displacement potential as Gulf health systems evaluate colloid solutions for sepsis and burn resuscitation protocols.
- Local Content Mandates:Saudi Vision 2030 healthcare self-sufficiency incentives are creating preferential procurement pathways for manufacturers committing to domestic compounding facility investment.
Industry Challenges
- Aseptic Compounding Certification:Hospital pharmacy staff require specialized training in ISO 5 cleanroom operations and sterility assurance testing, constraining rapid technology deployment.
- Legacy Inventory System Integration:ERP platforms in established UAE health systems require costly customization to track lot-specific IV solution consumption against patient billing records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Intravenous Solutions Market |
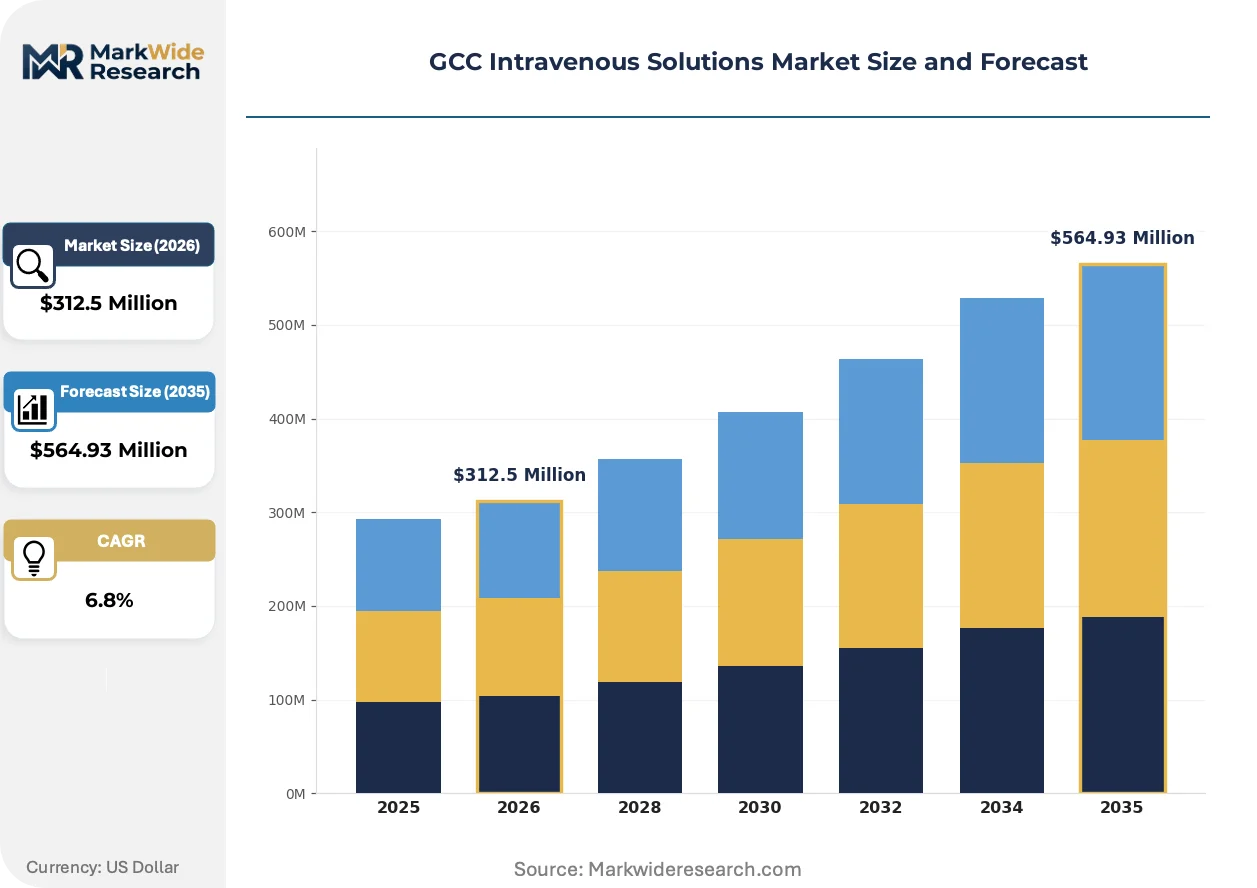
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Solutions, Nutritional Solutions, Antibiotic Solutions, Sterile Water Application: Chemotherapy, Surgery, Hydration, Critical Care End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Delivery Mode: Peripheral IV, Central IV, Continuous Infusion, Intermittent Infusion |
| Companies Covered | ICU Medical Inc., Otsuka Pharmaceutical Co., Ltd., Baxter International Inc., Amanta Healthcare, Grifols S.A., Fresenius Kabi AG, Pfizer Inc., Ajinomoto Co., Inc., B. Braun SE, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Intravenous Solutions Market Strategic Shifts & Innovations
Technology convergence between automated compounding systems and real-time inventory tracking is compressing the traditional separation between manufacturing and clinical pharmacy operations across Gulf health systems.
Closed-system transfer devices with integrated barcode verification are rendering obsolete manual admixture preparation in Saudi oncology units, where pharmacist adoption is accelerating to reduce medication error exposure, and this shift is compressing the market for pre-mixed multi-chamber bags that cannot accommodate dose customization.
SFDA implementation of Gulf Central Committee for Drug Registration pharmacovigilance reporting requirements is elevating post-market surveillance obligations for multinational manufacturers, compelling distributors to maintain localized adverse event databases and quarterly safety update submissions that smaller regional players struggle to resource.
Hospital procurement departments in Dubai and Abu Dhabi are consolidating IV solution purchasing through centralized tender platforms that aggregate demand across health system networks, displacing the fragmented direct-manufacturer relationships that previously dominated supply arrangements and compressing price negotiation cycles to annual rather than multi-year terms.
GCC Intravenous Solutions Market Segmentation
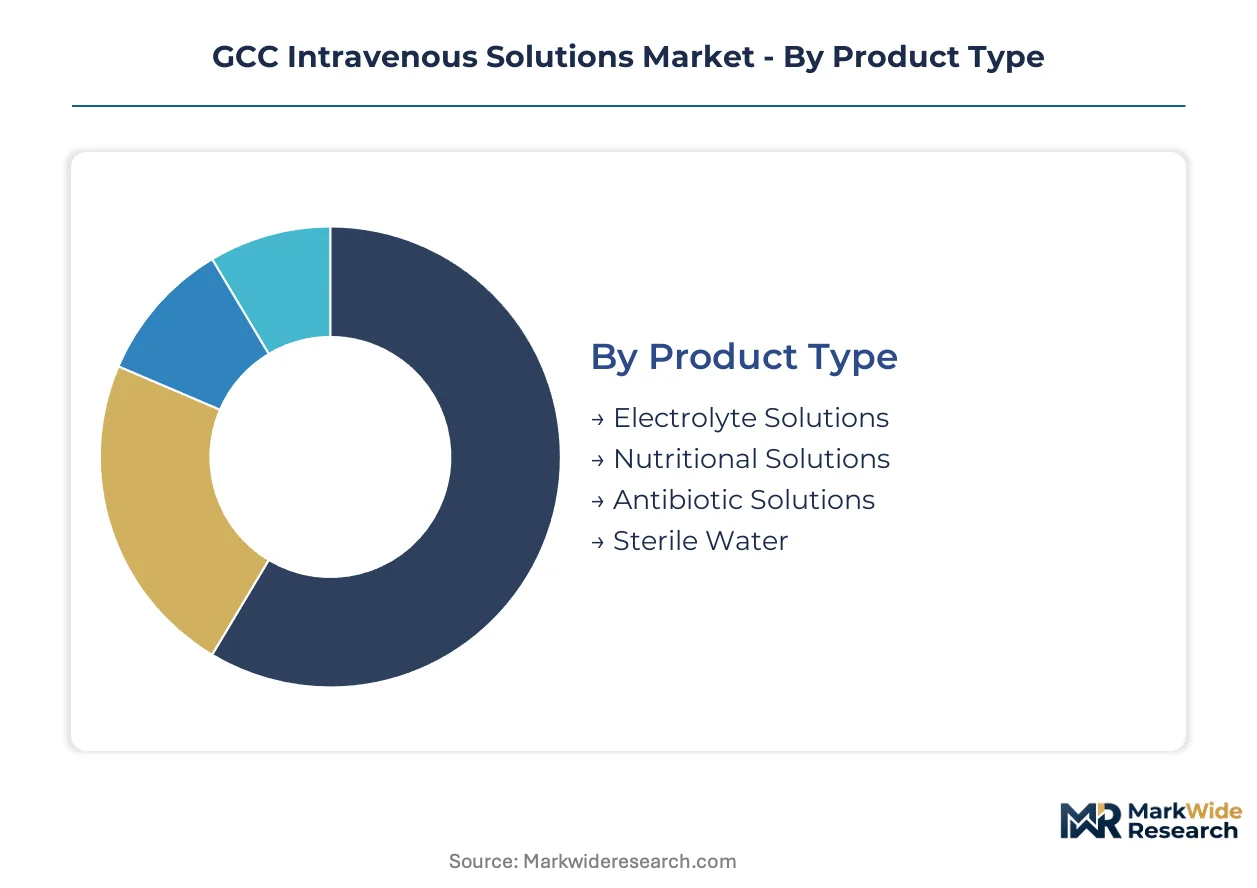
Segmentation in the GCC intravenous solutions market reveals distinct procurement rhythms across product categories. Hospital pharmacy inventory cycles vary dramatically between high-turnover electrolyte solutions and specialized nutritional formulations with extended shelf requirements.
Product Type:
Cycle times diverge sharply across this category, with electrolyte solutions turning over weekly in high-volume surgical wards while nutritional solutions move through specialized compounding workflows with extended preparation lead times.
- Electrolyte Solutions:Sodium chloride, potassium chloride, and balanced crystalloid formulations calibrated to plasma osmolality dominate perioperative and sepsis protocols. Procurement concentrates in Riyadh and Dubai tertiary centers where surgical volume expansion drives bulk purchasing agreements with 48-hour replenishment cycles.
- Nutritional Solutions:Parenteral nutrition formulations combining amino acids, lipids, and glucose require patient-specific compounding. Demand clusters in oncology and prolonged ICU stays across Emirates critical care units, with SFDA batch release protocols adding 72-hour regulatory holds to delivery timelines.
- Antibiotic Solutions:Pre-mixed antimicrobial IV preparations for hospital-acquired infection protocols.
- Sterile Water:Pyrogen-free diluent for medication reconstitution and irrigation procedures.
Electrolyte solutions anchor the volume base while nutritional solutions gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity hydration therapy from premium-priced oncology and critical care protocols requiring specialized formulation oversight.
- Chemotherapy:Cytotoxic drug delivery demands closed-system transfer devices and pharmacist-verified admixture protocols. Dubai oncology units are displacing pre-mixed bags with real-time compounding to accommodate dose customization, elevating per-treatment costs but reducing wastage from expired multi-chamber inventory.
- Surgery:Perioperative fluid resuscitation protocols consume crystalloid solutions in standardized ratios. Saudi Arabia's scaling trauma and elective procedure volume in Jeddah medical clusters drives predictable, high-frequency procurement with minimal specification variance.
- Hydration:Routine fluid replacement for dehydration and electrolyte imbalance management.
- Critical Care:Precision-controlled infusion for hemodynamic stabilization and organ support.
Surgery anchors the volume base while chemotherapy gains share at the steepest rate.
End User:
Customer type determines contract structure complexity, with health system networks consolidating purchasing power while fragmented clinic channels sustain distributor intermediation.
- Hospitals:Tertiary care centers across Saudi Arabia and the UAE aggregate demand through centralized tender platforms. SFDA facility inspection cycles and MOHAP compliance requirements favor established manufacturers with localized quality documentation.
- Clinics:Outpatient facilities in Kuwait and Bahrain present first-mover opportunities before competitor saturation.
- Home Care:Patient-administered infusion for chronic conditions and post-acute recovery.
- Ambulatory Surgical Centers:Same-day procedure facilities with streamlined hydration protocols.
Hospitals anchor the volume base while clinics gain share at the steepest rate.
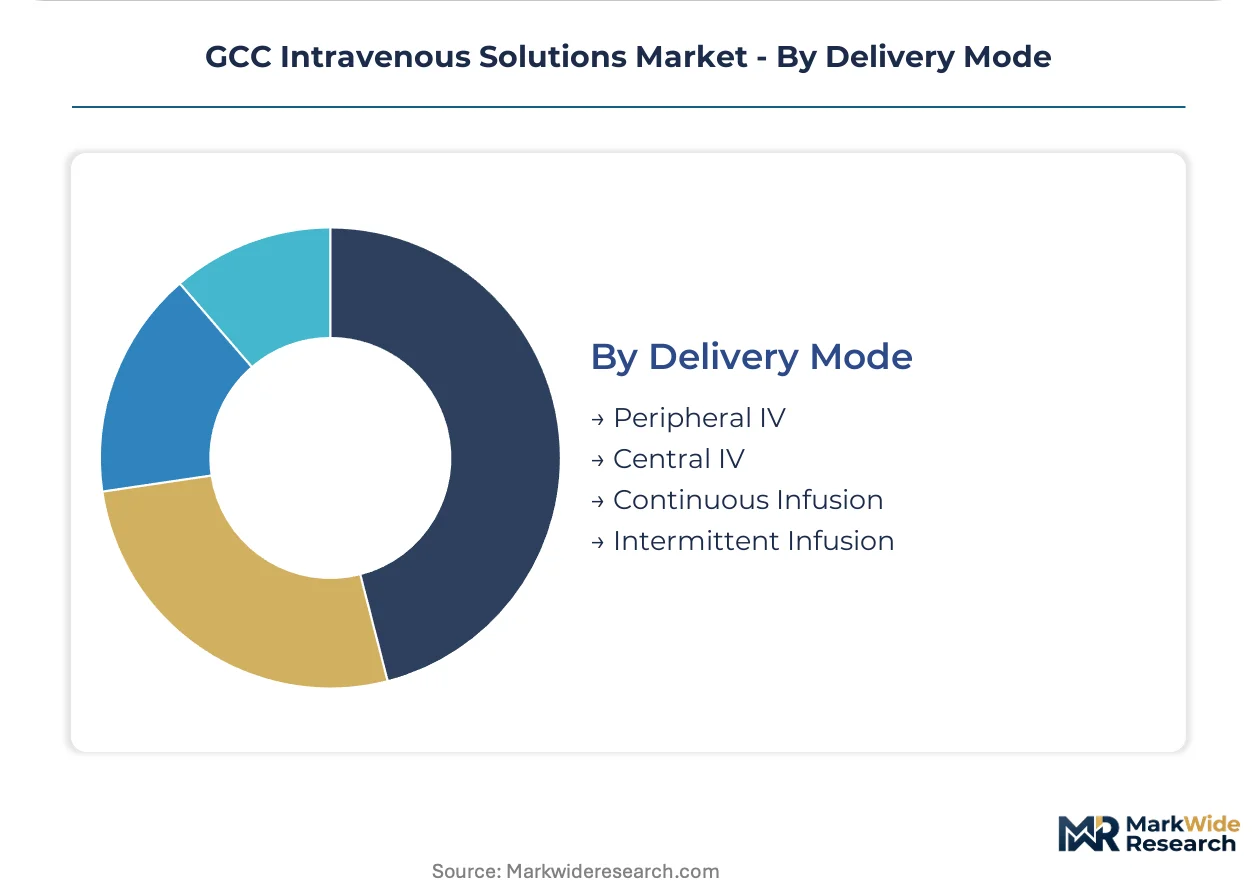
Delivery Mode:
Technology maturity separates established peripheral access from advancing central line protocols requiring specialized insertion certification and infection control infrastructure.
- Peripheral IV:Short-term venous access via catheter insertion in extremity vessels. The installed base spans regional clinics and ambulatory centers, with lowest barrier to deployment but limited dwell time for prolonged therapeutic regimens.
- Central IV:Catheter placement in larger central veins enables high-volume flow and vesicant drug administration. Tertiary hospitals in Riyadh and Abu Dhabi are expanding dedicated insertion teams to support oncology and ICU expansion.
- Continuous Infusion:Steady-rate delivery systems for maintenance fluids and medication.
- Intermittent Infusion:Scheduled bolus administration with between-dose line locking.
Peripheral IV anchors the volume base while central IV gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European pharmaceutical exporters dominate API supply corridors into Gulf health systems, with German and Swiss manufacturers shipping active ingredients through Dubai's Jebel Ali port for final formulation across Saudi Arabia and the Emirates.
Saudi Arabia
Riyadh's King Faisal Specialist Hospital and Jeddah's medical city clusters are scaling parenteral nutrition protocols for oncology and critical care expansion. SFDA batch release requirements and Gulf Central Committee for Drug Registration alignment compress approval timelines for multinational entrants. The Eastern Province's Dammam industrial zone hosts emerging compounding facility investments targeting Vision 2030 localization mandates.
United Arab Emirates
Dubai Health Authority and Abu Dhabi Health Services Company are consolidating procurement through centralized tender platforms aggregating demand across hospital networks. MOHAP facility inspection cycles and pharmacovigilance reporting requirements elevate compliance barriers for smaller distributors. Dubai's Healthcare City and Abu Dhabi's Al Maryah Island medical district concentrate tertiary care capacity and specialized infusion therapy demand.
Kuwait
The Ministry of Health's hospital modernization program is expanding ICU bed capacity and parenteral nutrition service lines. Kuwait's national pharmaceutical regulator enforces Gulf Central Committee technical guidelines for endotoxin testing and container integrity validation. Al-Sabah Medical District in Kuwait City anchors procurement volume, with underdeveloped tertiary infrastructure in outlying governorates presenting first-mover contract opportunities.
Bahrain
King Hamad University Hospital and Salmaniya Medical Complex are upgrading surgical and oncology units driving electrolyte and nutritional solution demand. The National Health Regulatory Authority coordinates with GCC standards for product registration and post-market surveillance. Manama's concentrated hospital infrastructure offers limited but high-value procurement contracts before competitor saturation.
Qatar
Hamad Medical Corporation's expansion of specialized cancer and trauma centers is elevating demand for patient-specific compounding capabilities. The Ministry of Public Health's alignment with Gulf Central Committee standards streamlines multinational manufacturer entry. Doha's Education City medical district and West Bay hospital cluster concentrate advanced care capacity requiring sophisticated infusion therapy protocols.
GCC Intravenous Solutions Market Key Industry Players
On the supply side, the industry is consolidating around multinational pharmaceutical manufacturers with established Gulf distribution networks and localized regulatory compliance infrastructure. Tiered competitive positioning separates integrated global suppliers from regional compounders and specialized nutrition formulators. Three archetypes dominate: backward-integrated API controllers, dedicated parenteral nutrition manufacturers, and plasma-derived colloid specialists. Capacity expansion through domestic compounding facility investment and strategic partnerships with hospital pharmacy automation vendors represent the dominant competitive moves.
Among integrated multinational suppliers, Baxter International Inc., Fresenius Kabi AG, and Grifols S.A. occupy positions exemplifying distinct strategic archetypes. Baxter represents backward-integrated API sourcing control, Fresenius Kabi anchors dedicated parenteral nutrition manufacturing scale, and Grifols exemplifies plasma-derived differentiation from synthetic electrolyte competitors. These three sit within the premium-tier supplier category where regulatory documentation depth and Gulf Central Committee registration breadth determine contract access.
| Leading Market Players |
|---|
| ICU Medical Inc. |
| Otsuka Pharmaceutical Co., Ltd. |
| Baxter International Inc. |
| Amanta Healthcare |
| Grifols S.A. |
| Fresenius Kabi AG |
| Pfizer Inc. |
| Ajinomoto Co., Inc. |
| B. Braun SE |
| Others |
Cost & Logistics Intelligence
Overcapacity in European API manufacturing is compressing margin structures for GCC-bound electrolyte solutions while simultaneously enabling Gulf hospital systems to extract volume-based concessions from multinational suppliers. This utilization dynamic rewards backward-integrated manufacturers with captive active pharmaceutical ingredient production, leaving pure-play compounders exposed to procurement leverage from consolidated Saudi and UAE health system networks.
Pricing Analysis
Prior-generation glass-bottle formulations trade at steep discounts to current-generation flexible plastic containers with integrated barcode verification, while next-generation closed-system transfer devices command premiums for oncology applications. Three-tier pricing structure across premium, standard, and economy levels separates plasma-derived colloid solutions from synthetic crystalloids and commodity saline. Pricing pressure stems from centralized tender platforms in Dubai and Abu Dhabi aggregating demand across hospital networks. Government hospital procurement committees exhibit highest price sensitivity, while private oncology centers in Riyadh and Dubai prioritize formulation customization over unit cost.
Supply Chain Analysis
Export-control regimes on pharmaceutical manufacturing equipment limit technology transfer into Gulf compounding facilities, constraining local capacity expansion. Active pharmaceutical ingredient supply concentrates in Germany, Switzerland, and India, with final formulation and aseptic filling distributed across Saudi Arabia and the UAE. Raw material dependencies include sodium chloride from European chemical suppliers, pharmaceutical-grade water systems, and multi-layer polymer films for container manufacturing. Single-source vulnerability runs through Jebel Ali port consolidation for API importation. Distribution runs through manufacturer-direct contracts with tertiary hospital networks and specialized distributor intermediaries serving fragmented clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through health system consolidation across Saudi Arabia and the UAE, with centralized tender platforms displacing fragmented procurement relationships and compressing supplier margins.
For Market Incumbents: Pre-empt margin erosion by deepening backward integration into API sourcing and establishing dedicated compounding partnerships with Saudi Vision 2030 localization incentives. Baxter International's captive supply chain model offers a template for defending position against emerging regional compounders. Prioritize SFDA batch release certification investments to maintain access to consolidated government procurement channels. For New Entrants and Emerging Players: Pursue first-mover contracts in Kuwait and Bahrain before competitor saturation, where underdeveloped tertiary infrastructure offers direct hospital relationships without incumbent lock-in. Target oncology compounding services in Qatar's expanding cancer centers, where patient-specific formulation demand outstrips current supply. Leverage ready-to-mix technology partnerships with hospital pharmacy automation vendors as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with dedicated parenteral nutrition facilities and long-term GPO contracts across Gulf health systems. Five-to-ten year viability favors integrated suppliers with localized regulatory compliance infrastructure over pure distribution plays. Acquisition targets should demonstrate established Gulf Central Committee registration breadth and SFDA facility inspection history. Watch for inflection signals in Saudi domestic compounding facility investment commitments under healthcare self-sufficiency mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Sourcing | Baxter International's captive supply chain insulates margins from currency volatility and shipping disruptions. |
| Domestic Compounding Facility Investment | Saudi Vision 2030 incentives create preferential procurement pathways for localized manufacturers. |
| Hospital Pharmacy Automation Partnership | Ready-to-mix technology deployment accelerates real-time compounding adoption in Dubai oncology units. |
| SFDA Batch Release Certification | Regulatory documentation depth determines contract access to consolidated government tender platforms. |
| Plasma-Derived Albumin Portfolio Expansion | Grifols S.A. differentiates from synthetic electrolyte competitors in sepsis and burn resuscitation protocols. |
Research Approach
A spread of perspectives from hospital pharmacy directors, regulatory affairs specialists at multinational manufacturers, procurement managers at Saudi GPOs, and biomedical engineering consultants converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SFDA registration databases, Gulf Central Committee technical guidelines, hospital procurement tender records, and customs import data for active pharmaceutical ingredients. Bottom-up demand modeling across electrolyte, nutritional, and specialized solution categories triangulated against top-down market sizing from manufacturer distribution disclosures.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across product type, application, end user, and delivery mode dimensions. Compound annual growth rates derived from surgical volume trajectories, ICU bed expansion plans, and parenteral nutrition protocol adoption curves across Saudi Arabia and the UAE. Forecast inputs incorporated SFDA harmonization timelines with Gulf Central Committee standards and MOHAP facility inspection cycle frequencies.
Sensitivities concentrate around API import disruption scenarios, currency volatility effects on European supplier pricing, and accelerated localization mandates under Saudi Vision 2030 healthcare self-sufficiency agendas. Forecasts reflect documented assumptions regarding regulatory approval timelines and hospital infrastructure investment commitments. Material shifts in Gulf Central Committee technical guideline revisions or SFDA batch release protocol changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Blood Bags Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Specimen Containers Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Face Mask Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Nasal Splints Market