
 Advanced Glycation End Products Market | 2026-2036
Advanced Glycation End Products Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Glycation End Products Market Analysis
Project finance for specialized biopharma manufacturing facilities is rewriting competitive entry barriers in analytical reagent production. Thermo Fisher Scientific leverages its captive supply of high-purity reference materials to dominate contract research channels. Merck KGaA anchors European distribution through its life sciences division, while Diagnoptics Technologies BV specializes in non-invasive autofluorescence detection systems for clinical AGE measurement.
Advanced glycation end products are heterogeneous compounds formed through non-enzymatic Maillard reactions between reducing sugars and amino groups on proteins, lipids, or nucleic acids, with carboxymethyllysine and pentosidine serving as the most quantified biomarkers for tissue damage assessment. Their primary commercial purpose spans pharmaceutical drug discovery for diabetic complications, nutritional quality control in processed foods, and cosmetic anti-aging formulation testing. The pharmaceutical application commands the deepest margin pools due to regulatory-grade assay requirements, while the food industry segment sustains volume leadership through manufacturer demand for Maillard reaction monitoring. Research laboratories represent the fastest-growing end user category as academic institutions expand gerontology and metabolic disease programs.
FDA scrutiny of glycation biomarkers in diabetes drug trials shapes clinical assay validation requirements, while EMA's MDR framework tightens performance standards for in vitro diagnostic devices measuring tissue AGE accumulation. ISO 15189 accreditation pressures hospital laboratories to upgrade analytical protocols for patient monitoring applications. Stakeholders must monitor evolving reimbursement codes for non-invasive AGE testing as payers reassess preventive screening value frameworks.
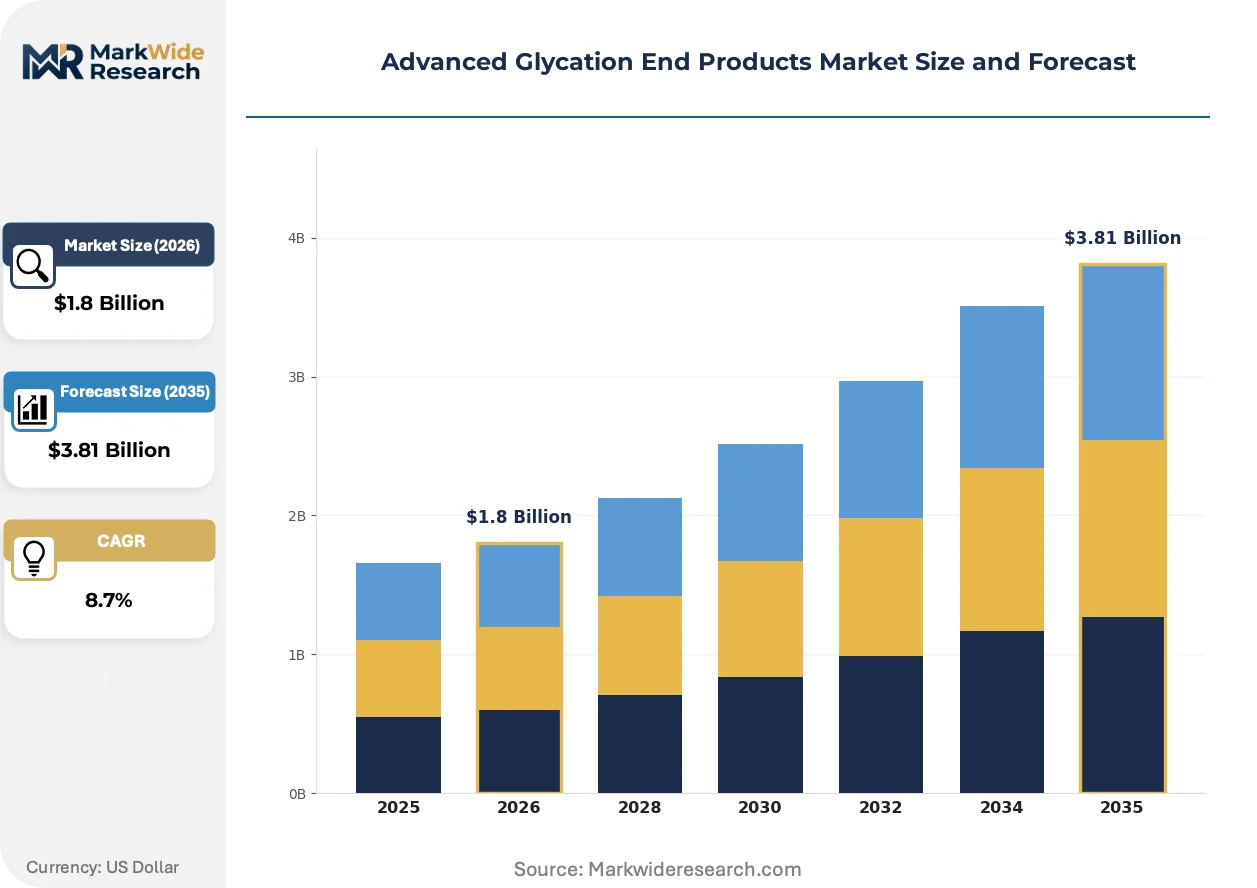
Market Dynamics
Regulatory-grade assay validation requirements for glycation biomarkers are compressing vendor margins while elevating technical barriers for analytical reagent suppliers serving pharmaceutical drug discovery channels.
Growth Catalysts
- FDA biomarker scrutiny:Tightened validation standards for diabetes drug trials are forcing contract research organizations to upgrade AGE detection protocols, expanding demand for certified reference materials.
- Academic gerontology expansion:Research laboratories across the United States are building dedicated metabolic disease programs that require high-throughput glycation analysis platforms.
- Non-invasive autofluorescence systems:Clinical adoption of skin-based AGE measurement devices is creating parallel demand for calibration standards and quality control reagents.
Market Restraints
- High-purity amino acid derivative costs:Synthesis of carboxymethyllysine and pentosidine reference compounds requires specialized carbohydrate chemistry expertise concentrated in Germany and Switzerland.
- EMA MDR compliance timelines:In vitro diagnostic device manufacturers face extended certification cycles for AGE measurement systems intended for clinical deployment.
- Mass spectrometry substitution:Proteomics laboratories increasingly bypass commercial ELISA kits in favor of in-house LC-MS/MS methods for glycation site mapping.
Strategic Opportunities
- Japan's aging demographic:METI-funded longevity research initiatives are creating dedicated funding streams for AGE biomarker studies in sarcopenia and vascular complications.
- Cosmetic anti-aging claims substantiation:Skincare manufacturers in France require third-party glycation inhibition testing to support product positioning against dermal protein crosslinking.
- ISO 15189 laboratory accreditation:Hospital networks in the United Kingdom are outsourcing AGE testing to specialized reference laboratories rather than building in-house capabilities.
Industry Challenges
- Maillard chemistry expertise scarcity:Few analytical chemists possess combined skills in carbohydrate biochemistry and clinical assay development, constraining R&D team expansion.
- Cross-platform standardization delays:Autofluorescence readings vary significantly between device manufacturers, complicating multi-site clinical trial data reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Glycation End Products Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactive Dicarbonyls, Amadori Products, Carboxymethyllysine, Pentosidine Application: Food Industry, Pharmaceutical Industry, Nutraceuticals, Cosmetic Industry Source: Animal Products, Plant-Based Sources, Synthetic Origins, Fermented Sources End User: Food Manufacturers, Research Laboratories, Hospitals, Cosmetic Companies |
| Companies Covered | AbbVie Inc., Novartis International AG, Merck KGaA, AstraZeneca PLC, Alteon Inc., Thermo Fisher Scientific Inc., Takeda Pharmaceutical Company Limited, Diagnoptics Technologies BV, Cell Biolabs Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Glycation End Products Market Emerging Trajectories
Detection modality convergence and regulatory data requirements are compressing traditional assay development cycles while fragmenting procurement authority between research procurement offices and quality assurance departments.
Surface-enhanced Raman spectroscopy (SERS) substrates functionalized with glycation-specific molecular recognition elements are rendering obsolete traditional HPLC-based quantification methods for tissue biopsy samples. Pharmaceutical toxicology groups have adopted SERS workflows for preclinical diabetic nephropathy studies, cutting analytical turnaround from days to hours and eliminating solvent disposal burdens.
EMA's Medical Device Regulation (MDR) Article 10 technical documentation requirements now mandate clinical performance studies for AGE measurement devices claiming correlation with diabetic complication risk. European IVD manufacturers are restructuring quality management systems to accommodate notified body scrutiny of glycation biomarker clinical validation packages, with small-cap specialists facing disproportionate compliance cost absorption.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for analytical reagents in United States academic medical centers. Hospital networks now negotiate enterprise-wide contracts for glycation assay kits, compressing available vendor pools and privileging suppliers with CAP proficiency testing program participation.
Advanced Glycation End Products Market Segmentation
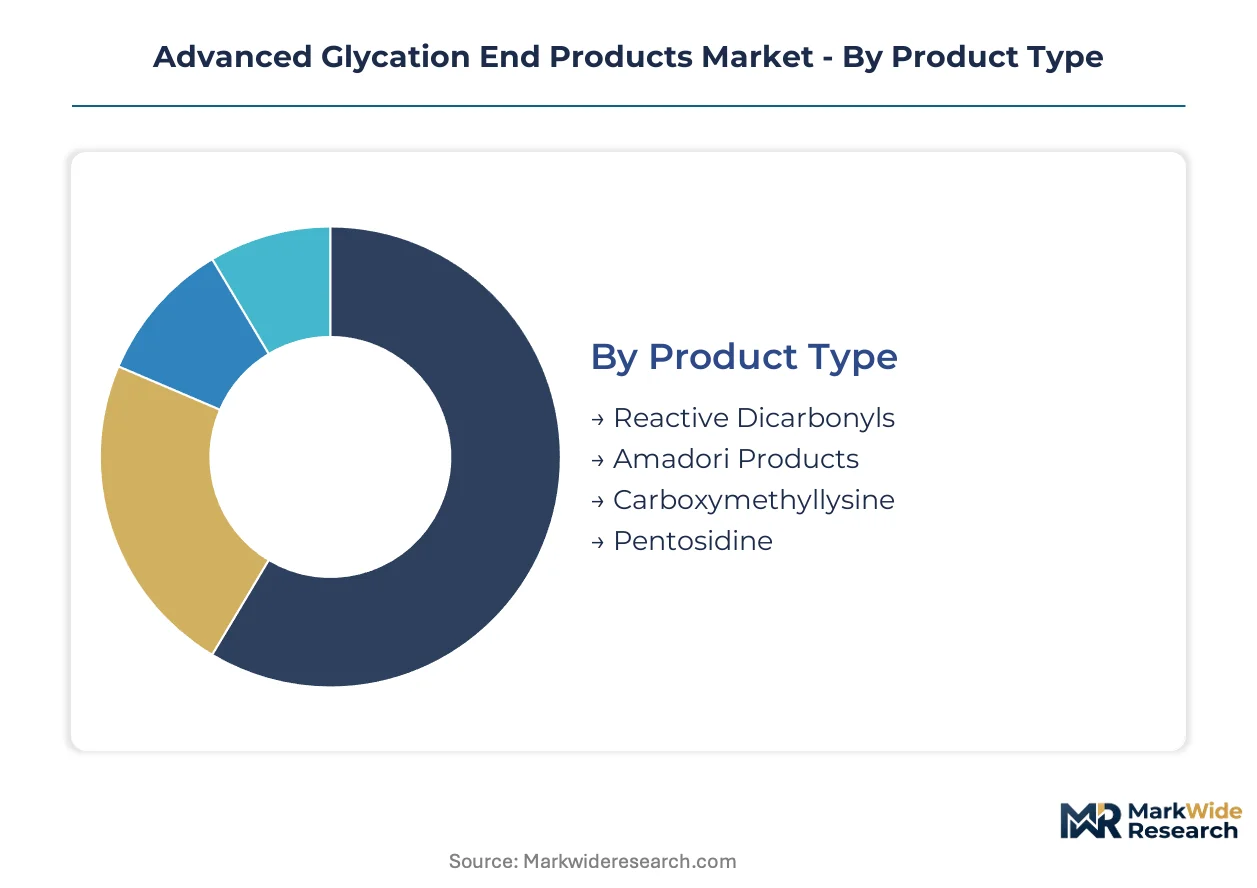
Segmentation in the Advanced Glycation End Products market reveals how technical specifications, regulatory pathways, and end-use requirements fragment procurement patterns across distinct buyer clusters. Each category carries divergent margin profiles and service intensity demands that reshape vendor positioning strategies.
Product Type:
After-sales service intensity varies sharply across product categories, with reference-grade compounds demanding ongoing calibration support and technical consultation that commodity reagents do not require.
- Reactive Dicarbonyls:These highly reactive carbonyl intermediates—glyoxal, methylglyoxal, and 3-deoxyglucosone—serve as critical precursors in Maillard reaction kinetic studies. Pharmaceutical toxicology groups in the United States procure these compounds under strict cold-chain protocols for diabetic nephropathy model development, where supplier technical support determines protocol reproducibility.
- Carboxymethyllysine:The most extensively validated AGE biomarker for tissue damage quantification commands premium positioning due to ISO 17034-certified reference material requirements. FDA scrutiny of glycation endpoints in diabetes drug trials forces sponsors to source this compound exclusively from suppliers with documented measurement uncertainty budgets.
- Amadori Products:Early-stage Maillard intermediates used primarily in food quality control applications where thermal processing monitoring drives routine procurement.
- Pentosidine:Fluorescent crosslink compound serving as a long-term glycation marker in gerontology research programs.
By volume, Reactive Dicarbonyls leads. By growth pace, Carboxymethyllysine is ahead.
Application:
Application-based cost tiers separate commodity testing services from regulatory-grade validation packages that absorb tenfold price multiples.
- Pharmaceutical Industry:Drug discovery for diabetic complications and aging-related indications consumes the highest-grade analytical reagents under FDA-enforced assay validation protocols. Sponsors demand comprehensive certificate of analysis packages and stability data that elevate procurement costs relative to other segments.
- Food Industry:Maillard reaction monitoring for processed food quality control sustains volume leadership through manufacturer demand for thermal damage indicators and nutritional labeling support. Large-scale processors prioritize cost efficiency over certification depth.
- Cosmetic Industry:Anti-aging claims substantiation requires third-party glycation inhibition testing, particularly among French skincare manufacturers positioning against dermal protein crosslinking.
- Nutraceuticals:Dietary supplement manufacturers utilize AGE detection for ingredient quality verification and finished product release testing.
Pharmaceutical Industry commands the steepest expansion trajectory. Food Industry maintains the deepest procurement volumes.
Source:
Supply concentration patterns favor synthetic origins for reproducibility, while fermentation expertise constrains viable supplier pools.
- Synthetic Origins:Chemically defined production routes deliver batch-to-batch consistency that reference material suppliers require for ISO 17034 accreditation. German and Swiss carbohydrate chemistry specialists dominate this high-margin segment through proprietary synthesis protocols.
- Animal Products:Collagen-derived AGEs from bovine or porcine tissues serve specialized research applications where native protein context matters.
- Plant-Based Sources:Soy and wheat protein isolates provide alternative matrices for nutritional studies and vegan product development.
- Fermented Sources:Microbial production systems offer scalable routes to complex AGE structures, though viable manufacturing partners remain scarce.
Synthetic Origins dominates value capture. Fermented Sources is climbing the fastest as biotechnology platforms mature.
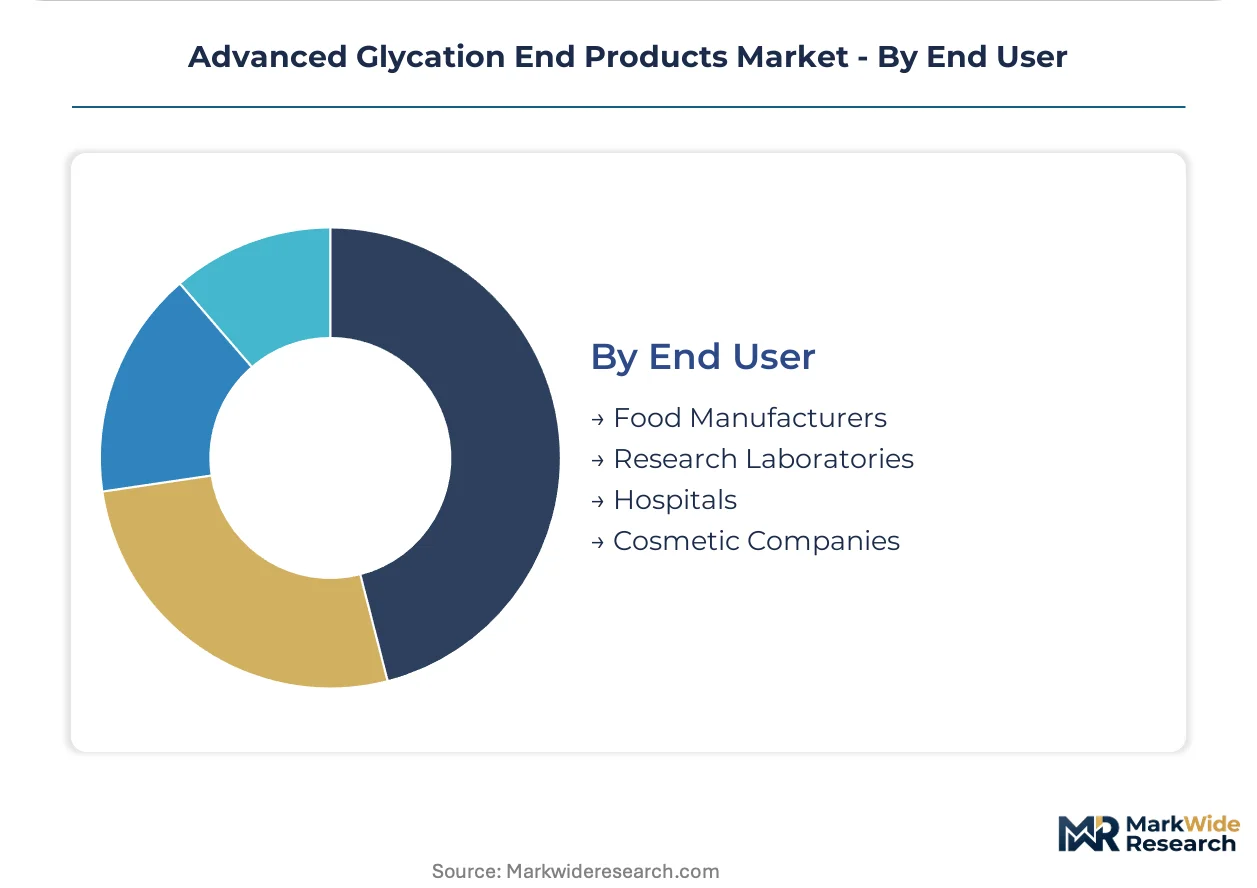
End User:
Customer type determines whether procurement flows through centralized research offices or decentralized quality assurance departments with divergent technical specifications.
- Research Laboratories:Academic gerontology and metabolic disease programs across the United States drive the fastest-growing demand category, requiring high-throughput glycation analysis platforms with flexible assay configurations. Federal funding expansion for longevity research accelerates capital equipment procurement cycles.
- Food Manufacturers:Industrial quality control departments prioritize integrated detection systems that slot into existing HPLC or mass spectrometry workflows without specialized operator training.
- Hospitals:Clinical laboratories pursuing ISO 15189 accreditation outsource AGE testing to specialized reference laboratories rather than building in-house capabilities, particularly within United Kingdom hospital networks.
- Cosmetic Companies:Formulation R&D groups and regulatory affairs departments commission third-party testing to support anti-aging marketing claims.
Food Manufacturers leads by installed base. Research Laboratories is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal research funding expansions and regulatory pathway clarifications are reshaping geographic demand patterns for AGE detection technologies. Pharmaceutical drug trials and academic gerontology programs concentrate procurement authority in specific metropolitan clusters.
United States
NIH-funded longevity research initiatives at Stanford and Harvard Medical School drive demand for high-throughput glycation analysis platforms. FDA biomarker scrutiny in diabetes drug trials forces sponsors to source certified reference materials exclusively from ISO 17034-accredited suppliers. The Boston-Cambridge biotech corridor anchors contract research organization procurement of analytical reagents.
Germany
Specialized carbohydrate chemistry expertise for carboxymethyllysine synthesis concentrates in Heidelberg and Munich academic-industrial partnerships. EMA MDR compliance timelines extend certification cycles for AGE measurement devices, favoring established quality management systems. The Rhine-Main region houses reference material producers serving pan-European pharmaceutical clients.
Switzerland
Swissmedic oversight of clinical trial materials elevates technical documentation requirements for glycation biomarker suppliers. Basel's pharmaceutical manufacturing density creates captive demand for in-process glycation monitoring. Zurich-based analytical chemistry specialists command premium positioning for high-purity amino acid derivative production.
Japan
METI-funded sarcopenia and vascular complication research channels public investment toward AGE biomarker studies. PMDA guidance on glycation endpoints in aging-related indications shapes assay validation protocols for domestic sponsors. The Kanto region's university hospital networks drive clinical adoption of non-invasive autofluorescence detection systems.
United Kingdom
NHS England outsourcing frameworks redirect AGE testing from hospital laboratories to specialized reference providers. ISO 15189 accreditation pressures concentrate procurement authority in London and Oxford academic medical centers. Manchester's emerging biotech cluster attracts metabolic disease program investment requiring glycation analysis infrastructure.
Advanced Glycation End Products Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority. Thermo Fisher Scientific leverages captive supply of high-purity reference materials to dominate contract research channels, while Merck KGaA anchors European distribution through life sciences division infrastructure. Three archetypes define competitive positioning: diversified analytical platform providers, specialized glycation detection system manufacturers, and reference-grade compound synthesis specialists. Dominant competitive moves include strategic partnerships for regulatory-grade assay validation and geographic expansion through distributor network consolidation.
Among diversified analytical platform providers, Thermo Fisher Scientific Inc. exemplifies channel control through integrated reagent-instrument workflows. Merck KGaA occupies a position bridging European distribution scale with life sciences technical depth. Diagnoptics Technologies BV represents the specialized detection system archetype, anchoring non-invasive clinical measurement applications. These three entities collectively illustrate how technical specification depth and regulatory compliance capability determine vendor selection in pharmaceutical and clinical end markets.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis International AG |
| Merck KGaA |
| AstraZeneca PLC |
| Alteon Inc. |
| Thermo Fisher Scientific Inc. |
| Takeda Pharmaceutical Company Limited |
| Diagnoptics Technologies BV |
| Cell Biolabs Inc. |
| Others |
Supply Flow & Price Mechanics
Heidelberg's carbohydrate chemistry cluster anchors global capacity for carboxymethyllysine synthesis, concentrating pricing power among German and Swiss reference material suppliers who serve FDA-scrutinized diabetes drug trials. EMA MDR compliance timelines extend certification cycles for AGE measurement devices, compressing margins for European IVD manufacturers while elevating technical documentation costs passed downstream.
Pricing Analysis
Certification level creates the primary spread between commodity reagents and regulatory-grade compounds. Three-tier pricing structure separates ISO 17034-accredited reference materials from CE-marked clinical assays and economy research-grade kits. Cost compression in the food industry segment is intensifying because large-scale processors prioritize thermal damage indicators over certification depth. Pharmaceutical sponsors show least price sensitivity due to FDA-enforced assay validation protocols, while academic laboratories exhibit highest elasticity.
Supply Chain Analysis
High-purity amino acid derivative feedstocks draw from specialized carbohydrate chemistry expertise concentrated in Germany, Switzerland, and select United States academic-industrial partnerships. Synthesis of carboxymethyllysine and pentosidine reference compounds rests on scarce Maillard chemistry skills and cold-chain logistics infrastructure. Single-source vulnerability runs through Heidelberg and Munich production nodes for pharmaceutical-grade materials. Distribution runs through contract research organization procurement offices and group purchasing organizations in United States academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration support and technical consultation services are expanding faster than hardware sales as FDA biomarker scrutiny forces sponsors toward ongoing assay validation partnerships. This service-attach dynamic elevates recurring revenue stability above transactional reagent margins.
For Market Incumbents: Pre-empt mass spectrometry substitution by embedding SERS substrate workflows into preclinical toxicology service bundles. Deepen captive supply of ISO 17034-certified reference materials to defend against emerging German synthesis specialists. Lock in multi-year enterprise contracts with United States academic medical centers before GPO consolidation completes.
For New Entrants and Emerging Players: Establish a beachhead in Japan's METI-funded sarcopenia research segment where domestic AGE biomarker supply remains underdeveloped. Target cosmetic anti-aging claims substantiation services for French skincare manufacturers seeking third-party glycation inhibition testing. Pursue direct technical support relationships with Stanford and Harvard Medical School laboratories rather than distributor intermediation.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA and EMA compliance timelines create durable moats around quality management systems. Acquisition candidates with notified body relationships for MDR Article 10 technical documentation command scarcity premiums. Watch for PMDA guidance finalization on glycation endpoints as inflection signal for Japan market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17034 Reference Material Accreditation | FDA scrutiny of diabetes drug trials forces exclusive sourcing from measurement-uncertainty-documented suppliers. |
| Non-Invasive Autofluorescence Device CE Marking | EMA MDR Article 10 clinical performance studies extend certification cycles for European IVD manufacturers. |
| SERS Substrate Platform Integration | Pharmaceutical toxicology groups adopt surface-enhanced Raman spectroscopy to cut analytical turnaround times. |
| Group Purchasing Organization Contract Consolidation | United States academic medical centers displace direct manufacturer relationships for analytical reagent procurement. |
| Japan METI Research Partnership Structuring | Public funding streams for sarcopenia and vascular complication studies create dedicated AGE biomarker demand. |
Methodological Framework
Desk research of FDA guidance documents, EMA MDR technical specifications, and ClinicalTrials.gov biomarker endpoints preceded structured interviews with drug development executives, regulatory affairs leads at IVD manufacturers, hospital laboratory directors, and reference material procurement managers. Secondary validation drew from ISO accreditation databases, notified body certification records, and academic gerontology program funding disclosures. Bottom-up demand modeling across end-user segments triangulated against top-down pharmaceutical R&D expenditure allocations.
Assumptions held FDA biomarker scrutiny intensity and EMA MDR compliance timelines constant across the projection horizon, while varying academic research funding trajectories and mass spectrometry substitution rates. Segmentation dimensions modeled include product type certification grade, application regulatory pathway, and end-user procurement authority structure. CAGRs derived from segment-level demand build-ups incorporating NIH longevity research budget allocations and METI-funded initiative disbursements.
Macroeconomic conditions sit as an overlay; deviation in federal research funding appropriations or pharmaceutical R&D budget reallocations would shift the trajectory. Forecasts reflect assumptions regarding regulatory pathway stability and synthesis expertise scarcity persistence. Quarterly review of FDA biomarker guidance updates and EMA notified body capacity indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market