
 Adult Clinical Nutrition Market | 2026-2036
Adult Clinical Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Adult Clinical Nutrition Market Insights
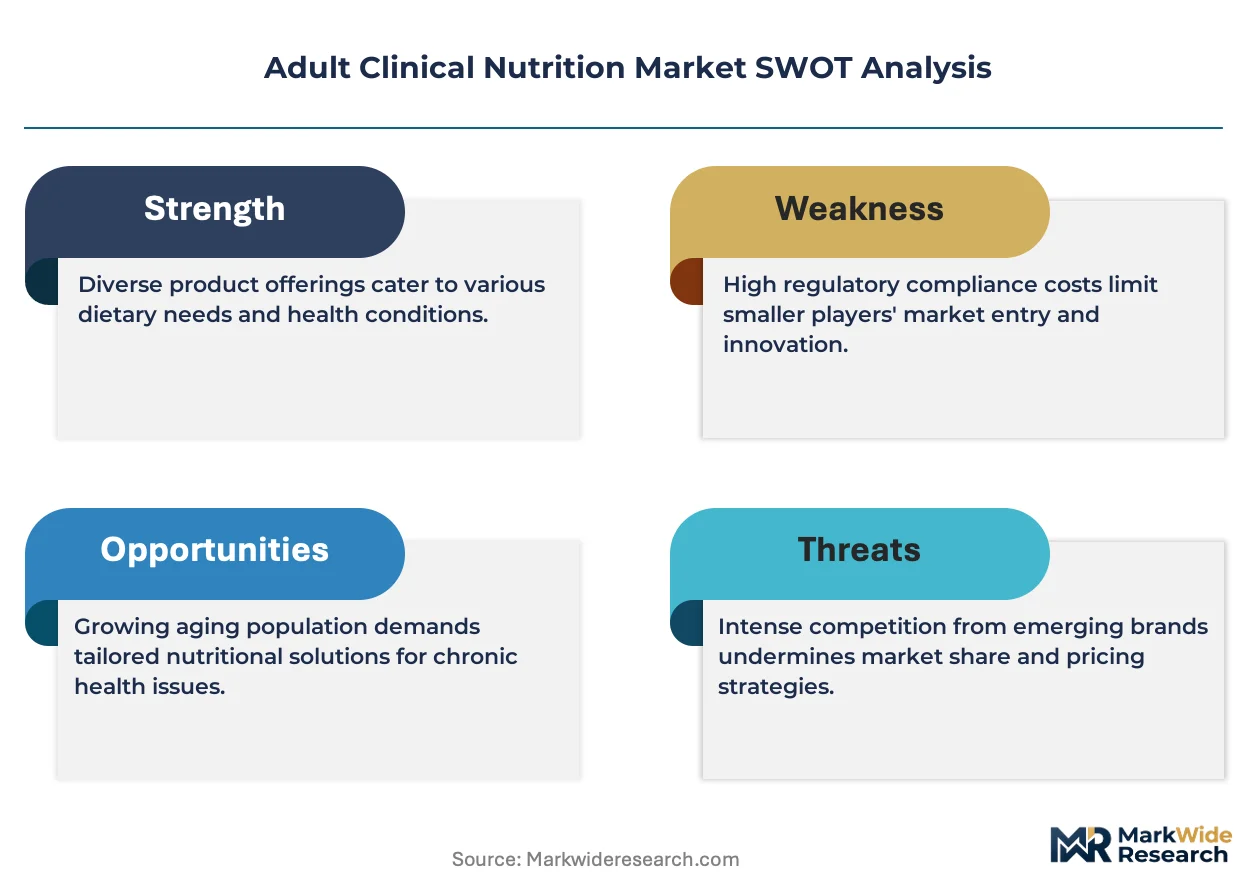
Project finance and hospital leasing arrangements for nutrition formularies is tilting competitive access toward suppliers with balance-sheet depth. Abbott Laboratories leverages captive manufacturing of amino acid solutions to sustain margin on parenteral lines. Fresenius Kabi AG anchors European hospital contracts through integrated dialysis-nutrition bundles. Nestlé Health Science competes in homecare channels with ready-to-drink portfolios that bypass institutional purchasing committees.
Adult clinical nutrition comprises medically formulated substrates—proteins, lipids, carbohydrates, vitamins, and trace elements—delivered orally, enterally, or intravenously to patients with compromised absorption or elevated metabolic needs, with osmolality and nitrogen content calibrated to disease state. Enteral formulas lead volume due to lower complication rates versus parenteral routes, while oncology applications command premium positioning as immuno-nutrition blends gain protocol adoption. Homecare delivery mode is expanding fastest as discharge planning shifts nutrition support beyond hospital walls.
FDA oversight of medical foods and EMA's Medical Device Regulation frame product classification, labeling claims, and reimbursement eligibility across jurisdictions. The EPA and national health technology assessment bodies influence hospital procurement by embedding environmental criteria into tender evaluations. Stakeholders must monitor evolving reimbursement codes for outpatient enteral therapy as payers recalibrate site-of-care economics.
Market Dynamics
Medicare readmission penalties are restructuring hospital nutrition procurement, forcing acute-care facilities to front-load enteral formula investments that reduce length-of-stay metrics and avoid reimbursement clawbacks.
Growth Catalysts
- ICU capacity expansion:United States hospital construction is adding specialized metabolic support units that standardize enteral feeding protocols from admission.
- FDA purity standard tightening:Reformulation mandates for parenteral lipid emulsions are accelerating supplier R&D spend on next-generation emulsion stability.
- Immuno-nutrition protocol adoption:Oncology departments are integrating arginine, omega-3, and nucleotide blends into perioperative care pathways.
Market Restraints
- Fish oil supply concentration:Parenteral lipid emulsion feedstock depends on Peruvian and Chilean anchovy harvest volatility.
- EMA Medical Device Regulation compliance costs:Reclassification of enteral delivery systems as Class IIa devices extends certification timelines for European market entry.
- Homecare reimbursement code fragmentation:United States state-level Medicaid variation creates administrative burden that slows discharge-to-home nutrition transitions.
Strategic Opportunities
- Ready-to-drink homecare bypass:Direct-to-patient subscription models circumvent institutional purchasing committee gatekeeping.
- EPA environmental tender criteria:Sustainability scoring in United States hospital procurement creates differentiation for suppliers with lifecycle-certified packaging.
- Integrated dialysis-nutrition bundles:European renal care networks are consolidating vendor relationships across fluid management and nutritional support.
Industry Challenges
- Clinical nutrition specialist workforce gaps:Certified nutrition support clinicians remain concentrated in academic medical centers, limiting protocol standardization in community hospitals.
- Legacy EMR integration friction:Enteral feeding order sets require custom build-outs within Cerner and Epic implementations that delay automated dosing alerts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adult Clinical Nutrition Market |
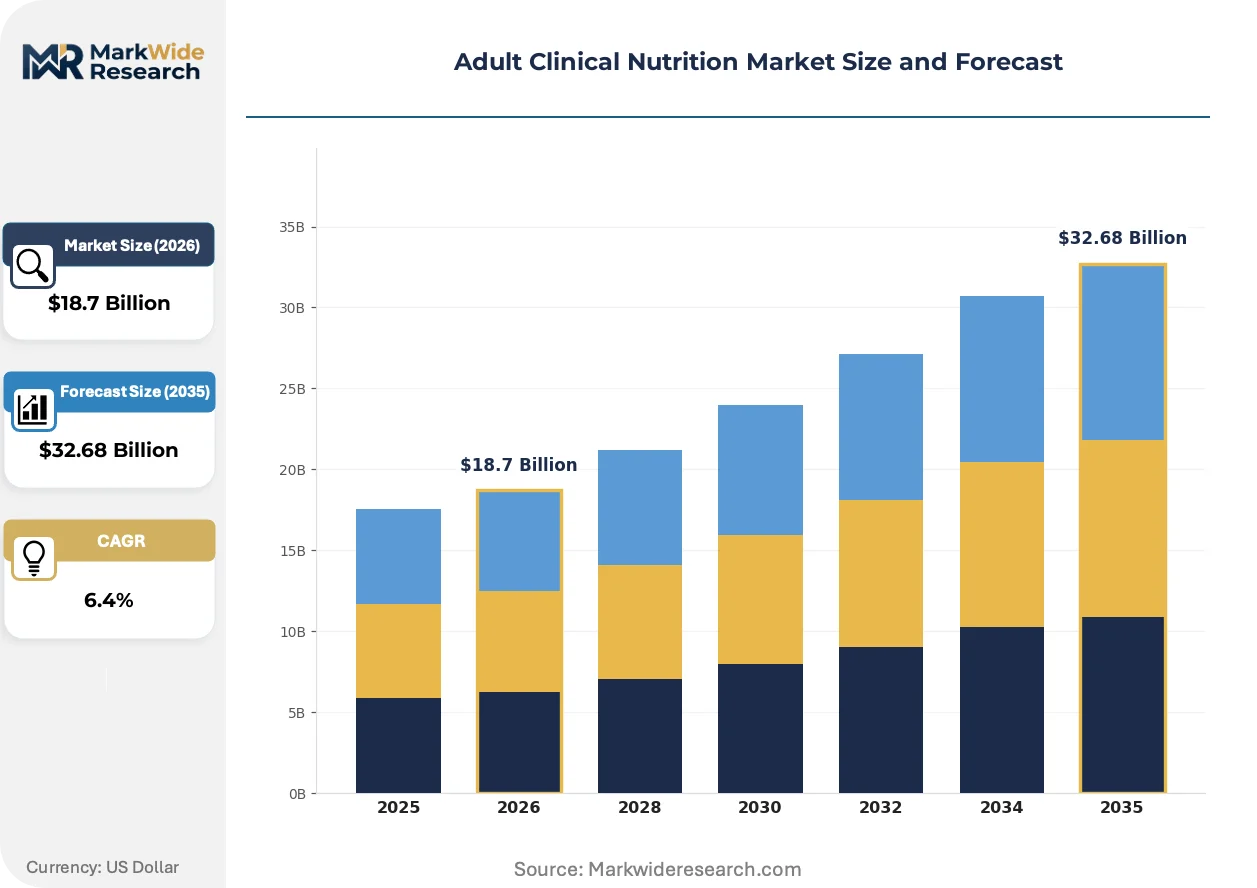
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Nutritional Supplements, Enteral Formulas, Parenteral Nutrition, Functional Foods End User: Hospitals, Outpatient Clinics, Nursing Homes, Homecare Application: Oncology, Neurology, Gastroenterology, Critical Care Delivery Mode: Liquid, Powder, Ready-to-Drink, Tablets |
| Companies Covered | Abbott Laboratories, Nestlé Health Science, Danone S.A., Fresenius Kabi AG, Baxter International Inc., B. Braun Melsungen AG, Mead Johnson Nutrition, Otsuka Pharmaceutical Co., Ltd., Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adult Clinical Nutrition Market Trends and Innovations
Digital connectivity is penetrating enteral delivery devices, generating real-time adherence data that reshapes how payers evaluate outpatient nutrition therapy effectiveness.
Smart pump connectivity with cloud-based monitoring platforms is virtualizing the traditional nurse-driven feeding verification workflow. Home health agencies are deploying these systems fastest in United States Medicare Advantage plans seeking to reduce emergency department visits. The technology is virtualizing compliance documentation into automated insurance-submittable records that compress administrative overhead.
EMA's Medical Device Regulation enforcement is elevating biocompatibility testing requirements for enteral feeding tubes and connectors. Manufacturers must now submit extended cytotoxicity and sensitization data that extends product development cycles by twelve to eighteen months. European hospital procurement teams are responding by consolidating supplier lists to favor MDR-compliant incumbents with dossier depth.
Site-of-care economics are compressing the traditional hospital-centric nutrition support model. United States discharge planners are routing stable patients to home infusion pharmacies that coordinate with visiting nurses for parenteral line management. This channel rotation is most visible in oncology and post-surgical recovery verticals where length-of-stay reduction directly improves facility margin.
Adult Clinical Nutrition Market Segmentation
Segmentation in adult clinical nutrition reveals how reimbursement mechanics and site-of-care economics allocate demand across delivery modes and institutional settings. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Mature hospital-centric formats dominate revenue concentration while emerging home-compatible formats reshape volume trajectories.
- Oral Nutritional Supplements:Polymeric and disease-specific powders or liquids designed for patients with intact gastrointestinal function but inadequate oral intake. Demand concentrates in United States nursing home discharge protocols where Medicare Advantage plans bundle these into post-acute care bundles to reduce readmission penalties.
- Enteral Formulas:Tube-delivered polymeric, oligomeric, or modular substrates calibrated by osmolality and nitrogen content for compromised absorption. ICU capacity expansion across United States academic medical centers drives standardized feeding protocol adoption from admission.
- Parenteral Nutrition:Intravenous amino acid, glucose, and lipid emulsion formulations for intestinal failure or severe malabsorption. FDA purity standard tightening for lipid emulsions forces reformulation investments that compress margins for suppliers lacking captive manufacturing.
- Functional Foods:Medical foods with targeted nutrient profiles for specific disease states outside standard formula categories. Homecare channels in United States Medicare Advantage networks absorb these fastest as direct-to-patient subscription models bypass institutional purchasing committees.
Enteral formulas retain volume leadership; functional foods hold the steepest expansion curve.
End User:
Cost tier stratification separates high-acuity institutional settings from lower-cost ambulatory and residential channels.
- Hospitals:Acute-care facilities with specialized metabolic support units and standardized enteral feeding protocols. Medicare readmission penalties restructure procurement toward front-loaded formula investments that reduce length-of-stay metrics.
- Outpatient Clinics:Ambulatory infusion centers and specialty clinics managing stable parenteral nutrition patients. United States discharge planners route oncology and post-surgical recovery patients here to improve facility margin through length-of-stay reduction.
- Nursing Homes:Long-term care facilities with high prevalence of dysphagia and protein-energy malnutrition. Medicaid reimbursement variation across United States states creates administrative burden that slows nutrition protocol standardization.
- Homecare:Patient-resident settings with visiting nurse coordination and remote monitoring infrastructure. Smart pump connectivity with cloud-based platforms virtualizes compliance documentation into automated insurance-submittable records.
Hospitals command revenue concentration; homecare gains share fastest through site-of-care rotation.
Application:
Application segmentation tracks how disease-state specificity commands premium positioning through immuno-nutrition and metabolic calibration.
- Oncology:Perioperative and chemoradiation support with arginine, omega-3, and nucleotide-enriched immuno-nutrition blends. United States cancer centers integrate these into standardized care pathways that improve surgical outcomes and reduce complication-related costs.
- Neurology:Enteral support for stroke, Parkinson's, and amyotrophic lateral sclerosis patients with dysphagia. Swallowing disorder prevalence in aging United States populations drives demand for texture-modified and fiber-enriched formulas.
- Gastroenterology:Disease-specific formulations for inflammatory bowel disease, short bowel syndrome, and malabsorption disorders. EMA Medical Device Regulation reclassification of enteral delivery systems as Class IIa devices extends certification timelines for European market entry.
- Critical Care:ICU metabolic support with high-protein, immune-modulating substrates for sepsis, trauma, and burns. Specialized metabolic support unit construction across United States hospital systems standardizes feeding protocols from admission.
Critical care anchors volume throughput; oncology secures the highest margin per patient day.
Delivery Mode:
Customer type segmentation separates institutional bulk procurement from individual patient convenience and compliance optimization.
- Liquid:Pre-mixed enteral formulas in ready-to-hang containers for hospital and nursing home tube feeding. Shelf-stable packaging with lifecycle certification gains differentiation in EPA-scored United States hospital tenders.
- Powder:Reconstitutable formulations offering shipping efficiency and extended stability for homecare and international distribution. Peruvian and Chilean anchovy harvest volatility constrains parenteral lipid emulsion feedstock availability.
- Ready-to-Drink:Single-serve oral supplements in palatable formats for ambulatory and homecare patients. Direct-to-patient subscription models circumvent institutional purchasing committee gatekeeping in United States Medicare Advantage networks.
- Tablets:Compressed nutrient delivery for patients with intact swallowing function requiring discrete supplementation. Limited penetration outside geriatric and bariatric surgery follow-up protocols due to caloric density constraints.
Liquid formats dominate institutional procurement; ready-to-drink climbs fastest through homecare channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in clinical nutrition tilt toward deficit regions with aging demographics, while manufacturing concentrates where pharmaceutical infrastructure and regulatory dossier depth overlap. The United States runs the largest import requirement for parenteral lipid emulsions, offset by European and Asian production clusters.
United States
Medicare Advantage expansion and ICU capacity construction in Texas and Florida drive enteral formula absorption. FDA purity standard tightening for lipid emulsions forces domestic reformulation partnerships. The Research Triangle in North Carolina anchors clinical trial infrastructure for immuno-nutrition protocol validation.
Germany
Integrated dialysis-nutrition bundles through Fresenius Kabi anchor hospital procurement consolidation. EMA Medical Device Regulation enforcement extends enteral delivery system certification timelines. The Rhine-Ruhr corridor concentrates parenteral amino acid manufacturing with captive supply chains.
Japan
Super-aging demographics and homecare infrastructure expansion accelerate ready-to-drink oral supplement demand. PMDA oversight of medical foods frames reimbursement eligibility for disease-specific formulations. The Kansai region around Osaka hosts specialized metabolic support unit engineering.
China
Domestic ICU construction and cancer center proliferation absorb imported enteral formulas while local manufacturing scales. NMPA registration requirements for parenteral nutrition products extend market entry timelines. The Yangtze River Delta clusters pharmaceutical packaging and logistics infrastructure.
Brazil
Private hospital network expansion in São Paulo and Minas Gerais drives standardized feeding protocol adoption. ANVISA medical device classification for enteral delivery systems mirrors EMA complexity. Southeast industrial zones concentrate reconstitutable powder formulation for regional distribution.
Adult Clinical Nutrition Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with feedstock and modular substrate advantages. The market structures around three tiers: diversified health conglomerates with captive nutrition divisions, mid-scale pharmaceutical-nutrition hybrids, and regional formulation specialists. Consolidation pressure concentrates among European hospital contract holders facing MDR compliance cost spikes. Geographic expansion and integrated service bundling represent the dominant competitive vectors.
Among diversified health conglomerates, Abbott Laboratories and Nestlé Health Science occupy positions spanning institutional and homecare channels. Fresenius Kabi AG exemplifies the pharmaceutical-nutrition hybrid archetype with dialysis-nutrition integration. These anchors represent divergent strategic postures: captive manufacturing depth versus direct-to-patient channel bypass.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé Health Science |
| Danone S.A. |
| Fresenius Kabi AG |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Mead Johnson Nutrition |
| Otsuka Pharmaceutical Co., Ltd. |
| Koninklijke DSM N.V. |
| Others |
Pricing and Supply Chain Analysis
Fish oil supply concentration from Peruvian and Chilean anchovy harvests determines both the premium spread for immuno-nutrition formulations and the geographic clustering of parenteral lipid emulsion manufacturing. This single-source dependency forces hospital procurement departments into long-term offtake contracts that compress margins for suppliers lacking backward integration into omega-3 feedstock.
Pricing Analysis
Hospital procurement departments anchor contract-based long-term offtake pricing for enteral formulas, with three-tier pricing structure across premium, standard, and economy levels differentiated by FDA certification tier and volume scale commitments. Price differentiation stems from immuno-nutrition blend complexity and EMA Medical Device Regulation compliance dossier depth. Cost compression in standard polymeric formulas is intensifying because Medicare reimbursement code fragmentation forces suppliers to absorb administrative overhead. Community hospital systems exhibit highest price sensitivity due to constrained formulary budgets, while academic medical centers prioritize clinical outcome data over unit cost.
Supply Chain Analysis
Contract manufacturing for parenteral amino acid solutions concentrates with Abbott Laboratories' captive production in the United States, Fresenius Kabi AG's Rhine-Ruhr corridor facilities in Germany, and B. Braun Melsungen AG's European manufacturing network. Raw material dependencies center on Peruvian anchovy oil for lipid emulsions, corn-derived dextrose for glucose solutions, and fermentation-produced amino acids from Chinese and Indian API suppliers. Single-source vulnerability in omega-3 feedstock creates exposure to El Niño-driven harvest volatility. Distribution runs through hospital GPO contracts in the United States, integrated dialysis-nutrition bundles in Europe, and home infusion pharmacy networks for outpatient parenteral therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adult clinical nutrition is restructuring around service-attach revenue, with smart pump connectivity and cloud-based adherence monitoring expanding faster than commodity formula sales. This recurring-revenue layer rewards suppliers who virtualize compliance documentation into automated insurance-submittable records.
For Market Incumbents: Insulate hospital contract positions by deepening captive manufacturing of amino acid solutions to offset margin compression from FDA purity standard tightening. Lock in EMA Medical Device Regulation dossier depth to extend certification timelines that disadvantage European challengers. Prioritize backward integration into omega-3 feedstock to neutralize anchovy harvest volatility.
For New Entrants and Emerging Players: Pursue direct-to-patient subscription models in United States Medicare Advantage networks, where ready-to-drink homecare formats bypass institutional purchasing committee gatekeeping. Target the functional foods segment with disease-specific formulations for oncology and neurology applications, leveraging EPA-scored sustainability packaging to differentiate in hospital tenders.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors pharmaceutical-nutrition hybrids with integrated service bundling capability. Long-term viability hinges on site-of-care economics rotation toward homecare channels. Watch for inflection in smart pump connectivity adoption rates as the signal for platform consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Investment | EMA dossier depth extends certification timelines that filter European market entrants. |
| Homecare Channel Expansion | Direct-to-patient models circumvent hospital GPO gatekeeping in Medicare Advantage networks. |
| Immuno-Nutrition R&D | Arginine and omega-3 blends command premium positioning in oncology perioperative protocols. |
| Smart Pump Connectivity | Cloud-based adherence monitoring virtualizes compliance into automated reimbursement records. |
| Backward Integration | Captive amino acid production insulates margins from API supply volatility. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, clinical nutrition specialists, GPO contracts directors, and home infusion pharmacy operators; and secondary validation through FDA 510(k) filings, EMA Medical Device Regulation submissions, CMS Medicare reimbursement databases, and hospital construction permits. Bottom-up enteral formula volume estimates triangulated against top-down Medicare spending data.
Forecast inputs across the analysis window incorporated delivery mode segmentation by liquid, powder, ready-to-drink, and tablet formats; end-user stratification across hospitals, outpatient clinics, nursing homes, and homecare channels; and application-specific modeling for oncology, neurology, gastroenterology, and critical care. CAGRs derived from regression against ICU capacity expansion trajectories, Medicare Advantage enrollment curves, and EMA regulatory enforcement timelines.
Sensitivities concentrate around anchovy harvest volatility, Medicaid reimbursement code harmonization, and smart pump connectivity adoption curves. Quarterly review of FDA purity standard enforcement actions, EMA certification backlog data, and Medicare site-of-care policy bulletins is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
North America Clinical Nutrition Market