
 Intravenous Nutritional Therapy Market | 2026-2036
Intravenous Nutritional Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Intravenous Nutritional Therapy Market Insights
Buyer concentration among hospital networks is shifting toward centralized procurement of parenteral nutrition solutions. Baxter leverages its integrated manufacturing footprint to supply multi-chamber bags at scale across North American health systems. Fresenius Kabi AG anchors European demand through its lipid emulsion portfolio and compounding pharmacy network. Grifols, S.A. differentiates via plasma-derived protein solutions and specialized neonatal formulations.
Intravenous nutritional therapy delivers essential macronutrients, micronutrients, and electrolytes directly into the venous system when enteral feeding is contraindicated, typically formulated as sterile emulsions with osmolarity calibrated between 600 and 900 mOsm/L for peripheral administration. The therapy serves patients with gastrointestinal failure, malabsorption syndromes, or hypermetabolic states requiring bypass of the alimentary tract. Amino acid formulations command premium positioning in oncology and critical care settings where protein synthesis demands peak. Home infusion delivery mode is expanding fastest as payors push cost-bearing to outpatient settings and ambulatory infrastructure matures. Hospital infusion retains volume leadership but faces margin compression from group purchasing organization contract tiers.
FDA enforces current Good Manufacturing Practice standards for outsourced compounding facilities under Section 503B of the FD&C Act, while EMA's GMP Annex 1 revision mandates stricter environmental monitoring for sterile medicinal products. These frameworks elevate compliance costs for smaller compounders and favor manufacturers with validated aseptic filling lines and automated isolator technology. Stakeholders must monitor reimbursement parity between inpatient and home-based parenteral nutrition as this determines channel economics and capital allocation across delivery infrastructure.
Market Dynamics
Hospital procurement centralization among integrated health systems in the United States, Germany, and Japan is compressing supplier margins while elevating sterility compliance thresholds under FDA and EMA frameworks. This structural force favors manufacturers with validated aseptic filling infrastructure and automated isolator technology.
Growth Catalysts
- Home infusion infrastructure maturation:Payor cost-bearing shifts toward outpatient settings are accelerating ambulatory delivery channel expansion across United States health systems.
- FDA Section 503B enforcement:Current Good Manufacturing Practice standards for outsourced compounding facilities are elevating quality thresholds that favor established manufacturers with validated production lines.
- Hypermetabolic patient population expansion:Oncology and critical care settings are driving amino acid formulation demand where protein synthesis requirements peak.
Market Restraints
- Soybean and fish oil input volatility:Lipid emulsion feedstock price fluctuations compress margin stability for manufacturers dependent on agricultural commodity markets.
- European compounding pharmacy concentration:Fresenius Kabi AG's network dominance in Germany and surrounding markets creates supply vulnerability for health systems seeking multi-source procurement.
- Peripheral administration osmolarity ceiling:The 600-900 mOsm/L formulation constraint limits macronutrient density for patients requiring compact volume delivery.
Strategic Opportunities
- Japanese home parenteral nutrition underpenetration:METI-supported ambulatory infrastructure investment creates expansion white space for infusion service providers.
- Plasma-derived protein specialization:Neonatal formulation segments offer premium positioning for manufacturers with fractionation capabilities and specialized compounding expertise.
- EMA GMP Annex 1 revision compliance services:Environmental monitoring mandate expansion creates advisory and technology retrofit revenue streams for sterile facility consultants.
Industry Challenges
- Aseptic processing technician scarcity:Validated cleanroom operations require specialized personnel that compounders struggle to recruit and retain under wage pressure from pharmaceutical manufacturing.
- Multi-chamber bag production line capex intensity:Automated filling and sealing equipment for integrated parenteral nutrition systems demands capital deployment that smaller compounders cannot access.
- Reimbursement parity timeline uncertainty:Inpatient versus home-based parenteral nutrition payment differential delays channel investment decisions by health system administrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravenous Nutritional Therapy Market |
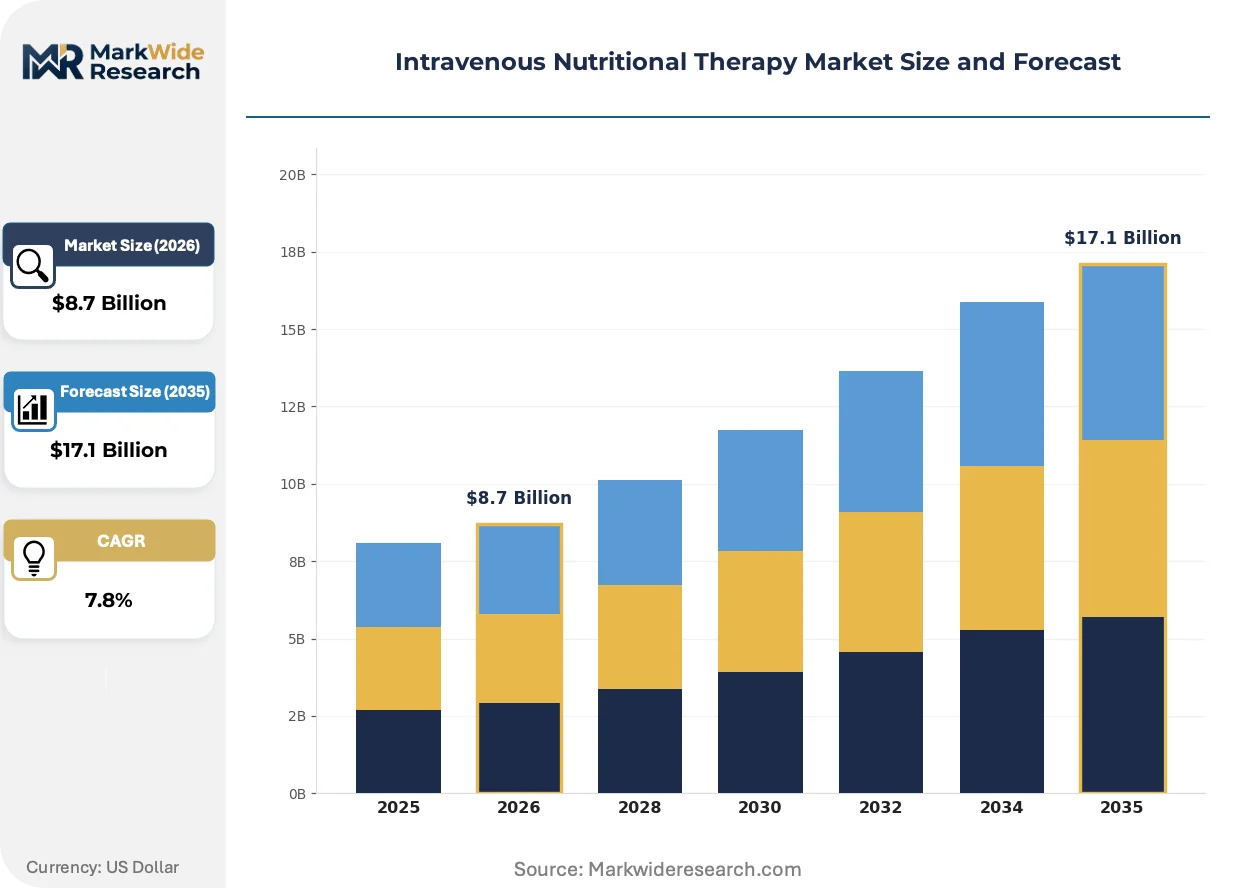
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Amino Acids, Electrolytes, Trace Elements Therapy Area: Oncology, Gastroenterology, Critical Care, Neurology Delivery Mode: Centrally Administered, Peripherally Administered, Home Infusion, Hospital Infusion End User: Hospitals, Clinics, Homecare, Rehabilitation Centers |
| Companies Covered | Baxter, Fresenius Kabi AG, B. Braun SE, Otsuka Pharmaceutical Co., Ltd., ICU Medical, Inc., Grifols, S.A., Pfizer, Inc., JW Life Science Corporation, Kelun Industry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravenous Nutritional Therapy Market Trends and Innovations
Multi-chamber bag technology and automated compounding systems are actively reshaping formulation delivery economics while regulatory environmental monitoring mandates elevate facility investment requirements. These forces are compressing the viable supplier base toward integrated manufacturers.
Multi-chamber bag systems separate amino acids, glucose, and lipid emulsions in distinct compartments that mix immediately before administration. Critical care units in United States academic medical centers are adopting these configurations to reduce compounding labor and contamination risk. This technology is expanding into oncology infusion centers where pharmacy workflow efficiency determines treatment chair throughput.
EMA's GMP Annex 1 revision mandates continuous environmental monitoring for Grade A and B cleanroom operations with stricter viable particle limits. Compounding facilities across Germany and France face facility retrofit requirements or operational shutdown risk. Sterile medicinal product manufacturers with existing isolator technology are capturing contract volume from facilities lacking upgrade capital.
Health system pharmacy directors are consolidating parenteral nutrition procurement through group purchasing organization tier contracts that bundle multi-chamber bags with lipid emulsion volume commitments. Academic medical centers in the United States are displacing standalone hospital negotiations with system-wide agreements covering dozens of facilities. This concentration is most visible in California and Texas where integrated delivery networks control substantial infusion service capacity.
Intravenous Nutritional Therapy Market Segmentation
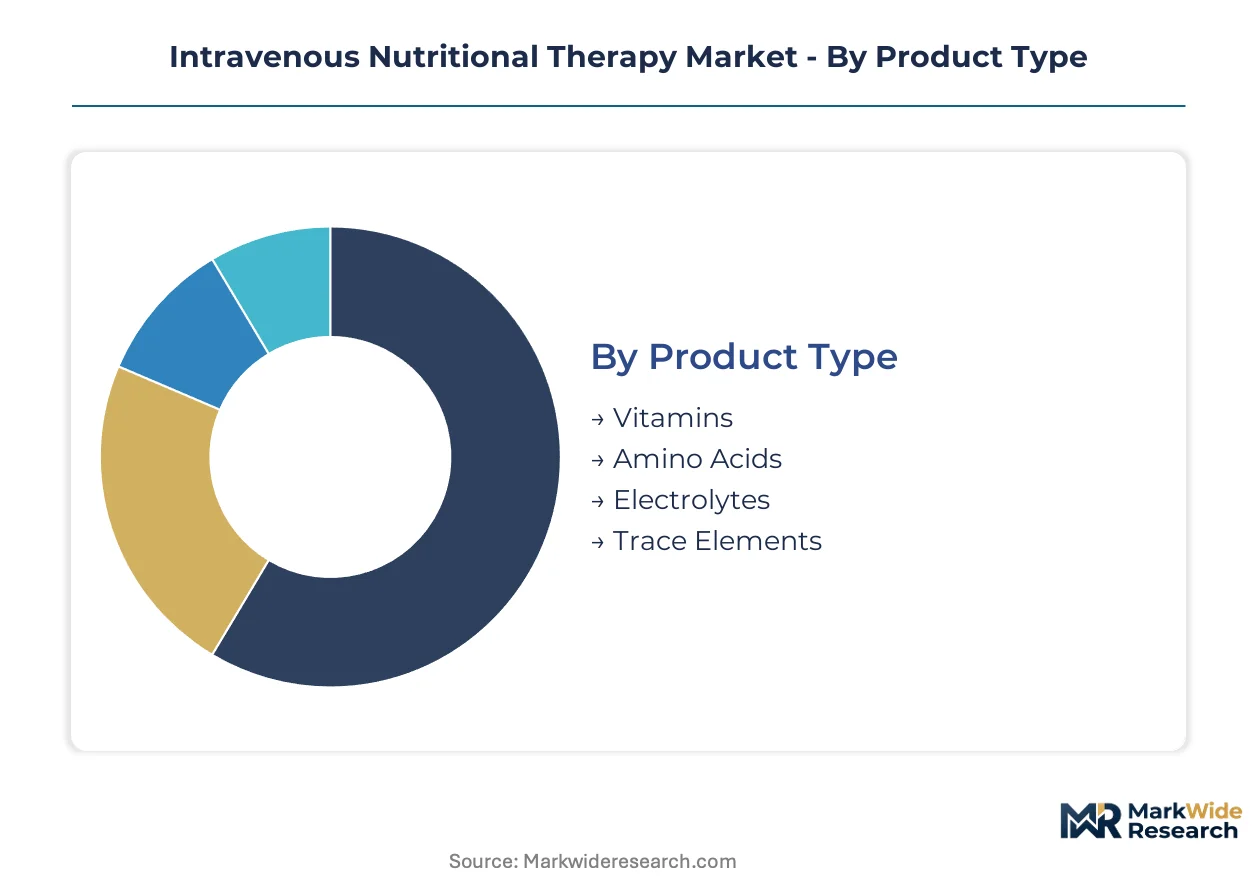
Segmentation in intravenous nutritional therapy reveals distinct regulatory pathways and reimbursement profiles that shape supplier economics. Each dimension carries specific sterility certification requirements and channel margin structures that determine competitive positioning.
Product Type:
Amino acid formulations and lipid emulsions demand FDA Section 503B compliance or EMA GMP Annex 1 certification depending on compounding site location, while electrolyte and trace element solutions face lighter documentation burdens.
- Amino Acids:Protein synthesis substrates formulated in concentrations ranging from 3% to 20% for hypermetabolic states. Oncology and critical care units in United States academic medical centers concentrate procurement through group purchasing organization tier contracts. FDA 503B sterility mandates elevate entry barriers for compounders lacking validated isolator infrastructure.
- Lipid Emulsions:Soybean oil, fish oil, or olive oil-based energy carriers providing essential fatty acids. German hospital networks anchor European demand through Fresenius Kabi AG's compounding pharmacy network. EMA environmental monitoring requirements under Annex 1 revision compress the viable supplier base toward integrated manufacturers with automated filling lines.
- Vitamins:Water-soluble and fat-soluble micronutrient cocktails preventing deficiency states in long-term parenteral nutrition patients.
- Electrolytes:Sodium, potassium, calcium, and magnesium solutions maintaining acid-base balance and osmotic equilibrium.
- Trace Elements:Zinc, copper, manganese, and selenium formulations dosed in microgram quantities for metabolic enzyme function.
Amino acids sits at the top of the volume ranking, with lipid emulsions climbing the fastest.
Therapy Area:
Oncology and critical care generate premium pricing due to hypermetabolic protein demands, while gastroenterology and neurology segments operate under tighter reimbursement constraints.
- Critical Care:ICU settings requiring immediate nutritional intervention for sepsis, trauma, or multi-organ failure. United States integrated health systems centralize procurement of multi-chamber bag systems across dozens of facilities. Amino acid density requirements peak here, driving formulation complexity and sterility assurance costs.
- Oncology:Chemotherapy-induced mucositis and gastrointestinal toxicity necessitating bypass of enteral routes. Japanese infusion centers are expanding ambulatory capacity under METI infrastructure investment programs. Home parenteral nutrition penetration remains underdeveloped relative to Western markets.
- Gastroenterology:Short bowel syndrome, Crohn's disease, and intestinal failure requiring chronic nutritional support.
- Neurology:Stroke, traumatic brain injury, and neurodegenerative conditions with swallowing dysfunction or altered consciousness.
Critical care commands the highest per-patient revenue, with oncology gaining share fastest.
Delivery Mode:
Central versus peripheral administration determines osmolarity constraints and formulation economics, while channel selection between hospital and home settings drives reimbursement rate differentials.
- Home Infusion:Ambulatory delivery of parenteral nutrition through specialized nursing services and patient training programs. United States payor cost-bearing shifts are accelerating infrastructure investment by integrated delivery networks. Reimbursement parity uncertainty between inpatient and outpatient settings delays capital allocation decisions.
- Centrally Administered:Central venous catheter delivery permitting hyperosmolar formulations above 900 mOsm/L. Texas and California health systems dominate procurement volume through consolidated group purchasing agreements.
- Peripherally Administered:Peripheral vein delivery limited to 600-900 mOsm/L osmolarity ceiling, restricting macronutrient density.
- Hospital Infusion:Inpatient administration retaining volume leadership but facing margin compression from procurement centralization.
Hospital infusion retains volume leadership, with home infusion expanding most quickly.
End User:
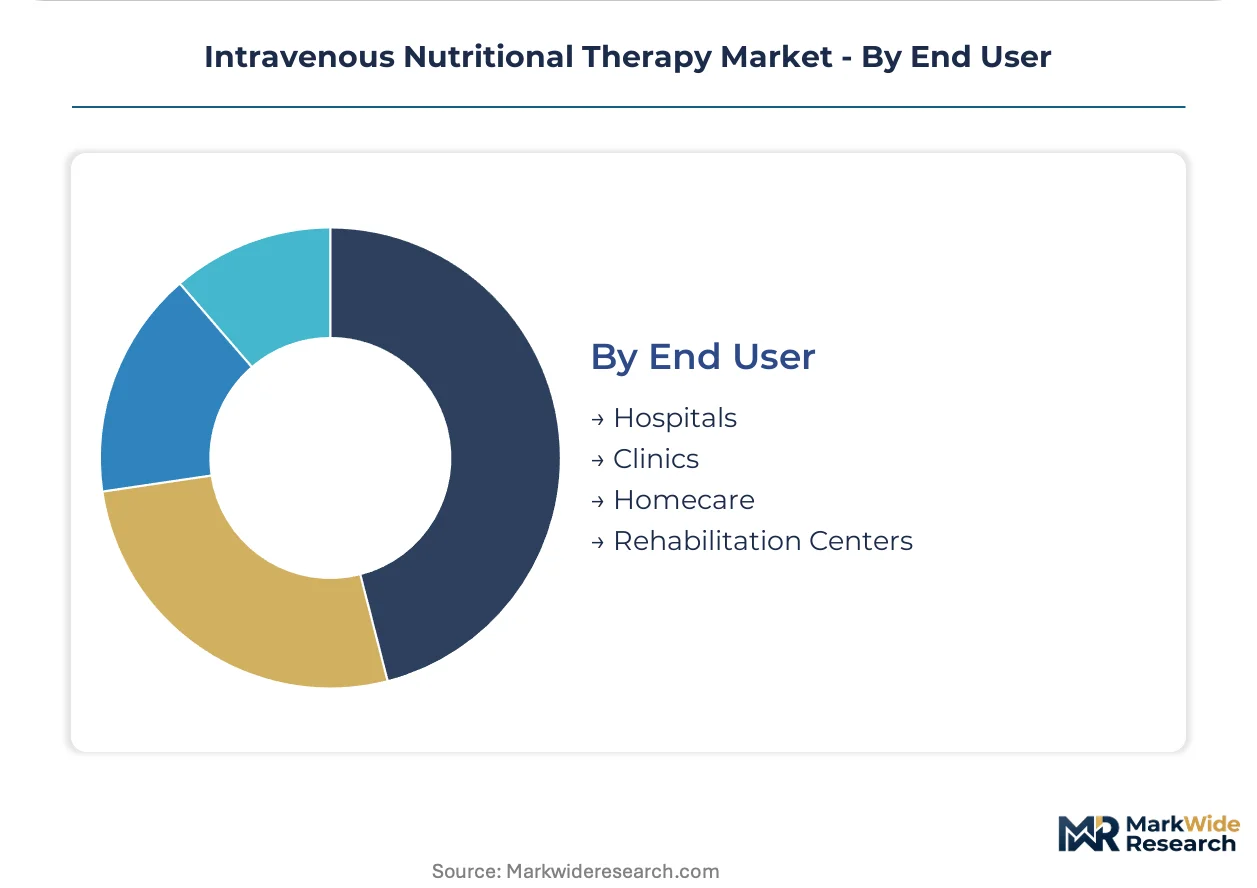
Hospital and homecare segments diverge sharply in procurement sophistication, with clinics and rehabilitation centers occupying intermediate positions on compliance burden and contract scale.
- Hospitals:Academic medical centers and community hospitals with integrated pharmacy compounding or outsourced 503B relationships. German university hospitals anchor European demand through centralized tender processes. EMA GMP Annex 1 facility retrofit requirements are displacing smaller compounders from approved supplier lists.
- Homecare:Specialized infusion service providers managing long-term parenteral nutrition patients in residential settings. Japanese METI-supported ambulatory infrastructure investment creates expansion white space for service providers. Reimbursement rate negotiation complexity slows market entry.
- Clinics:Outpatient oncology and gastroenterology practices with limited in-house compounding capabilities.
- Rehabilitation Centers:Post-acute facilities transitioning patients from hospital to home parenteral nutrition.
Hospitals dominate procurement volume, with homecare showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's compounding pharmacy networks anchor European supply chains, while Japan's ambulatory infrastructure lags Western home infusion penetration despite comparable aging demographics. These divergent development trajectories create asymmetric expansion opportunities across the three major demand centers.
United States
Integrated health systems in Texas and California concentrate procurement through group purchasing organization tier contracts covering dozens of facilities. FDA Section 503B enforcement elevates compliance costs for outsourced compounding, favoring manufacturers with validated aseptic filling infrastructure. Academic medical centers in Boston and New York Metro displace standalone hospital negotiations with system-wide agreements.
Germany
University hospitals anchor European demand through centralized tender processes that bundle multi-chamber bags with lipid emulsion volume commitments. EMA's GMP Annex 1 revision mandates stricter environmental monitoring for Grade A and B cleanroom operations, compressing the viable supplier base. The Rhine-Ruhr industrial corridor hosts concentrated compounding pharmacy capacity serving hospital networks across Western Europe.
Japan
METI-supported ambulatory infrastructure investment accelerates home parenteral nutrition channel development, though reimbursement parity uncertainty delays capital allocation decisions. Oncology infusion centers in Tokyo and Osaka expand capacity under government healthcare modernization programs. Domestic manufacturers face import competition from Korean and Chinese suppliers in standard formulation segments.
China
Kelun Industry Group anchors domestic production capacity serving hospital networks in the Yangtze River Delta and Pearl River Delta regions. NMPA sterility requirements for compounded parenteral nutrition are tightening quality thresholds, elevating compliance costs for smaller compounders. Beijing-Tianjin-Hebei hospital procurement centralization mirrors Western integrated health system consolidation patterns.
Intravenous Nutritional Therapy Market Competitive Landscape
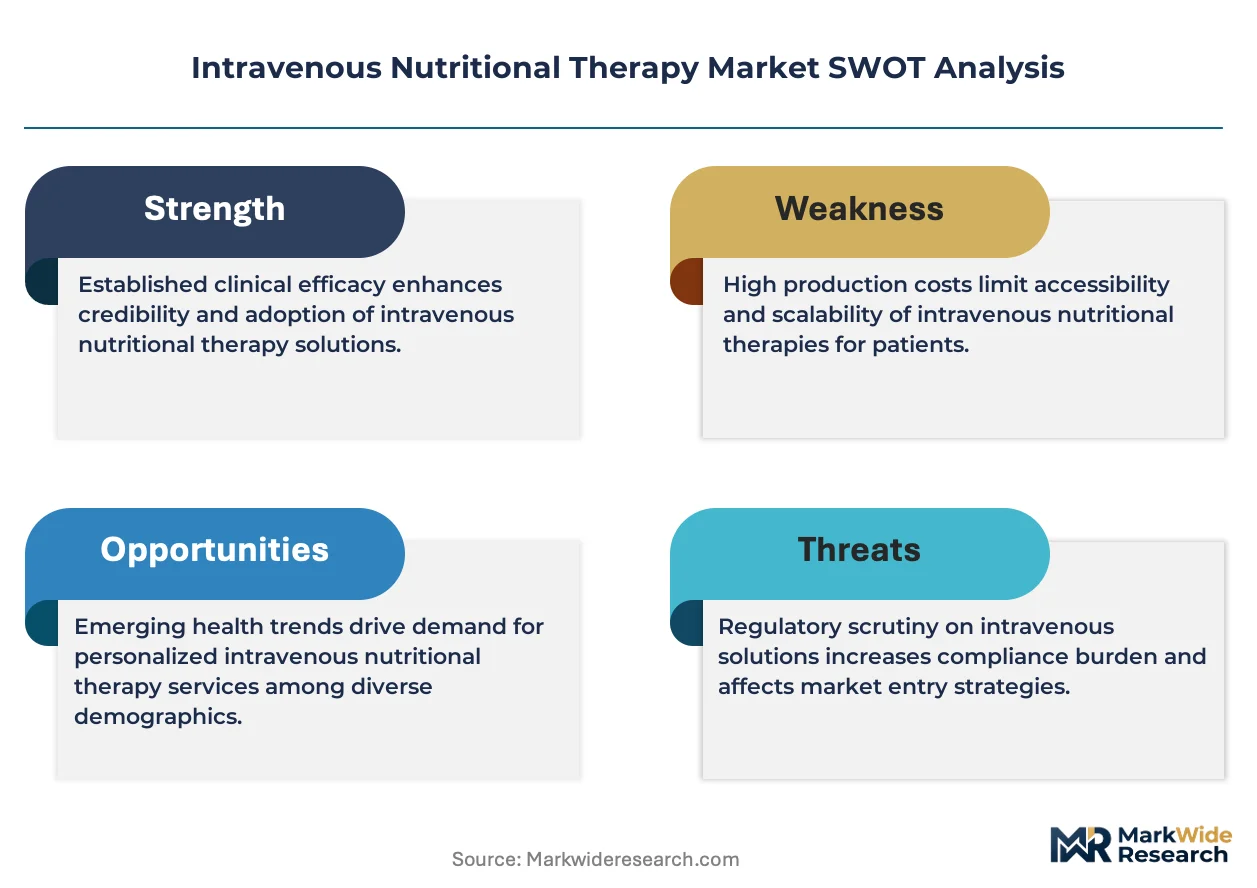
Diversified conglomerates compete with focused pure-play specialists across formulation, compounding, and delivery infrastructure segments. The supplier base concentrates toward integrated manufacturers with validated aseptic filling lines and automated isolator technology, while smaller compounders face displacement from approved supplier lists. Three strategic archetypes dominate: pharmaceutical conglomerates with parenteral nutrition divisions, specialized infusion therapy companies, and regional compounding pharmacy networks. Competitive moves center on multi-chamber bag production line expansion and EMA GMP Annex 1 compliance service offerings.
Among diversified healthcare conglomerates, Baxter and Fresenius Kabi AG exemplify scale-driven archetypes with integrated manufacturing footprints spanning multiple continents. Grifols, S.A. occupies a specialized position within the plasma-derived protein formulation segment, representing premium-tier positioning in neonatal applications. These three companies anchor the competitive structure, with B. Braun SE and ICU Medical, Inc. representing mid-scale specialists competing on compounding pharmacy network density and automated delivery system technology respectively.
| Leading Market Players |
|---|
| Baxter |
| Fresenius Kabi AG |
| B. Braun SE |
| Otsuka Pharmaceutical Co., Ltd. |
| ICU Medical, Inc. |
| Grifols, S.A. |
| Pfizer, Inc. |
| JW Life Science Corporation |
| Kelun Industry Group |
| Others |
Pricing and Supply Chain Analysis
Integrated health system procurement concentration in the United States, Germany, and Japan drives contract-based long-term offtake pricing with volume-tier discounts that compress margins for compounders lacking multi-chamber bag production scale.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for lipid emulsion formulations as Fresenius Kabi AG and Baxter expand automated filling lines. Pricing stratifies across FDA 503B-certified premium tiers, EMA GMP Annex 1 mid-tiers, and non-certified economy compounders. Cost compression in standard amino acid formulations is intensifying because soybean oil feedstock volatility transfers directly to contract renegotiations. Oncology and critical care units show least price sensitivity due to hypermetabolic formulation complexity, while community hospitals face acute margin pressure from group purchasing organization tier mandates.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States integrated health systems and German university hospital networks force qualification of at least two sterile compounding suppliers per formulation category. Manufacturing concentrates in the United States, Germany, and Japan, with China emerging as a secondary hub through Kelun Industry Group's Yangtze River Delta capacity. Supply chains draw from agricultural commodity markets for soybean and fish oil lipid feedstocks, specialized polymer resins for multi-chamber bag films, and plasma fractionation for protein formulations. Single-source vulnerability concentrates in Fresenius Kabi AG's German compounding pharmacy network. Distribution runs through health system central pharmacies, outsourced 503B facilities, and home infusion service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in intravenous nutritional therapy rests on automated isolator technology cost-down curves and premium-tier positioning in neonatal plasma-derived protein segments.
For Market Incumbents: Lock in group purchasing organization tier contracts through multi-chamber bag volume commitments that displace smaller compounders from approved supplier lists. Expand backward integration into lipid emulsion feedstock sourcing to buffer agricultural commodity volatility. FDA Section 503B enforcement timelines represent the critical threat to non-compliant facilities. For New Entrants and Emerging Players: Launch via Japanese home infusion service partnerships where METI-supported ambulatory infrastructure investment outpaces domestic supply capacity. Target plasma-derived protein specialization in neonatal formulations where Grifols, S.A. maintains limited competition. Reimbursement parity negotiation expertise serves as the essential go-to-market angle for channel access. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with parenteral nutrition divisions are the most active acquirer in this space, seeking automated aseptic filling capabilities. The five-to-ten year viability window favors targets with validated isolator infrastructure and EMA GMP Annex 1 compliance certification. Watch FDA 503B facility inspection frequency as the inflection signal for supplier base consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Isolator Technology Deployment | FDA 503B enforcement elevates compliance costs that favor manufacturers with validated aseptic filling lines. |
| Multi-Chamber Bag Production Scale-Up | Integrated health systems in Texas and California consolidate procurement through volume-tier contracts covering dozens of facilities. |
| EMA GMP Annex 1 Compliance Certification | German university hospital networks disqualify non-compliant compounders from centralized tender processes. |
| Home Infusion Service Network Expansion | United States payor cost-bearing shifts accelerate ambulatory channel investment by integrated delivery networks. |
| Plasma-Derived Protein Fractionation Investment | Neonatal formulation segments offer premium positioning for manufacturers with specialized compounding expertise. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital pharmacy directors, GPO contracts managers, sterile compounding facility operators, and home infusion service executives with secondary validation through FDA 503B facility registration databases, EMA GMP inspection records, hospital procurement contract filings, and CMS Medicare reimbursement data. Bottom-up formulation volume estimates and top-down health system expenditure analysis triangulated to segment-level outputs.
Historical reference periods anchored the projection horizon to observed procurement centralization trends and regulatory enforcement timelines across the analysis window. Segmentation modeling captured product type, therapy area, delivery mode, and end user dimensions with regional regulatory cluster overlays. CAGRs derived from trend extrapolation of amino acid formulation demand in oncology and critical care settings, lipid emulsion volume commitments in German hospital networks, and home infusion channel penetration rates in United States integrated health systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reimbursement parity delays or EMA GMP Annex 1 facility shutdown waves. Forecasts reflect documented assumptions regarding sterility compliance cost trajectories and integrated health system consolidation velocity. Deviation in FDA 503B enforcement intensity or soybean oil commodity price spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Maternal Nutrition Products Market