
 Global Clinical Nutrition Products Market | 2026-2036
Global Clinical Nutrition Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Nutrition Products Market Analysis
Subscription-based replenishment programs for home enteral nutrition is recalibrating how manufacturers capture lifetime patient value. Abbott Laboratories leverages its direct-to-patient logistics network to sustain recurring revenue streams outside hospital purchasing committees. Fresenius Kabi anchors European parenteral nutrition supply through hospital contracting and compounding pharmacy partnerships. Nestlé Health Science competes by extending its specialty nutrition portfolio into rare metabolic disorder protocols.
Clinical nutrition products comprise formulated foods, solutions, and supplements administered enterally or parenterally to patients unable to meet nutritional requirements through standard diet, typically standardized to precise macronutrient ratios, osmolality parameters, and micronutrient densities for tissue repair, immune support, and metabolic maintenance. Enteral formulations dominate volume due to lower complication rates and gut integrity preservation, while parenteral nutrition commands premium positioning in intensive care and bowel failure cases. Oncology application segments are expanding fastest as cancer-related cachexia protocols integrate nutrition into standard supportive care, whereas metabolic disorders represent a concentrated margin pool driven by orphan disease pricing and limited competition.
The FDA regulates clinical nutrition under medical food and drug frameworks depending on intended use and disease claims, while the EMA's F-Gas Regulation affects parenteral lipid emulsion manufacturing through propellant and solvent restrictions. WHO guidelines on inpatient malnutrition screening are reshaping procurement criteria in emerging hospital systems. Stakeholders must monitor how reimbursement authorities in Germany, Japan, and the United States classify clinical nutrition relative to pharmaceuticals versus standard foods, as this determination governs pricing autonomy and formulary placement.
Market Dynamics
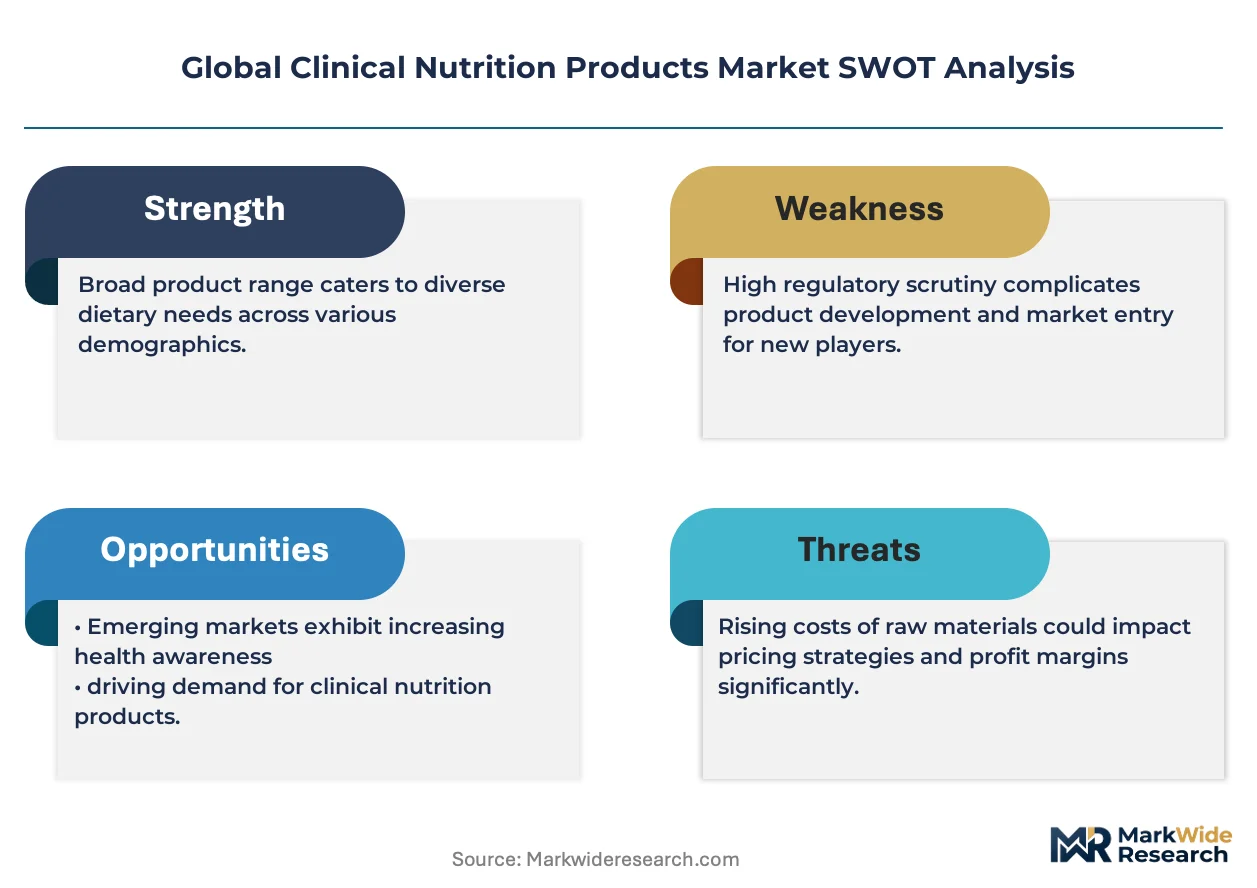
The transition from hospital-based administration to home care delivery is restructuring distribution economics and patient relationship models across the clinical nutrition sector. Reimbursement authorities in mature markets now classify home enteral nutrition as durable medical equipment rather than pharmacy benefit, altering margin capture and logistics requirements for manufacturers.
Growth Catalysts
- WHO malnutrition screening mandates:The World Health Organization's inpatient malnutrition protocols are embedding nutrition assessment into standard hospital admission procedures across emerging health systems, expanding institutional procurement volumes.
- Germany's Diätenverordnung framework:This reimbursement classification system for medical foods creates predictable pricing corridors that incentivize manufacturer investment in specialized metabolic disorder formulations.
- Japan's super-aged demographic profile:With the highest proportion of citizens over 80 globally, Japan's long-term care insurance system generates sustained demand for home-administered enteral products.
Market Restraints
- Fish oil supply concentration:Omega-3 lipid emulsions for parenteral nutrition depend on Peruvian and Chilean anchovy fisheries, exposing formulation costs to El Niño-driven catch volatility and quota restrictions.
- EMA F-Gas Regulation solvent restrictions:Propellant limitations on manufacturing processes for lipid emulsions force capital-intensive process revalidation and temporary supply bottlenecks.
- Substitution by compounded pharmacy formulations:Hospital pharmacies with 503B compounding licenses in the United States produce customized parenteral mixtures at lower unit costs, eroding branded premix volumes.
Strategic Opportunities
- Brazil's ANVISA regulatory harmonization:Alignment with ICH standards accelerates approval timelines for imported clinical nutrition products, opening South America's largest hospital market to multinational entrants.
- Oncology cachexia protocol integration:Cancer centers increasingly bundle nutrition support into chemotherapy regimens, creating indication-specific formulation demand with premium positioning potential.
- Direct-to-patient subscription logistics:Specialized cold-chain delivery networks bypass traditional wholesale distribution, enabling recurring revenue capture and adherence monitoring in home care segments.
Industry Challenges
- Clinical dietitian workforce scarcity:Specialized training programs for nutrition support certification lag demand growth, constraining patient onboarding and protocol compliance in expanded home care programs.
- Cross-border formulation harmonization:Divergent micronutrient labeling requirements between FDA medical food standards and EMA borderline substance classifications force redundant SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Nutrition Products Market |
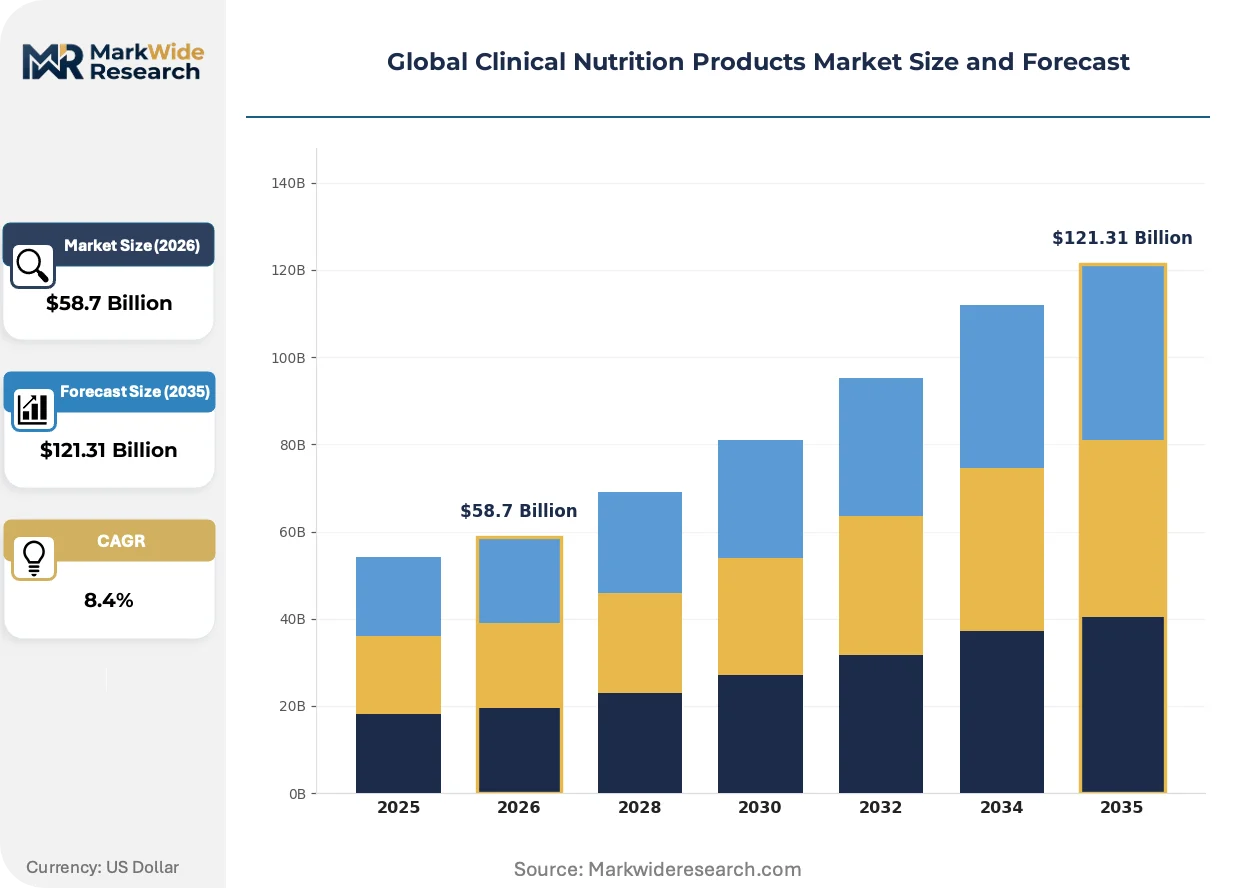
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enteral, Parenteral, Specialty, Nutraceutical Application: Oncology, Gastroenterology, Neurology, Metabolic Disorders End User: Hospitals, Home Care, Nursing Facilities, Rehabilitation Centers Distribution Channel: Online, Pharmacies, Wholesalers, Direct Sales |
| Companies Covered | Danone, B. Braun, Abbott Laboratories, Meiji Holdings, Otsuka Pharmaceutical, Nestlé Health Science, Baxter International, Perrigo Company, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Nutrition Products Market Emerging Trajectories
Formulation science and delivery mechanisms are converging to address the tension between clinical precision and patient autonomy in self-administered nutrition therapy. These developments reshape competitive advantage toward integrated service capabilities rather than commodity manufacturing.
Ready-to-hang enteral feeding systems is modularizing home care infrastructure by eliminating manual decanting and reducing contamination risk. Home health agencies in the United States and Germany are adopting these closed-system designs at accelerating rates, compressing the traditional distinction between acute care and ambulatory nutrition delivery.
The EMA's F-Gas Regulation is tightening solvent and propellant specifications for parenteral lipid emulsion manufacturing, forcing reformulation of legacy products. European manufacturers are responding by investing in supercritical fluid extraction technologies, with intensive care and bowel failure segments absorbing transitional supply constraints.
Hospital purchasing committees are fragmenting into specialty nutrition subcommittees with distinct clinical governance. Oncology and surgical service lines now autonomously specify enteral protocols, displacing centralized pharmacy formulary control, with this pattern most visible in academic medical centers across the United States and Switzerland.
Global Clinical Nutrition Products Market Segmentation
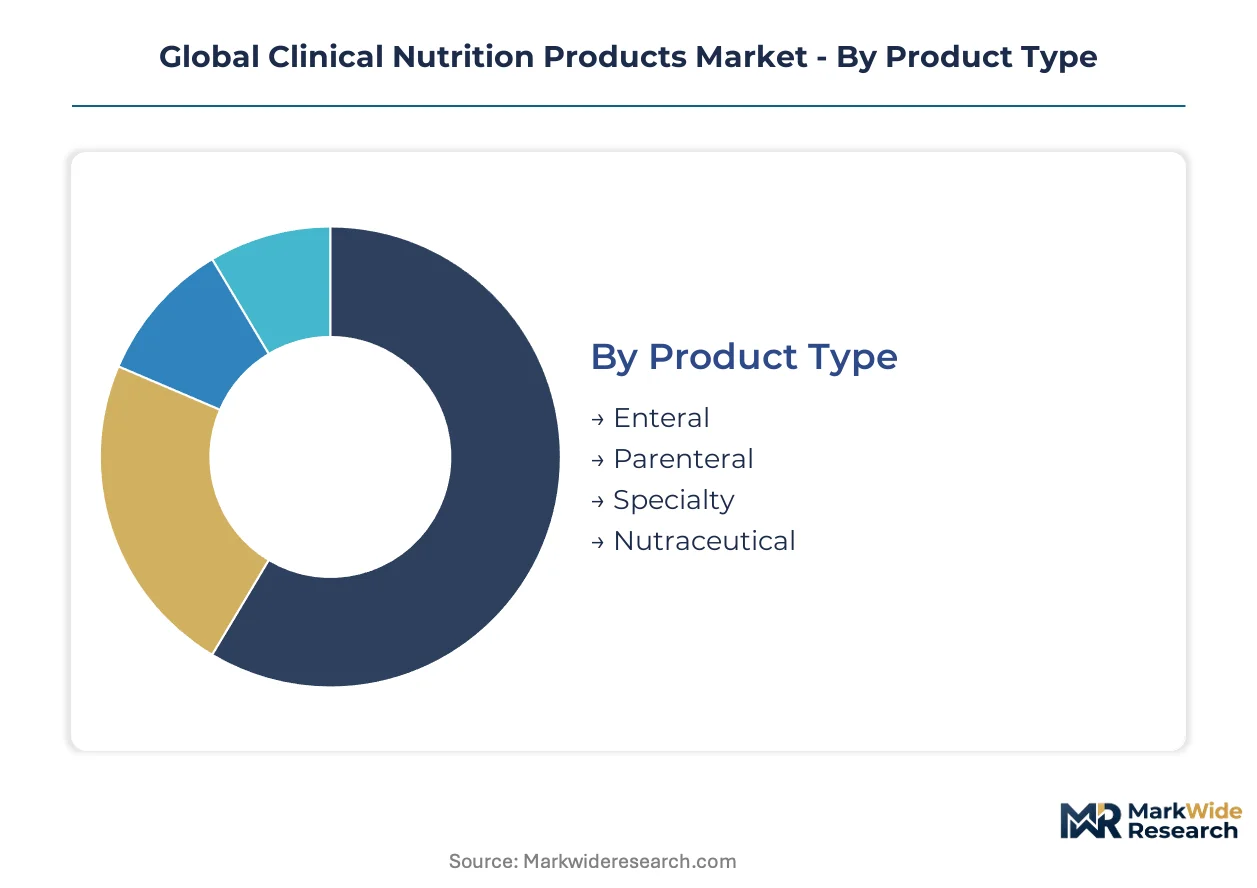
Segmentation in clinical nutrition reveals how reimbursement frameworks, patient acuity, and administration setting interact to determine product specifications and margin structures. Manufacturers configure formulation portfolios around these intersecting demands rather than pursuing uniform market coverage.
Product Type:
Buyers in this category differentiate by route of administration tolerance, infection risk tolerance, and metabolic stability requirements.
- Enteral:Standardized liquid formulations delivered via nasogastric, gastrostomy, or jejunostomy tubes preserve gut mucosal integrity and reduce septic complications versus intravenous alternatives. Home care agencies in Germany and Japan absorb the majority of volume as long-term care insurance frameworks expand tube-feeding coverage for dementia and stroke patients with intact gastrointestinal function.
- Parenteral:Complete nutrient solutions administered intravenously bypass the digestive tract entirely, requiring sterile compounding and lipid emulsion stabilization for patients with bowel failure or severe malabsorption. Intensive care units in the United States concentrate demand for three-chamber bag systems that simplify pharmacy workflow, though 503B compounding pharmacies erode branded premix volumes through customized lower-cost alternatives.
- Specialty:Disease-specific formulations target inherited metabolic disorders such as phenylketonuria or maple syrup urine disease with precisely restricted amino acid profiles. Germany's Diätenverordnung reimbursement corridor incentivizes development of these orphan indications.
- Nutraceutical:Medical food-grade supplements bridge gaps between conventional diet and clinical intervention, typically positioned for preoperative optimization or immune support in oncology protocols.
Enteral leads volumes today; specialty formulations are gaining share fastest through orphan disease pricing mechanisms.
Application:
Clinical indication determines macronutrient density, immunonutrient inclusion, and osmolality specifications across formulation development priorities.
- Oncology:High-protein, omega-3-enriched formulations counter cancer-related cachexia and chemotherapy-induced mucositis, with arginine and nucleotide supplementation showing protocol adoption in academic medical centers. Cancer centers in Switzerland and the United States increasingly bundle these products into supportive care pathways.
- Gastroenterology:Elemental and semi-elemental formulations with predigested peptides and medium-chain triglycerides minimize digestive burden for inflammatory bowel disease and short bowel syndrome patients.
- Neurology:Ketogenic and modified Atkins formulations support drug-resistant epilepsy management, with home administration protocols expanding under specialized dietitian supervision.
- Metabolic Disorders:Genetically targeted amino acid-modified products command premium positioning through limited competition and lifelong therapy requirements.
Gastroenterology anchors current volume; oncology applications are expanding most quickly as cachexia protocols standardize.
End User:
Site of care dictates packaging format, shelf-life requirements, and the depth of clinical support bundled with product delivery.
- Hospitals:Acute care settings demand ready-to-hang closed systems and standardized protocols for ICU nutrition support, with purchasing committees fragmenting into specialty service lines.
- Home Care:Ambulatory patients require monthly supply logistics, pump equipment, and dietitian monitoring, with subscription-based replenishment models capturing recurring revenue outside hospital procurement.
- Nursing Facilities:Long-term care operators prioritize cost-efficient standard formulas for dysphagia and dementia populations, with regulatory compliance around aspiration risk driving thickener and texture-modified product selection.
- Rehabilitation Centers:Post-acute facilities bridge hospital discharge and home independence, demanding transitional protocols and patient education infrastructure.
Hospitals dominate value capture currently; home care is displacing institutional volume fastest as aging demographics shift treatment location.
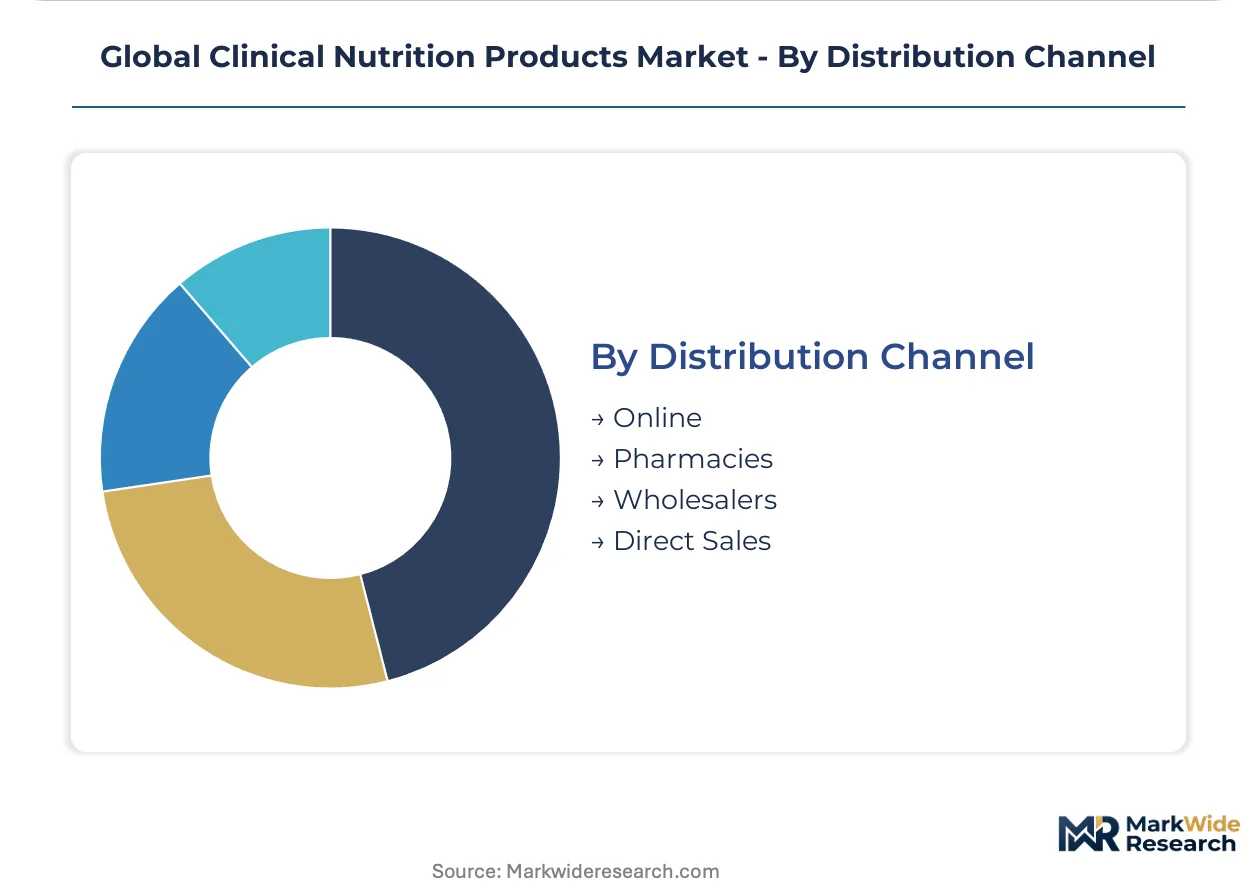
Distribution Channel:
Channel selection reflects patient mobility, reimbursement classification, and cold-chain requirements for lipid-containing formulations.
- Online:Direct-to-patient platforms with specialized cold-chain logistics bypass wholesale markups and enable adherence monitoring through connected delivery infrastructure.
- Pharmacies:Retail and hospital outpatient pharmacies handle prescription medical foods where reimbursement frameworks classify products as pharmacy benefits rather than durable medical equipment.
- Wholesalers:Traditional distribution maintains position in institutional contracts where volume aggregation and just-in-time delivery to hospital warehouses remain efficient.
- Direct Sales:Manufacturer field forces engage specialty nutrition subcommittees and home health agencies for complex metabolic disorder and parenteral nutrition contracts.
Wholesalers retain institutional dominance; online channels are climbing fastest as home care reimbursement shifts toward direct-to-patient models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's reimbursement corridors for medical foods generate more predictable manufacturer investment than the United States' fragmented insurance classifications, while Japan's demographic trajectory sustains demand volumes unmatched by younger populations elsewhere.
United States
FDA medical food regulations and 503B compounding pharmacy licensing create dual pathways for enteral and parenteral products. Hospital purchasing committees in academic medical centers fragment into oncology and surgical subcommittees with autonomous protocol authority. The Boston-Cambridge corridor concentrates metabolic disorder research institutions driving specialty formulation demand.
Germany
The Diätenverordnung framework establishes pricing predictability for inherited metabolic disease nutrition, incentivizing orphan indication development. EMA F-Gas Regulation compliance costs burden lipid emulsion manufacturing with solvent revalidation requirements. North Rhine-Westphalia hosts compounding pharmacy networks supplying home parenteral nutrition to bowel failure patients.
Japan
Long-term care insurance expansion funds home enteral tube feeding for dementia and stroke populations with intact gastrointestinal function. PMDA streamlined approval pathways accelerate metabolic disorder product registrations. The Kanto region around Tokyo concentrates geriatric care facilities driving ready-to-hang system adoption rates.
Brazil
ANVISA regulatory harmonization with ICH standards compresses import approval timelines for multinational clinical nutrition portfolios. Private hospital networks in São Paulo and Rio de Janeiro expand oncology cachexia protocol integration. The Southeast region anchors institutional procurement volume as reimbursement frameworks mature.
Switzerland
Swissmedic borderline substance classifications for medical foods diverge from EMA standards, forcing SKU adaptation for alpine market access. Cancer centers in Basel and Zurich bundle immunonutrient-enriched formulations into supportive care pathways. The Lake Geneva corridor concentrates contract research organizations validating metabolic disorder protocols.
Global Clinical Nutrition Products Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital contracting favoring integrated service capabilities and home care rewarding direct-to-patient logistics infrastructure. The vendor base clusters into three tiers: diversified nutrition conglomerates with metabolic disorder portfolios, parenteral-focused hospital suppliers, and regional enteral specialists. Consolidation pressures concentrate among mid-scale European manufacturers facing EMA compliance cost escalation. Dominant competitive moves include subscription-based patient relationship models and cold-chain delivery network acquisitions.
Among diversified nutrition conglomerates, Danone and Nestlé Health Science occupy positions spanning enteral, parenteral, and metabolic disorder categories across multiple continents. Abbott Laboratories exemplifies the hospital-to-home transition archetype through direct-to-patient logistics infrastructure. These three entities represent contrasting strategic postures: European-headquartered portfolio breadth, North American service integration, and Swiss-American metabolic specialization.
| Leading Market Players |
|---|
| Danone |
| B. Braun |
| Abbott Laboratories |
| Meiji Holdings |
| Otsuka Pharmaceutical |
| Nestlé Health Science |
| Baxter International |
| Perrigo Company |
| Fresenius Kabi |
| Others |
Supply Flow & Price Mechanics
EMA F-Gas Regulation solvent restrictions gate qualified supply for parenteral lipid emulsions and simultaneously create premium-tier pricing access for manufacturers with validated supercritical fluid extraction capabilities. Buyers in Germany and Japan absorb higher unit costs for compliant formulations while non-compliant suppliers face exclusion from hospital contracting.
Pricing Analysis
Capacity additions in Switzerland and Germany are reshaping price floors for sterile parenteral compounding as EMA-compliant facilities capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and cold-chain reliability. Cost compression in standard enteral formulas is intensifying because 503B compounding pharmacies produce customized alternatives at lower unit costs. Home care agencies exhibit highest price sensitivity due to reimbursement classification as durable medical equipment, while intensive care units show lowest sensitivity for three-chamber bag systems.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for temperature-controlled last-mile delivery to home care patients. Manufacturing concentration in Switzerland, Germany, and the United States feeds from Peruvian and Chilean anchovy fisheries for omega-3 lipid emulsions. Single-source vulnerability in fish oil raw materials exposes formulation costs to El Niño-driven catch volatility. Distribution runs through direct-to-patient subscription platforms and hospital GPO contracts in parallel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Germany's Diätenverordnung pricing corridors and the United States' fragmented insurance classifications rewards manufacturers with dual-hemisphere regulatory capabilities and localized compounding partnerships.
For Market Incumbents: Anchor defensive positioning through backward integration into cold-chain logistics networks and captive supply of omega-3 lipid sources. Consolidate compounding pharmacy partnerships in North Rhine-Westphalia to offset 503B pharmacy substitution threats. Prioritize EMA F-Gas Regulation compliance investments to sustain premium-tier hospital access. For New Entrants and Emerging Players: Home care dietitian services represent an underserved buyer archetype with fragmented local provision and unmet adherence monitoring demand. Target Brazil's ANVISA-harmonized import pathway for fastest regulatory access in South America. Deploy direct-to-patient subscription platforms with connected pump infrastructure as primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional enteral specialists because EMA compliance cost escalation forces mid-scale European manufacturers toward exit. Target vertically integrated service providers with metabolic disorder portfolios and home care logistics capabilities. Watch oncology cachexia protocol standardization rates as inflection indicator for premium formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Logistics Acquisition | Abbott Laboratories' direct-to-patient network demonstrates recurring revenue capture outside hospital procurement committees. |
| Supercritical Fluid Extraction Investment | Fresenius Kabi's EMA F-Gas compliance maintains European parenteral supply continuity amid solvent restriction bottlenecks. |
| Metabolic Disorder Portfolio Extension | Nestlé Health Science's rare disease protocols leverage Germany's Diätenverordnung pricing predictability for orphan indications. |
| 503B Compounding Partnership | Hospital pharmacy alliances in the United States erode branded premix volumes through customized lower-cost alternatives. |
| ANVISA Regulatory Harmonization | Multinational entrants accelerate Brazilian market access through alignment with ICH standards for clinical nutrition products. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's clinical nutrition procurement networks. The research combined structured interviews with hospital purchasing committee directors, home care agency operations managers, metabolic disorder clinic dietitians, and GPO contracts specialists with secondary validation through FDA medical food registrations, EMA borderline substance classifications, CMS Medicare durable medical equipment reimbursement data, and WHO malnutrition screening protocol documentation. Bottom-up demand modeling across patient populations triangulated against top-down manufacturer revenue aggregation.
Granularity was maintained at the route-of-administration by application by end-user level throughout the projection horizon. The analytical framework modeled enteral, parenteral, specialty, and nutraceutical product types across oncology, gastroenterology, neurology, and metabolic disorder indications, with hospital, home care, nursing facility, and rehabilitation center settings as distinct demand clusters. CAGRs were derived from patient population growth trajectories, reimbursement framework expansion rates, and protocol adoption curves for cachexia and inherited metabolic disease nutrition support.
Inputs from hospital procurement databases and regulatory filing repositories were available through the study window; gaps in real-time home care adherence monitoring data introduce uncertainty bands around patient lifetime value estimates. Forecasts reflect documented assumptions regarding reimbursement classification stability and EMA F-Gas Regulation implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Obesity Management Market