
 Global Enteral Feeding Formulas Market | 2026-2036
Global Enteral Feeding Formulas Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enteral Feeding Formulas Market Foresight
Home healthcare providers is collapsing the traditional hospital-centric procurement model for enteral feeding formulas as payers push cost-efficient post-discharge nutrition protocols. Abbott Laboratories leverages its chronic disease-specific portfolio to anchor relationships with managed care networks across North America. Nestlé Health Science competes through direct-to-patient subscription platforms that bypass conventional distributor markups. Fresenius Kabi sustains its European installed base with integrated pump-and-formula bundling contracts that lock in long-term supply agreements.
Enteral feeding formulas are liquid or semi-liquid nutritional preparations delivered through gastrointestinal tubes or oral routes, typically containing proteins, carbohydrates, lipids, vitamins, and minerals in osmolalities ranging from 300 to 900 mOsm/kg to ensure GI tolerance. These formulations serve patients with functional gastrointestinal tracts who cannot meet nutritional requirements through voluntary oral intake alone, spanning acute surgical recovery to lifelong neurodegenerative conditions. Disease-specific formulas for oncology and diabetes command premium positioning due to clinical outcome differentiation and reimbursement advantages. Polymeric standard formulations occupy the volume base across hospital formularies where cost-per-calorie dominates procurement decisions. Home healthcare delivery through gastrostomy and jejunostomy tubes represents the fastest-expanding channel as discharge planning prioritizes continuity of care.
FDA medical food regulations, EU MDR device-formula combination requirements, and Japan's PMDA reimbursement coding for home enteral nutrition collectively elevate compliance costs while restricting market access for non-specialized manufacturers. The FDA distinguishes medical foods from dietary supplements through intended-use documentation, forcing reformulation investments for products crossing category boundaries. Stakeholders must monitor evolving homecare reimbursement thresholds and tube-feeding device interoperability standards as integrated delivery ecosystems consolidate purchasing influence.
Market Dynamics
Post-acute care decentralization is collapsing the traditional hospital-centric procurement model for enteral feeding formulas as payers mandate cost-efficient discharge nutrition protocols and home healthcare infrastructure expands.
Growth Catalysts
- Aging demographics in Japan, Germany, and the United States:Chronic disease prevalence and extended longevity are expanding the addressable patient base requiring long-term enteral nutrition support through gastrostomy and jejunostomy delivery.
- EU MDR device-formula combination requirements:Regulatory harmonization is accelerating integrated pump-and-formula system adoption by mandating interoperability standards that favor bundled supply contracts.
- Home healthcare channel expansion:Discharge planning protocols now prioritize continuity of care outside institutional settings, redirecting volume toward direct-to-patient delivery models and specialized nutrition services.
Market Restraints
- Protein and lipid input cost volatility:Specialized amino acid sources and structured lipid emulsions face supply concentration among pharmaceutical-grade ingredient manufacturers, compressing formulation margins.
- FDA medical food labeling documentation:The intended-use distinction between medical foods and dietary supplements forces reformulation investments and extends product development cycles for category-crossing formulations.
- Ready-to-drink oral nutrition substitutes:Palatable high-protein beverages for ambulatory patients reduce tube-feeding necessity in transitional care settings, limiting formula volume growth.
Strategic Opportunities
- Underpenetrated home enteral nutrition in India:Rising surgical volumes and expanding health insurance coverage create whitespace for disease-specific formula portfolios tailored to diabetic and oncology patient segments.
- Japan PMDA reimbursement coding evolution:Updated home enteral nutrition reimbursement thresholds incentivize premium disease-specific formulations with demonstrated clinical outcome differentiation.
- Smart pump connectivity convergence:Integration of enteral feeding pumps with electronic health record systems and remote monitoring platforms enables subscription-based formula delivery with adherence tracking.
Industry Challenges
- Clinical nutrition specialist workforce scarcity:Registered dietitians with enteral feeding certification remain concentrated in tertiary hospital systems, creating bottlenecked patient education capacity for home initiation.
- ISO 13485 and EU MDR dual certification timelines:Device-formula combination products face extended conformity assessment periods, delaying market entry for integrated delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enteral Feeding Formulas Market |
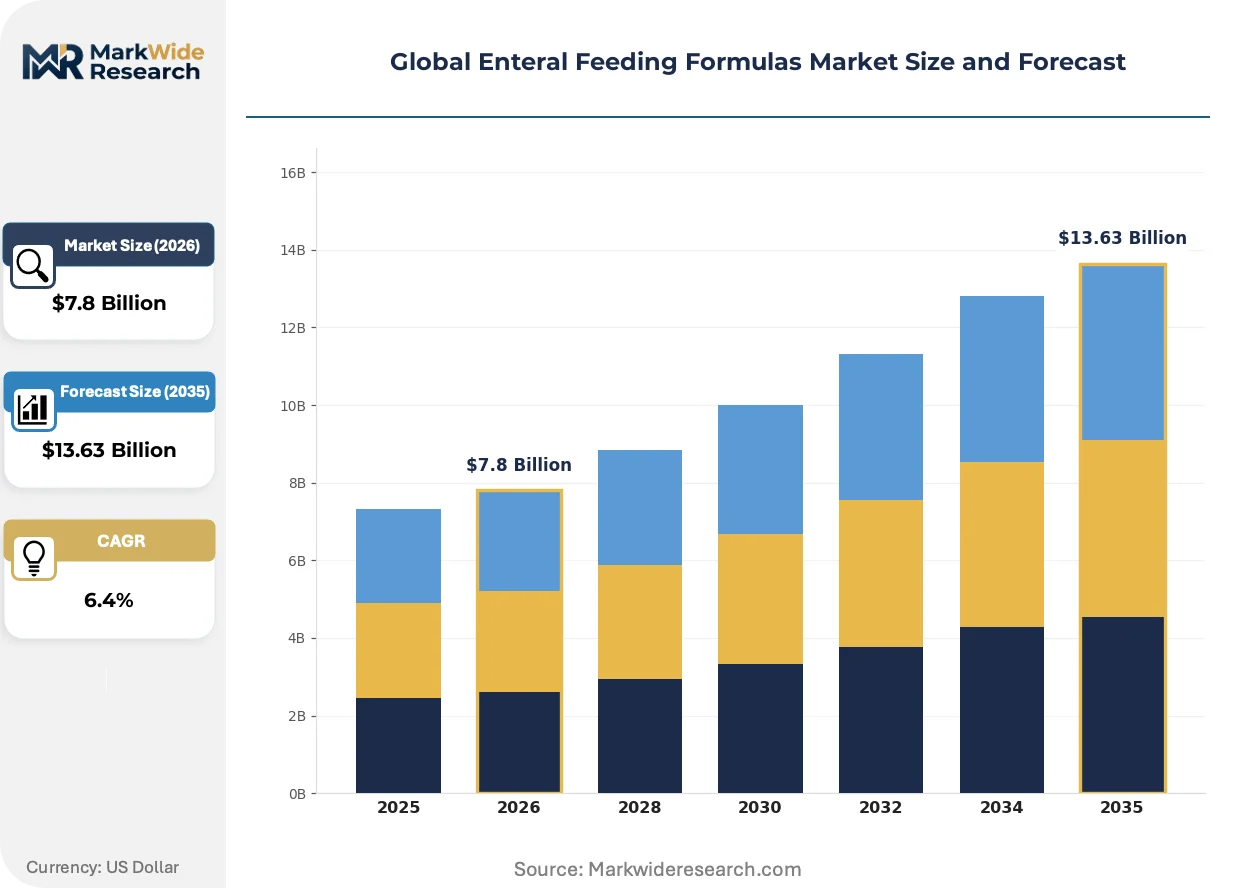
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formula Type: Polymeric, Oligomeric, Modular, Disease-Specific, Elemental Application: Neurological Disorders, Surgical Recovery, Oncology Support, Pediatric Nutrition, Geriatric Care End User: Hospitals, Long-Term Care Facilities, Rehabilitation Centers, Home Healthcare Providers Delivery Method: Nasogastric Tube, Gastrostomy Tube, Jejunostomy Tube, Oral Intake |
| Companies Covered | Abbott Laboratories, Nestlé Health Science, Danone, Fresenius Kabi, B. Braun Melsungen, Reckitt Benckiser Group, Meiji Holdings, Otsuka Pharmaceutical, Global Health Product, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enteral Feeding Formulas Market Shifts & Advancements
Formula development is splitting along functional lines as manufacturers balance cost-per-calorie hospital procurement demands against premium disease-specific positioning for reimbursed home care segments.
Peptide-based semi-elemental formulations are bifurcating the standard polymeric market by addressing malabsorption in critical care and oncology patients with compromised gastrointestinal function. Intensive care units and oncology wards in the United States and Germany are adopting these hydrolyzed protein systems despite 40-60% price premiums over intact protein alternatives. This technology is bifurcating procurement patterns as hospitals maintain polymeric formularies for routine surgical recovery while carving out premium budgets for specialized metabolic support.
EU MDR Article 117 device-formula combination requirements are forcing enteral feeding manufacturers to submit technical documentation for integrated delivery systems or secure notified body opinions on legacy products. The regulation compresses time-to-market for new pump-formula bundles while elevating compliance costs for smaller manufacturers lacking in-house regulatory affairs capacity. Oncology and critical care segments face the steepest adaptation curves as these categories disproportionately rely on precision delivery devices with programmable flow rates.
Direct-to-patient subscription platforms are disintermediating traditional distributor networks by capturing recurring revenue streams and patient adherence data previously inaccessible to manufacturers. Home healthcare providers and individual caregivers in Japan and Germany are migrating toward auto-replenishment models that bundle formula delivery with remote monitoring services. This channel evolution concentrates purchasing influence among platform operators capable of integrating insurance pre-authorization workflows with logistics fulfillment.
Global Enteral Feeding Formulas Market Segmentation
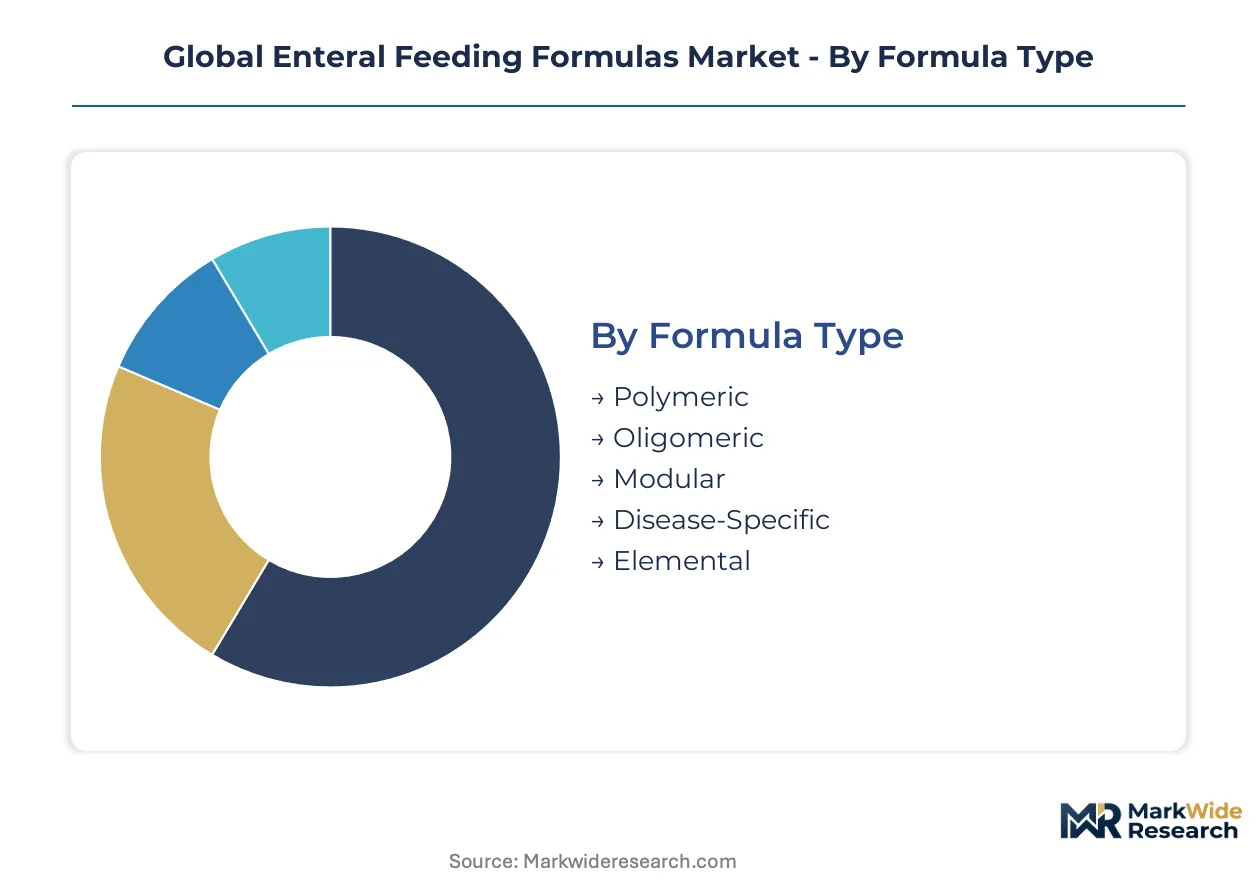
Enteral feeding formula manufacturers navigate divergent procurement logics across institutional and home settings, with reimbursement pathways and clinical outcomes driving portfolio prioritization. Segmentation reveals where premium positioning commands pricing power versus where cost-per-calorie optimization dominates purchasing decisions.
Formula Type:
Substitution pressure from oral nutrition supplements and parenteral alternatives varies sharply across formula complexity tiers, with intact protein systems facing the most acute ready-to-drink competition.
- Polymeric:Standard intact protein formulations with macronutrients in polymeric form require normal digestive function and dominate hospital formularies. Procurement in the United States and Germany concentrates on cost-per-calorie metrics as surgical recovery volumes sustain bulk purchasing agreements.
- Disease-Specific:Oncology and diabetic variants incorporate condition-modified macronutrient profiles with immune-modulating additives. Japan's PMDA reimbursement coding for home enteral nutrition incentivizes these premium formulations where clinical outcome documentation supports higher reimbursement tiers.
- Oligomeric:Partially hydrolyzed protein systems bridge standard and elemental categories for compromised absorption.
- Modular:Single-nutrient supplements enable customized caloric and protein augmentation of base formulas.
- Elemental:Predigested free amino acid formulations serve severe malabsorption cases in critical care settings.
Polymeric formulations anchor the volume base while disease-specific variants gain share at the steepest rate.
Application:
Clinical setting determines formula selection complexity, with acute surgical recovery favoring standardized protocols and chronic neurological conditions requiring individualized long-term regimens.
- Neurological Disorders:Amyotrophic lateral sclerosis, Parkinson's disease, and stroke-related dysphagia create sustained demand for gastrostomy-delivered nutrition. Home healthcare infrastructure expansion in Germany and Japan supports patient discharge with long-term tube-feeding protocols.
- Oncology Support:Cancer cachexia and treatment-related mucositis drive demand for peptide-based semi-elemental systems with immune-enhancing substrates. Intensive care units in the United States adopt these despite substantial price premiums over standard alternatives.
- Surgical Recovery:Post-operative ileus and temporary enteral access needs favor cost-optimized polymeric selection.
- Pediatric Nutrition:Growth-calibrated micronutrient profiles address developmental requirements in congenital anomalies.
- Geriatric Care:Sarcopenia-focused high-protein formulations target aging-related muscle preservation.
Surgical recovery generates the highest patient throughput while oncology support commands the strongest pricing premiums.
End User:
Channel economics reshape competitive dynamics as institutional procurement consolidates through group purchasing organizations and home delivery fragments toward direct-to-patient platforms.
- Home Healthcare Providers:Discharge planning protocols in the United States now mandate nutrition continuity outside hospitals, driving auto-replenishment subscription models. Remote monitoring integration with electronic health records enables adherence tracking and reimbursement documentation.
- Hospitals:Acute care formularies prioritize inventory efficiency and standardized protocols across medical and surgical units. EU MDR device-formula combination requirements are accelerating integrated pump-and-formula bundling contracts.
- Long-Term Care Facilities:Skilled nursing regulations govern nutritional assessment and intervention timelines.
- Rehabilitation Centers:Transitional care settings bridge acute and home environments with mixed delivery modalities.
Hospitals retain the largest absolute volume while home healthcare providers expand most quickly.
Delivery Method:
Tube placement durability and aspiration risk profile determine method selection, with long-term accessibility favoring surgical gastrostomy over transnasal alternatives.
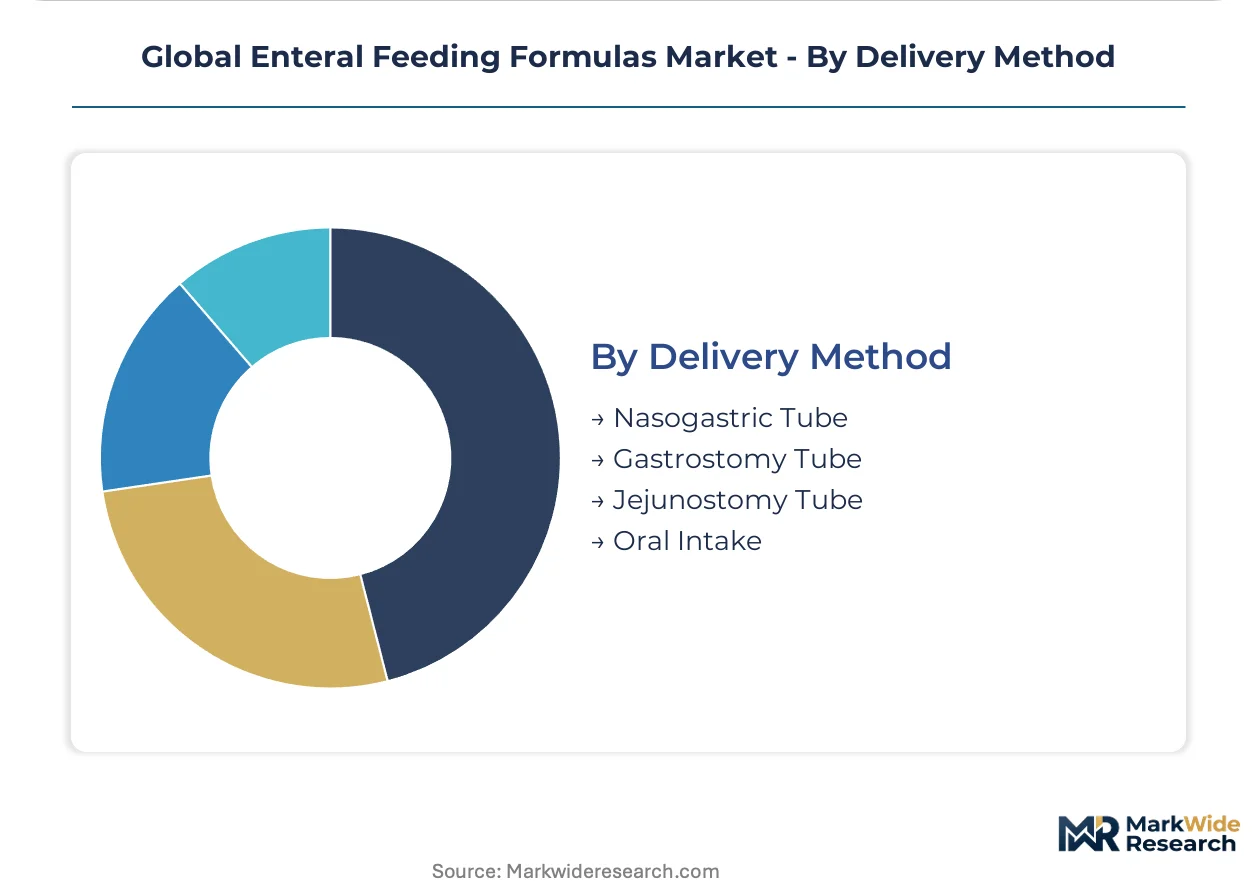
- Gastrostomy Tube:Percutaneous endoscopic gastrostomy provides durable enteral access for patients requiring nutrition support exceeding several weeks. Japan's aging demographic and extended longevity patterns sustain percutaneous placement volumes for neurodegenerative conditions.
- Nasogastric Tube:Transnasal placement dominates acute surgical recovery and short-term bridge feeding in hospital settings. United States tertiary centers maintain rapid-response nursing protocols for bedside insertion and verification.
- Jejunostomy Tube:Post-pyloric delivery bypasses gastric dysfunction and aspiration risk in critical care populations.
- Oral Intake:Palatable thickened formulations serve transitional and supplementary nutrition in ambulatory patients.
Gastrostomy tube delivery anchors the chronic care volume base while jejunostomy applications climb the fastest as critical care protocols emphasize aspiration prevention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement managers and home healthcare providers concentrate purchasing power in aging economies with established reimbursement infrastructure for long-term enteral nutrition. Japan, Germany, and the United States absorb the dominant share of disease-specific formula volumes.
United States
Medicare Advantage plans and managed care networks now mandate post-discharge nutrition protocols, accelerating home enteral nutrition adoption. FDA medical food labeling requirements force reformulation investments for products crossing category boundaries. The Cleveland Clinic and Mayo Clinic anchor institutional procurement concentration in the Midwest, driving standardized polymeric formularies for surgical recovery.
Germany
Statutory health insurance funds expanded homecare reimbursement for percutaneous endoscopic gastrostomy patients with neurodegenerative conditions. EU MDR device-formula combination requirements accelerate integrated pump-and-formula bundling contracts. The Rhine-Ruhr metropolitan region concentrates distributor networks serving long-term care facilities across North Rhine-Westphalia.
Japan
PMDA reimbursement coding evolution incentivizes premium disease-specific formulations with demonstrated clinical outcome differentiation. METI supports smart pump connectivity convergence through digital health infrastructure grants. The Kanto region surrounding Tokyo anchors percutaneous placement volumes for amyotrophic lateral sclerosis and Parkinson's disease patient cohorts.
India
Rising surgical volumes and expanding health insurance coverage create whitespace for disease-specific formula portfolios tailored to diabetic and oncology segments. CDSCO regulatory pathways for medical foods remain underdeveloped, slowing multinational market entry. Mumbai and Delhi-NCR concentrate private hospital chains piloting post-operative enteral nutrition protocols.
United Kingdom
NHS England's discharge planning mandates prioritize nutrition continuity outside acute settings, redirecting volume toward community-based delivery. MHRA post-Brexit regulatory divergence from EU MDR creates compliance complexity for device-formula combinations. The Greater Manchester health system pilots auto-replenishment subscription models with remote monitoring integration.
Global Enteral Feeding Formulas Market Competitive Landscape
Player mix skews toward diversified nutrition conglomerates with chronic disease-specific portfolios anchoring managed care relationships. Three to four multinational healthcare groups capture the majority of reimbursed homecare volume. Strategic archetypes include integrated device-formula bundlers, direct-to-patient platform operators, and regional pharmacy distributors. Competitive moves concentrate on securing long-term supply agreements with group purchasing organizations and acquiring home healthcare service capabilities.
Among diversified healthcare conglomerates, Abbott Laboratories and Nestlé Health Science occupy positions exemplifying contrasting channel strategies. Abbott anchors institutional procurement through North American managed care network relationships. Nestlé Health Science represents the direct-to-patient platform archetype with subscription-based models bypassing conventional distribution. Fresenius Kabi exemplifies the integrated bundling approach with European pump-and-formula combination contracts.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé Health Science |
| Danone |
| Fresenius Kabi |
| B. Braun Melsungen |
| Reckitt Benckiser Group |
| Meiji Holdings |
| Otsuka Pharmaceutical |
| Global Health Product |
| Others |
Supply & Pricing Matrix
Peptide-based semi-elemental formulations replacing standard polymeric systems in critical care are redrawing procurement geography toward Germany and United States manufacturing clusters while compressing margins on intact protein alternatives through reimbursement tier compression.
Pricing Analysis
Cost-plus contracts with pharmaceutical-grade whey protein isolate indexation dominate hospital procurement in the United States and Germany. Three-tier pricing structure across premium disease-specific, standard polymeric, and economy modular levels separates oncology formulations from surgical recovery volumes. Cost compression in the polymeric tier is intensifying because group purchasing organizations aggregate surgical volumes into single-source agreements. Long-term care facilities exhibit the highest price sensitivity, while intensive care units demonstrate lowest sensitivity due to outcome-based formulary carve-outs.
Supply Chain Analysis
Just-in-time inventory strategies prevail among United States hospital systems, while Japanese distributors maintain strategic stockpiles against PMDA reimbursement coding volatility. Pharmaceutical-grade amino acid production concentrates in Switzerland, Germany, and Japan. Formulation draws from structured lipid emulsions, micronutrient premixes, and hydrolyzed protein isolates. Single-source vulnerability pervades specialized peptide suppliers serving oncology segments. Distribution runs through regional pharmacy wholesalers with cold-chain capabilities in North America and direct-to-patient platforms in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as home healthcare infrastructure penetrates post-acute settings previously captive to hospital discharge planning.
For Market Incumbents: Shield formulary positioning through backward integration into pharmaceutical-grade protein isolate production, particularly in Switzerland and Germany manufacturing corridors. Secure ISO 13485 certification for device-formula combinations ahead of EU MDR enforcement waves. Prioritize GPO contract renewal timing to preempt emerging platform competitors.
For New Entrants and Emerging Players: Remote patient monitoring integration represents the most under-served service layer where Abbott and Fresenius Kabi lack native digital health capabilities. Target India's private hospital chains in Mumbai and Delhi-NCR with diabetic-specific formulations ahead of CDSCO medical food pathway formalization. Deploy direct-to-patient subscription models with insurance pre-authorization automation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed home healthcare service platforms seeking formula manufacturing integration to complete vertical delivery stacks. Five-to-ten-year viability hinges on reimbursement durability for disease-specific tiers. Watch Japan PMDA coding updates as inflection signal for premium formulation adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Device-Formula Bundling | Accelerates integrated pump-and-formula contracts through notified body conformity assessment. |
| Direct-to-Patient Platform Launch | Captures recurring revenue and adherence data previously held by distributor networks. |
| Peptide-Based Formulation Expansion | Addresses malabsorption in oncology and critical care with 40-60% price premiums. |
| Smart Pump Connectivity Integration | Enables EHR-linked remote monitoring with subscription-based formula replenishment. |
| India Disease-Specific Portfolio Entry | Exploits whitespace in diabetic and oncology segments amid expanding health insurance. |
Research Methodology
The analysis maps polymeric, disease-specific, oligomeric, modular, and elemental formulation tiers, each validated through hospital procurement managers, home healthcare service directors, enteral feeding pump biomedical engineers, and GPO contracts specialists. Primary interviews with registered dietitians and regulatory affairs leads at FDA-registered medical food manufacturers combined with secondary validation through FDA medical food labeling guidance documents, EU MDR Article 117 technical documentation, Japan PMDA reimbursement coding circulars, and hospital formulary databases. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored segmentation outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include formula complexity tier, clinical application setting, delivery method durability, and end-user channel type. CAGRs derived from patient population growth rates, procedure volume trajectories, and reimbursement pathway evolution. Industry-specific inputs encompass gastrostomy placement volumes by neurological indication and smart pump connectivity adoption curves.
Underlying assumptions cover reimbursement stability for home enteral nutrition, regulatory harmonization timelines, and protein input cost normalization, with deviation risk concentrated in FDA medical food category enforcement and EU MDR notified body capacity constraints. Revision becomes warranted when PMDA reimbursement tier thresholds or Medicare Advantage nutrition protocol mandates cross material adoption inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Parenteral Nutrition Market