
 Nutrition Apps Market | 2026-2036
Nutrition Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Nutrition Apps Market Insights
The split between premium subscription tiers and basic freemium offerings is rebalancing as users demand AI-powered personalization and clinical-grade nutrient analysis. MyFitnessPal leverages its massive food database to sustain engagement across diverse dietary protocols. Noom differentiates through psychology-backed coaching workflows that anchor higher retention rates. Cronometer specializes in micronutrient precision, occupying a technical niche that commands subscription loyalty among advanced users.
Nutrition apps are software platforms that log dietary intake, analyze macronutrient and micronutrient composition against personalized targets, and sync biometric data from wearables to deliver actionable feedback. These systems rely on standardized food databases, optical barcode recognition, and API integrations with glucose monitors or continuous heart-rate sensors to serve both consumer wellness and clinical adjacency purposes. Calorie tracking remains the most mature application type, while fitness integration represents the fastest-expanding segment as users demand unified health dashboards. The subscription model landscape tilts toward annual commitments, where upfront payment improves lifetime value metrics and reduces churn relative to monthly billing cycles.
The FDA regulates apps making disease-related claims as medical devices under its digital health enforcement discretion policy, while GDPR and HIPAA frameworks govern cross-border health data flows and employer-sponsored wellness deployments. These compliance requirements raise engineering costs but also create defensible moats against undercapitalized entrants. Stakeholders must monitor how FDA classification shifts and state-level biometric privacy laws in Illinois, Texas, and Washington reshape permissible data collection and monetization pathways.
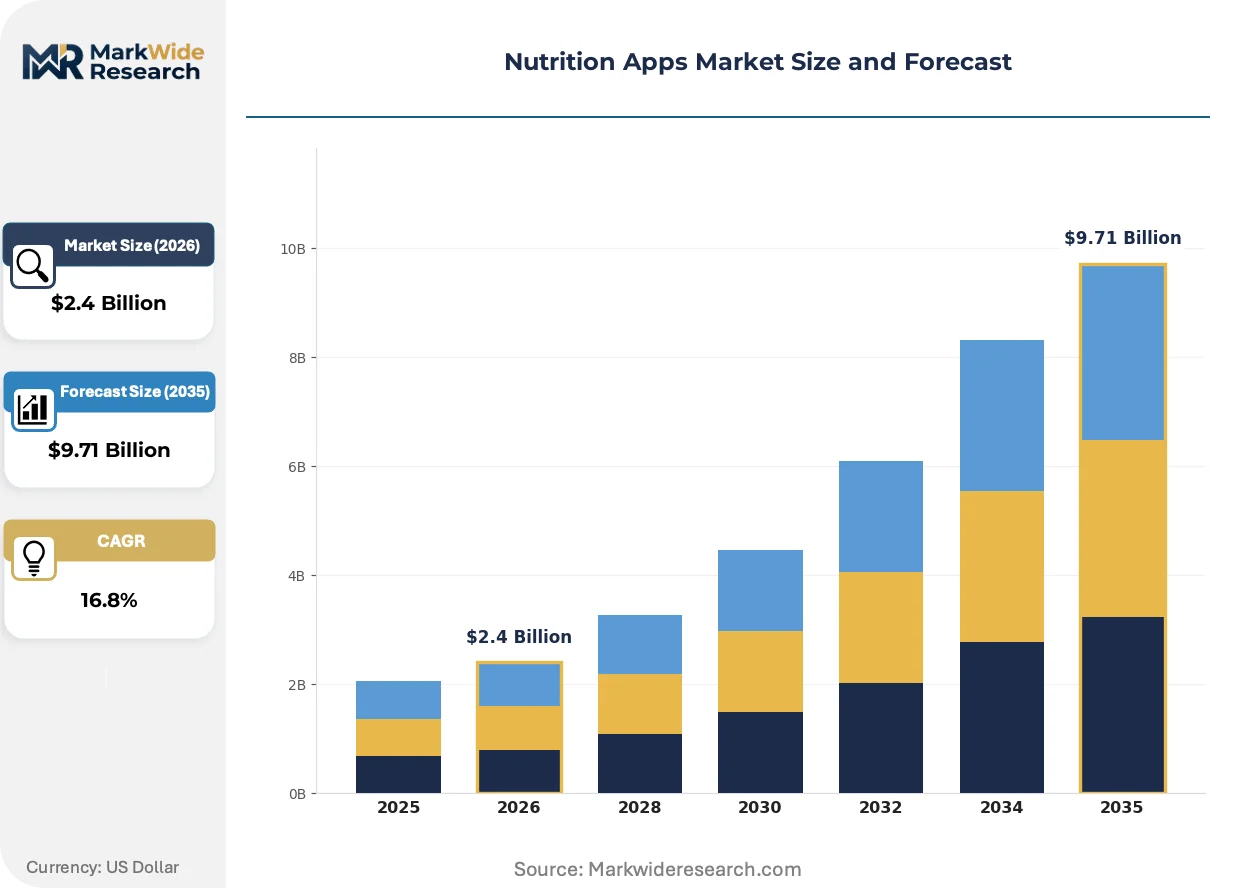
Market Dynamics
The convergence of FDA digital health enforcement discretion with GDPR biometric data rules is forcing nutrition app developers to rebuild data architectures around compliance-first design rather than retrofitting privacy controls post-launch.
Growth Catalysts
- Corporate wellness mandates:Large employers in the United States and Germany now subsidize nutrition tracking as preventive health benefits, expanding the addressable user base beyond individual consumers.
- Continuous glucose monitor APIs:Dexcom and Abbott Libre integrations enable real-time glycemic feedback loops that transform calorie logging into metabolic management tools.
- Japan's METI Healthy Japan 21 initiative:Government-backed digital health adoption targets accelerate smartphone-based dietary intervention deployment across aging prefectures.
Market Restraints
- Food database licensing costs:Commercial access to standardized nutritional datasets from USDA and EFSA imposes recurring fees that compress margins for mid-tier developers.
- Sensor hardware concentration:Wearable biometric data flows depend disproportionately on Apple Watch and Garmin device ecosystems, creating platform dependency risk.
- HIPAA business associate agreements:Employer-sponsored deployments require contractual overhead that extends sales cycles and inflates legal expenditure for vendors.
Strategic Opportunities
- India's NDHM integration pathway:The National Digital Health Mission's open API standards create infrastructure for localized nutrition apps to connect with government health records.
- AI-photography food recognition:Convolutional neural networks trained on regional cuisine databases reduce manual logging friction in underpenetrated Asian markets.
- Pharmacy channel expansion:CVS and Walgreens in the United States now allocate shelf space to app-enabled nutrition programs, creating physical-digital distribution hybrids.
Industry Challenges
- Registered dietitian credentialing:Scaling coaching services requires navigating state-level licensure variance across Illinois, Texas, and California that complicates telehealth staffing models.
- ISO 27001 certification timelines:Enterprise sales cycles stall while vendors complete information security audits required by hospital system procurement departments.
- Legacy EHR integration:Epic and Cerner interoperability protocols demand specialized engineering resources that smaller developers struggle to allocate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutrition Apps Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $9.71 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Calorie Tracking, Meal Planning, Recipe Sharing, Fitness Integration End User: Fitness Enthusiasts, Dietitians, General Consumers, Health Coaches Subscription Model: Freemium, Monthly Subscription, Annual Subscription, One-Time Purchase Feature Set: Barcode Scanning, Nutrient Analysis, Progress Tracking, Community Support |
| Companies Covered | BodyFast, FatSecret, MyFitnessPal, MacroFactor, Healthify, Noom, Yazio, Lifesum, Cronometer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutrition Apps Market Trends and Innovations
Artificial intelligence is collapsing the cost curve for personalized dietary recommendations while regulatory fragmentation forces architectural decisions that prioritize data sovereignty over feature velocity.
Edge-deployed machine learning models for food image recognition are decentralizing computational workloads from cloud servers to smartphone processors. Users in bandwidth-constrained regions of Brazil and Indonesia gain full functionality without persistent connectivity. This architecture shift reduces API call costs for developers while eliminating latency barriers to real-time meal logging.
GDPR Article 9 special category processing requirements and the EU AI Act's risk classification for health-related algorithms are mandating algorithmic impact assessments before deployment. European nutrition app publishers now maintain audit trails for recommendation logic that were previously treated as proprietary machine learning black boxes. The compliance burden falls heaviest on freemium models dependent on ad-supported data monetization.
Employer procurement departments are unbundling nutrition coaching from comprehensive wellness platforms and contracting directly with specialized vendors. This disintermediation of legacy benefits administrators concentrates purchasing power among Fortune 500 benefits teams while fragmenting the vendor landscape into point-solution specialists. The pattern is most pronounced in the United States, where self-insured employers seek direct accountability for health outcome metrics.
Nutrition Apps Market Segmentation
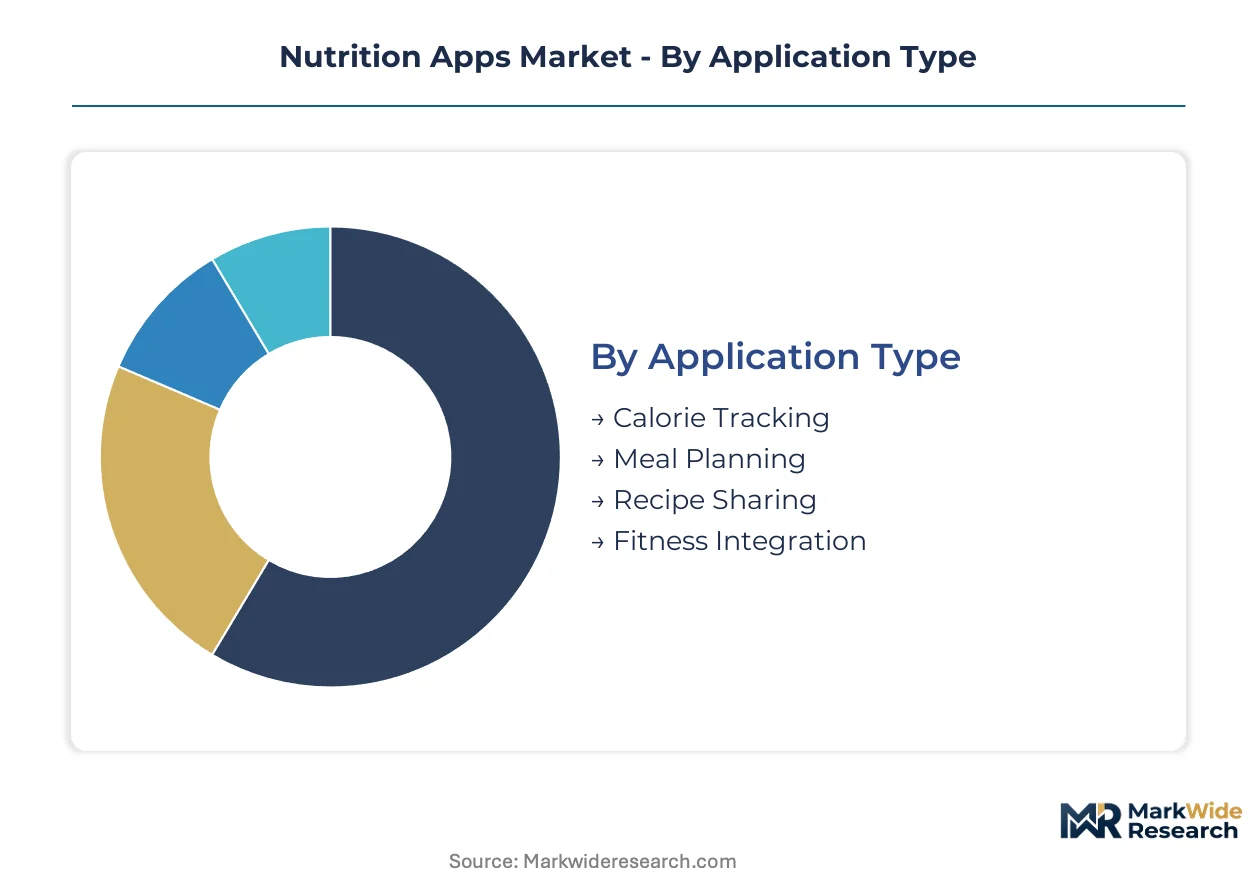
Nutrition apps serve divergent user workflows ranging from casual weight management to clinical-grade metabolic monitoring. Segmentation reveals how feature depth, pricing architecture, and professional credentialing requirements partition the addressable market into distinct commercial battlegrounds.
Application Type:
Functional architecture determines data capture methods and engagement frequency across user cohorts.
- Calorie Tracking:Core functionality centers on macronutrient logging against personalized targets using standardized food databases. Demand concentrates among general consumers in the United States and Germany where smartphone penetration overlaps with weight management program enrollment. Manual entry friction limits retention among users seeking passive monitoring solutions.
- Fitness Integration:Unified dashboards synchronize dietary intake with biometric streams from Apple Watch and Garmin ecosystems. Corporate wellness deployments in Japan's aging prefectures drive procurement volume through METI Healthy Japan 21 initiative subsidies. API maintenance costs and hardware dependency create margin pressure for standalone developers.
- Meal Planning:Automated grocery list generation and recipe scaling reduce decision fatigue for time-constrained households.
- Recipe Sharing:Social content networks leverage user-generated photography to build engagement moats against utility-focused competitors.
Mature deployment sits with Calorie Tracking. Newer deployment is concentrated in Fitness Integration.
End User:
Credential requirements and reimbursement pathways segment pricing power across professional and consumer tiers.
- General Consumers:Mass-market users prioritize low-friction onboarding and gamified adherence mechanics over clinical precision. Volume concentrates in the United States where employer-sponsored wellness subsidies reduce effective subscription costs. Churn rates exceed professional segments due to goal attainment attrition.
- Dietitians:Licensed practitioners require HIPAA-compliant data export and client management dashboards for telehealth reimbursement. State-level licensure variance across Illinois, Texas, and California complicates platform scaling for coaching marketplaces. Enterprise contracts carry extended sales cycles but improve lifetime value metrics.
- Fitness Enthusiasts:Performance-oriented users demand micronutrient precision and periodization tools aligned with training cycles.
- Health Coaches:Non-credentialed advisors operate in regulatory gray zones that limit clinical claim permissibility under FDA enforcement discretion policies.
Revenue concentration favors Dietitians. User volume leadership belongs to General Consumers.
Subscription Model:
Payment periodicity structures cash flow predictability and customer acquisition cost recovery timelines.
- Annual Subscription:Upfront commitment improves lifetime value calculations and reduces monthly churn volatility for finance teams. Corporate wellness procurement in Germany mandates annual billing alignment with benefits enrollment cycles. Discount depth compresses effective revenue per user versus monthly equivalents.
- Freemium:Ad-supported tiers acquire users for premium conversion funnels while exposing developers to GDPR Article 9 special category processing constraints. European publishers face algorithmic audit requirements under EU AI Act health algorithm classifications. Data monetization pathways narrow under biometric privacy laws in Illinois, Texas, and Washington.
- Monthly Subscription:Lower barrier entry supports trial behavior but elevates cancellation flexibility.
- One-Time Purchase:Deprecated model survives only in offline database products serving bandwidth-constrained regions.
Enterprise procurement demands Annual Subscription. Freemium dominates new user acquisition funnels.
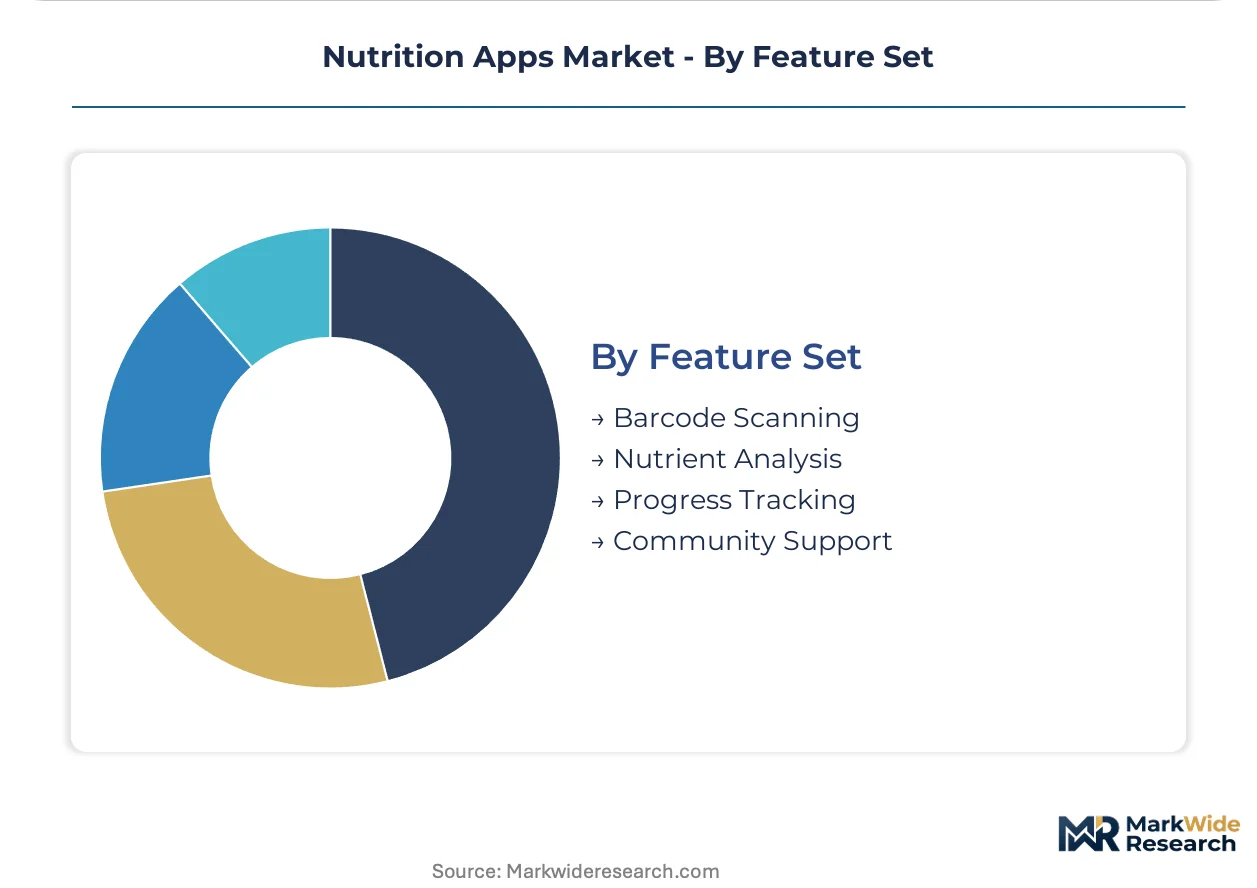
Feature Set:
Data input modalities and analytical depth differentiate technical positioning across price tiers.
- Nutrient Analysis:Micronutrient precision targeting vitamins and minerals requires curated database licensing from USDA and EFSA sources. Advanced users in Japan and Germany sustain subscription loyalty for clinical-grade tracking unavailable in mass-market alternatives. Recurring dataset fees compress margins for mid-tier developers.
- Barcode Scanning:Optical recognition streamlines packaged food logging through smartphone camera integration. Deployment concentrates in the United States where standardized nutrition labeling enables reliable database matching. Regional cuisine variance in Asian markets degrades recognition accuracy without localized training data.
- Progress Tracking:Visualization dashboards aggregate biometric trends from continuous glucose monitors and wearable sensors.
- Community Support:Peer accountability networks reduce coaching labor costs but expose platforms to content moderation liability.
Technical differentiation centers on Nutrient Analysis. Mass-market accessibility depends on Barcode Scanning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors nutrition app development density, hosting engineering clusters that serve employer-sponsored wellness contracts across the United States. Smartphone penetration rates and health-conscious consumer bases concentrate demand in specific metropolitan corridors where digital health infrastructure overlaps with corporate benefits administration.
United States
Employer wellness subsidies and FDA digital health enforcement discretion create dual demand channels for clinical-adjacent and consumer-grade platforms. HIPAA business associate agreements govern enterprise deployments, extending vendor sales cycles. Silicon Valley and Boston clusters concentrate venture-backed developers targeting Fortune 500 benefits procurement.
Germany
Corporate wellness mandates and GDPR Article 9 special category processing requirements shape product architecture decisions. EFSA dataset licensing fees compress margins for mid-tier entrants. Berlin and Munich host engineering teams building compliance-first platforms for annual subscription billing aligned with benefits enrollment cycles.
Japan
METI Healthy Japan 21 initiative subsidies accelerate smartphone-based dietary intervention deployment across aging prefectures. Continuous glucose monitor API integrations transform calorie logging into metabolic management tools. Tokyo and Osaka metropolitan areas concentrate user volume for fitness-integrated nutrition dashboards.
India
National Digital Health Mission open API standards create infrastructure for localized apps connecting with government health records. AI-photography food recognition reduces manual logging friction for regional cuisine diversity. Bengaluru and Hyderabad clusters drive engineering capacity for edge-deployed machine learning models.
United Kingdom
NHS digital health procurement frameworks and GDPR biometric data rules mandate algorithmic impact assessments before deployment. London fintech corridors intersect with health tech venture formation. Manchester and Edinburgh sub-regions host specialized developers targeting dietitian credentialing workflows for telehealth reimbursement.
Nutrition Apps Market Competitive Landscape
Premium-margin players sit above commodity-margin players across data precision and coaching credentialing dimensions. The vendor base separates into three tiers: mass-market freemium platforms, clinical-grade micronutrient specialists, and psychology-backed coaching marketplaces. Strategic archetypes include database-scale incumbents, API-integrated metabolic management tools, and employer-facing wellness vendors. Dominant competitive moves encompass pharmacy channel expansion partnerships and AI-photography feature deployment for Asian market penetration.
Within the psychology-backed coaching tier, Noom occupies a position exemplifying retention-focused workflow design. MyFitnessPal and Cronometer represent contrasting archetypes—database-scale engagement platforms versus micronutrient precision specialists commanding subscription loyalty among advanced users. These three entities anchor the competitive spectrum from mass-market accessibility to clinical-grade analytical depth.
| Leading Market Players |
|---|
| BodyFast |
| FatSecret |
| MyFitnessPal |
| MacroFactor |
| Healthify |
| Noom |
| Yazio |
| Lifesum |
| Cronometer |
| Others |
Pricing and Supply Chain Analysis
Fortune 500 benefits procurement teams concentrate purchasing power through annual subscription mandates that compress effective revenue per user while extending vendor cash conversion cycles. This buyer archetype dominance forces developers to front-load engineering investment for HIPAA-compliant architectures before recovering costs through multi-year enterprise contracts.
Pricing Analysis
Outcome-based pricing anchors enterprise contracts where employers tie subscription fees to employee engagement metrics and health outcome improvements. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade micronutrient analysis from basic calorie logging and ad-supported freemium tiers. Pricing pressure stems from food database licensing fees that compress margins for mid-tier developers lacking proprietary dataset scale. General consumers exhibit highest price sensitivity, while dietitian-facing platforms with HIPAA-compliant data export command premium tolerance.
Supply Chain Analysis
Direct-to-employer channels handle hyperscale corporate wellness demand, bypassing legacy benefits administrators that previously aggregated purchasing power. Engineering talent concentrates in the United States, Germany, and India, with San Francisco, Berlin, and Bengaluru hosting specialized development clusters. Raw material dependencies include USDA and EFSA nutritional datasets, continuous glucose monitor APIs from Dexcom and Abbott, and cloud infrastructure from AWS and Google Cloud. Single-source vulnerability runs through Apple Watch and Garmin wearable ecosystems that dominate biometric data flows. Distribution runs through app store marketplaces, pharmacy retail partnerships, and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over proprietary food databases and coaching credentialing infrastructure determines margin sustainability. Players are pursuing downstream integration into employer benefits administration to capture recurring revenue streams.
For Market Incumbents: Cement database-scale advantages through exclusive licensing agreements with USDA and EFSA dataset providers that raise rival input costs. Deepen coaching marketplace moats by securing multi-state dietitian licensure coverage across Illinois, Texas, and California before regulatory fragmentation hardens. These moves defend against API-integrated metabolic management tools that threaten to disintermediate standalone nutrition platforms.
For New Entrants and Emerging Players: App store optimization and pharmacy retail partnerships offer lower customer acquisition cost routes than competing for Fortune 500 RFP cycles. India's NDHM integration pathway presents the most penetrable geography, with government API standards reducing infrastructure build requirements. Target AI-photography food recognition for regional Asian cuisines where manual logging friction remains highest and incumbent database coverage thins.
For Investors and Strategic Acquirers: The window for entry favors clinical-adjacent platforms with HIPAA-compliant architectures and existing hospital system procurement relationships. Long-term viability hinges on navigating FDA digital health classification shifts that will separate regulated medical devices from consumer wellness tools. Watch for state-level biometric privacy law expansion beyond Illinois, Texas, and Washington as the signal for compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CGM API connectivity with Dexcom and Abbott Libre transforms calorie logging into metabolic management. |
| Geographic Expansion | NDHM-aligned localization captures India's government-backed digital health infrastructure subsidies. |
| Regulatory Certification | ISO 27001 completion unlocks hospital system procurement channels stalled by security audit requirements. |
| Strategic Partnership | CVS and Walgreens shelf space allocation creates physical-digital distribution hybrids for employer programs. |
| Acquisition of Specialist Firm | Regional cuisine database specialists reduce AI-photography training costs for Asian market penetration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced with primary interviews across app developers, corporate benefits directors, and hospital procurement managers. FDA digital health guidance documents, GDPR implementation reports, and METI Healthy Japan 21 initiative filings provided regulatory boundary conditions. Bottom-up triangulation against app store download estimates and subscription revenue disclosures validated top-down market sizing from venture capital investment databases.
Reconciliation of user adoption curves with employer procurement cycle data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include application type, end user credential requirements, subscription periodicity, and feature set depth. CAGRs were derived from fitted growth curves against historical adoption benchmarks in adjacent digital health categories. Continuous glucose monitor penetration rates and corporate wellness subsidy expansion served as nutrition-specific demand drivers.
The model holds under stable FDA enforcement discretion and steady employer wellness investment; deviation in biometric privacy law expansion or CGM hardware pricing would shift trajectory. Forecasts reflect documented assumptions about smartphone penetration saturation and health data interoperability standards. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Weight Loss Market