
 Europe Cardiac Holter Monitor Market | 2026-2036
Europe Cardiac Holter Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cardiac Holter Monitor Market Intelligence
Germany is rewriting the competitive map for cardiac Holter manufacturing in Europe. GE Healthcare leverages its established imaging infrastructure to cross-sell Holter systems into hospital networks. Koninklijke Philips N.V. anchors its position through deep channel relationships with European cardiology departments. Schiller competes aggressively on portable device portfolios tailored to ambulatory settings.
A cardiac Holter monitor records electrocardiographic signals continuously for 24 to 48 hours—or up to 14 days with patch-based systems—using electrodes attached to the patient's chest and a compact digital recorder to capture transient arrhythmias missed by standard ECG. Wireless Holter Monitors lead product type demand as patients reject wired tethering during extended monitoring, while Mobile Cardiac Telemetry captures the fastest growth by enabling real-time arrhythmia alerting to clinicians. AI-Enabled technology concentrates investment from vendors seeking reimbursement differentiation through automated beat classification and predictive alerts.
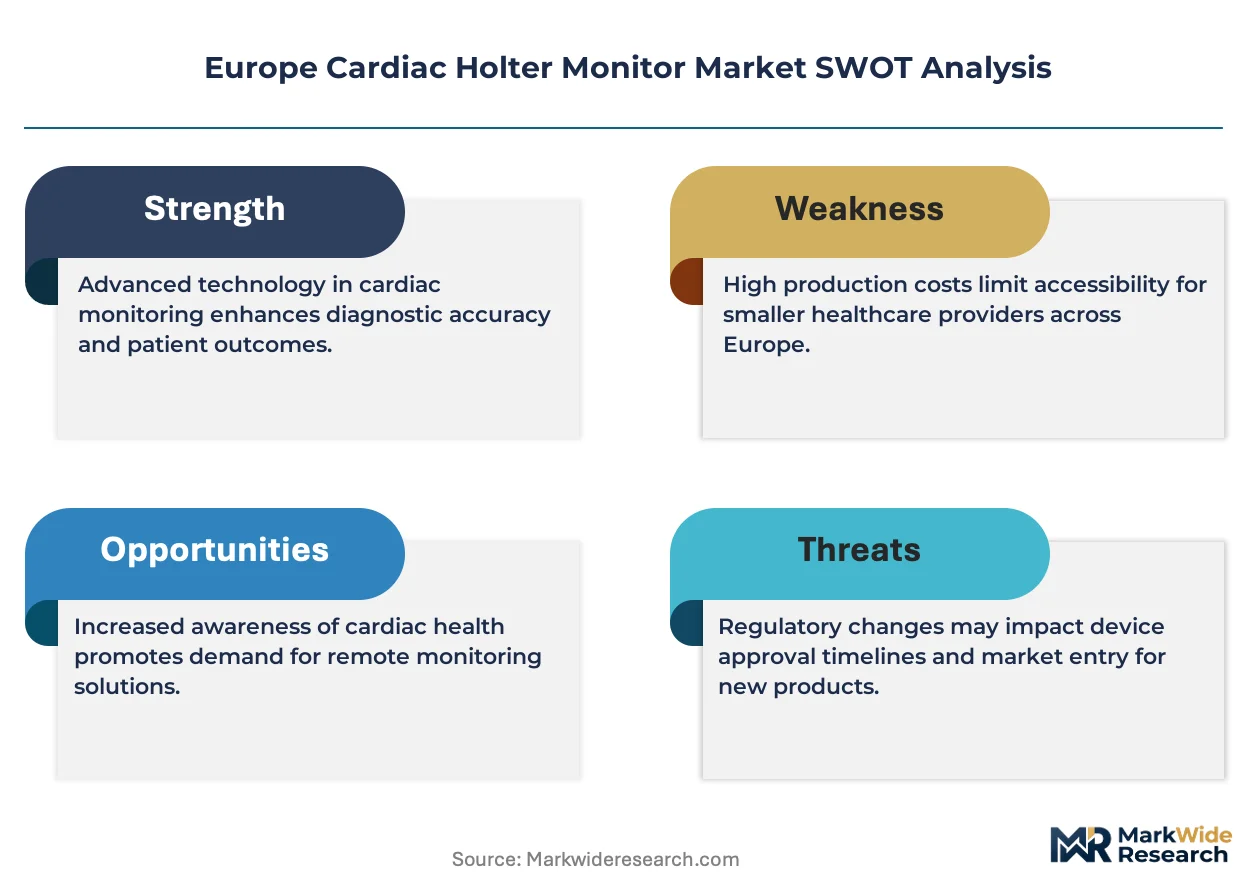
EMA guidance and the EU MDR framework govern clinical evidence requirements for Class IIa cardiac monitoring devices, forcing manufacturers to maintain post-market surveillance systems and updated technical documentation. CE marking under MDR Article 52 demands notified body involvement for most Holter variants, extending time-to-market for new entrants. Stakeholders must track evolving HTA assessments from France's HAS and Germany's G-BA as these bodies increasingly condition hospital reimbursement on demonstrated reduction in undiagnosed atrial fibrillation burden.
Market Dynamics
The EU Medical Device Regulation is compressing time-to-market timelines while simultaneously elevating clinical evidence requirements for Class IIa cardiac monitoring devices, forcing manufacturers to rebuild technical documentation and post-market surveillance infrastructure from the ground up.
Growth Catalysts
- Ambulatory Care Expansion:Western European health systems are relocating cardiac monitoring from inpatient wards to outpatient clinics and home settings, creating pull-through demand for portable Holter systems that integrate with hospital EHR networks.
- EU MDR Article 52:The notified body involvement mandate for CE marking, while burdensome, is clearing marginal competitors from the field and concentrating procurement among vendors with established regulatory affairs capabilities.
- Patch-Based Extended Monitoring:Electrode patch technologies enabling 7-14 day wear are displacing traditional 24-48 hour Holter studies for cryptogenic stroke workups, expanding the addressable patient population for ambulatory arrhythmia detection.
Market Restraints
- Notified Body Bottleneck:The limited number of EU MDR-accredited notified bodies in Germany, France, and the Netherlands is extending certification timelines to 18-24 months, freezing product pipelines for mid-tier manufacturers.
- Semiconductor Supply Concentration:Analog front-end chips and low-power microcontrollers for Holter recorders concentrate in Taiwanese and South Korean foundries, exposing European assemblers to geopolitical supply shocks.
- Mobile Cardiac Telemetry Substitution:Real-time cellular-enabled monitors are capturing diagnostic cases previously routed to traditional Holter studies, compressing volume for store-and-forward devices in hospital-based programs.
Strategic Opportunities
- Eastern European Hospital Modernization:Poland, Romania, and Hungary are channeling EU structural funds into cardiology department upgrades, creating first-mover advantage for vendors willing to navigate fragmented procurement at the member-state level.
- AI-Enabled Beat Classification:Machine learning algorithms embedded in Holter analysis software are creating reimbursement differentiation through automated atrial fibrillation burden quantification, a metric increasingly valued by France's HAS and Germany's G-BA.
- Direct-to-Consumer Channel Emergence:Consumer-grade wearable ECG devices are conditioning patients to expect continuous monitoring, opening physician-supervised subscription models that bypass traditional hospital procurement committees.
Industry Challenges
- Clinical Engineering Talent Scarcity:European medical device manufacturers face acute shortages of firmware engineers with combined expertise in biopotential signal processing and IEC 60601-1-2 electromagnetic compatibility compliance.
- Legacy System Integration Friction:Hospital IT departments struggle to interface cloud-based Holter analysis platforms with on-premise PACS and EHR architectures, delaying deployment and triggering penalty clauses in framework agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cardiac Holter Monitor Market |
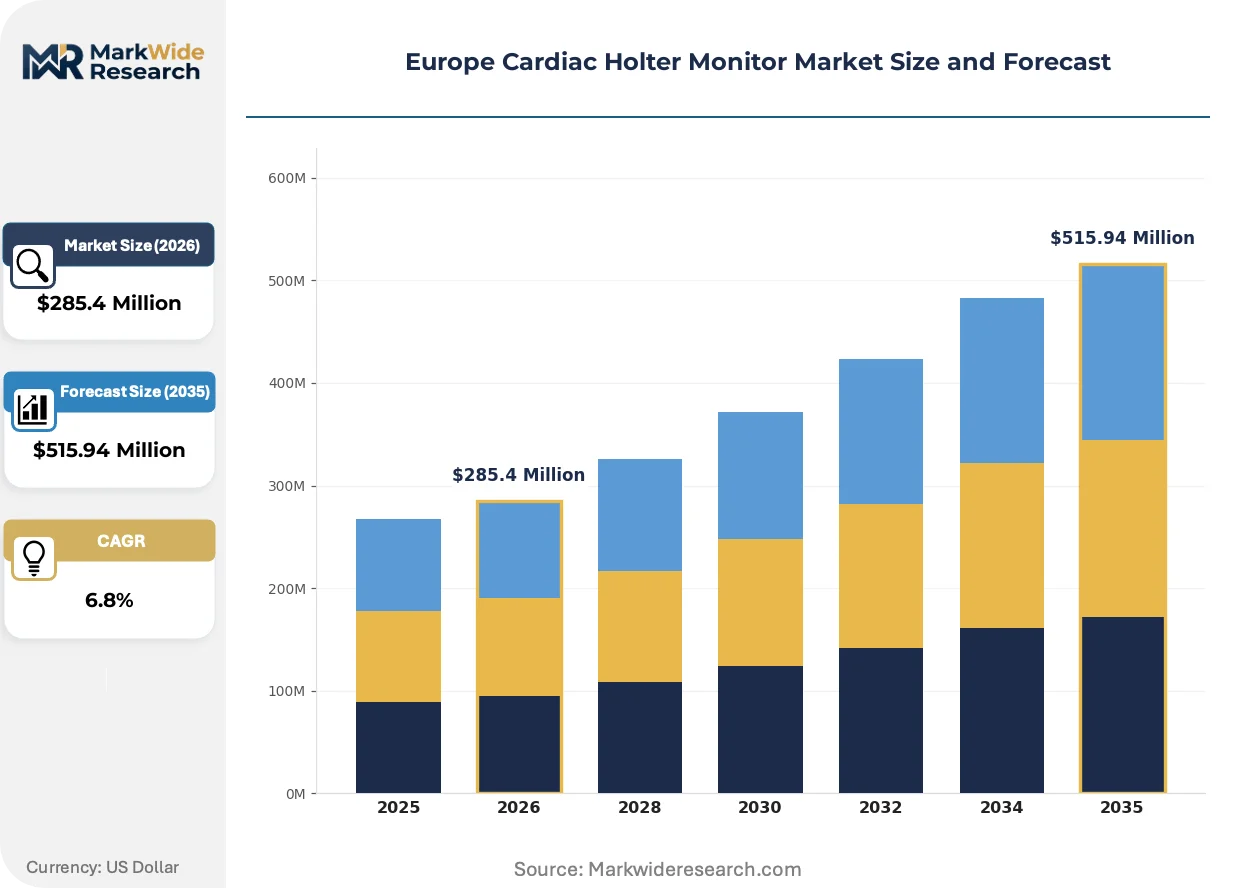
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Holter Monitors, Wireless Holter Monitors, Handheld Monitors, Mobile Cardiac Telemetry End User: Hospitals, Clinics, Home Healthcare, Diagnostic Centers Technology: Analog, Digital, Cloud-Based, AI-Enabled Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Spacelabs Healthcare, Schiller, GE Healthcare, Nasiff Associates, Inc., BTL, FUKUDA DENSHI, Welch Allyn, LifeWatch AG, Koninklijke Philips N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cardiac Holter Monitor Market Strategic Shifts & Innovations
Artificial intelligence is penetrating cardiac rhythm analysis at the algorithmic core, while regulatory frameworks and procurement behaviors are simultaneously adapting to accommodate continuous monitoring modalities that blur traditional diagnostic categories.
Deep learning algorithms trained on million-beat arrhythmia databases are digitizing the clinical workflow for Holter interpretation. Cardiology departments in university hospitals across Germany and the Netherlands are deploying FDA-cleared and CE-marked AI classifiers to reduce technician reading time by flagging normal sinus rhythm strips for automated dismissal. This compression of human review burden is enabling higher patient throughput without proportional staffing expansion, reshaping unit economics for high-volume monitoring centers.
The EU MDR's post-market surveillance requirements are tightening real-world evidence collection for Class IIa devices. Manufacturers must now maintain proactive vigilance systems that capture device malfunctions and serious incidents across distributed ambulatory deployments, a mandate that favors larger vendors with dedicated regulatory affairs teams. Smaller Holter specialists are responding by outsourcing post-market surveillance to specialized CROs or exiting the European market entirely.
Hospital purchasing consortia in France and the United Kingdom are consolidating cardiac monitoring procurement into multi-year framework agreements that bundle Holter hardware, analysis software, and technician interpretation services. This unbundling reversal compresses vendor margins while locking in volume commitments that disadvantage smaller competitors without integrated service capabilities. The model is most visible in England's NHS Supply Chain cardiology frameworks and France's regional hospital group purchasing organizations.
Europe Cardiac Holter Monitor Market Segmentation
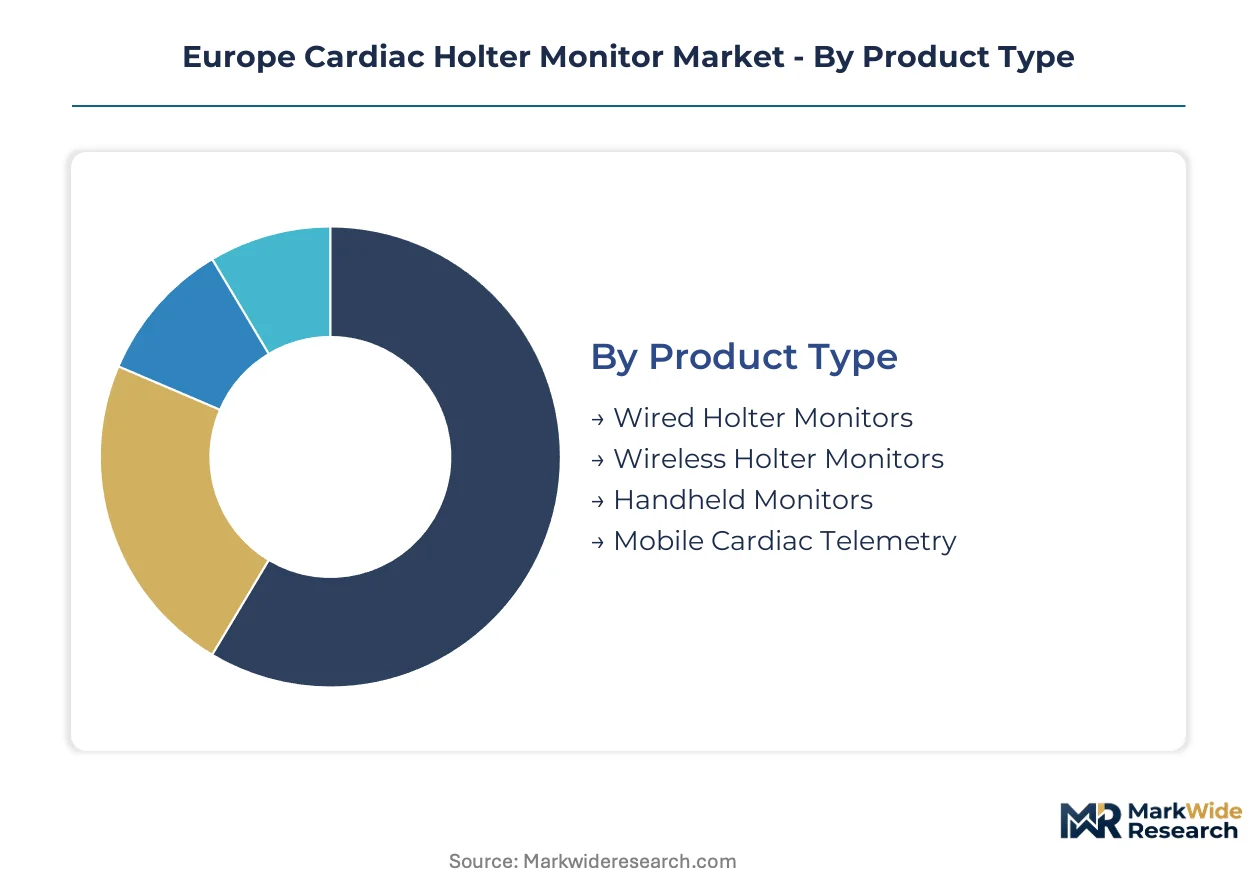
Segmentation in the European cardiac Holter monitor market reveals how procurement priorities diverge across care settings and technology readiness levels. Hospital purchasers prioritize regulatory certainty and EHR integration, while ambulatory providers weigh portability against reimbursement pathways.
Product Type:
Use-case spectrum spans tethered inpatient monitoring through untethered outpatient arrhythmia surveillance, with each modality carrying distinct reimbursement and workflow implications.
- Wired Holter Monitors:Traditional electrode-lead configurations deliver 24-48 hour continuous recording with proven signal fidelity. German university hospitals and French public hospital groups still specify wired systems for cryptogenic stroke protocols where data integrity outweighs patient convenience. Established volume favors Wired Holter Monitors; emerging adoption favors Mobile Cardiac Telemetry.
- Wireless Holter Monitors:Bluetooth-enabled recorders eliminate lead tethers while maintaining diagnostic-grade sampling rates. Demand concentrates in Netherlands outpatient cardiology clinics and UK NHS community diagnostic hubs where patient compliance directly impacts study completion rates. Wireless systems are gaining share fastest among replacement purchases in Western European health systems.
- Handheld Monitors:Compact event recorders activated by symptomatic patients capture intermittent arrhythmia episodes. Spanish and Italian private cardiology practices deploy these for palpitation workups where continuous monitoring is unnecessary.
- Mobile Cardiac Telemetry:Cellular-connected devices stream real-time ECG data to centralized monitoring centers. Poland and Hungary are piloting MCT programs for post-discharge atrial fibrillation surveillance using EU structural health funds.
Procurement committees in France and Germany are rewriting technical specifications to favor wireless and telemetry-capable systems, though wired infrastructure retains installed-base lock-in at major teaching hospitals.
End User:
Customer-type concentration determines pricing tolerance and service bundling requirements, with hospital systems demanding full-risk contracts and home healthcare operators seeking hardware-only procurement.
- Hospitals:Inpatient cardiology departments and emergency observation units require CE-marked Class IIa devices with MDR Article 52 technical documentation. UK NHS Supply Chain frameworks bundle Holter hardware with technician interpretation services, locking vendors into multi-year volume commitments.
- Clinics:Outpatient cardiology practices across Belgium and Austria prioritize portable systems with rapid patient turnaround. These settings tolerate higher per-test costs in exchange for reduced capital equipment footprints.
- Home Healthcare:Remote patient monitoring programs in Sweden and Denmark dispatch patch-based Holter systems directly to patients' residences. Reimbursement variability across EU member states constrains scalable deployment.
- Diagnostic Centers:Independent testing facilities in France's HAS-accredited network perform high-volume Holter analysis under regional hospital group purchasing organization contracts.
Hospital procurement dominates current volume; home healthcare channels are climbing the fastest as post-acute monitoring programs expand.
Technology:
Technology maturity curves separate legacy analog installations from cloud-native deployments, with regulatory validation timelines creating staggered adoption across European health systems.
- Analog:Legacy tape-based and early solid-state recorders persist in Eastern European facilities with limited capital replacement budgets. Romanian and Bulgarian regional hospitals maintain analog fleets where MDR transition timelines have extended grandfathering periods.
- Digital:Solid-state storage with USB or SD card data transfer remains the workhorse technology for mid-tier European hospitals. Digital systems balance acquisition cost against established reimbursement codes in Germany's G-BA framework.
- Cloud-Based:Web-accessible analysis platforms enable distributed cardiologist review across hospital networks. Netherlands-based cardiology cooperatives deploy cloud Holter systems to pool interpretation expertise across rural and urban sites.
- AI-Enabled:Machine learning classifiers embedded in analysis software automate atrial fibrillation burden quantification. France's HAS and Germany's G-BA are conditioning favorable reimbursement on demonstrated AI-driven diagnostic accuracy improvements.
Digital platforms anchor present procurement; AI-Enabled systems are expanding most quickly as vendors seek differentiation in HTA assessments.
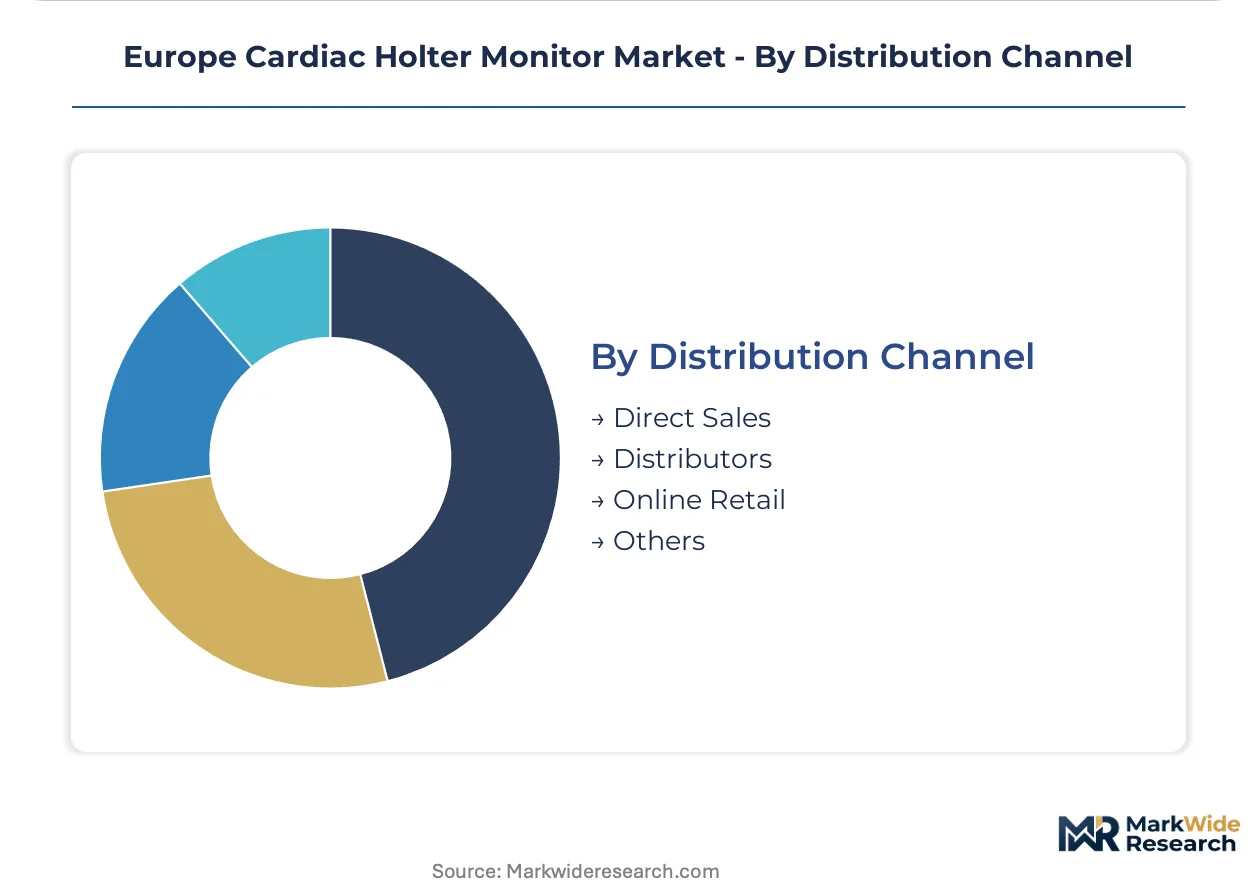
Distribution Channel:
Channel structure reflects customer scale and geographic concentration, with direct relationships dominating consolidated hospital systems and distributor networks covering fragmented private practice markets.
- Direct Sales:Manufacturer field organizations engage hospital purchasing consortia and regional health authorities in France, Germany, and the UK. Direct relationships enable service bundling and framework agreement participation.
- Distributors:Specialized medical device distributors cover private cardiology clinics and diagnostic centers across Spain, Italy, and Portugal. These intermediaries provide local technical support and MDR compliance guidance.
- Online Retail:B2B procurement platforms and manufacturer-direct portals serve smaller clinics and replacement part purchases. Channel penetration remains limited by CE marking documentation requirements.
- Others:Group purchasing organizations and hospital supply cooperatives aggregate demand across member institutions. England's NHS Supply Chain and France's regional GPOs operate as quasi-direct channels with standardized tender processes.
Direct sales capture hospital system volume; distributor networks are gaining share fastest in Southern European private practice markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Holter monitor manufacturing concentrates in German industrial clusters, with component sourcing stretching across Taiwanese and South Korean semiconductor foundries. Procurement patterns diverge sharply between Western European hospital consortia and Eastern European modernization programs.
Germany
University hospitals in Baden-Württemberg and Bavaria drive demand for AI-integrated analysis platforms. The G-BA reimbursement framework conditions hospital payments on demonstrated atrial fibrillation detection accuracy. Berlin-Brandenburg hosts regulatory affairs clusters serving MDR compliance for Class IIa cardiac devices.
France
Regional hospital group purchasing organizations consolidate cardiac monitoring procurement into multi-year service bundles. HAS technical assessments increasingly require AI-enabled beat classification for favorable reimbursement. The Île-de-France region concentrates diagnostic center networks performing high-volume Holter analysis.
United Kingdom
NHS Supply Chain frameworks bundle hardware with technician interpretation services, locking vendors into volume commitments. NICE guidance shapes procurement specifications for ambulatory arrhythmia detection. London and Southeast England anchor community diagnostic hubs relocating monitoring from inpatient wards.
Netherlands
Cardiology cooperatives deploy cloud-based Holter systems to pool interpretation expertise across rural and urban sites. The Dutch Healthcare Authority monitors reimbursement parity between hospital and home-based cardiac monitoring. The Eindhoven region hosts medical device engineering clusters supporting firmware development.
Poland
EU structural funds channel investment into cardiology department upgrades across Warsaw and Kraków metropolitan hospitals. The national health fund pilots mobile cardiac telemetry programs for post-discharge surveillance. Regional procurement fragmentation creates first-mover opportunities for vendors navigating member-state tender processes.
Europe Cardiac Holter Monitor Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying analog front-end chips and low-power microcontrollers. Market structure tilts toward consolidation as MDR compliance costs clear marginal competitors. Three archetypes dominate: imaging conglomerates cross-selling cardiac monitoring into installed hospital networks; dedicated cardiology device houses competing on portable form factors; and telemetry specialists enabling real-time arrhythmia alerting. Dominant competitive moves include strategic partnerships for EHR integration and portfolio diversification into AI-enabled analysis software.
Among diversified health technology conglomerates, GE Healthcare and Koninklijke Philips N.V. occupy positions anchoring the premium system tier through established channel relationships with European cardiology departments. Schiller represents the specialized cardiology device archetype, competing on portable portfolios tailored to ambulatory settings. These three exemplify how regulatory affairs capabilities and service bundling increasingly determine competitive position under EU MDR frameworks.
| Leading Market Players |
|---|
| Spacelabs Healthcare |
| Schiller |
| GE Healthcare |
| Nasiff Associates, Inc. |
| BTL |
| FUKUDA DENSHI |
| Welch Allyn |
| LifeWatch AG |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Taiwanese analog front-end semiconductor foundries compresses pricing tier spreads while simultaneously tethering European assemblers to geopolitical risk premiums. The EU MDR Article 52 notified body bottleneck concentrates procurement leverage among hospital purchasing consortia in Germany and France, forcing mid-tier manufacturers to absorb certification cost inflation or exit the market entirely.
Pricing Analysis
EU MDR Article 52 dictates the pricing tier structure across the European cardiac Holter monitor market by conditioning hospital procurement on Class IIa technical documentation depth. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated analysis platforms from digital storage workhorses and legacy analog systems. Cost compression in the economy tier is intensifying because Eastern European hospitals with extended MDR grandfathering periods delay replacement cycles. Home healthcare operators demonstrate highest price sensitivity due to reimbursement variability across EU member states, while German university hospitals tolerate premium positioning for demonstrated atrial fibrillation detection accuracy.
Supply Chain Analysis
Analog front-end chips and low-power microcontrollers feed from Taiwanese and South Korean semiconductor foundries, with electrode patch materials sourcing from German and Swiss medical-grade adhesive suppliers. Raw material dependencies center on biocompatible conductive polymers, lithium coin cells, and medical-grade silicones. Single-source vulnerability concentrates in the analog front-end segment where TSMC and Samsung Foundry dominate high-precision biopotential signal processing chip production. Distribution runs through direct manufacturer field organizations for hospital consortia and specialized medical device distributors for Southern European private clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital purchasing consortia consolidation across France, Germany, and the United Kingdom has shifted bargaining power decisively toward buyers, compressing vendor margins and locking suppliers into multi-year volume commitments.
For Market Incumbents: Entrench regulatory affairs capabilities as the primary defensive moat by expanding Berlin-Brandenburg compliance clusters and acquiring notified body relationships ahead of competitor pipeline freezes. Invest in backward integration into AI-enabled analysis software to escape hardware commoditization pressure from mobile cardiac telemetry substitutes. Channel control through NHS Supply Chain framework participation locks out mid-tier challengers lacking integrated service bundling. For New Entrants and Emerging Players: Eastern European hospital modernization programs in Poland, Romania, and Hungary represent the most penetrable entry point given EU structural fund availability and fragmented member-state procurement processes. AI-Enabled beat classification for atrial fibrillation burden quantification offers differentiation in HTA assessments from France's HAS and Germany's G-BA. Direct-to-consumer subscription models bypassing traditional hospital procurement committees provide a go-to-market angle conditioned by consumer-grade wearable ECG device familiarity. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors platform integrators with established MDR compliance infrastructure and hospital network relationships. Long-term viability favors acquisition targets with dedicated post-market surveillance systems and cloud-native analysis platforms. The signal to watch is HTA assessment evolution from France's HAS and Germany's G-BA conditioning reimbursement on AI-driven diagnostic accuracy improvements.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 52 compliance compresses time-to-market for Class IIa cardiac devices through notified body pre-submission. |
| Hospital System Partnership | NHS Supply Chain framework participation locks multi-year volume commitments across England's community diagnostic hubs. |
| Software Companion Development | AI-enabled beat classification embedded in Holter analysis platforms creates reimbursement differentiation in G-BA assessments. |
| Reimbursement Strategy | Demonstrated atrial fibrillation burden quantification secures favorable HTA positioning from France's HAS. |
| Geographic Expansion | Poland and Hungary channel EU structural funds into cardiology department upgrades for telemetry pilot programs. |
Research Approach
A spread of perspectives from hospital purchasing committee members, biomedical engineers with firmware expertise, GPO contracts managers, and regulatory affairs leads converged on the working assumptions driving this analysis. Primary interviews with cardiology department heads and diagnostic center operators combined with secondary validation against EMA guidance documents, EU MDR technical documentation requirements, hospital procurement databases, and HTA assessment records from France's HAS and Germany's G-BA. Bottom-up segmentation modeling triangulated against top-down macroeconomic overlays across the European cardiac monitoring sector.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling volume and value outputs through product type, end user, technology maturity, and distribution channel dimensions. CAGRs derived from historical procurement trajectory analysis and forward-looking reimbursement pathway assessments. Forecast inputs incorporated EU MDR transition timelines, notified body capacity constraints, and semiconductor supply chain risk premiums.
Macroeconomic conditions sit as an overlay; deviation in eurozone healthcare expenditure growth or Taiwan Strait logistics disruption would shift the trajectory. Forecasts reflect underlying assumptions about MDR compliance cost absorption and AI-enabled diagnostic accuracy validation timelines. Cross-checking against EMA post-market surveillance incident databases and national health fund reimbursement bulletins is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Cerebral Oximetry Monitoring Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
Transcutaneous Monitors Market