
 Vitamin Deficiency Treatment Market | 2026-2036
Vitamin Deficiency Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin Deficiency Treatment Market Analytics
Good Manufacturing Practice certification for dietary supplement production is collapsing as a baseline qualifier, separating contract manufacturers from integrated pharmaceutical operators. Merck & Co. Inc. leverages its prescription-grade vitamin portfolio to anchor hospital and clinical channel access. Pfizer Inc. competes through backward integration into active pharmaceutical ingredient sourcing for parenteral vitamin formulations. Sun Pharmaceutical Industries Ltd dominates emerging market distribution with localized tablet and liquid production networks.
Vitamin deficiency treatment encompasses therapeutic interventions using isolated or compounded micronutrients—typically formulated at pharmacological doses ranging from 1,000 IU to 50,000 IU for vitamin D, and 1,000 mcg for cyanocobalamin—to correct clinically diagnosed insufficiencies identified through serum biomarker testing. These therapies restore enzymatic cofactor availability, reverse hematological and neurological deficits, and prevent skeletal complications in populations with malabsorption, restricted diets, or photosynthesis limitations. Multivitamins and vitamin D together occupy the largest revenue share, while vitamin B12 injectables generate the highest per-unit margins due to cold-chain handling and administration requirements. Gummy delivery formats are gaining fastest among pediatric and geriatric patient groups, though tablets retain cost advantages in institutional procurement.
The US FDA enforces Current Good Manufacturing Practice standards for dietary supplements under 21 CFR Part 111, mandating identity testing, contamination controls, and adverse event reporting that elevates compliance costs for market entry. India's CDSCO requires pharmaceutical-grade vitamin formulations to meet Schedule H or H1 prescription protocols, channeling severe deficiency treatments through qualified medical practitioners. EMA's updated food supplement guidelines across EU member states are harmonizing maximum permitted levels for fat-soluble vitamins, reshaping product concentration strategies for exporters. Stakeholders must monitor evolving bioequivalence requirements for generic injectable vitamins as regulatory agencies tighten therapeutic equivalence standards for narrow-therapeutic-index micronutrients.
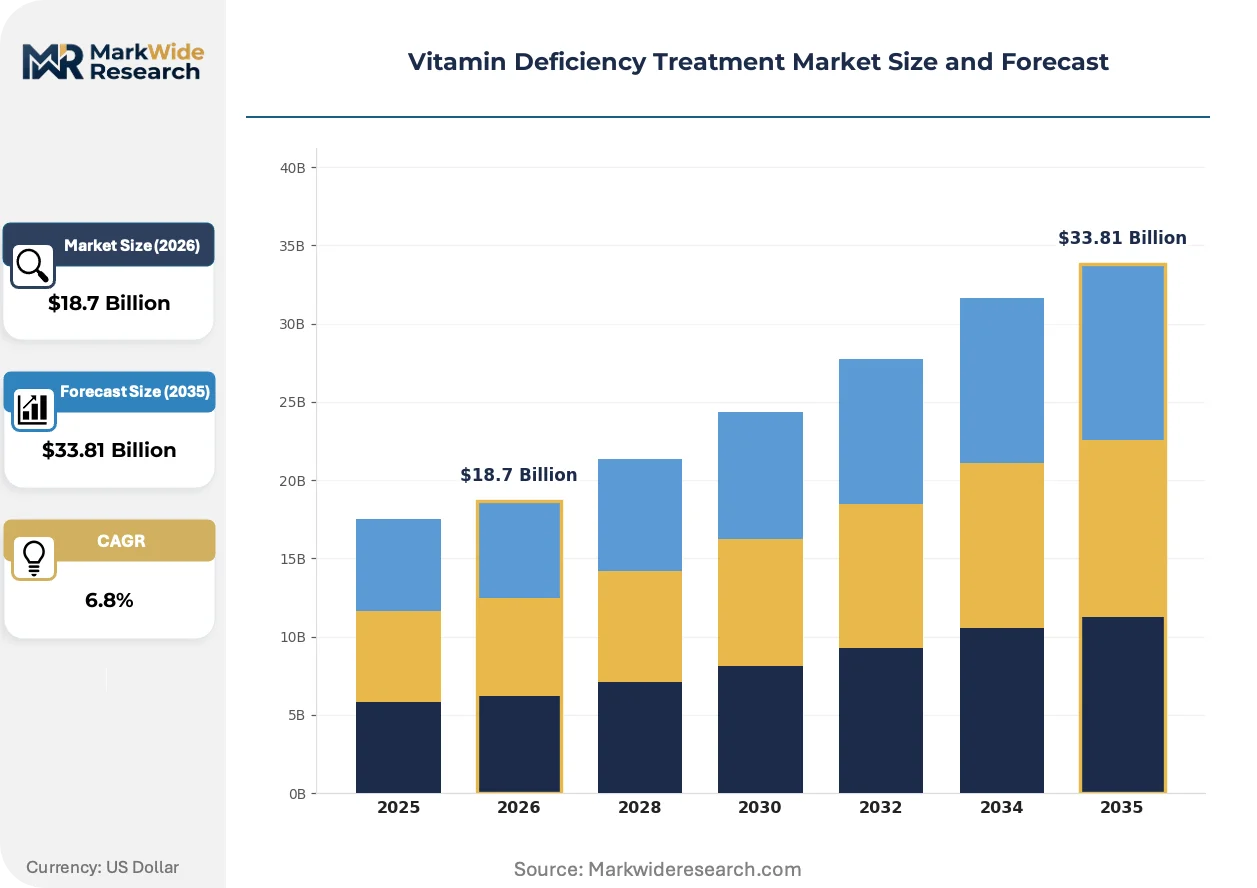
Market Dynamics
Hospital procurement of injectable B12 and vitamin D concentrates is reshaping competitive positioning, as cold-chain handling requirements and administration protocols favor integrated pharmaceutical operators over contract manufacturers lacking GMP certification depth.
Growth Catalysts
- India's micronutrient fortification mandates:Government programs targeting wheat flour and edible oil drive volume procurement of pharmaceutical-grade vitamin premixes through public distribution channels.
- Serum biomarker testing expansion:Diagnostic laboratories in tier-2 and tier-3 cities are scaling 25-hydroxy vitamin D and methylmalonic acid assays, converting undiagnosed deficiencies into addressable treatment demand.
- 21 CFR Part 111 compliance elevation:FDA's tightened identity testing and contamination control standards are filtering out subscale supplement manufacturers, concentrating volume with certified producers.
Market Restraints
- Cholecalciferol API concentration:Active pharmaceutical ingredient production for high-potency vitamin D3 concentrates in limited manufacturing clusters creates supply vulnerability during geopolitical disruptions.
- EMA maximum permitted level harmonization:EU member state alignment on fat-soluble vitamin upper limits forces reformulation of existing products, compressing margin on legacy SKUs.
- Oral spray and transdermal patch substitution:Alternative delivery formats for B12 and D3 are capturing wellness-oriented consumers outside clinical deficiency protocols, narrowing the addressable therapeutic market.
Strategic Opportunities
- Geriatric polypharmacy integration:Fixed-dose combinations of B12 with metformin or vitamin D with calcium channel through hospital formularies capture chronic disease management workflows.
- Pediatric gummy format penetration:Palatable delivery systems for iron and multivitamin complexes address compliance gaps in school-based supplementation programs.
- CDSCO Schedule H1 channel control:India's prescription-grade classification for severe deficiency injectables creates protected market access for pharmaceutical-grade manufacturers against dietary supplement competitors.
Industry Challenges
- Injectable bioequivalence demonstration:Narrow-therapeutic-index requirements for cyanocobalamin and ergocalciferol parenterals demand extensive pharmacokinetic studies, extending generic approval timelines.
- Cold-chain infrastructure capex:Temperature-controlled distribution networks for heat-labile vitamin formulations require substantial capital deployment in emerging markets with unreliable logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin Deficiency Treatment Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivitamins, Vitamin D, Vitamin B12, Vitamin C Delivery Mode: Tablets, Powders, Liquids, Gummies End User: Adults, Children, Pregnant Women, Elderly Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Stores |
| Companies Covered | Merck & Co. Inc., Pfizer Inc., Cipla Inc., Sun Pharmaceutical Industries Ltd, F. Hoffmann-La Roche Ltd, Sandoz International GmbH, Mankind Pharma, BASF SE, Glanbia plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin Deficiency Treatment Market Evolving Landscape
Formulation science and delivery mechanism evolution is fragmenting the traditional tablet-dominated market, with novel absorption technologies and channel-specific packaging formats creating parallel demand streams across clinical, retail, and direct-to-consumer segments.
Liposomal encapsulation technology is fragmenting bioavailability assumptions in vitamin D and B12 supplementation. Functional food manufacturers and compounding pharmacies are adopting phospholipid-based delivery systems at accelerating rates. This technology is fragmenting the competitive map by enabling non-pharmaceutical entrants to claim therapeutic-equivalent absorption profiles without prescription-grade manufacturing infrastructure.
REACH and RoHS substance restrictions across EU member states are forcing reformulation of coating materials and excipients in tablet and capsule production. Manufacturers must substitute titanium dioxide and certain synthetic colorants with compliant alternatives. The dietary supplement export segment is responding by accelerating clean-label certification investments to maintain shelf access in German and French retail chains.
Direct-to-clinic subscription models are compressing traditional wholesale-distributor margins in the parenteral vitamin segment. Physician practices and infusion centers are consolidating procurement through specialized distributors offering inventory management and patient compliance tracking. This pattern concentrates most visibly in US integrated delivery networks and Indian corporate hospital chains seeking to reduce stockout incidents in high-throughput deficiency clinics.
Vitamin Deficiency Treatment Market Segmentation
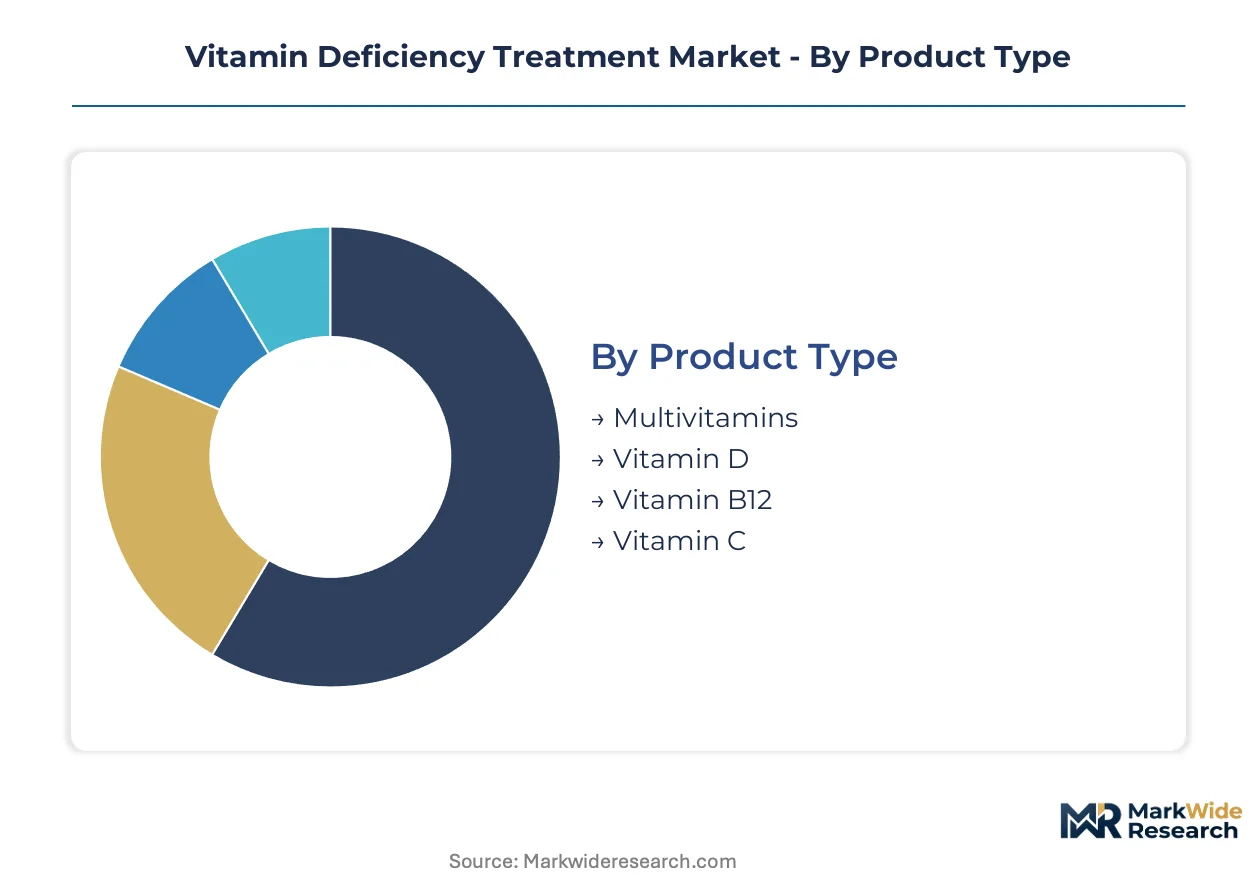
Segmentation in vitamin deficiency treatment reveals how regulatory classification, delivery technology, and patient demographics fragment procurement channels. Manufacturers must align formulation strategies with distinct compliance requirements and administration settings across each category.
Product Type:
FDA's 21 CFR Part 111 and India's CDSCO Schedule H protocols create divergent pathways for pharmaceutical-grade versus dietary supplement positioning, determining reimbursement eligibility and channel access.
- Multivitamins:Broad-spectrum formulations combining fat-soluble and water-soluble micronutrients at maintenance dosages. Institutional procurement in Indian government fortification programs and US hospital formularies drives volume concentration, though margin compression intensifies from private-label competition.
- Vitamin D:Isolated cholecalciferol and ergocalciferol at pharmacological potencies from 1,000 IU to 50,000 IU. Serum 25-hydroxy testing expansion in Indian tier-2 cities and US accountable care organizations converts diagnostic penetration into addressable therapeutic demand.
- Vitamin B12:Cyanocobalamin and methylcobalamin formulations for hematological and neurological deficiency correction. Injectable concentrates generate premium positioning through cold-chain requirements and parenteral administration protocols.
- Vitamin C:Ascorbic acid at therapeutic dosages for scurvy treatment and immune support applications. Wellness channel distribution dominates retail positioning outside clinical deficiency protocols.
Established volume favors multivitamins; emerging adoption favors vitamin D.
Delivery Mode:
Cost tier differentiation separates institutional procurement from direct-to-consumer premium positioning, with manufacturing complexity and stability requirements determining margin architecture.
- Tablets:Compressed solid-dose formulations with extended shelf stability and lowest per-unit production cost. Hospital and pharmacy procurement in India and the US concentrates volume through tender-based purchasing and generic substitution policies.
- Powders:Granular or effervescent formats enabling dose titration and pediatric administration flexibility. Emerging market accessibility programs and compounding pharmacy channels support volume expansion.
- Liquids:Aqueous or oil-based suspensions for populations with dysphagia or malabsorption conditions. Geriatric care facilities and pediatric clinics in Japan and Germany drive specialized demand.
- Gummies:Gelatin or pectin-based chewable matrices with flavor masking for compliance optimization. Palatability-driven positioning captures pediatric and geriatric adherence gaps in US and UK retail channels.
Tablets dominate institutional procurement; gummies are climbing the fastest in direct-to-consumer segments.
End User:
Application-specific dosing requirements and physiological absorption variability shape formulation concentration and delivery technology selection across patient populations.
- Adults:Working-age populations with dietary restriction, malabsorption, or limited sun exposure. Occupational health screening and workplace wellness programs in Germany and South Korea expand diagnostic capture.
- Children:Pediatric populations requiring age-appropriate dosing and palatability engineering. School-based supplementation mandates in India and Mexico drive institutional procurement volume.
- Pregnant Women:Gestational populations with elevated folate, iron, and vitamin D requirements. Prenatal care protocols and maternal health initiatives in Brazil and Nigeria concentrate prescription-channel demand.
- Elderly:Geriatric populations with polypharmacy complexity and reduced gastric acid secretion. Polypharmacy integration with chronic disease management in US Medicare Advantage and Japanese long-term care facilities shapes formulary positioning.
Adults represent the largest addressable base; elderly applications are gaining share fastest from polypharmacy integration.
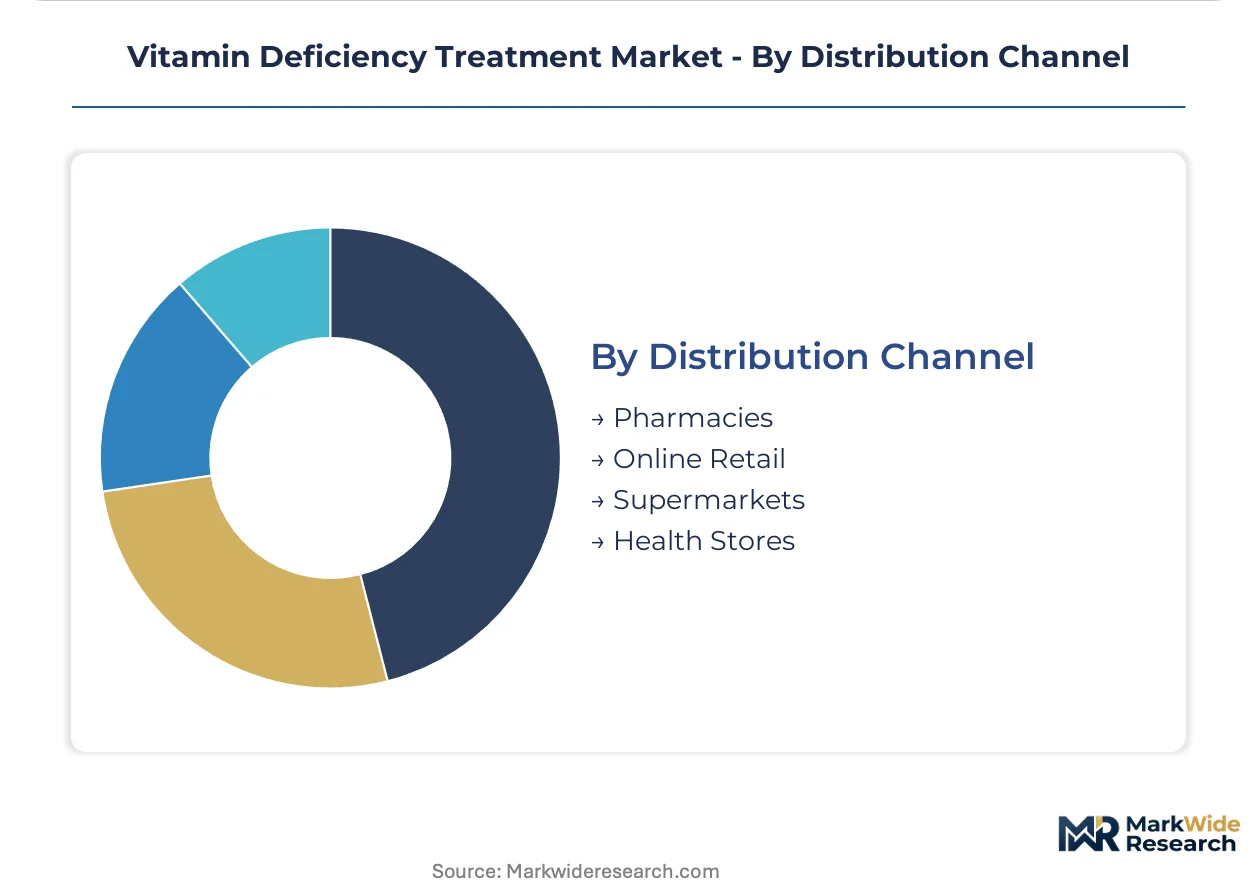
Distribution Channel:
Customer-type fragmentation separates clinical prescription workflows from self-directed wellness purchasing, with channel-specific compliance and counseling requirements determining operator economics.
- Pharmacies:Licensed dispensaries with pharmacist consultation and prescription verification. CDSCO Schedule H1 enforcement in India and US state board regulations protect pharmaceutical-grade positioning against dietary supplement substitution.
- Online Retail:Direct-to-consumer platforms with subscription logistics and telehealth integration. Amazon and specialized vitamin distributors in the US and UK compress traditional wholesale margins through inventory centralization.
- Supermarkets:Mass retail with shelf-stable dietary supplement positioning. Clean-label certification requirements under EU REACH and EFSA guidelines determine shelf access in German and French retail chains.
- Health Stores:Specialty retailers with practitioner-grade and practitioner-exclusive formulations. Functional medicine and integrative health networks in Australia and Canada support premium positioning outside pharmacy channels.
Pharmacies anchor prescription-grade volume; online retail shows steepest expansion trajectory from subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government fortification mandates and diagnostic infrastructure expansion are redrawing procurement patterns across national vitamin deficiency treatment markets. Regulatory classification systems determine whether micronutrient products access prescription channels or compete in dietary supplement retail.
United States
Accountable care organizations and Medicare Advantage plans are embedding 25-hydroxy vitamin D testing into annual wellness protocols. FDA's 21 CFR Part 111 enforcement elevates identity testing costs, filtering subscale supplement manufacturers from hospital pharmacy tenders. Boston and Minneapolis anchor hospital formulary procurement networks for parenteral B12 concentrates.
India
CDSCO Schedule H1 prescription protocols channel severe deficiency injectables through qualified medical practitioners, protecting pharmaceutical-grade positioning. Government wheat flour and edible oil fortification programs drive volume procurement of vitamin premixes through public distribution systems. Mumbai and Hyderabad concentrate contract manufacturing capacity for both domestic supply and export formulation.
Germany
EMA maximum permitted level harmonization across EU member states forces reformulation of fat-soluble vitamin concentrations in legacy products. REACH substance restrictions on coating materials accelerate clean-label certification investments for retail shelf access. Frankfurt and Munich host specialized distribution networks serving integrative medicine practitioners.
Japan
PMDA pharmaceutical-grade classification for high-potency vitamin D and B12 injectables maintains prescription-channel exclusivity against wellness-oriented alternatives. METI standards for functional food labeling create parallel compliance pathways for food-format delivery systems. Osaka and Nagoya concentrate geriatric care facility procurement for liquid and powder formulations.
Brazil
ANVISA prenatal care protocols mandate folate and iron supplementation, concentrating prescription-channel demand through maternal health initiatives. Public health distribution networks for pediatric multivitamins expand through school-based supplementation programs. São Paulo and Rio de Janeiro anchor pharmaceutical manufacturing clusters serving Latin American export markets.
Vitamin Deficiency Treatment Market Competitive Landscape
Player mix skews toward integrated pharmaceutical operators with prescription-grade manufacturing infrastructure and GMP certification depth. Contract manufacturers lacking cold-chain logistics capabilities are retreating from parenteral vitamin segments. Two strategic archetypes dominate: multinational pharmaceutical conglomerates leveraging hospital channel access, and emerging market specialists with localized production networks. Competitive moves concentrate on backward integration into active pharmaceutical ingredient sourcing and fixed-dose combination development for polypharmacy integration.
Within the integrated pharmaceutical tier, Merck & Co. Inc. and Pfizer Inc. occupy positions anchored by prescription-grade vitamin portfolios and hospital formulary relationships. Sun Pharmaceutical Industries Ltd exemplifies the emerging market specialist archetype with localized tablet and liquid production networks. These three entities represent the competitive spectrum from multinational channel dominance to regional manufacturing scale.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Pfizer Inc. |
| Cipla Inc. |
| Sun Pharmaceutical Industries Ltd |
| F. Hoffmann-La Roche Ltd |
| Sandoz International GmbH |
| Mankind Pharma |
| BASF SE |
| Glanbia plc |
| Others |
Value Network & Pricing Analysis
Capacity utilization at GMP-certified injectable facilities in India and Germany sets price floors for pharmaceutical-grade vitamin concentrates, while contract manufacturers lacking cold-chain infrastructure face margin compression from tender-based hospital procurement. Scale economies in high-potency cholecalciferol API production concentrate pricing power with integrated operators possessing backward integration into active pharmaceutical ingredient sourcing.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and dietary supplement positioning, with FDA 21 CFR Part 111 compliance and CDSCO Schedule H1 classification commanding premium positioning against uncertified alternatives. Three-tier pricing structure separates hospital formulary injectables from retail pharmacy tablets and direct-to-consumer gummy formats. Cost compression in retail multivitamin tiers is intensifying because private-label substitution and Amazon subscription models compress wholesale margins. Institutional buyers in Indian government fortification programs exhibit highest price sensitivity, while US hospital pharmacy procurement prioritizes supply security over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for heat-labile vitamin formulations requiring refrigerated transport. API production draws from concentrated manufacturing clusters in India, China, and Switzerland, with cholecalciferol and cyanocobalamin concentrates exhibiting geographic supply concentration. Dependency on imported pharmaceutical-grade excipients, specialized coating materials, and cold-chain packaging components creates vulnerability. Single-source vulnerability in high-potency D3 API manufacturing poses structural risk. Distribution runs through hospital procurement consortia, specialized pharmaceutical distributors, and direct-to-clinic subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diagnostic penetration in emerging market tier-2 cities and government fortification mandate expansion signal early-cycle expansion, with serum biomarker testing adoption creating addressable demand faster than supply response.
For Market Incumbents: Consolidate hospital formulary relationships through fixed-dose combination development integrating B12 with metformin or vitamin D with cardiovascular therapies. Deepen captive supply of cholecalciferol API to defend against generic injectable entrants. Liposomal encapsulation technology from non-pharmaceutical competitors threatens absorption-profile parity without GMP infrastructure investment. For New Entrants and Emerging Players: Lead with pediatric gummy formats for Indian school-based supplementation programs, where palatability requirements and institutional procurement rules favor specialized formulation capabilities. Target CDSCO Schedule H1 prescription-grade injectables in corporate hospital chains seeking reduced stockout incidents. Partner with diagnostic laboratories for patient compliance tracking integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-model direct-to-clinic distributors with inventory management and patient adherence platforms. Five-to-ten year viability favors integrated pharmaceutical operators with cold-chain logistics networks over contract manufacturers lacking GMP certification depth. Monitor FDA bioequivalence requirement tightening for narrow-therapeutic-index injectables as inflection indicator for generic approval timeline extension.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Sourcing | Captive cholecalciferol supply secures margin against raw material volatility in India and China. |
| Fixed-Dose Combination Development | B12-metformin pairings capture chronic disease management workflows in US Medicare Advantage formularies. |
| Cold-Chain Infrastructure Expansion | Temperature-controlled distribution networks unlock parenteral vitamin access in tier-2 Indian cities. |
| Direct-to-Clinic Subscription Launch | Inventory centralization and compliance tracking compress traditional wholesale-distributor margins. |
| Clean-Label Certification Investment | REACH-compliant coating substitution maintains shelf access in German and French retail chains. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with pharmaceutical manufacturing executives, hospital pharmacy procurement managers, CDSCO regulatory affairs leads, and diagnostic laboratory directors; and secondary validation through FDA 21 CFR filings, CDSCO Schedule H1 notifications, EMA food supplement guidelines, and hospital formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical market sizing were triangulated against customs data for vitamin premix imports.
Across the projection horizon, the analytical framework modeled segmentation by product type, delivery mode, end-user population, and distribution channel, with regional regulatory clusters treated as distinct demand environments. CAGRs were derived from penetration curve analysis of serum biomarker testing and fortification program procurement schedules, incorporating pharmaceutical-grade versus dietary supplement classification splits.
The analysis sits within stated boundaries; outcomes outside sustained government fortification mandate funding, stable API supply from concentrated manufacturing clusters, or continued diagnostic test reimbursement would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance cost trajectories and cold-chain infrastructure deployment rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Clinical Nutrition Market