
 Maternal Nutrition Products Market | 2026-2036
Maternal Nutrition Products Market Size, Share, and Industry Trends Forecast 2026-2036
Maternal Nutrition Products Market Foresight
The EU Green Deal is rebalancing ingredient sourcing priorities across European maternal nutrition supply chains. Nestlé S.A. leverages its vertical integration into dairy-derived micronutrient bases to secure consistent DHA and choline supply. Bayer AG anchors its position through pharmaceutical-grade folate formulations that dominate hospital procurement channels. Abbott Laboratories differentiates via science-backed prenatal protocols embedded in clinical nutrition programs.
Maternal nutrition products encompass scientifically formulated dietary supplements, functional foods, and medical nutrition items designed to meet elevated physiological requirements during gestation and lactation, typically delivering calibrated doses of folic acid, iron, calcium, DHA, and vitamin D through controlled-release matrices or bioavailable chelates. Their primary purpose centers on reducing neural tube defect risk, supporting fetal neurodevelopment, and preventing maternal anemia. Pills and powders capture the dominant volume share due to dosage precision and extended shelf stability, while liquid formats gain traction among women experiencing first-trimester pill aversion. Online retailers represent the fastest-growing distribution channel as subscription models and telehealth referrals reshape replenishment behavior.
FDA pregnancy labeling rules and EFSA health claim evaluations shape product positioning and market access thresholds in the United States and Europe, while India's FSSAI fortification standards govern local manufacturing compliance for iron and folic acid premixes. WHO prenatal micronutrient guidelines further influence national procurement policies and donor-funded distribution programs. Stakeholders must monitor evolving bioequivalence requirements for generic prenatal entrants and the shifting reimbursement status of prescription versus over-the-counter maternal supplements across major health systems.
Market Dynamics
Hospital network consolidation is reshaping procurement leverage for maternal nutrition products, with integrated health systems demanding science-backed formulations and transparent supply chain documentation under ESG-linked purchasing criteria.
Growth Catalysts
- WHO prenatal micronutrient guidelines:National health ministries in low-income settings are aligning procurement specifications with WHO recommendations, expanding institutional demand for iron-folic acid and multiple micronutrient supplements.
- Telehealth-integrated subscription models:Direct-to-consumer platforms with clinician oversight are capturing recurring revenue from expectant mothers seeking personalized prenatal protocols.
- Brazil's private maternity care expansion:Rising cesarean rates and hospital births in Brazilian metropolitan centers are elevating physician-prescribed supplement penetration among middle-income households.
Market Restraints
- Marine-derived DHA supply volatility:Peruvian anchovy quota fluctuations and climate-driven algae bloom disruptions constrain omega-3 raw material availability for prenatal formulations.
- EFSA health claim evaluation delays:Pending scientific opinions on choline and lutein benefits create regulatory uncertainty for European product positioning and marketing investments.
- Generic bioequivalence requirements:FDA tightening of dissolution standards for prenatal vitamins is extending approval timelines for cost-competitive entrants.
Strategic Opportunities
- Postpartum recovery formulations:Extended supplementation protocols targeting maternal depletion, lactation support, and mood regulation represent underdeveloped white space beyond traditional prenatal windows.
- EU Green Deal sustainable sourcing mandates:Early compliance with CSRD reporting and regenerative agriculture certifications creates preferential access to ESG-screened institutional procurement channels.
- Men's preconception nutrition:Emerging clinical evidence on paternal micronutrient status and sperm quality is opening adjacent demand from couples planning pregnancy.
Industry Challenges
- Formulation stability expertise:Shortage of pharmaceutical scientists skilled in controlled-release matrix design for iron-calcium interaction mitigation limits product differentiation capabilities.
- Cross-border e-commerce compliance:Divergent national regulations on maximum permitted vitamin levels create fulfillment complexity for direct-to-consumer brands shipping across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maternal Nutrition Products Market |
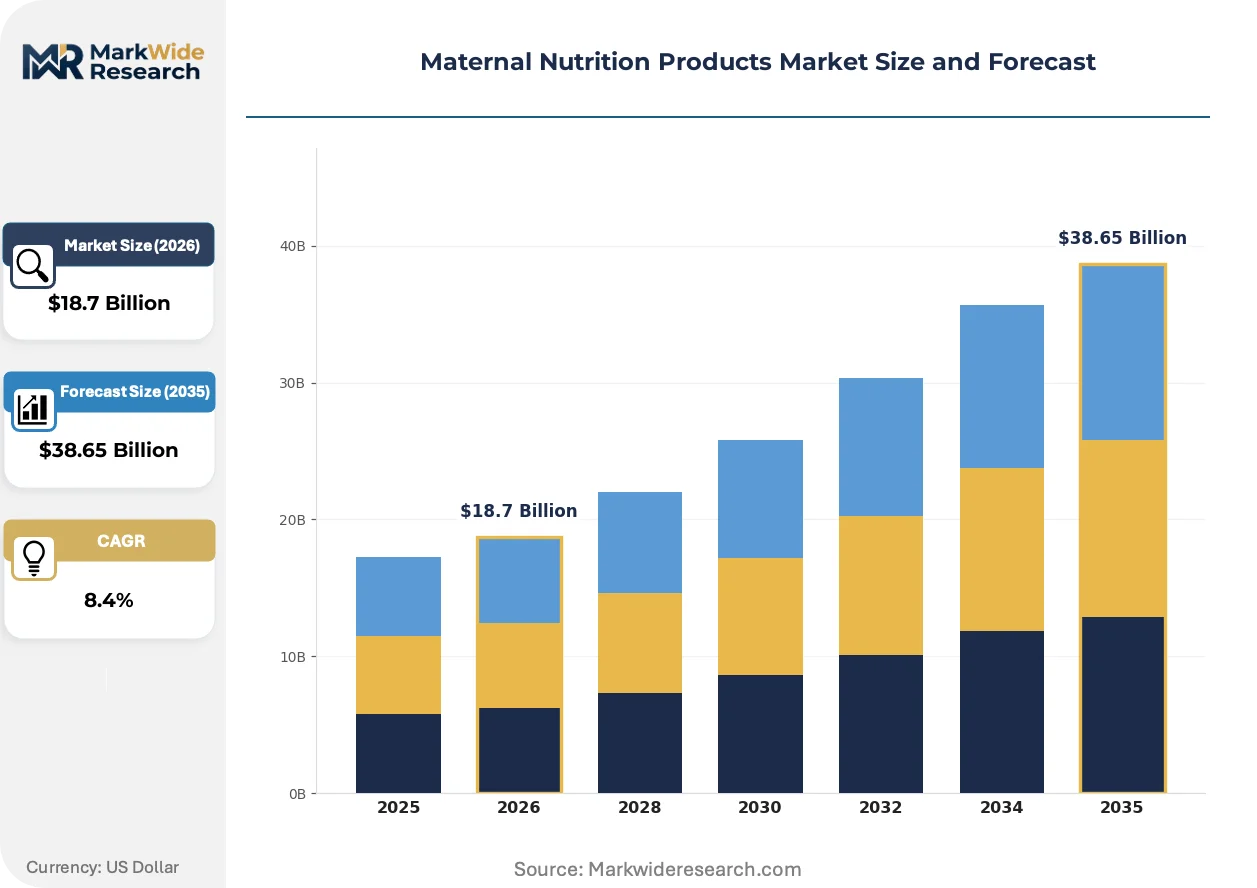
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Supplements, Protein Powders Form: Pills, Powders, Liquid, Bars Distribution Channel: Pharmacies, Supermarkets, Online Retailers, Health Stores Target Audience: Pregnant Women, Nursing Mothers, Healthcare Providers, Nutritionists |
| Companies Covered | Nestlé S.A., Bayer AG, Abbott Laboratories, GlaxoSmithKline plc, Danone S.A., Reckitt Benckiser Group plc, Koninklijke DSM N.V., Arla Food Ingredients Group, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternal Nutrition Products Market Shifts & Advancements
Personalization engines and bioavailability science are converging to displace one-size-fits-all prenatal formulations, with nutrient delivery systems adapting to individual metabolic profiles and trimester-specific physiological demands.
Liposomal encapsulation technology is unifying lipid-soluble vitamin delivery with aqueous mineral suspension in single-dose formats, enabling pharmaceutical manufacturers to consolidate previously separate supplement regimens into unified prenatal protocols that hospital formularies increasingly prefer for patient compliance.
The EU Green Deal's deforestation-free supply chain requirements are compelling ingredient suppliers to document sustainable marine oil and plant extract provenance, with EFSA now evaluating novel sustainability-linked health claim submissions that manufacturers hope will differentiate premium-positioned products in European pharmacy channels.
Subscription-based replenishment with at-home micronutrient testing is displacing traditional retail purchasing cycles, with expectant mothers in US metropolitan markets piloting dried blood spot analysis to adjust DHA and vitamin D dosing throughout gestation rather than relying on static over-the-counter formulations.
Maternal Nutrition Products Market Segmentation
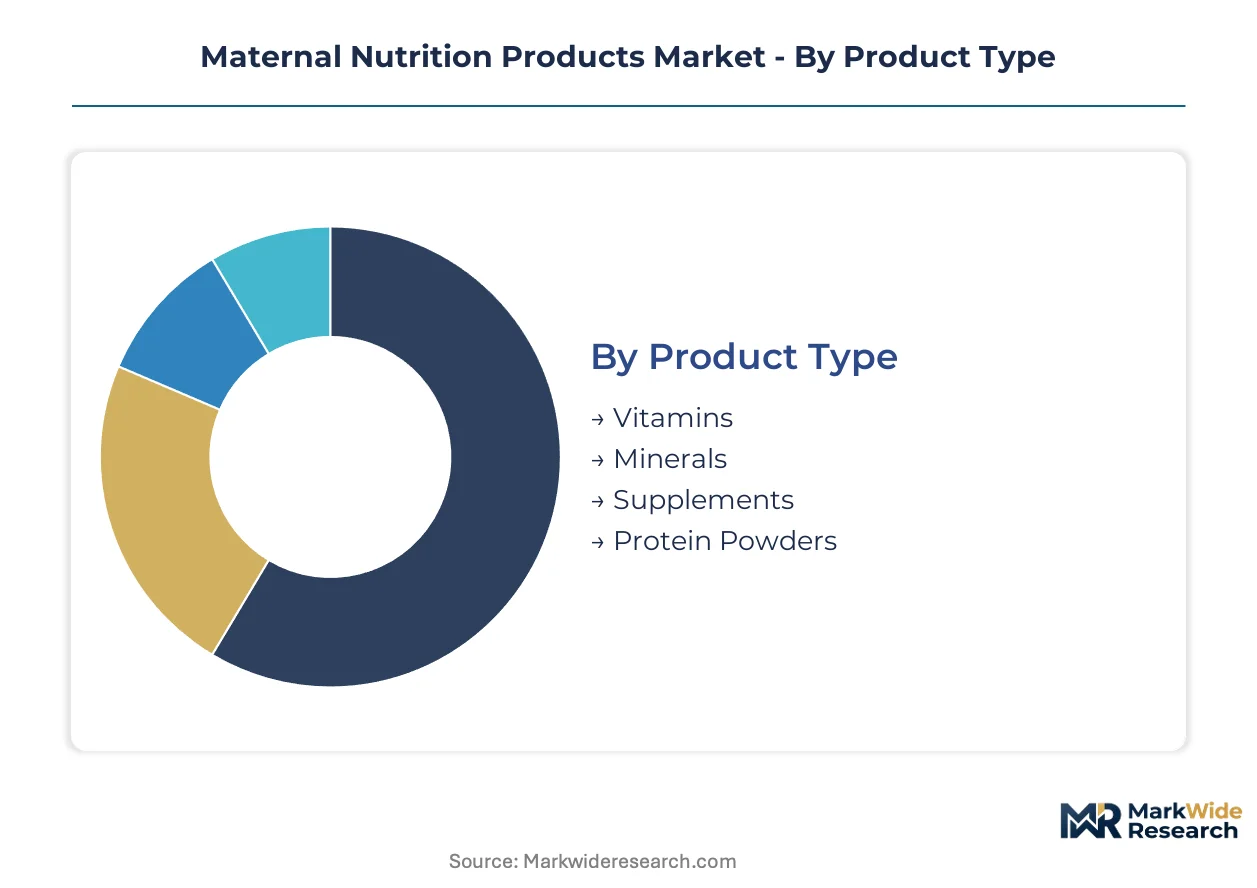
Maternal nutrition products fragment across formulation chemistry, physical delivery systems, and care setting access points. Each segmentation axis reveals distinct margin structures and compliance burdens that shape competitive positioning.
Product Type:
Vitamins and minerals operate as standalone single-nutrient interventions, while supplements and protein powders embed into broader dietary protocols requiring professional guidance.
- Vitamins:Folic acid, vitamin D, and B-complex formulations dominate hospital formularies with established bioequivalence pathways. Demand concentrates in Brazilian metropolitan centers where ANVISA-regulated maternity hospitals mandate prenatal vitamin protocols for insured births.
- Minerals:Iron chelates and calcium carbonate address gestational anemia and skeletal mineralization with controlled-release matrices mitigating gastrointestinal side effects. Procurement is tightening across EU hospital networks as CSRD-linked purchasing criteria demand supply chain documentation for mined mineral sources.
- Supplements:DHA and choline combinations target fetal neurodevelopment with lipid-based delivery systems.
- Protein Powders:Whey and plant-derived formulations support maternal tissue repair and lactation protein requirements.
Vitamins lead volumes today; supplements are gaining share fastest.
Form:
Physical delivery formats stratify by patient compliance economics and first-trimester tolerability constraints.
- Pills:Compressed tablets and softgels offer dosage precision and extended shelf stability that hospital procurement favors for inventory management. Brazilian private maternity networks prescribe physician-dispensed pill protocols to middle-income households with cesarean delivery plans.
- Liquid:Emulsion-based formats bypass pill aversion common in early gestation with flavor-masked suspensions. Telehealth-integrated subscription platforms in US metropolitan markets are capturing recurring revenue from expectant mothers seeking at-home replenishment.
- Powders:Reconstitutable sachets enable flexible dosing adjustment across trimesters.
- Bars:Meal-replacement formats embed maternal nutrition into convenience-oriented consumption occasions.
Pills dominate current procurement; liquid formats are climbing the fastest.
Distribution Channel:
Channel selection determines reimbursement access and professional oversight intensity.
- Pharmacies:Brick-and-mortar pharmacy networks anchor prescription prenatal distribution with pharmacist counseling requirements in regulated markets. EU member states with pharmacy-exclusive supplement policies concentrate volume through this channel.
- Online Retailers:Direct-to-consumer platforms with subscription mechanics and dried blood spot testing integration are displacing traditional replenishment cycles. US telehealth referrals increasingly route patients to clinician-validated online protocols.
- Supermarkets:Mass-market retail captures over-the-counter vitamin and mineral sales with limited professional guidance.
- Health Stores:Specialty retailers position premium-positioned organic and sustainably sourced formulations.
Pharmacies retain the largest volume position; online retailers show the steepest expansion trajectory.
Target Audience:
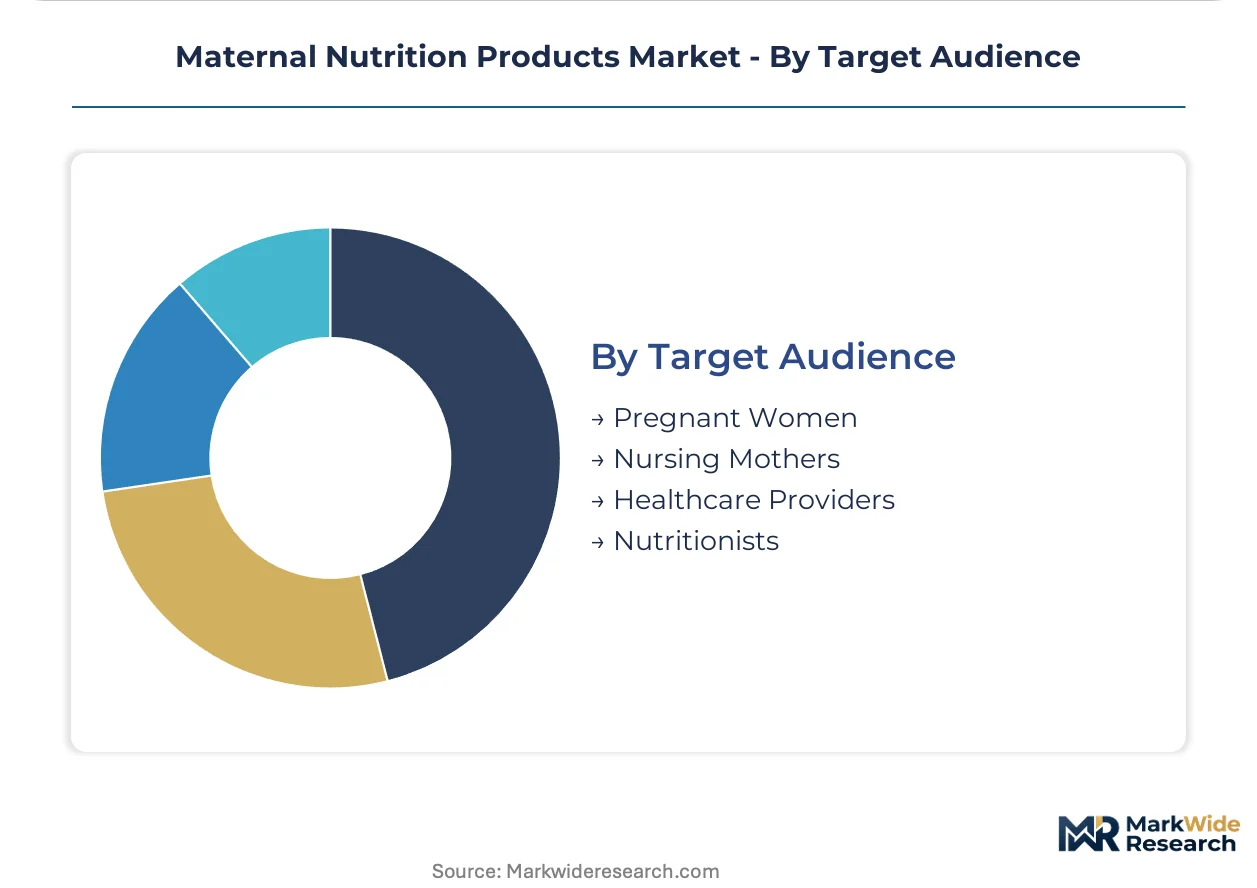
End-user segmentation separates institutional procurement from individual purchasing decisions.
- Pregnant Women:First-time mothers with elevated risk awareness drive premium formulation demand and at-home micronutrient testing adoption. Brazilian public health campaigns are elevating supplement penetration among expectant mothers in metropolitan centers.
- Nursing Mothers:Postpartum lactation support extends supplementation windows beyond gestation with DHA transfer optimization into breast milk. This segment remains underdeveloped relative to prenatal-focused portfolios.
- Healthcare Providers:Hospital networks and individual physicians control prescription protocol design and formulary inclusion.
- Nutritionists:Registered dietitians influence personalized supplementation regimens through telehealth platforms.
Pregnant women anchor current demand; nursing mothers represent the most underpenetrated expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maternal nutrition product manufacturing originated in Swiss and German pharmaceutical corridors during the mid-twentieth century, where precision nutrition science first merged with obstetric medicine. Production networks now span five continents with distinct regulatory and demand profiles shaping regional strategies.
United States
FDA pregnancy labeling rules and telehealth-integrated subscription platforms drive formulation innovation. Hospital network consolidation demands science-backed protocols with transparent supply chain documentation. Metropolitan clusters in Boston and San Francisco anchor clinical nutrition R&D alongside major pharmaceutical distributors.
Germany
EFSA health claim evaluations and pharmacy-exclusive supplement policies concentrate distribution through regulated channels. CSRD reporting requirements push manufacturers toward sustainable ingredient sourcing. The Rhine-Ruhr industrial corridor hosts pharmaceutical-grade premix production serving EU institutional procurement.
Brazil
ANVISA-regulated maternity hospitals and expanding private maternity care elevate physician-prescribed supplement penetration. Public health campaigns target expectant mothers in metropolitan centers with iron-folic acid distribution programs. São Paulo anchors both manufacturing and private hospital network procurement.
India
FSSAI fortification standards govern local manufacturing compliance for iron and folic acid premixes. National health ministry procurement aligns with WHO prenatal micronutrient guidelines for low-income distribution. Maharashtra and Gujarat concentrate contract manufacturing for domestic and export markets.
China
NMPA registration requirements and dual carbon goals reshape ingredient sourcing priorities for domestic formulators. E-commerce platforms displace traditional pharmacy channels for middle-class expectant mothers. Yangtze River Delta clusters integrate algae-derived DHA production with pharmaceutical packaging capabilities.
Maternal Nutrition Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and clinical validation intensity. The vendor base stratifies into three tiers: pharmaceutical conglomerates with hospital formulary access, specialized nutrition houses with ingredient technology advantages, and regional contract manufacturers serving price-sensitive procurement. Dominant competitive moves include backward integration into dairy and marine oil supply chains, plus strategic partnerships with telehealth platforms for direct-to-consumer distribution.
Within the pharmaceutical conglomerate tier, Nestlé S.A., Bayer AG, and Abbott Laboratories exemplify divergent sourcing strategies. Nestlé leverages in-house production of dairy-derived micronutrient bases. Bayer anchors hospital channels through pharmaceutical-grade folate formulations. Abbott differentiates via embedded clinical nutrition programs. These three occupy positions spanning vertical control, regulatory expertise, and healthcare system integration.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Bayer AG |
| Abbott Laboratories |
| GlaxoSmithKline plc |
| Danone S.A. |
| Reckitt Benckiser Group plc |
| Koninklijke DSM N.V. |
| Arla Food Ingredients Group |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Pharmaceutical formulation scientists concentrated in the Rhine-Ruhr corridor command wage premiums that widen spreads between premium pharmaceutical-grade and economy-tier maternal nutrition products. Labor-cost differentials between German precision-manufacturing clusters and Indian contract formulation hubs enable three-tier pricing structures that segment hospital procurement from direct-to-consumer subscription channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates maternal nutrition procurement, with pharmaceutical-grade folate certifications and ESG-linked supply chain documentation driving price differentiation between tiers. Cost compression in economy-tier iron-folic acid premixes is intensifying because Indian contract manufacturers compete on volume scale for national health ministry tenders. Hospital networks exhibit lowest price sensitivity due to formulary protocol requirements, while direct-to-consumer subscribers prioritize convenience premiums over unit economics.
Supply Chain Analysis
Direct-to-hospital channels handle institutional procurement volume, while direct-to-consumer platforms with subscription mechanics capture recurring replenishment demand. Raw material supply concentrates in Peru and Chile for marine-derived DHA, India and China for iron and folic acid premixes, and Germany for pharmaceutical-grade vitamin synthesis. Formulation stability rests on controlled-release matrix expertise, algae-derived omega-3 cultivation, and dairy-derived choline extraction. Single-source vulnerability in Peruvian anchovy quotas constrains DHA availability for prenatal formulations. Distribution runs through hospital procurement networks, pharmacy chains, and telehealth-integrated online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maternal nutrition manufacturing arbitrages regulatory compliance costs between EU CSRD-mandated sustainability documentation and Brazil's ANVISA efficiency pathways, with formulation stability expertise commanding location premiums in German pharmaceutical corridors.
For Market Incumbents: Cement formulary lock-in through embedded clinical nutrition programs that tie prenatal protocols to hospital network consolidation. Deepen backward integration into dairy-derived micronutrient bases to secure captive DHA and choline supply against marine quota volatility. Expand controlled-release matrix R&D capabilities to differentiate from generic entrants facing extended FDA dissolution-standard timelines. For New Entrants and Emerging Players: Liposomal encapsulation technology offers a technology-first wedge into the postpartum recovery formulation white space, where nursing mother segments remain underdeveloped relative to prenatal-focused portfolios. Target Brazilian private maternity care expansion with physician-dispensed protocols for middle-income cesarean delivery households. Deploy telehealth-integrated subscription models with at-home micronutrient testing to bypass pharmacy channel gatekeeping. For Investors and Strategic Acquirers: Pharmaceutical conglomerates with hospital formulary access are the most active acquirer in this space, seeking ingredient technology advantages to complement existing clinical nutrition programs. Acquisition target archetypes include specialized nutrition houses with algae-derived DHA production capabilities and regenerative agriculture certifications for EU Green Deal compliance. Watch EFSA health claim evaluation outcomes on choline and lutein as inflection indicators for premium positioning viability in European pharmacy channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marine Oil Supply | Peruvian anchovy quota volatility makes captive DHA sourcing critical for formulation continuity. |
| CSRD-Linked Sustainability Certification | EU Green Deal compliance unlocks preferential access to ESG-screened hospital procurement channels. |
| Telehealth Platform Partnership | Clinician-validated subscription models displace traditional pharmacy replenishment cycles in US metropolitan markets. |
| Postpartum Formulation Line Extension | Maternal depletion and lactation support protocols capture underpenetrated demand beyond gestation windows. |
| Controlled-Release Matrix R&D Investment | Iron-calcium interaction mitigation expertise limits generic bioequivalence competition from cost-competitive entrants. |
Research Methodology
Multiple input streams — executive interviews with pharmaceutical formulation directors, procurement managers at hospital networks, regulatory affairs leads at ANVISA and FDA, and telehealth platform operators — were reconciled against secondary validation from FDA pregnancy labeling filings, EFSA health claim submission databases, WHO prenatal micronutrient guideline documentation, and Brazilian national health ministry procurement records. Bottom-up demand modeling across product type, physical form, distribution channel, and target audience segments was triangulated with top-down value chain analysis.
Data-stream reconciliation anchored volume and value outputs across the analysis window through segmented demand modeling that incorporated formulation chemistry tiers, care setting access points, and regional regulatory clusters. CAGRs were derived from trajectory fitting to historical procurement patterns and forward projection of telehealth-integrated subscription adoption, hospital network consolidation effects, and CSRD-linked purchasing criteria penetration. Industry-specific forecast inputs included ANVISA-regulated maternity hospital expansion rates and algae-derived DHA production capacity buildout in Yangtze River Delta clusters.
The model holds under stable regulatory enforcement of FDA dissolution standards and EFSA health claim timelines; deviation in WHO guideline revisions or Peruvian anchovy quota allocations would shift institutional procurement specifications and raw material cost structures. Periodic stress-testing of base assumptions against marine oil supply volatility and generic entrant bioequivalence success rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
US Clinical Nutrition Market