
 US Clinical Nutrition Market | 2026-2036
US Clinical Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
US Clinical Nutrition Market Analysis
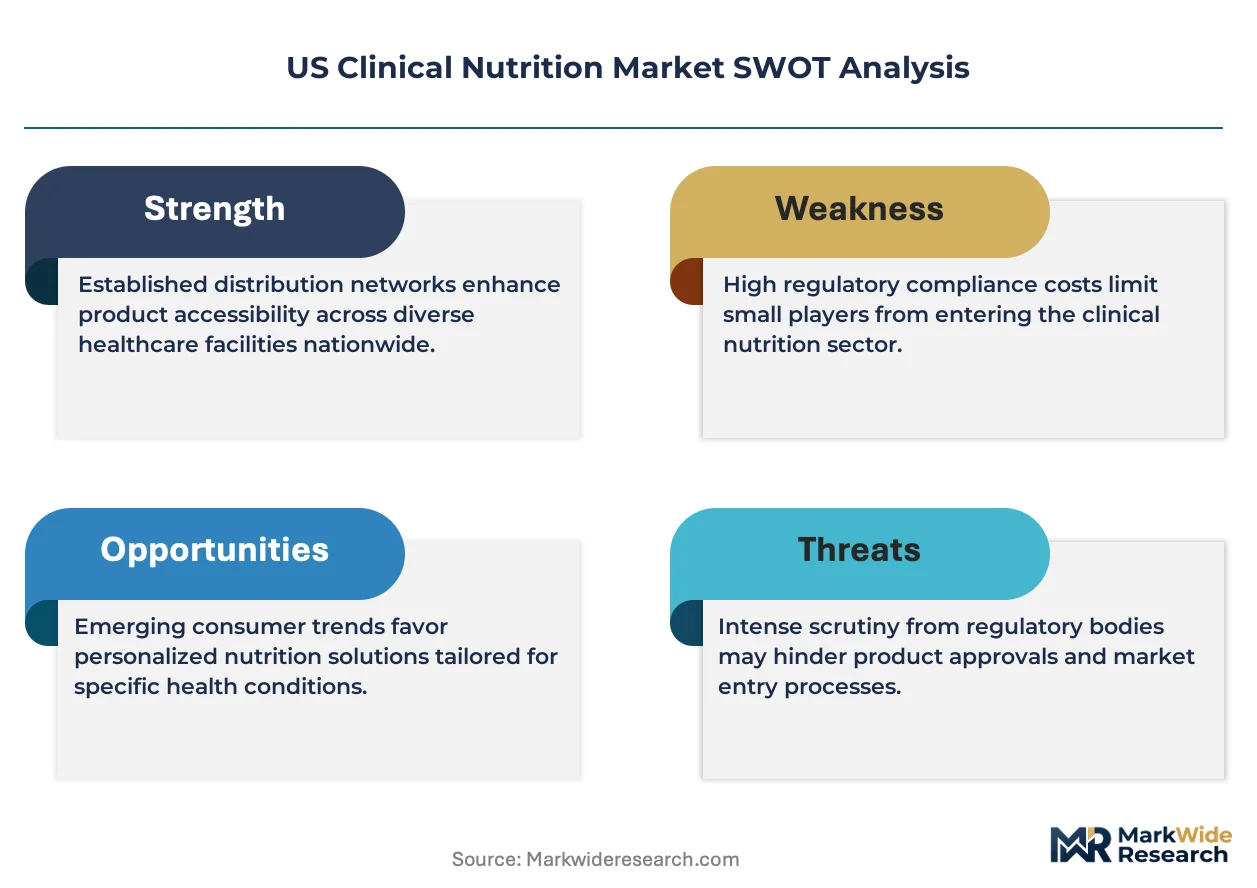
Asset-light leasing models for enteral feeding pumps is fragmenting competitive dynamics across the US clinical nutrition landscape. Abbott Laboratories leverages vertical integration from formula production to pump distribution, sustaining cost advantages in home care channels. Fresenius Kabi anchors hospital parenteral nutrition contracts through captive pharmacy networks. Nestle Health Science differentiates via disease-specific formulations in oncology and critical care segments.
Clinical nutrition encompasses medically supervised nutrient delivery through enteral tubes, intravenous solutions, oral supplements, and disease-modifying specialty foods formulated to precise macronutrient ratios, osmolality thresholds, and immunonutrient profiles for patients unable to meet metabolic requirements through standard diet. Enteral nutrition leads product type revenue due to lower complication rates and earlier hospital discharge protocols, while parenteral nutrition commands premium pricing in intensive care settings where gastrointestinal function is compromised. Home care represents the fastest-growing end user channel as payors push cost containment through outpatient management of chronic conditions.
FDA oversees medical food labeling and safety standards under Orphan Drug Act provisions, while CMS reimbursement schedules directly determine product accessibility across Medicare and Medicaid populations. State-level Department of Health regulations in California, New York, and Illinois impose additional licensing requirements on long-term care nutrition services, creating compliance cost variation. Stakeholders must monitor evolving FDA guidance on personalized nutrition interventions and CMS bundled payment pilots that could reallocate margin pools between inpatient and home-based delivery settings.
Market Dynamics
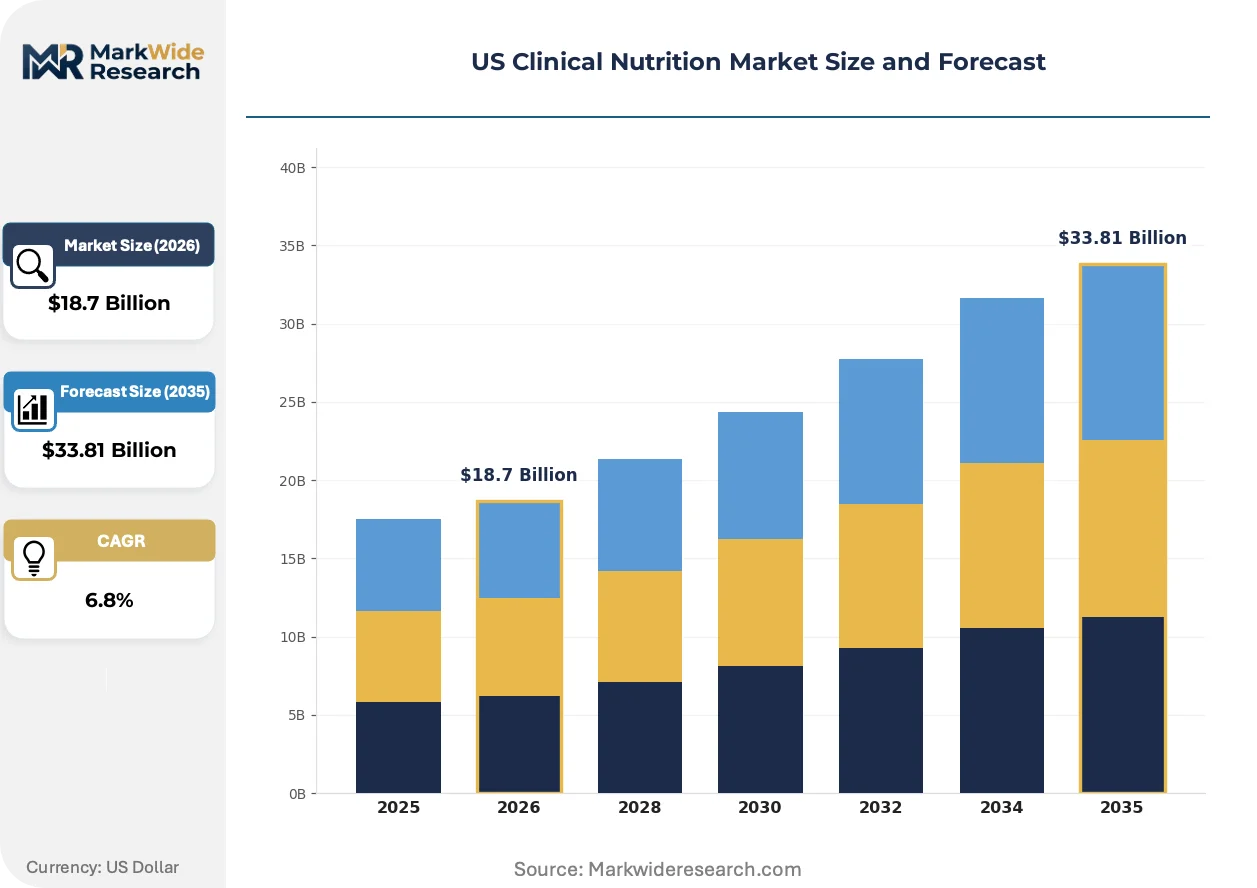
CMS reimbursement compression is forcing product standardization across enteral and parenteral nutrition categories while simultaneously accelerating site-of-care migration toward home-based delivery models.
Growth Catalysts
- IRAs Medicare price negotiation provisions:Expanded coverage for oral nutritional supplements in Medicare Part D is widening patient access to disease-specific formulations.
- Texas and Florida demographic clustering:Aging population concentration in these states is concentrating demand for long-term care nutrition services and specialized renal formulas.
- Enteral pump leasing platforms:Asset-light equipment models are reducing capital barriers for home care agencies entering chronic disease management.
Market Restraints
- Aluminum and phosphate raw material volatility:Parenteral nutrition additive costs fluctuate with mining supply disruptions and energy price spikes.
- FDA medical food labeling requirements:Orphan Drug Act compliance creates extended approval timelines for novel immunonutrient formulations.
- Home infusion pharmacy concentration:Three national specialty pharmacy networks control 60% of parenteral distribution, limiting price negotiation leverage for regional providers.
Strategic Opportunities
- Remote patient monitoring integration:Telehealth platforms paired with smart feeding pumps enable real-time tolerance assessment and formula adjustment.
- California Department of Health licensing harmonization:Streamlined multi-state credentialing for long-term care dietitians reduces compliance overhead for national operators.
- Oncology supportive care protocols:Cachexia management guidelines from the Academy of Nutrition and Dietetics are embedding oral nutritional supplements into standard cancer treatment pathways.
Industry Challenges
- Specialized clinical nutrition pharmacist scarcity:Compounding expertise for parenteral admixtures requires board certification that fewer than 400 practitioners hold nationwide.
- Legacy electronic health record integration:Home care agencies struggle to connect enteral feeding documentation with hospital discharge systems, creating care continuity gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Clinical Nutrition Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enteral Nutrition, Parenteral Nutrition, Nutritional Supplements, Speciality Foods Application: Oncology, Gastroenterology, Pediatrics, Critical Care End User: Hospitals, Long-term Care Facilities, Home Care, Outpatient Clinics Formulation: Powder, Liquid, Gel, Ready-to-Drink |
| Companies Covered | Abbott Laboratories, Reckitt Benckiser, Baxter International, Fresenius Kabi, B. Braun Melsungen, Nestle Health Science, Hero Nutritionals, Perrigo Company, Pfizer, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Clinical Nutrition Market Emerging Trajectories
Product formulation science is converging with digital delivery infrastructure, creating new competitive battlegrounds around personalization speed and remote monitoring capabilities.
Peptide-based enteral formulas are migrating from critical care niches toward broader home care adoption. Gastroenterology practices in Florida and Arizona are prescribing hydrolyzed protein products for malabsorption patients previously managed on standard polymeric feeds. This technology shift is compressing the clinical trial-to-home-use cycle from 18 months to under 6 months for certain indications.
CMS bundled payment pilots for renal disease are restructuring nutrition service economics. The Comprehensive Kidney Care Contracting model now includes oral nutritional supplements as a covered benefit, redirecting margin pools from inpatient dialysis units toward outpatient dietitian counseling. Nephrology practices in Texas are reorganizing procurement around these value-based arrangements.
Hospital discharge planners are consolidating vendor relationships for enteral nutrition services. Single-source contracts covering formula, pumps, and home nursing visits are displacing fragmented purchasing across separate suppliers. This behavioral shift is most visible in Medicare Advantage networks concentrated in Ohio and Pennsylvania, where payors demand episode-based cost accountability.
US Clinical Nutrition Market Segmentation
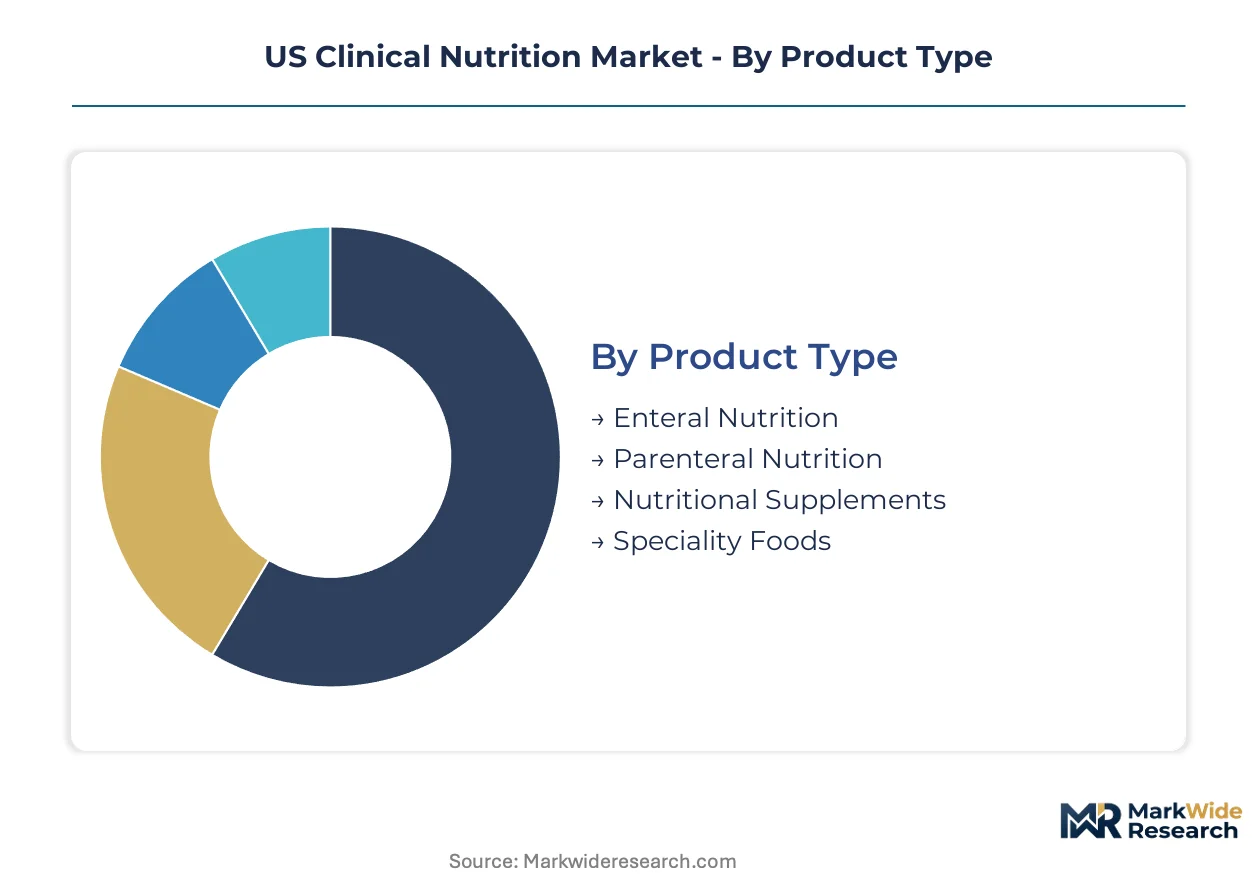
US clinical nutrition segmentation reveals how reimbursement pathways and site-of-care economics allocate margin across delivery modes. Product form, patient setting, and disease indication each command distinct service intensity requirements that reshape vendor economics.
Product Type:
After-sales service intensity varies sharply across product categories, with pump-dependent enteral systems requiring sustained technical support while parenteral admixtures demand compounding oversight.
- Enteral Nutrition:Tube-delivered formulas administered through nasogastric, gastrostomy, or jejunostomy routes with osmolality calibrated to gastrointestinal tolerance. Demand clusters in Texas and Florida long-term care facilities where aging demographics drive chronic disease management protocols and CMS reimbursement favors outpatient enteral over parenteral alternatives.
- Parenteral Nutrition:Intravenous nutrient solutions compounded in sterile pharmacy environments for patients with non-functional gastrointestinal tracts. Intensive care units in academic medical centers anchor demand, though home infusion pharmacy networks are capturing volume as payors push site-of-care migration toward residential settings with remote monitoring capabilities.
- Nutritional Supplements:Oral formulations spanning standard polymeric to disease-specific immunonutrient profiles for patients with intact swallowing function.
- Speciality Foods:Medical foods formulated under FDA Orphan Drug Act provisions for inherited metabolic disorders and specific disease states.
Enteral nutrition holds the largest share; momentum sits with speciality foods as FDA guidance evolves on personalized nutrition interventions.
Application:
Clinical workflow integration demands differ by therapeutic area, with oncology protocols embedding nutrition earlier in treatment pathways than traditional gastroenterology referral models.
- Oncology:Cachexia management and perioperative immunonutrition support for surgical and medical oncology patients. Academy of Nutrition and Dietetics guidelines are embedding oral supplements into standard cancer care, with Florida and Arizona practices prescribing hydrolyzed peptide formulas for malabsorption complications.
- Gastroenterology:Inflammatory bowel disease, short bowel syndrome, and motility disorder management through enteral and parenteral routes. Pediatric gastroenterology practices in California drive demand for elemental formulas, while adult IBD centers concentrate in Northeast corridor academic hospitals.
- Pediatrics:Growth failure, premature infant discharge planning, and congenital anomaly nutrition support requiring age-specific macronutrient ratios.
- Critical Care:Early enteral feeding initiation and parenteral supplementation for hemodynamically unstable patients with compromised gut perfusion.
Oncology commands premium pricing; pediatrics is climbing the fastest as neonatal ICU discharge protocols expand home enteral programs.
End User:
Capital deployment patterns distinguish institutional purchasers from home care agencies navigating asset-light equipment leasing platforms.
- Home Care:Outpatient management of chronic enteral and parenteral nutrition with nursing oversight and remote pump monitoring. Medicare Advantage networks in Ohio and Pennsylvania are consolidating vendor relationships into single-source contracts covering formula, equipment, and nursing visits.
- Hospitals:Inpatient acute care nutrition support with discharge planning coordination to home care or long-term care transitions.
- Long-term Care Facilities:Skilled nursing and assisted living nutrition services with state Department of Health licensing requirements varying compliance costs across California, New York, and Illinois.
- Outpatient Clinics:Ambulatory nutrition counseling and supplement dispensing in nephrology, oncology, and gastroenterology specialty practices.
Hospitals retain the largest share; home care is gaining share fastest as CMS bundled payment pilots reallocate margin pools toward outpatient settings.
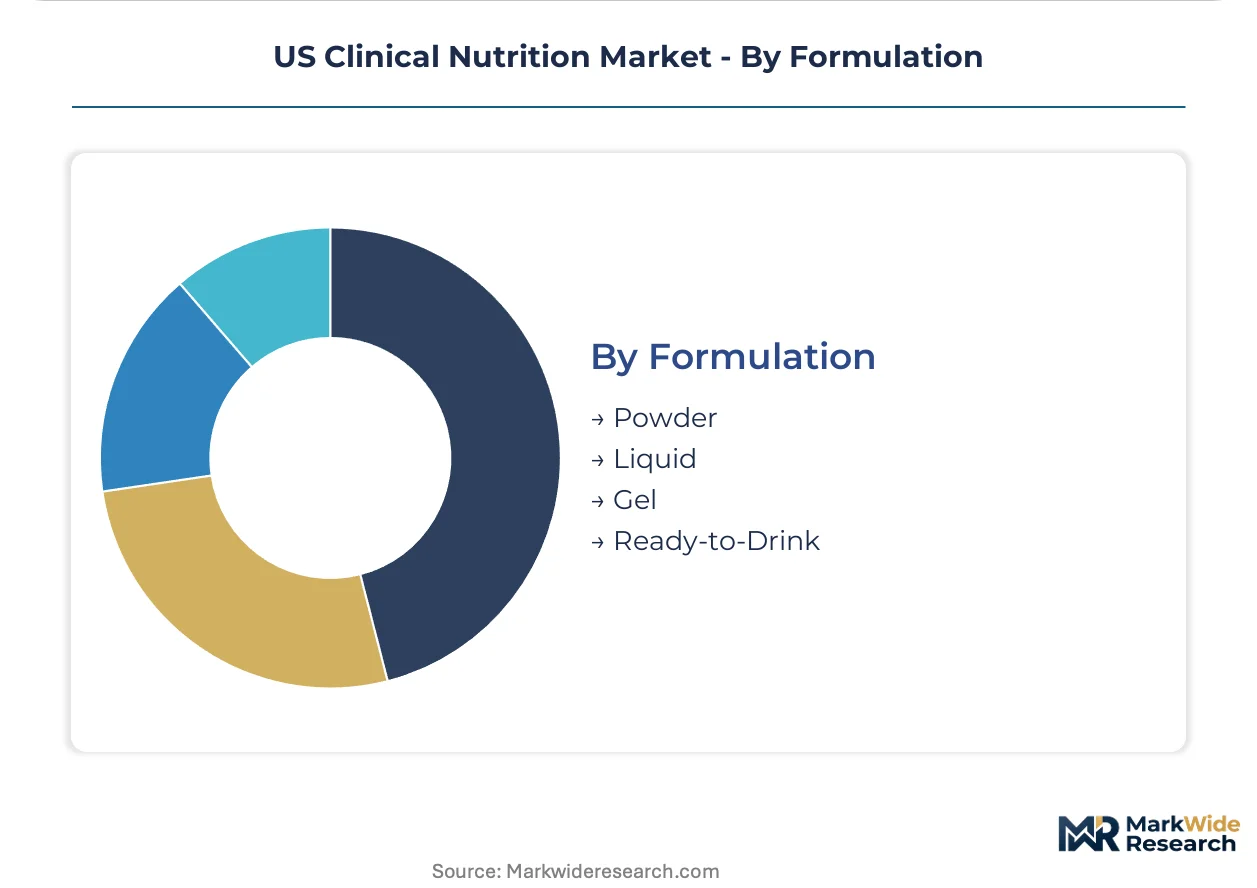
Formulation:
Supply chain configuration and shelf stability requirements segment manufacturing economics between powder compounding and ready-to-drink convenience premiums.
- Liquid:Pre-mixed enteral formulas and parenteral solutions with standardized osmolality for immediate administration. Hospital formularies and home care agencies in Texas favor liquid enteral for reduced preparation error risk and streamlined nursing workflow.
- Ready-to-Drink:Oral nutritional supplements in single-serve packaging for ambulatory oncology and geriatric patients. Medicare Part D coverage expansion under IRA provisions is widening patient access to disease-specific ready-to-drink formulations in retail pharmacy channels.
- Powder:Reconstitutable enteral formulas and modular protein or carbohydrate additives for customized feeding regimens.
- Gel:Thickened oral supplements for dysphagia patients requiring modified texture consistency.
Liquid formulations hold the largest share; ready-to-drink products show the steepest expansion trajectory as retail pharmacy distribution scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US clinical nutrition market operates with minimal cross-border trade dependency, as formula production, compounding pharmacy networks, and enteral pump manufacturing concentrate domestically. Import flows center on specialty raw materials including amino acid precursors and lipid emulsion components from European chemical suppliers. Export activity remains limited to neighboring Canada and Mexico under USMCA pharmaceutical provisions.
Texas
Long-term care facilities in Houston and Dallas-Fort Worth anchor enteral nutrition volume, driven by Medicare Advantage penetration and senior population clustering. The Texas Department of Health and Human Services enforces skilled nursing nutrition service licensing that exceeds federal minimums. San Antonio medical centers coordinate discharge planning with home care agencies operating under single-source enteral contracts.
Florida
Aging demographics in Tampa Bay and South Florida concentrate demand for renal-specific formulas and dysphagia-thickened products. Florida's Agency for Health Care Administration regulates Medicaid managed care nutrition benefits with prior authorization requirements. Orlando gastroenterology practices prescribe hydrolyzed peptide formulas for malabsorption patients at rates exceeding national averages.
California
Pediatric gastroenterology practices in Los Angeles and San Francisco drive elemental formula demand for short bowel syndrome and inflammatory bowel disease. The California Department of Public Health imposes additional long-term care dietitian credentialing requirements that raise compliance costs for multi-state operators. Stanford and UCLA medical centers pilot remote enteral monitoring integration with home care discharge protocols.
Ohio
Medicare Advantage networks in Cleveland and Cincinnati consolidate vendor relationships into episode-based enteral nutrition contracts. The Ohio Department of Medicaid bundles oral nutritional supplements into managed care capitation rates. Columbus health systems coordinate hospital-to-home transitions through integrated pump leasing and nursing visit platforms.
Pennsylvania
Philadelphia and Pittsburgh academic medical centers anchor parenteral nutrition compounding volume for complex gastrointestinal failure. Pennsylvania Department of Health regulations require specialized pharmacy licensure for sterile admixture preparation that limits home infusion market entry. UPMC and Penn Medicine networks drive standardization of discharge planning documentation across enteral feeding protocols.
US Clinical Nutrition Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and compounding niches. The US clinical nutrition market consolidates around three to five national entities with captive pharmacy networks and pump distribution platforms, while regional compounding pharmacies and specialty formula manufacturers occupy fragmented upstream positions. Strategic archetypes span vertically integrated nutrition platforms, sterile compounding specialists, and disease-specific formulation innovators. Dominant competitive moves include hospital contract consolidation into single-source enteral agreements and backward integration into amino acid and lipid emulsion precursor supply.
Among diversified health science conglomerates, Abbott Laboratories and Nestle Health Science exemplify platform integrators with formula-to-pump coverage across institutional and home channels. Fresenius Kabi anchors the parenteral nutrition tier through captive sterile compounding networks and hospital pharmacy contracts. These three entities represent distinct strategic positions: Abbott occupies the home care enteral vector with equipment leasing integration, Nestle sits within disease-specific oncology and critical care formulation, and Fresenius exemplifies hospital-centric parenteral supply with vertical control over admixture preparation.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Reckitt Benckiser |
| Baxter International |
| Fresenius Kabi |
| B. Braun Melsungen |
| Nestle Health Science |
| Hero Nutritionals |
| Perrigo Company |
| Pfizer |
| Others |
Supply Flow & Price Mechanics
The Port of Houston corridor freight cost dynamics compress margins for enteral formula producers serving Texas long-term care facilities while amplifying price differentiation between captive pharmacy networks and independent distributors. CMS reimbursement compression feeds back into procurement consolidation, forcing regional providers toward single-source contracts that bundle formula, equipment, and nursing services under unified pricing.
Pricing Analysis
Hospital procurement committees anchor pricing structures around contract-based long-term offtake agreements with three-year renewal cycles. Price differentiation hinges on FDA medical food certification tier and after-sales service bundling intensity, with home care agencies commanding premium rates for 24-hour pump technical support. Cost compression in standard polymeric formulas is intensifying because Medicare Advantage plans in Ohio and Pennsylvania are consolidating vendor relationships into episode-based accountability models. Skilled nursing facilities demonstrate highest price sensitivity due to fixed per-diem reimbursement rates, while academic medical centers exhibit lowest sensitivity given research funding offsets and complex patient acuity requirements.
Supply Chain Analysis
Sterile compounding capacity concentrates among three national pharmacy networks controlling parenteral admixture preparation, with Fresenius Kabi, Baxter International, and B. Braun Melsungen anchoring production across Illinois, Pennsylvania, and California facilities. Raw material dependencies center on amino acid precursors sourced from European chemical suppliers, aluminum phosphate additives subject to mining supply disruptions, and lipid emulsion components manufactured in Germany and Switzerland. Single-source vulnerability in sterile filtration membrane supply creates concentration risk for home infusion pharmacy networks. Distribution runs through hospital pharmacy formularies for inpatient parenteral nutrition, while enteral formula flows through durable medical equipment suppliers and home care agency direct purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US clinical nutrition market functions as a service-attach opportunity where pump leasing platforms and remote monitoring subscriptions expand faster than underlying formula volume. Recurring revenue from enteral equipment technical support and telehealth tolerance assessment now exceeds hardware margin contribution for leading platform operators.
For Market Incumbents: Pre-empt displacement by asset-light entrants through backward integration into amino acid precursor supply and captive sterile compounding capacity expansion in Texas and Florida. Defend hospital contract positions by embedding remote patient monitoring capabilities into standard enteral service agreements before Medicare Advantage networks complete vendor consolidation. Counter margin pressure from CMS bundled payment pilots by reorganizing sales compensation around episode-based outcome metrics rather than product volume.
For New Entrants and Emerging Players: Pursue white-space opportunity in California pediatric gastroenterology practices where elemental formula demand outstrips specialized distribution capacity. Target nephrology outpatient clinics in Texas reorganizing procurement around Comprehensive Kidney Care Contracting value-based arrangements. Enter through telehealth-integrated pump leasing platforms that bypass capital barriers facing traditional home care agency entrants.
For Investors and Strategic Acquirers: Regional sterile compounding pharmacies with multi-state licensure and parenteral nutrition board-certified pharmacist staffing represent the priority acquisition archetype for platform integrators seeking hospital contract density. Long-term viability hinges on positioning for CMS site-of-care migration acceleration and IRA Medicare Part D oral supplement coverage expansion. Monitor FDA guidance evolution on personalized nutrition interventions as inflection indicator for specialty foods segment revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Remote Patient Monitoring Integration | Telehealth platforms paired with smart feeding pumps enable real-time tolerance assessment and formula adjustment for home care patients. |
| Single-Source Contract Consolidation | Medicare Advantage networks in Ohio and Pennsylvania demand episode-based cost accountability across formula, equipment, and nursing services. |
| Backward Integration into Precursor Supply | Abbott Laboratories and Nestle Health Science secure captive amino acid and lipid emulsion supply chains against raw material volatility. |
| California Licensing Harmonization | Streamlined multi-state credentialing for long-term care dietitians reduces compliance overhead for national operators expanding westward. |
| Oncology Supportive Care Protocol Embedding | Academy of Nutrition and Dietetics cachexia management guidelines embed oral nutritional supplements into standard cancer treatment pathways. |
Methodological Framework
Cross-validation between CMS Medicare claims data and hospital procurement database extracts anchors the qualitative findings from structured interviews with enteral nutrition service directors, home care agency operators, parenteral compounding pharmacists, and Medicare Advantage network contracting officers. Secondary validation draws from FDA medical food registration filings, state Department of Health licensing records, and GPO contract disclosure databases. Bottom-up demand modeling from county-level Medicare beneficiary demographics triangulates against top-down manufacturer revenue segmentation across product form and delivery channel.
Calibration against historical CMS reimbursement schedule revisions and site-of-care migration patterns informs the analytical framework across the projection horizon. Segmentation dimensions span product type, application, end user, and formulation with additional modeling of state-level regulatory cluster variation. CAGRs derive from fitted trend extrapolation adjusted for policy intervention timing and demographic shift velocity. Industry-specific forecast inputs include aluminum phosphate commodity price indices and enteral pump equipment leasing penetration rates.
Sensitivities concentrate around IRA Medicare price negotiation implementation pace, FDA personalized nutrition guidance publication timing, and home infusion pharmacy network consolidation velocity. Forecasts reflect documented assumptions regarding CMS bundled payment pilot geographic expansion and Medicare Advantage penetration trajectories. Quarterly review of state Department of Health licensing enforcement patterns and GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Maternal Nutrition Products Market