
 Canada Clinical Nutrition Market | 2026-2036
Canada Clinical Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Clinical Nutrition Market Insights
Asset-light leasing models for enteral feeding pumps are reshaping how smaller homecare providers access clinical nutrition equipment without capital-intensive purchases. Fresenius Kabi AG leverages its hospital infusion technology heritage to compete in parenteral nutrition compounding services. Abbott Laboratories anchors its position through extensive outpatient clinic partnerships that sustain recurring formula demand. Nestle S.A. dominates pediatric specialty nutrition through deep shelf presence in Canadian children's hospitals.
Clinical nutrition encompasses medically prescribed formulations designed to deliver complete or supplemental macronutrient and micronutrient support to patients unable to meet requirements through conventional diet, typically manufactured under sterile conditions with protein concentrations ranging from ten to twenty percent for standard enteral solutions. Its primary purpose spans malnutrition intervention, metabolic disorder management, and perioperative recovery support across acute and chronic care pathways. Enteral nutrition leads product type revenue due to lower complication rates and earlier hospital discharge protocols, while parenteral nutrition commands premium positioning in intensive care and intestinal failure segments where intravenous delivery remains unavoidable. Homecare application growth outpaces institutional channels as provincial health authorities expand reimbursement for domestic infusion therapy, though hospitals retain the largest absolute volume through centralized procurement contracts.
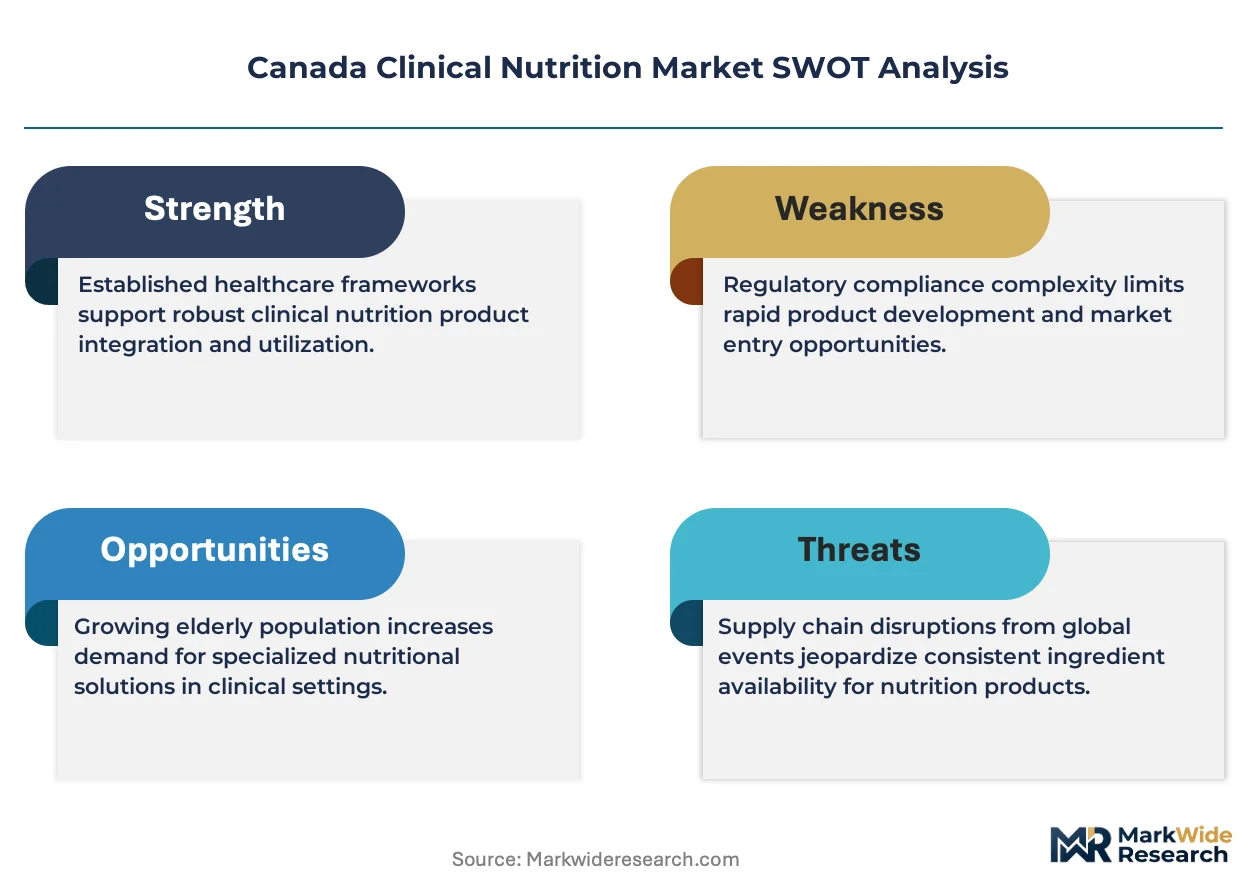
Health Canada and the Canadian Food Inspection Agency jointly govern medical food labeling and novel ingredient approvals, creating compliance thresholds that favor established manufacturers with dedicated regulatory affairs teams. Provincial formularies administered by bodies such as Ontario's Ministry of Health determine reimbursement eligibility, directly shaping product access and prescribing patterns across jurisdictions. Stakeholders must monitor evolving standards for plant-based protein fortification and personalized nutrition algorithms as these domains attract both venture investment and regulatory scrutiny.
Market Dynamics
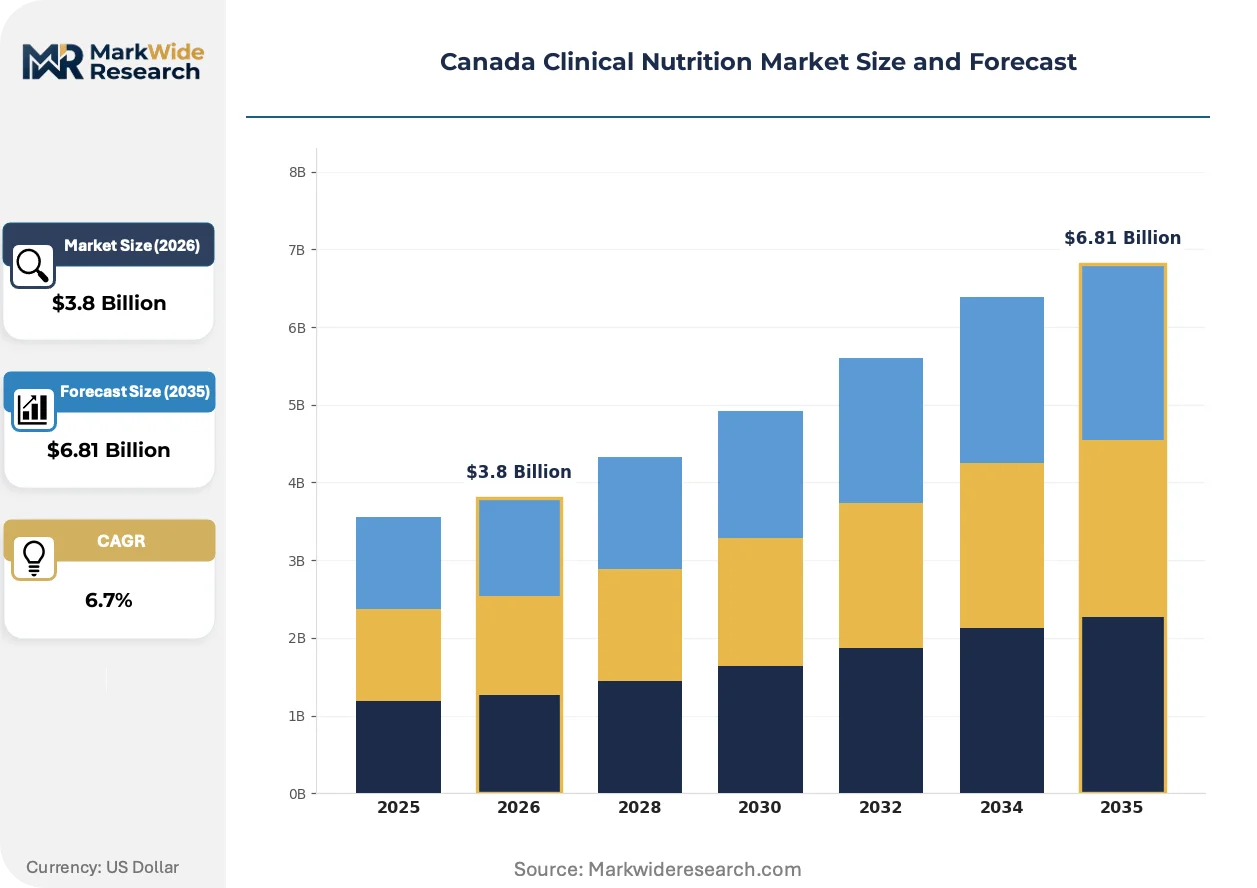
Provincial reimbursement expansion for home-based enteral therapy is compressing hospital-centric procurement models while fragmenting demand across domestic infusion networks. Health Canada's tightening medical food classification standards are simultaneously elevating compliance costs and disqualifying smaller formula importers from formulary access.
Growth Catalysts
- Homecare Reimbursement Expansion:Ontario's Ministry of Health and British Columbia's PharmaCare have broadened coverage for enteral feeding pumps and formula in domestic settings, diverting patient volume from acute care facilities.
- Aging Demographics in Long-Term Care:Quebec and Alberta are experiencing concentrated demand for specialized malnutrition interventions as their long-term care resident populations expand.
- Enteral Feeding Technology Miniaturization:Portable pump systems with programmable flow rates are enabling safer patient discharge and sustaining formula consumption outside institutional walls.
Market Restraints
- Whey Protein Isolate Supply Concentration:Canadian formulators remain dependent on North American dairy processing clusters for high-purity protein inputs, exposing margins to agricultural commodity volatility.
- PMRA Novel Ingredient Review Timelines:Health Canada's Pest Management Regulatory Agency and Food Directorate jointly extend approval cycles for plant-derived fortification compounds, delaying product launches by 18-24 months.
- Parenteral Compounding Infrastructure Limits:Sterile intravenous nutrition admixture requires ISO Class 5 cleanroom facilities that few regional hospitals outside Toronto, Montreal, and Calgary maintain.
Strategic Opportunities
- Remote Patient Monitoring Integration:Telehealth platforms paired with connected feeding pumps enable real-time tolerance assessment and formula adjustment across rural Manitoba and Saskatchewan.
- Pediatric Metabolic Disorder Specialization:Inherited metabolic disease centers in Ontario and Quebec generate recurring demand for custom amino acid profiles that standard formulas cannot address.
- Provincial Formulary Harmonization Pressure:Interprovincial health ministerial councils are negotiating standardized medical food reimbursement codes that would reduce jurisdictional fragmentation for national suppliers.
Industry Challenges
- Clinical Dietitian Workforce Constraints:Specialized certification in enteral and parenteral prescription remains concentrated in major urban teaching hospitals, limiting rural homecare program expansion.
- Legacy Hospital Information System Integration:Electronic medical record platforms in older Quebec facilities lack interoperability with automated feeding pump documentation, forcing manual reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Clinical Nutrition Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enteral Nutrition, Parenteral Nutrition, Specialty Products, Nutraceuticals Application: Hospitals, Homecare, Long-term Care, Outpatient Clinics End User: Healthcare Providers, Patients, Caregivers, Nutritional Support Centers Form: Liquid, Powder, Semi-solid, Ready-to-use |
| Companies Covered | Nestle S.A., Abbott Laboratories, Danone S.A., Baxter International Inc., Fresenius Kabi AG, Mead Johnson Nutrition Company, Bayer AG, Nutricia North America, Otsuka Pharmaceutical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Clinical Nutrition Market Trends and Innovations
Digital connectivity and protein diversification are converging to transform how clinical nutrition is prescribed, monitored, and reimbursed across Canadian care pathways.
Smart enteral feeding pumps with embedded sensors and cloud-based reporting capabilities are collapsing the information gap between hospital discharge and homecare follow-up. Ontario's Community Care Access Centres are deploying these devices to reduce emergency readmissions among recently discharged gastrointestinal surgery patients. Real-time tolerance data flows directly to hospital dietitians, compressing the response window for formula intolerance events from days to hours.
Health Canada's evolving medical food classification standards are mandating granular amino acid disclosure and allergen traceability that exceeds conventional food labeling requirements. Manufacturers must now submit complete supply chain documentation for novel protein sources such as pea isolate and algae-derived lipids. Pediatric specialty formulas face the tightest scrutiny, with children's hospitals in Toronto and Montreal demanding batch-level certificates of analysis before formulary inclusion.
Buying committees at provincial health authorities are consolidating formula procurement through centralized tender processes that unbundle pump leasing from consumable supply. Alberta Health Services and Vancouver Coastal Health have shifted to multi-year sole-source agreements with performance guarantees for delivery reliability and patient outcome metrics. This concentration rewards suppliers with national distribution networks and disqualifies regional importers lacking inventory depth.
Canada Clinical Nutrition Market Segmentation
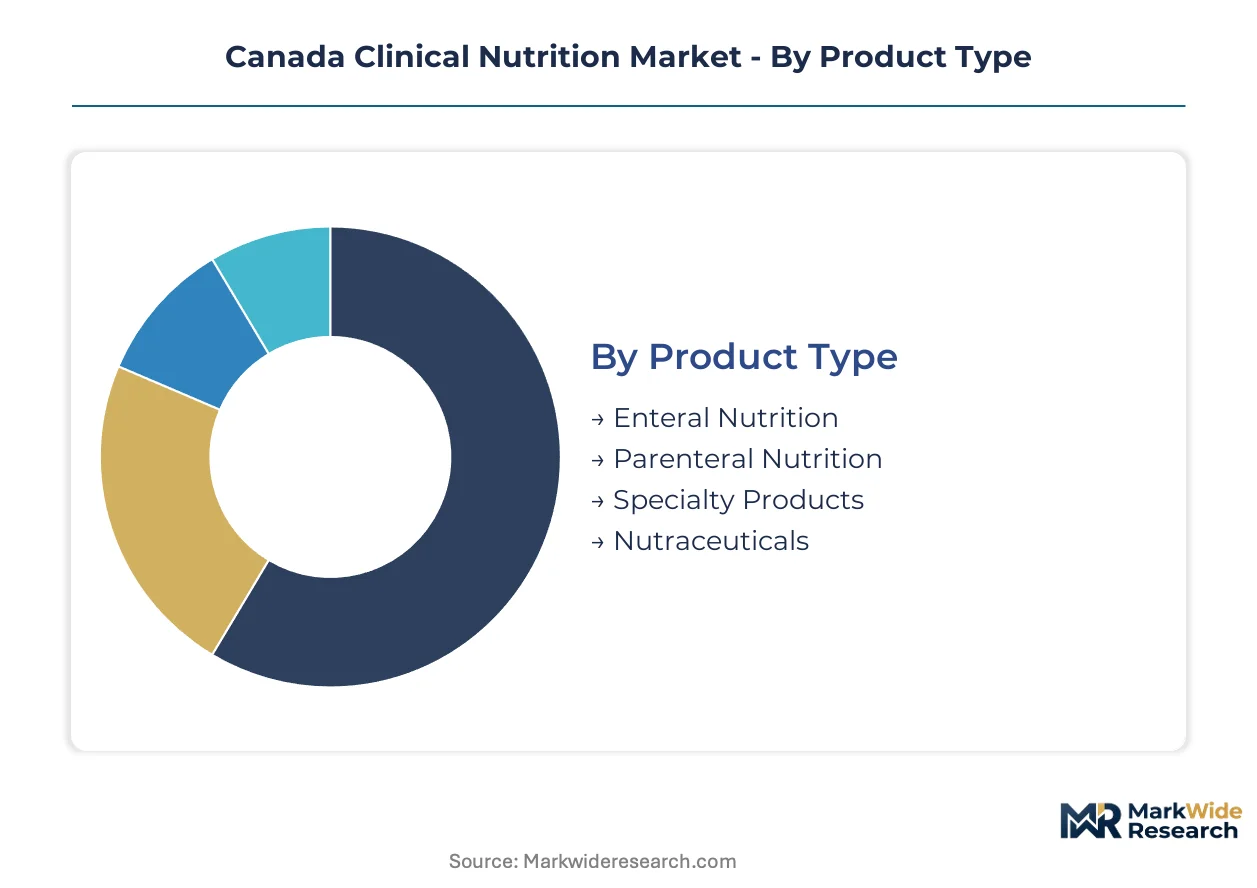
Segmentation in Canada's clinical nutrition market reveals how reimbursement policy, care setting economics, and patient mobility reshape demand patterns across provincial health systems. Understanding these dimensions exposes where formulary access concentrates and which product formats align with homecare expansion timelines.
Product Type:
Cost tier differentiation separates commodity formulations from premium-positioned therapeutic nutrition, with reimbursement codes directly mapping to protein concentration and clinical indication specificity.
- Enteral Nutrition:Standard and disease-specific polymeric formulas deliver ten to twenty percent protein through nasogastric or gastrostomy tubes. Ontario's Community Care Access Centres and British Columbia's PharmaCare reimbursement expansion are accelerating pump-and-formula leasing for post-surgical patients discharged to domestic settings.
- Parenteral Nutrition:Sterile intravenous admixtures combining dextrose, amino acids, and lipids bypass compromised gastrointestinal tracts entirely. Demand clusters in Toronto, Montreal, and Calgary tertiary centers where ISO Class 5 cleanroom infrastructure supports compounding for intestinal failure and critical care patients.
- Specialty Products:Disease-specific formulations target inherited metabolic disorders, renal failure, and hepatic insufficiency with modified electrolyte and micronutrient profiles.
- Nutraceuticals:Medical food classifications governed by Health Canada and the Canadian Food Inspection Agency bridge conventional supplements and prescription nutrition.
Enteral Nutrition holds installed capacity. Specialty Products is rotating up the share rankings.
Application:
Geography determines application priority, with provincial health authority procurement centralization fragmenting demand across domestic infusion networks and institutional contracts.
- Hospitals:Acute care facilities in Quebec and Alberta maintain the largest absolute formula volume through centralized tender processes. Buying committees at Alberta Health Services and Vancouver Coastal Health unbundle pump leasing from consumable supply, demanding performance guarantees for delivery reliability.
- Homecare:Portable pump systems with programmable flow rates enable safer patient discharge and sustain formula consumption outside institutional walls. Ontario's Ministry of Health reimbursement broadening diverts gastrointestinal surgery recovery from acute beds to domestic settings.
- Long-term Care:Aging demographics in Quebec and Alberta generate concentrated demand for specialized malnutrition interventions among residents with dysphagia and cognitive impairment.
- Outpatient Clinics:Recurring formula demand sustains through extensive clinic partnerships that anchor patient compliance and prescriber relationships.
Hospitals retain procurement concentration. Homecare is gaining share fastest.
End User:
Customer type stratification reflects who controls prescribing authority, reimbursement submission, and adherence monitoring across care transitions.
- Healthcare Providers:Hospital dietitians, gastroenterologists, and surgeons initiate prescriptions and manage tolerance protocols. Specialized certification in enteral and parenteral prescription remains concentrated in major urban teaching hospitals, constraining rural program expansion.
- Patients:Self-administering homecare recipients depend on telehealth platforms paired with connected feeding pumps for real-time tolerance assessment across rural Manitoba and Saskatchewan.
- Caregivers:Family members and home health aides execute feeding schedules and pump maintenance in domestic settings.
- Nutritional Support Centers:Dedicated facilities coordinate complex parenteral compounding and metabolic monitoring for intestinal failure populations.
Healthcare Providers anchor prescribing volume. Patients are climbing the fastest as homecare reimbursement expands.
Form:
Volume and handling characteristics determine which formats suit institutional bulk preparation versus individual patient portability requirements.
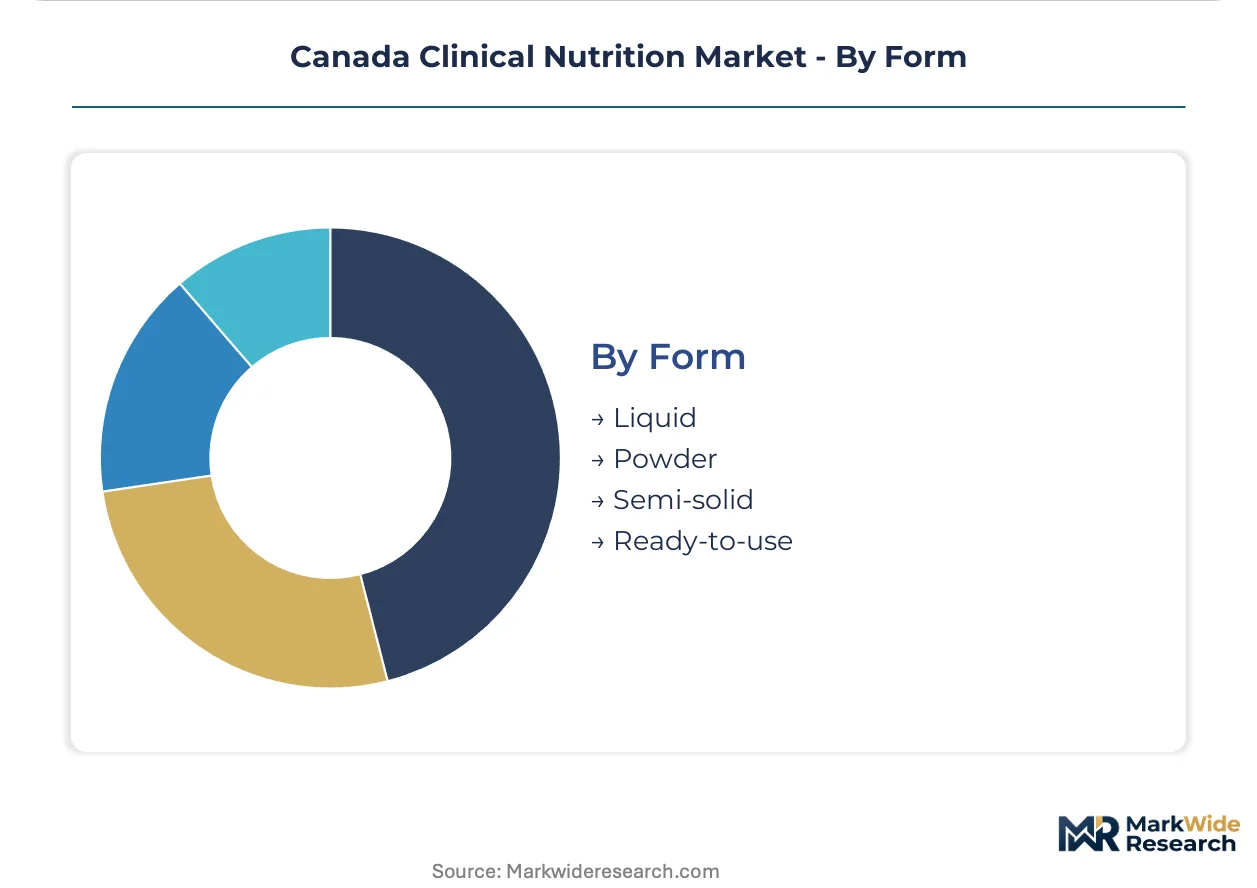
- Liquid:Pre-mixed solutions in ready-to-hang containers dominate hospital and long-term care where refrigeration and pump compatibility are assured. Health Canada's tightening medical food classification standards mandate granular amino acid disclosure that elevates compliance documentation for liquid manufacturers.
- Powder:Reconstitutable formulations reduce shipping weight and storage footprint for homecare patients managing limited refrigerator space. Demand concentrates where provincial formularies reimburse powder-to-liquid preparation as equivalent to pre-mixed alternatives.
- Semi-solid:Pudding-thick preparations serve dysphagia patients requiring modified texture consistency.
- Ready-to-use:Single-serve containers eliminate preparation error risk and support travel mobility for active homecare patients.
Liquid maintains formulary dominance. Ready-to-use is expanding most quickly among mobile homecare populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's clinical nutrition trade flows reflect domestic manufacturing concentration against import dependence for specialized formulations. Provincial procurement centralization creates distinct sub-regional demand patterns across five key areas.
Ontario
Toronto's hospital network drives the largest absolute formula volume through centralized tender processes. Ontario's Ministry of Health reimbursement expansion for home-based enteral therapy diverts gastrointestinal surgery recovery from acute beds to domestic settings. Community Care Access Centres deploy smart feeding pumps with cloud-based reporting across the Greater Toronto Area.
Quebec
Montreal's tertiary centers maintain ISO Class 5 cleanroom infrastructure for parenteral nutrition compounding. Aging demographics in long-term care facilities generate concentrated demand for specialized malnutrition interventions. Health Canada's bilingual labeling requirements elevate compliance documentation for formula manufacturers serving this market.
Alberta
Calgary anchors intestinal failure treatment capacity with dedicated nutritional support centers. Alberta Health Services consolidates procurement through multi-year sole-source agreements demanding performance guarantees for delivery reliability. Edmonton clusters pediatric metabolic disorder specialization with recurring demand for custom amino acid profiles.
British Columbia
Vancouver Coastal Health unbundles pump leasing from consumable supply in centralized tender processes. PharmaCare reimbursement broadening accelerates homecare adoption of portable enteral feeding systems. Victoria's aging population drives long-term care demand for dysphagia-appropriate formulations.
Manitoba and Saskatchewan
Rural homecare networks depend on telehealth platforms paired with connected feeding pumps for real-time tolerance assessment. Winnipeg and Saskatoon anchor regional distribution for powder formulations reducing shipping weight to remote communities. Provincial formularies reimburse powder-to-liquid preparation as equivalent to pre-mixed alternatives.
Canada Clinical Nutrition Market Competitive Landscape
On the supply side, the industry is consolidating around multinational pharmaceutical-nutrition conglomerates with dedicated regulatory affairs teams. Tiered competitive positioning separates hospital-centric formula suppliers from homecare-focused pump-and-consumable integrators. Three archetypes dominate: diversified healthcare conglomerates with infusion technology heritage, pediatric specialty nutrition specialists with deep hospital shelf presence, and regional compounding services with sterile admixture capabilities. Dominant competitive moves include provincial formulary harmonization lobbying and asset-light leasing model deployment for capital-constrained homecare providers.
Among Switzerland-based and US-based healthcare conglomerates, Nestle S.A., Abbott Laboratories, and Fresenius Kabi AG exemplify contrasting strategic positions. Nestle S.A. occupies a position anchored in pediatric specialty nutrition through children's hospital formulary dominance. Abbott Laboratories represents the outpatient clinic partnership model sustaining recurring formula demand across provincial networks. Fresenius Kabi AG sits within the parenteral compounding tier, leveraging hospital infusion technology heritage for sterile intravenous nutrition services.
| Leading Market Players |
|---|
| Nestle S.A. |
| Abbott Laboratories |
| Danone S.A. |
| Baxter International Inc. |
| Fresenius Kabi AG |
| Mead Johnson Nutrition Company |
| Bayer AG |
| Nutricia North America |
| Otsuka Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
The Great Lakes freight corridor's refrigerated container rates directly compress margins for whey protein isolate shipments moving from Wisconsin dairy processing clusters to Toronto formulation facilities, concentrating pricing power among manufacturers with captive cold-chain infrastructure while forcing smaller compounders toward powder-based alternatives that reduce transport cost exposure.
Pricing Analysis
Provincial health authority buyers anchor contract-based pricing through multi-year sole-source agreements that unbundle pump leasing from formula supply. Three-tier pricing structure across premium therapeutic, standard polymeric, and economy modular levels reflects Health Canada certification tier and amino acid disclosure granularity. Cost compression in standard enteral formulas is intensifying as Alberta Health Services and Vancouver Coastal Health consolidate procurement volumes. Long-term care facilities exhibit highest price sensitivity due to fixed per-resident nutrition budgets, while pediatric metabolic centers show lowest sensitivity given custom formulation requirements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier financing arrangements as multinational nutrition conglomerates leverage balance sheet depth against regional compounders. Manufacturing concentrates in the United States, Germany, and Switzerland for sterile parenteral admixtures, while Canada hosts limited ISO Class 5 cleanroom capacity. Raw material inputs draw from North American dairy processing for whey isolates, European lipid sources, and Asian amino acid precursors. Single-source vulnerability concentrates in parenteral lipid emulsions where few global suppliers meet Health Canada standards. Distribution runs through provincial health authority central warehouses to hospital networks and homecare infusion providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's tightening medical food classification standards constitute a regulatory inflection that will disqualify importers lacking batch-level traceability infrastructure, compressing viable supplier ranks while amplifying returns for compliant incumbents.
For Market Incumbents: Build formulary lock-in moats through exclusive Ontario Community Care Access Centre partnerships that embed smart pump technology with recurring formula subscriptions. Expand captive ISO Class 5 cleanroom capacity in Calgary and Montreal to capture parenteral compounding demand from intestinal failure centers. Counter emerging regional compounders by pre-empting provincial reimbursement code harmonization through early Health Canada novel ingredient dossier submissions. For New Entrants and Emerging Players: Pursue remote patient monitoring integration for rural Manitoba and Saskatchewan homecare networks where telehealth platforms paired with connected feeding pumps remain underdeployed. Target pediatric metabolic disorder specialization in Edmonton and Quebec City where custom amino acid profile demand exceeds current supplier capacity. Deploy asset-light leasing models for enteral feeding pumps to bypass capital barriers facing smaller homecare providers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core nutrition assets amid portfolio rationalization pressures. Five-to-ten year viability favors suppliers with Health Canada regulatory affairs teams and provincial formulary penetration across multiple jurisdictions. Monitor interprovincial health ministerial council negotiations for standardized reimbursement codes as signal of consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Provincial Formulary Harmonization Lobbying | Standardized reimbursement codes would reduce jurisdictional fragmentation for national suppliers. |
| Remote Patient Monitoring Integration | Telehealth platforms paired with connected feeding pumps enable real-time tolerance assessment across rural networks. |
| Pediatric Metabolic Disorder Specialization | Custom amino acid profiles for inherited metabolic disease centers generate recurring demand beyond standard formulas. |
| Asset-Light Pump Leasing Deployment | Leasing models reshape how smaller homecare providers access equipment without capital-intensive purchases. |
| ISO Class 5 Cleanroom Capacity Expansion | Sterile intravenous nutrition admixture infrastructure concentrates in Toronto, Montreal, and Calgary tertiary centers. |
Research Methodology
Cross-validation between hospital procurement database analysis and Health Canada medical food registration records anchors the qualitative findings on formulary access patterns. Primary interviews with hospital dietitians, GPO contracts managers, provincial health authority buying committee members, and homecare infusion coordinators combined with secondary validation from Health Canada filings, provincial formulary databases, and hospital tender documentation. Bottom-up patient volume modeling and top-down provincial health expenditure triangulation produced convergent estimates.
Calibration against historical reimbursement expansion timelines and cleanroom infrastructure deployment cycles shaped the projection framework. Segmentation dimensions modeled include product type, application setting, end user category, and provincial regulatory cluster across the analysis window. CAGRs derived from compound growth mechanics applied to baseline expenditure figures. Forecast inputs incorporated aging demographic trajectories in Quebec and Alberta long-term care facilities alongside homecare reimbursement policy momentum in Ontario and British Columbia.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational nutrition conglomerates seeking vertical integration into parenteral lipid manufacturing would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Nutrition Apps Market