
 United States Specialty Generics Market | 2026-2036
United States Specialty Generics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Specialty Generics Market Intelligence
Complex injectable specifications are redrawing competitive boundaries in the United States Specialty Generics Market. Teva Pharmaceuticals USA leverages vertical integration across active pharmaceutical ingredient and finished dosage form production to control supply security for high-barrier generics. Viatris anchors its position through sustained R&D intensity in respiratory and biosimilar portfolios. Hikma Pharmaceuticals specializes in sterile injectable capacity, occupying a narrow but defensible manufacturing niche.
United States specialty generics comprise chemically equivalent versions of branded drugs with complex formulations, delivery mechanisms, or narrow therapeutic indices, including long-acting injectables requiring aseptic manufacturing under ISO 5 cleanroom conditions and bioequivalence studies following FDA guidance for pharmacokinetic endpoints. Their primary purpose is to reduce pharmaceutical expenditure while maintaining therapeutic equivalence for chronic and acute conditions previously served by single-source innovators. Injectable formulations lead volume contribution due to manufacturing complexity that limits competitor entry and preserves margin pools, while biosimilars represent the fastest-expanding category as FDA interchangeability designations accelerate payer substitution policies. Oncology therapy areas command the deepest demand concentration, driven by hospital formulary mandates and Medicare reimbursement structures that favor generic utilization in infused chemotherapy regimens.
FDA abbreviated new drug application pathways and USP monograph standards govern product approval and quality verification, with the 340B Drug Pricing Program shaping hospital purchasing incentives for specialty generic uptake. State-level pharmacy substitution laws and FDA Risk Evaluation and Mitigation Strategy requirements further determine market access speed and prescriber confidence in therapeutic equivalence. Stakeholders must monitor FDA guidance revisions on complex generic bioequivalence methodologies and state Medicaid preferred drug list negotiations to anticipate margin compression windows and portfolio reallocation priorities.
Market Dynamics
Hospital formulary mandates and the 340B Drug Pricing Program are compressing substitution timelines for infused oncology generics, forcing manufacturers to secure FDA abbreviated new drug application approvals ahead of patent cliffs to capture formulary slots.
Growth Catalysts
- FDA abbreviated new drug pathways:Streamlined bioequivalence guidance for complex injectables accelerates market entry for high-barrier formulations previously served by single-source innovators.
- Oncology center density in Texas and Florida:Concentrated cancer treatment infrastructure creates localized demand pull for sterile injectable generics with rapid formulary adoption cycles.
- Medicare reimbursement structures:Favorable ASP-plus reimbursement for generic infused chemotherapy drives hospital procurement preference toward therapeutic equivalents.
Market Restraints
- Active pharmaceutical ingredient supply concentration:Reliance on offshore API manufacturers creates vulnerability to import delays and quality enforcement actions.
- ISO 5 cleanroom capex requirements:Aseptic manufacturing infrastructure demands substantial capital deployment with extended depreciation timelines.
- FDA Risk Evaluation and Mitigation Strategy complexity:Shared-system REMS requirements for certain oncology generics impose coordination costs with reference product sponsors.
Strategic Opportunities
- Interchangeable biosimilar designations:FDA interchangeability standards enable automatic substitution at the pharmacy level, expanding addressable market for biosimilar portfolios.
- Specialty pharmacy infrastructure expansion:Hub-and-spoke distribution models in underserved metropolitan areas reduce cold-chain logistics friction for temperature-sensitive injectables.
- 340B contract pharmacy networks:Eligible entity expansion creates new channel access points for disproportionate share hospitals serving high-volume oncology populations.
Industry Challenges
- Sterile manufacturing workforce scarcity:Aseptic technique certification and cGMP compliance training programs face capacity constraints relative to facility expansion timelines.
- Bioequivalence study complexity:FDA guidance revisions for long-acting injectables require adaptive clinical trial designs with extended pharmacokinetic endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Specialty Generics Market |
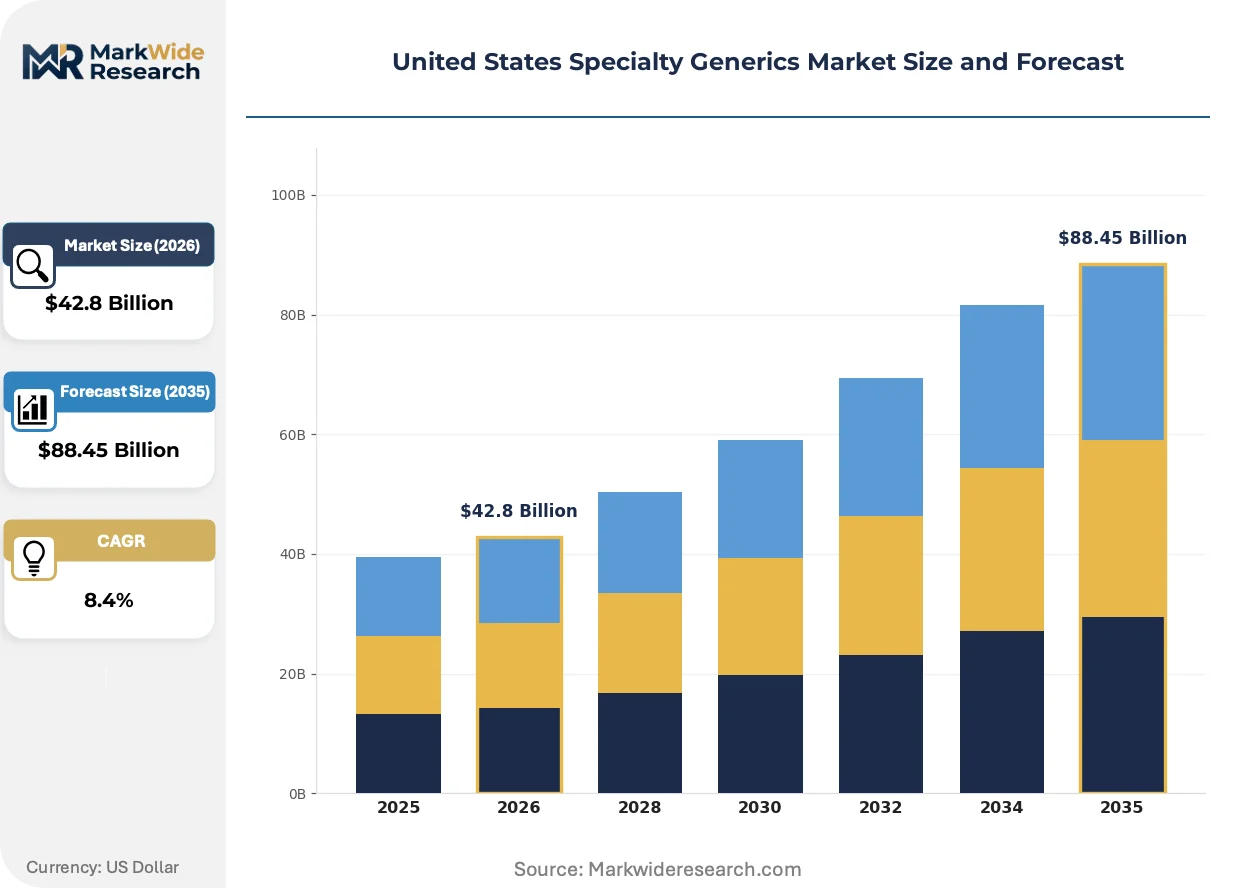
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $88.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Biosimilars, Topicals, Oral Solids End User: Pharmacies, Hospitals, Clinics, Wholesalers Distribution Channel: Retail, E-commerce, Hospital Pharmacies, Direct Sales Therapy Area: Oncology, Cardiovascular, Neurology, Endocrinology |
| Companies Covered | Teva Pharmaceuticals USA, Viatris, Pfizer, Novartis AG, Hikma Pharmaceuticals, Dr. Reddy's Laboratories, Baxter International, Amneal Pharmaceuticals, Endo Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Specialty Generics Market Strategic Shifts & Innovations
Continuous manufacturing platforms and real-time release testing are compressing batch cycle times for sterile injectables, while FDA policy evolution on complex generic bioequivalence is reshaping competitive entry barriers.
Single-use bioreactor systems are miniaturizing aseptic production footprints for high-potency oncology generics. Contract development and manufacturing organizations in Massachusetts and North Carolina are adopting disposable flow paths to reduce cross-contamination risk during campaign switches. This technology is miniaturizing minimum viable batch sizes, enabling economically viable production of narrow-therapeutic-index injectables with limited demand forecasts.
FDA draft guidance on in vivo bioequivalence alternatives for certain complex generics is expanding the acceptable evidence base for abbreviated new drug applications. The agency's emphasis on physiologically-based pharmacokinetic modeling reduces reliance on clinical endpoint studies for some long-acting formulations. Oncology injectables with established IVIVC correlations are the primary beneficiaries, with sponsors in California and New Jersey advancing model-informed drug development submissions.
Hospital purchasing consortiums are consolidating specialty generic sourcing through single-source agreements with price protection clauses. Group purchasing organizations are displacing direct manufacturer contracts for high-volume chemotherapy generics, concentrating procurement leverage among three dominant intermediaries. Texas Medical Center and MD Anderson Cancer Center procurement patterns demonstrate this consolidation most visibly, with formulary committees prioritizing total cost of acquisition over per-unit pricing.
United States Specialty Generics Market Segmentation

Specialty generics segmentation reveals how manufacturing complexity, reimbursement pathways, and clinical infrastructure concentrate margin pools across distinct product and channel configurations. Understanding these divides enables manufacturers to prioritize pipeline investments and distribution partnerships.
Product Type:
Margin pools concentrate in formulations requiring aseptic manufacturing and bioequivalence validation, where technical barriers limit competitor entry and preserve pricing power.
- Injectables:Sterile formulations demanding ISO 5 cleanroom production and complex pharmacokinetic equivalence studies command the deepest margin retention. Hospital procurement in Texas and Florida cancer centers drives concentrated demand for infused chemotherapy generics with rapid formulary adoption cycles.
- Biosimilars:FDA interchangeability designations enable automatic pharmacy-level substitution, expanding addressable markets for reference biologics approaching patent expiry. Medicare reimbursement structures favoring therapeutic equivalents accelerate hospital uptake in oncology and immunology.
- Topicals:Transdermal and dermal formulations with semi-solid manufacturing requirements serve dermatology and pain management segments.
- Oral Solids:Modified-release tablets and capsules face compressed margins due to lower technical barriers and extensive generic competition.
The dominant share belongs to Injectables, while Biosimilars is closing the gap fastest.
End User:
Customer concentration tracks directly to reimbursement leverage and formulary control mechanisms across the care continuum.
- Hospitals:340B Drug Pricing Program eligibility and ASP-plus reimbursement create procurement preference for infused oncology generics. Texas Medical Center and MD Anderson Cancer Center demonstrate concentrated purchasing power through single-source agreements with price protection clauses.
- Pharmacies:Specialty pharmacy infrastructure in Florida and California supports cold-chain distribution for temperature-sensitive biologics with hub-and-spoke logistics models.
- Clinics:Ambulatory infusion centers serve growing outpatient chemotherapy administration with limited formulary autonomy.
- Wholesalers:Three dominant intermediaries consolidate procurement leverage for high-volume chemotherapy generics, displacing direct manufacturer contracts.
Hospitals capture the largest volume share, though Pharmacies are expanding most quickly through specialty distribution networks.
Distribution Channel:
Channel selection determines cold-chain integrity requirements and margin capture through intermediation layers.
- Hospital Pharmacies:Direct procurement from group purchasing organizations minimizes distribution touchpoints for sterile injectables with narrow therapeutic indices. Formulary committees prioritize total cost of acquisition over per-unit pricing in consolidated sourcing agreements.
- Retail:Community pharmacy networks serve oral solid and topical generics with established generic substitution protocols under state-level pharmacy laws.
- E-commerce:Direct-to-patient platforms for specialty medications face REMS coordination requirements with reference product sponsors.
- Direct Sales:Manufacturer contracts with 340B eligible entities bypass wholesale markups for disproportionate share hospitals.
Hospital Pharmacies maintain channel dominance, while E-commerce is gaining traction fastest through patient convenience positioning.
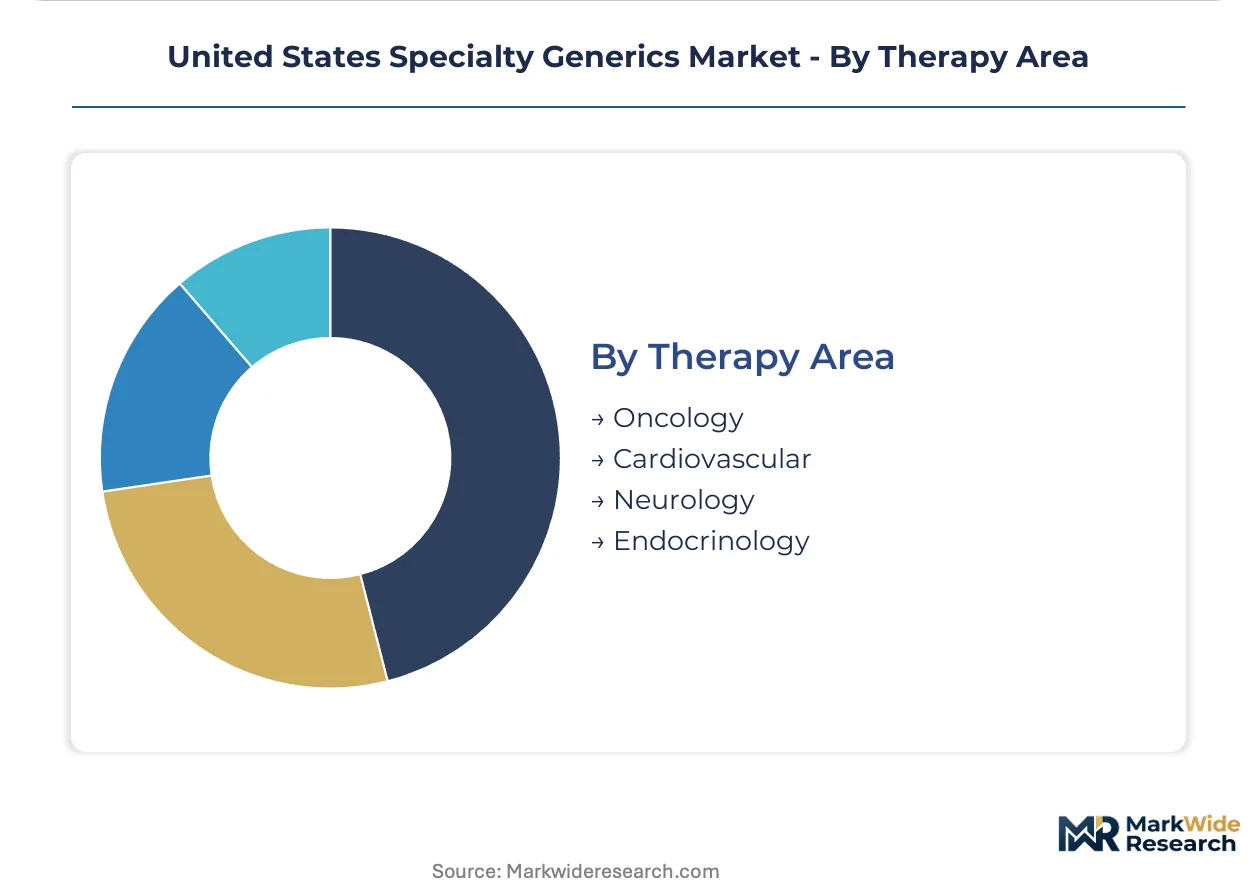
Therapy Area:
Clinical application segments align with disease prevalence, treatment infrastructure density, and Medicare reimbursement intensity.
- Oncology:Infused chemotherapy regimens command the deepest demand concentration through hospital formulary mandates and Medicare reimbursement structures favoring generic utilization. FDA abbreviated new drug pathways for complex injectables streamline approvals ahead of patent cliffs.
- Cardiovascular:Oral anticoagulants and antihypertensives face extensive generic competition with compressed margins despite high prescription volumes.
- Neurology:Long-acting injectables for schizophrenia and multiple sclerosis require aseptic manufacturing and extended pharmacokinetic endpoint studies.
- Endocrinology:Insulin biosimilars and GLP-1 receptor agonist equivalents represent emerging substitution opportunities as interchangeability standards evolve.
Oncology holds the dominant position, while Endocrinology is climbing the fastest on biosimilar pipeline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Specialty Generics Market operates as a net importer of active pharmaceutical ingredients while maintaining substantial finished dosage form production capacity. Regional demand clusters reflect cancer center density, 340B hospital concentration, and specialty pharmacy infrastructure distribution.
Texas
Texas Medical Center in Houston and MD Anderson Cancer Center drive concentrated procurement of sterile injectable oncology generics through single-source agreements with price protection clauses. The state's 340B disproportionate share hospital network creates substantial eligible entity volume for infused chemotherapy equivalents. Dallas-Fort Worth specialty pharmacy hubs support cold-chain distribution for temperature-sensitive biologics across the Southwest.
Florida
Moffitt Cancer Center and Sylvester Comprehensive Cancer Center anchor demand for complex injectable generics with rapid formulary adoption cycles. Florida's Medicare Advantage penetration exceeds national averages, accelerating therapeutic substitution in oncology and immunology. Miami and Tampa Bay specialty pharmacy infrastructure employs hub-and-spoke logistics models for last-mile delivery of narrow-therapeutic-index formulations.
California
University of California medical centers and Stanford Health Care generate demand for biosimilars with FDA interchangeability designations. The state's biosimilar substitution legislation enables automatic pharmacy-level exchange for qualifying products. San Diego and San Francisco Bay Area contract development and manufacturing organizations advance model-informed drug development submissions under FDA draft guidance.
Massachusetts
Massachusetts General Hospital and Dana-Farber Cancer Institute procurement committees prioritize total cost of acquisition over per-unit pricing in consolidated sourcing agreements. The state's 340B eligible entity expansion includes community health centers serving high-volume oncology populations. Greater Boston contract manufacturing facilities adopt single-use bioreactor systems to reduce cross-contamination risk during campaign switches.
North Carolina
Duke Cancer Institute and UNC Lineberger Comprehensive Cancer Center drive formulary mandates for generic infused chemotherapy regimens. The state's Research Triangle Park concentration supports bioequivalence study execution with adaptive clinical trial designs. Durham and Raleigh sterile manufacturing facilities face workforce scarcity in aseptic technique certification relative to facility expansion timelines.
United States Specialty Generics Market Key Industry Players
Concentration sits with vertically integrated pharmaceutical conglomerates controlling active pharmaceutical ingredient supply and finished dosage form production. The market structure reflects tiered competition between global generics divisions of innovator companies, standalone specialty generic manufacturers, and contract development and manufacturing organizations. Three strategic archetypes dominate: API-integrated finished dose producers, sterile injectable specialists, and biosimilar-focused developers. Capacity expansion and portfolio diversification through oncology pipeline prioritization constitute the primary competitive moves.
Among API-integrated manufacturers, Teva Pharmaceuticals USA and Viatris occupy positions exemplifying backward integration into active pharmaceutical ingredient production. Hikma Pharmaceuticals represents the sterile injectable specialist archetype with concentrated manufacturing footprint. These three entities anchor the competitive structure, with Dr. Reddy's Laboratories and Amneal Pharmaceuticals sitting within the mid-tier portfolio diversification segment.
| Leading Market Players |
|---|
| Teva Pharmaceuticals USA |
| Viatris |
| Pfizer |
| Novartis AG |
| Hikma Pharmaceuticals |
| Dr. Reddy's Laboratories |
| Baxter International |
| Amneal Pharmaceuticals |
| Endo Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Offshore API sourcing replacing domestic active pharmaceutical ingredient production simultaneously redistributes supply geography toward India and China while compressing margin pools for finished dosage form manufacturers facing import delay risks and quality enforcement volatility.
Pricing Analysis
Hospital procurement committees anchor contract-based long-term offtake structures for sterile injectable generics, with price differentiation resting on FDA approval tier and volume scale commitments. Three-tier pricing separates interchangeability-designated biosimilars from standard generics and economy oral solids. Cost compression in oncology injectables is intensifying because group purchasing organizations consolidate sourcing leverage. Safety-net hospitals under 340B eligibility demonstrate highest price sensitivity, while academic medical centers prioritize supply security over per-unit cost.
Supply Chain Analysis
Inventory buffers for temperature-sensitive biologics extend lead times for cold-chain distribution networks serving Texas and Florida cancer centers. Active pharmaceutical ingredient supply concentrates in India and China, with finished dosage form production anchored in North Carolina and Massachusetts facilities. Sterile manufacturing rests on single-use bioreactor systems, aseptic fill-finish equipment, and validated cleanroom infrastructure. Single-source vulnerability pervades high-potency oncology API categories. Distribution runs through three dominant wholesale intermediaries consolidating procurement leverage for hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Specialty Generics Market functions as a regulatory entrenchment story where FDA approval pathways and REMS coordination requirements create switching costs that protect incumbent positions.
For Market Incumbents: Fortify sterile manufacturing capacity in Research Triangle Park and Greater Boston corridors to preempt biosimilar entry waves. Secure backward integration into captive API supply for high-barrier oncology injectables facing Indian import inspection volatility. Prioritize FDA interchangeability designation submissions ahead of reference biologic patent cliffs. For New Entrants and Emerging Players: Anchor in 340B contract pharmacy networks serving disproportionate share hospitals in Dallas-Fort Worth and Miami metropolitan areas, the most penetrable channel for temperature-sensitive biologics with limited cold-chain infrastructure. Pursue hub-and-spoke distribution partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors sterile injectable specialists with ISO 5 cleanroom assets and established hospital formulary relationships. Long-term viability hinges on regulatory submission velocity and REMS program management capabilities. Monitor FDA draft guidance finalization on physiologically-based pharmacokinetic modeling as the signal to watch for bioequivalence study cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | ISO 5 cleanroom expansion in North Carolina addresses sterile workforce scarcity constraining batch output. |
| Regulatory Approval Pathway | FDA interchangeability designation submissions unlock automatic pharmacy substitution for biosimilar portfolios. |
| Backward Integration | Captive API production for oncology injectables mitigates Indian import inspection delay risks. |
| Strategic Partnership | 340B contract pharmacy network agreements create channel access for safety-net hospital procurement. |
| Pipeline Diversification | Long-acting injectable development in neurology extends aseptic manufacturing expertise beyond oncology. |
Research Approach
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration against FDA filing databases, CMS Medicare reimbursement data, 340B covered entity reports, and ClinicalTrials.gov records. Primary interviews with formulary directors and GPO contracts managers combined with secondary validation through SEC 10-K pharmaceutical disclosures and hospital procurement databases. Bottom-up volume modeling and top-down expenditure triangulation anchored market size estimation.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include product type, end user category, distribution channel configuration, and therapy area regulatory cluster. CAGRs derived from iterative growth rate convergence across demand-side forecasting and supply-side capacity assessment. Forecast inputs incorporated FDA approval timeline distributions and 340B eligible entity expansion trajectories.
Decision-makers should treat outputs as directional under stable FDA guidance interpretation and continued Medicare ASP-plus reimbursement structures; material deviation in interchangeability policy or 340B program scope would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Autosomal Dominant Polycystic Kidney Disease Treatment Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Neuromyelitis Optica Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market