
 Obesity Management Market | 2026-2036
Obesity Management Market Size, Share, and Industry Trends Forecast 2026-2036
Obesity Management Market Outlook
Bundle pricing of pharmacotherapy with nutritional counseling and remote monitoring is consolidating payer contracts and employer benefit designs. Novo Nordisk A/S leverages its manufacturing scale to secure preferred formulary tiers across major pharmacy benefit managers. Eli Lilly and Company differentiates through dual-hormone agonist platforms that extend its addressable patient population beyond diabetes overlap. WW International Inc. anchors its repositioning around clinician-referred behavioral programs, competing directly with digital therapeutics vendors for health plan contracts.
Obesity management encompasses pharmacological, surgical, and behavioral interventions targeting sustained reduction of adipose tissue mass and metabolic risk mitigation. GLP-1 and GIP receptor agonists function through delayed gastric emptying and central appetite suppression, requiring cold-chain distribution and subcutaneous administration protocols. Prescription drugs command the dominant margin pool as reimbursement frameworks expand, while bariatric surgical devices retain concentrated demand within tertiary hospital systems. Behavioral therapy segments through fitness centers and home care settings are capturing self-pay volume from patients excluded from prior authorization pathways.
The FDA's Risk Evaluation and Mitigation Strategy requirements for anti-obesity pharmacotherapy shape clinical trial design and post-market surveillance obligations for manufacturers. EMA's centralized marketing authorization procedures determine parallel entry timelines across EU member states, influencing capacity allocation for European launches. Payers and providers must monitor CMS Medicare coverage determinations and state Medicaid formulary decisions, as these will dictate accessible patient volumes and pricing power for injectable therapies across the United States.
Market Dynamics
GLP-1 receptor agonist manufacturing capacity constraints are reshaping competitive entry timelines and forcing pharmaceutical firms to prioritize cold-chain infrastructure investments over traditional marketing expenditures. This supply-side bottleneck is accelerating partnerships between drug developers and contract manufacturing organizations while compressing margin structures across the value chain.
Growth Catalysts
- Medicare Part D expansion:CMS coverage determinations for anti-obesity pharmacotherapy are unlocking accessible patient volumes among Medicare beneficiaries previously excluded from reimbursement pathways.
- Employer wellness program integration:Large self-insured employers in the United States are embedding pharmacotherapy benefits within diabetes prevention program frameworks, creating bundled demand pools.
- Cold-chain logistics maturation:Specialized distribution networks for temperature-sensitive biologics are reducing wastage rates and extending formulary placement feasibility into rural health systems.
Market Restraints
- Active pharmaceutical ingredient concentration:Peptide synthesis capacity remains concentrated among a handful of European and North American contract manufacturers, creating single-source vulnerabilities for GLP-1 agonist production.
- Medicaid formulary fragmentation:State-level prior authorization requirements vary across the United States, creating reimbursement patchworks that limit addressable populations in Medicaid expansion states versus non-expansion states.
- Subcutaneous administration barrier:Patient adherence rates for injectable therapies lag oral alternatives by substantial margins, compressing real-world effectiveness and payer value demonstration.
Strategic Opportunities
- Oral small-molecule development:Non-peptide GLP-1 receptor agonists in clinical pipelines promise to eliminate cold-chain dependencies and expand pharmacy dispensing into retail settings.
- India outpatient clinic networks:Private hospital chains and pharmacy retail formats in tier-2 and tier-3 Indian cities present underpenetrated channels for bariatric surgical device placement and post-operative care protocols.
- Digital therapeutics integration:FDA breakthrough device designation pathways for prescription digital therapeutics are enabling software-based behavioral interventions to secure formulary codes alongside pharmacotherapy.
Industry Challenges
- Specialized endocrinology workforce scarcity:Qualified obesity medicine physicians and certified bariatric nurses remain concentrated in academic medical centers, limiting patient throughput for comprehensive care models.
- Multi-site clinical trial complexity:FDA Risk Evaluation and Mitigation Strategy requirements mandate cardiovascular outcome trials spanning diverse demographic cohorts, extending development timelines and inflating study costs.
- Legacy electronic health record integration:Hospital systems struggle to embed obesity-specific diagnostic codes and automated BMI screening alerts into existing EHR workflows, delaying care pathway automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Obesity Management Market |
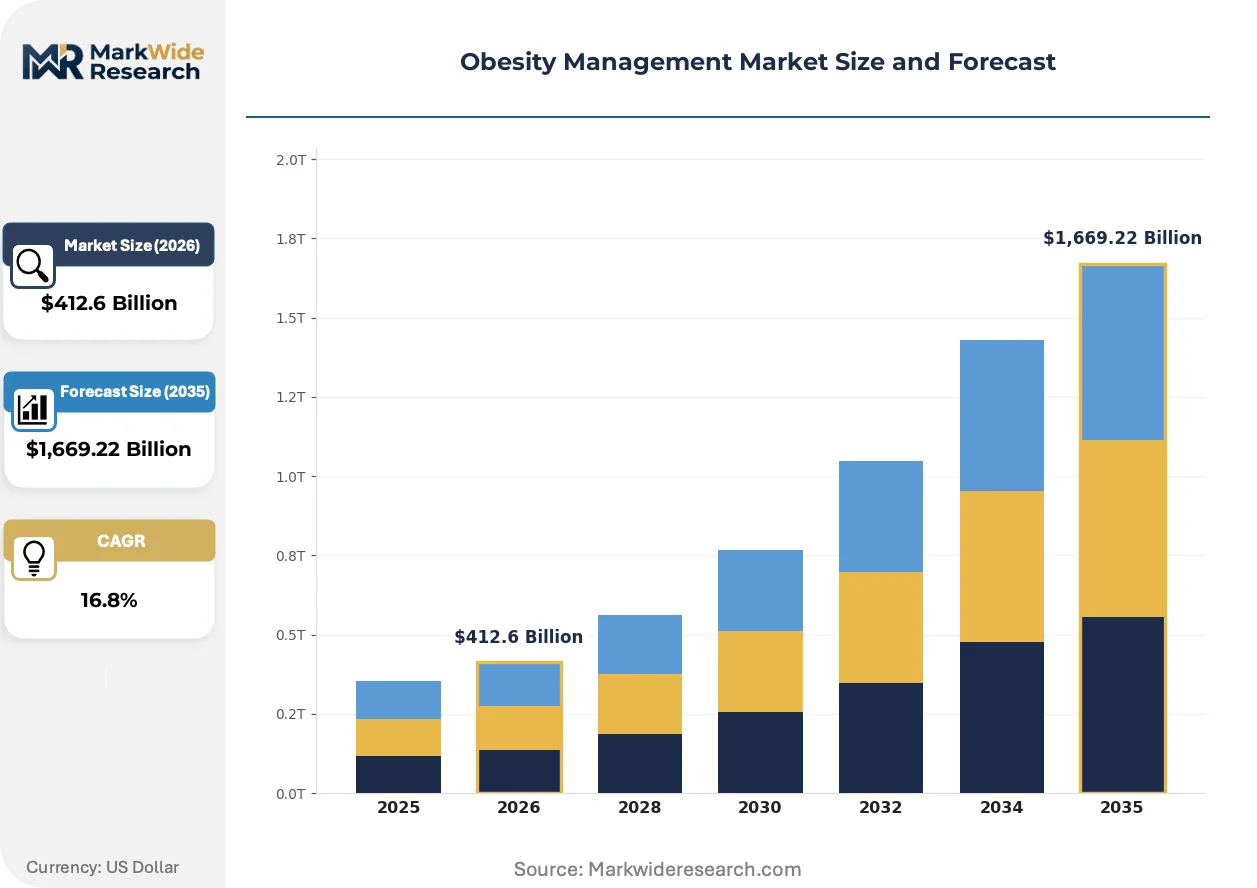
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $1,669.22 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Surgical Devices, Behavioral Therapy End User: Clinics, Hospitals, Home Care Settings, Fitness Centers Application: Weight Loss, Weight Maintenance, Post-Surgery Care, Lifestyle Management Treatment Type: Pharmacotherapy, Bariatric Surgery, Nutritional Counseling, Exercise Programs |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Herbalife Nutrition Ltd., Nestlé Health Science, WW International Inc., GlaxoSmithKline plc, Boehringer Ingelheim International GmbH, Medifast Inc., Noom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Obesity Management Market Strategic Shifts
Dual and triple hormone receptor agonism is compressing the therapeutic gap between pharmacological and surgical intervention thresholds. These molecular platforms are forcing incumbents to accelerate pipeline investments while reshaping how payers categorize obesity versus diabetes treatment paradigms.
Dual-incretin agonists targeting GLP-1 and GIP receptors simultaneously are unifying metabolic control mechanisms that previously required separate therapeutic classes. Academic medical centers and integrated delivery networks in the United States are adopting these agents as first-line options for patients with BMI thresholds above 35. This unification is compressing the addressable market for traditional single-hormone agonists and forcing wholesale formulary renegotiations.
EMA's centralized marketing authorization procedures for anti-obesity biologics are harmonizing entry timelines across EU member states while tightening post-market surveillance obligations. Manufacturers must now submit real-world evidence protocols alongside initial approval applications, extending pre-launch preparation cycles. The injectable therapy segment is responding by front-loading European health technology assessment submissions to secure parallel reimbursement decisions.
Employer-sponsored benefit designs are rotating procurement authority from human resources departments to chief medical officers and pharmacy benefit managers. Large self-insured employers in the United States are consolidating vendor relationships around integrated platforms that bundle pharmacotherapy, nutritional counseling, and remote monitoring. This consolidation is most visible among Fortune 500 technology and financial services firms with concentrated employee populations in coastal metropolitan areas.
Obesity Management Market Segmentation
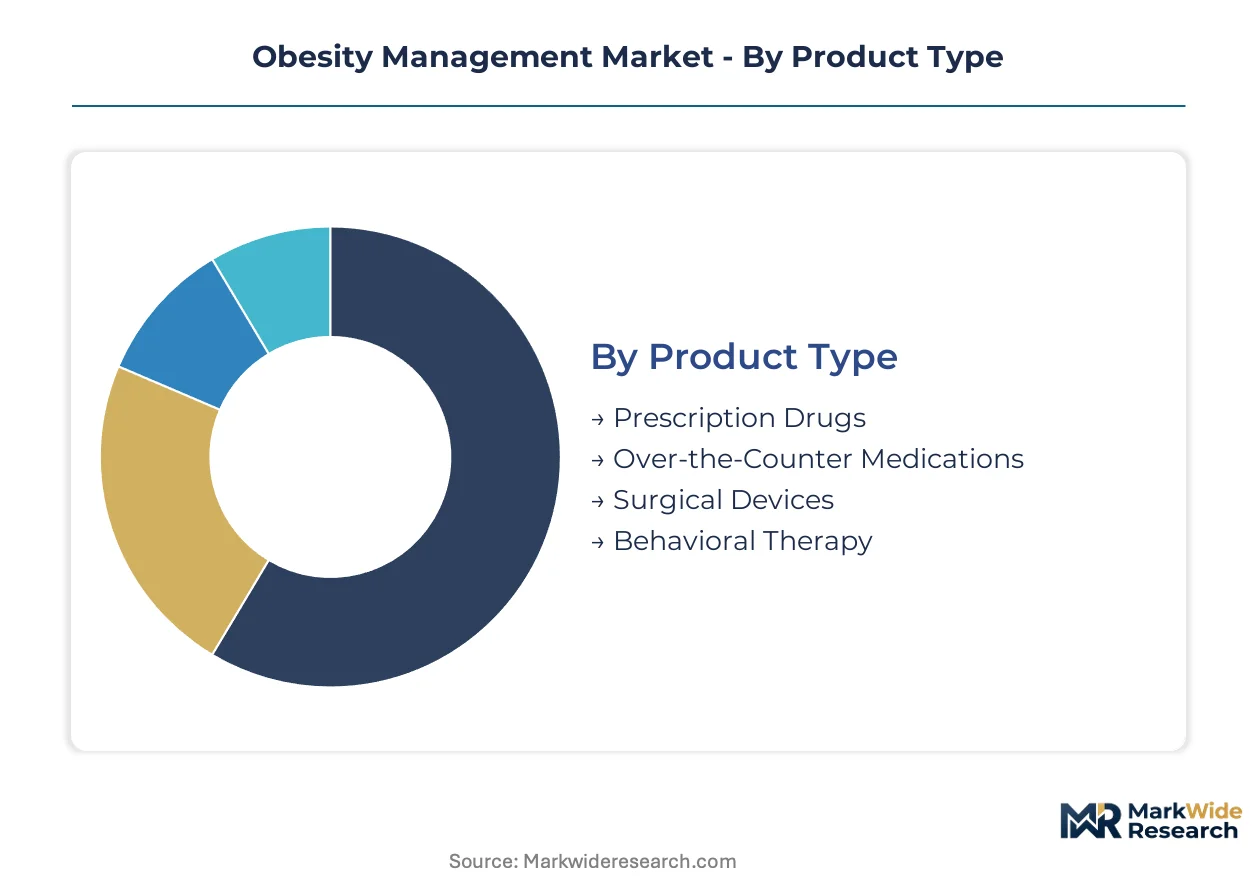
Segmentation in obesity management separates reimbursable clinical interventions from self-pay wellness offerings. Product type and end user dimensions reveal where cold-chain biologics command premium pricing versus where behavioral services compete on accessibility.
Product Type:
Standardization dominates prescription formulations while surgical devices and behavioral programs fragment across customization tiers.
- Prescription Drugs:GLP-1 and dual-hormone receptor agonists require peptide synthesis and cold-chain distribution infrastructure. Demand concentrates among integrated delivery networks in the United States where pharmacy benefit managers negotiate formulary placement for injectable therapies.
- Surgical Devices:Adjustable gastric bands, sleeve gastrectomy staplers, and intragastric balloons vary by anatomical compatibility and revision-surgery design. Tertiary hospital systems in Germany and South Korea drive procurement volume for reusable laparoscopic instrumentation.
- Over-the-Counter Medications:Appetite suppressants and fat-absorption blockers compete through retail pharmacy shelf placement without prescription requirements.
- Behavioral Therapy:Digital platforms and clinician-referred programs scale through employer wellness contracts and health plan reimbursements.
Leading the category by volume: Prescription Drugs. Expanding most quickly: Behavioral Therapy.
End User:
Cost tier stratification separates institutional procurement from direct-to-consumer payment models across delivery settings.
- Hospitals:Academic medical centers and tertiary systems house bariatric surgery suites and specialized obesity medicine clinics. Medicare coverage determinations and Medicaid formulary decisions in the United States dictate patient throughput for inpatient pharmacotherapy initiation.
- Clinics:Outpatient endocrinology and primary care practices manage dose titration and monitoring for injectable therapies. Private hospital chains in India and Brazil are expanding dedicated obesity clinics to capture self-pay volume outside reimbursement pathways.
- Home Care Settings:Self-administered subcutaneous injections and remote monitoring platforms reduce facility dependency for maintenance therapy.
- Fitness Centers:Commercial gyms and wellness studios deliver exercise programming and nutritional counseling on subscription or per-session payment terms.
Clinics capture the highest margin per patient encounter. Home Care Settings are climbing the fastest as cold-chain logistics mature for direct-to-patient delivery.
Application:
Volume concentration sits with acute intervention while recurring revenue pools form around maintenance and lifestyle adherence.
- Weight Loss:Pharmacotherapy and surgical intervention target BMI reduction thresholds for metabolic risk mitigation. FDA Risk Evaluation and Mitigation Strategy requirements shape clinical trial endpoints and post-market surveillance for anti-obesity drug approvals.
- Weight Maintenance:Long-term pharmacotherapy continuation and behavioral program enrollment prevent adipose tissue regain. Employer-sponsored wellness programs in the United States are bundling maintenance benefits within diabetes prevention frameworks.
- Post-Surgery Care:Nutritional monitoring and complication management follow bariatric procedures across hospital and home settings.
- Lifestyle Management:Comprehensive programs integrate diet, physical activity, and behavioral modification without procedural or pharmaceutical intervention.
Weight Loss dominates absolute patient initiations. Lifestyle Management is gaining share fastest as digital therapeutics secure formulary codes alongside traditional interventions.
Treatment Type:
Margin structure separates high-investment biologic manufacturing from labor-intensive counseling and device-dependent surgery.
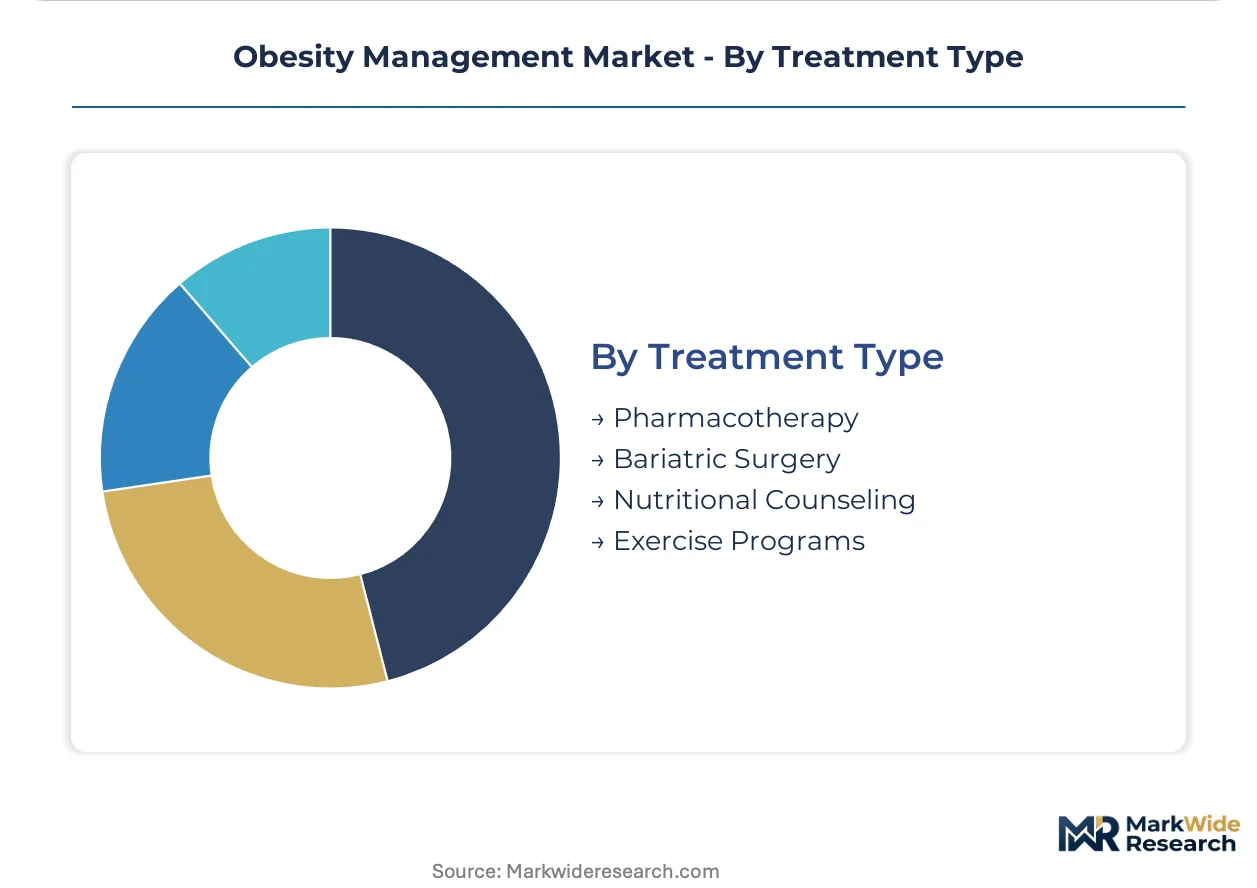
- Pharmacotherapy:Injectable peptide therapies command the dominant revenue pool as reimbursement frameworks expand across North America and Europe. EMA centralized marketing authorization procedures determine parallel entry timelines for EU member states.
- Bariatric Surgery:Roux-en-Y gastric bypass and sleeve gastrectomy procedures concentrate in tertiary hospital systems with specialized surgical teams. Indian private hospital chains in tier-2 and tier-3 cities present underpenetrated channels for device placement and post-operative protocols.
- Nutritional Counseling:Registered dietitian services deliver through telehealth platforms and in-person clinic visits on fee-for-service or bundled payment models.
- Exercise Programs:Structured physical activity interventions range from supervised clinical rehabilitation to commercial fitness memberships.
Pharmacotherapy leads by revenue contribution. Nutritional Counseling is expanding most quickly through digital therapeutics integration and remote delivery scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide synthesis capacity concentrates in European and North American contract manufacturing networks, while demand generation shifts toward employer-sponsored programs in the United States and private hospital chains in emerging Asian markets.
United States
Medicare Part D coverage determinations and Medicaid formulary decisions unlock patient volumes across integrated delivery networks. The FDA's Risk Evaluation and Mitigation Strategy requirements shape cardiovascular outcome trial designs for anti-obesity pharmacotherapy. Pharmacy benefit managers in coastal metropolitan areas negotiate preferred formulary tiers for GLP-1 receptor agonists.
Germany
Tertiary hospital systems drive procurement volume for reusable laparoscopic instrumentation and bariatric surgical devices. EMA centralized marketing authorization procedures harmonize entry timelines across EU member states while tightening post-market surveillance obligations. Academic medical centers in Bavaria and North Rhine-Westphalia adopt dual-incretin agonists as first-line options for patients with elevated BMI thresholds.
India
Private hospital chains in tier-2 and tier-3 cities capture self-pay volume outside reimbursement pathways for bariatric surgical device placement. CDSCO marketing authorization timelines influence parallel entry strategies for multinational pharmaceutical firms. Outpatient clinic networks in Maharashtra and Karnataka expand dedicated obesity medicine services to address underpenetrated demand pools.
Japan
PMDA approval pathways for anti-obesity biologics extend pre-launch preparation cycles through real-world evidence protocol requirements. METI industrial policy supports domestic peptide synthesis capacity investments to reduce import dependency. Medical centers in the Kanto and Kansai regions integrate pharmacotherapy with nutritional counseling under bundled payment frameworks.
Brazil
ANVISA regulatory harmonization with FDA standards accelerates clinical trial protocol acceptance for multinational sponsors. Private health plan coverage for bariatric surgery concentrates demand within São Paulo and Rio de Janeiro metropolitan hospital systems. Self-insured employer programs in the Southeast region embed weight management benefits within occupational health frameworks.
Obesity Management Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across pharmacotherapy, surgical devices, and behavioral intervention segments. The market structure exhibits tiered consolidation, with large-cap pharmaceutical manufacturers commanding formulary placement through manufacturing scale while mid-cap digital health vendors compete on employer contract accessibility. Three archetypes dominate: peptide synthesis specialists with cold-chain distribution networks, surgical device manufacturers with tertiary hospital relationships, and digital therapeutics vendors with health plan reimbursement codes. Capacity expansion partnerships with contract manufacturing organizations and strategic portfolio diversification into dual-hormone agonist platforms represent the dominant competitive moves.
Among large-cap pharmaceutical manufacturers, Novo Nordisk A/S and Eli Lilly and Company occupy positions defined by manufacturing scale and pipeline diversification into multi-hormone receptor platforms. These entities exemplify the archetype of vertically integrated peptide therapy producers with established pharmacy benefit manager relationships. WW International Inc. represents the behavioral intervention specialist archetype, competing for health plan contracts against digital therapeutics vendors through clinician-referred program positioning.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Herbalife Nutrition Ltd. |
| Nestlé Health Science |
| WW International Inc. |
| GlaxoSmithKline plc |
| Boehringer Ingelheim International GmbH |
| Medifast Inc. |
| Noom Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialized peptide synthesis chemists concentrated in Basel and Research Triangle Park drive labor-cost differentials that widen pricing-tier spreads between originator biologics and follow-on therapies. Cold-chain logistics specialists command premium wages that feed into three-tier pricing stratification across premium, standard, and economy patient access programs.
Pricing Analysis
Margin tightening in the behavioral therapy segment reflects digital therapeutics vendors compressing subscription fees to secure employer wellness contracts. Three-tier pricing structure across premium, standard, and economy levels separates concierge clinician-referred programs from telehealth platforms and self-directed apps. Cost-down pressure on surgical device bundles accelerates because Indian private hospital chains negotiate volume-based procurement contracts. Employer-sponsored wellness programs show least price sensitivity; self-pay patients in tier-3 Indian cities demonstrate highest.
Supply Chain Analysis
Single-source vulnerability sits with European contract manufacturers controlling active pharmaceutical ingredient synthesis for GLP-1 receptor agonists. Peptide production draws from Denmark, Switzerland, and North Carolina; cold-chain distribution rests on specialized packaging from Germany and temperature-controlled logistics from the Netherlands. Tariff exposure on Chinese-sourced excipients and single-use bioreactor components creates supply risk. Distribution runs through integrated delivery networks and pharmacy benefit managers in the United States, with direct-to-patient delivery expanding through specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from manufacturing scale requirements and FDA Risk Evaluation and Mitigation Strategy compliance costs will force subscale behavioral therapy vendors toward acquisition or exit.
For Market Incumbents: Hedge against oral small-molecule displacement by securing preferred formulary tiers through manufacturing scale commitments to pharmacy benefit managers. Deepen backward integration into peptide synthesis capacity in Basel and Research Triangle Park to reduce contract manufacturer dependency. Lock in multi-year employer wellness contracts before digital therapeutics vendors secure equivalent formulary codes.
For New Entrants and Emerging Players: Launch via direct-to-patient specialty pharmacy partnerships targeting tier-2 and tier-3 Indian cities where self-pay volume escapes reimbursement fragmentation. White-space opportunity sits with nutritional counseling platforms that integrate with existing electronic health record workflows. Penetrate through clinician-referred positioning rather than direct-to-consumer marketing to bypass prior authorization barriers.
For Investors and Strategic Acquirers: The window for entry favors digital therapeutics vendors with FDA breakthrough device designation and existing health plan reimbursement codes. Long-term viability hinges on formulary integration rather than standalone subscription models. Watch for CMS Medicare coverage determinations for anti-obesity pharmacotherapy as the inflection signal for addressable patient volume expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Cold-chain capacity expansion secures preferred formulary tiers with Express Scripts and CVS Caremark. |
| Regulatory Approval Pathway | FDA Risk Evaluation and Mitigation Strategy compliance accelerates cardiovascular outcome trial design standardization. |
| Pipeline Diversification | Dual-hormone agonist platforms extend addressable populations beyond diabetes overlap into obesity-specific indications. |
| Strategic Partnership | Employer wellness program bundling consolidates procurement authority under chief medical officers. |
| Software Companion Development | Digital therapeutics integration with pharmacotherapy secures parallel formulary codes and remote monitoring revenue. |
Study Parameters
Multi-period observation of formulary placement decisions, peptide synthesis capacity utilization, and employer benefit design changes anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare coverage determination databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Segment-weighting across product type, end user, application, and treatment type dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from fitted growth curves applied to reimbursable patient populations and self-pay volume pools. Forecast inputs incorporated Medicaid formulary expansion scenarios and cold-chain logistics maturation curves for rural health system penetration.
The model assumes a particular technology adoption path; alternative pathways for oral small-molecule GLP-1 agonists would alter the outlook if non-peptide candidates eliminate cold-chain dependencies. Forecasts reflect assumptions about Medicare Part D coverage determination timing and employer wellness program bundling velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Weight Loss Market