
 Weight Loss Market | 2026-2036
Weight Loss Market Size, Share, and Industry Trends Forecast 2026-2036
Weight Loss Market Intelligence
Employer-sponsored wellness programs is redrawing demand patterns in the weight loss industry, shifting purchasing power from individual consumers to institutional buyers. Novo Nordisk leverages its manufacturing scale to dominate the GLP-1 receptor agonist segment across North America and Europe. Eli Lilly anchors its position through R&D intensity in tirzepatide formulations, while WeightWatchers competes by repositioning its coaching platform around medication-adjacent behavioral support.
Weight loss encompasses pharmacological interventions, dietary modifications, physical activity regimens, and surgical procedures designed to reduce adipose tissue mass and improve metabolic biomarkers such as HbA1c, LDL cholesterol, and waist-to-hip ratio. The primary commercial purpose spans chronic disease prevention, aesthetic outcomes, and occupational health compliance. Dietary supplements occupy mature margin pools with commoditized pricing, while weight loss programs capture recurring revenue through subscription retention mechanics; fitness equipment segments face channel compression as home-gym saturation meets hybrid gym revival.
FDA oversees prescription anti-obesity drug approvals through risk-evaluation frameworks, while EMA's accelerated assessment pathways shape European launch timelines for new molecular entities. The EU Green Deal's packaging waste directives are forcing reformulation of single-use meal replacement formats, and HIPAA compliance requirements constrain how telehealth platforms share patient progress data with employers. Stakeholders must monitor pending Medicare coverage determinations for GLP-1 therapies, as these decisions will cascade through private payer formularies and reshape addressable patient populations.
Market Dynamics
GLP-1 receptor agonist supply concentration is restructuring competitive positioning across the weight loss industry, forcing incumbent dietary program operators to reposition around medication-adjacent behavioral support while manufacturing scale advantages determine prescription market access.
Growth Catalysts
- Employer-sponsored wellness expansion:Large self-insured employers in the United States are adding anti-obesity pharmacotherapy to covered benefits, redirecting purchasing power from individual consumers toward institutional procurement channels.
- FDA accelerated approval pathways:Risk-evaluation frameworks for chronic weight management drugs are compressing time-to-market for new molecular entities, expanding prescribable options beyond legacy anorectics.
- Telehealth platform proliferation:Direct-to-consumer digital health infrastructure is bypassing traditional primary care gatekeepers, enabling prescription acquisition through asynchronous clinical consultations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for peptide-based therapies clusters among specialized contract manufacturers in Switzerland and Denmark, creating single-source vulnerability.
- Medicare reimbursement exclusion:Statutory prohibitions on Medicare Part D coverage for weight-loss drugs limit addressable patient populations among Americans aged sixty-five and older.
- Compounded peptide substitution:503A pharmacy compounding of semaglutide alternatives is fragmenting demand and eroding brand pricing power through unregulated channels.
Strategic Opportunities
- Behavioral support bundling:Coaching platforms that integrate nutrition counseling with medication adherence protocols are capturing recurring subscription revenue from patients initiating pharmacotherapy.
- EU Green Deal packaging mandates:Single-use meal replacement format reformulation requirements are creating first-mover advantage for sustainable packaging innovators.
- Hybrid care model deployment:Clinic-at-home services combining remote patient monitoring with intermittent in-person metabolic assessment are penetrating suburban and exurban geographies previously underserved by bariatric centers.
Industry Challenges
- Endocrinology workforce scarcity:Limited fellowship-trained obesity medicine specialists constrain patient enrollment velocity for intensive lifestyle intervention programs.
- HIPAA-compliant data sharing:Employer wellness platforms face technical and legal friction when attempting to synchronize patient progress metrics with health plan administrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weight Loss Market |
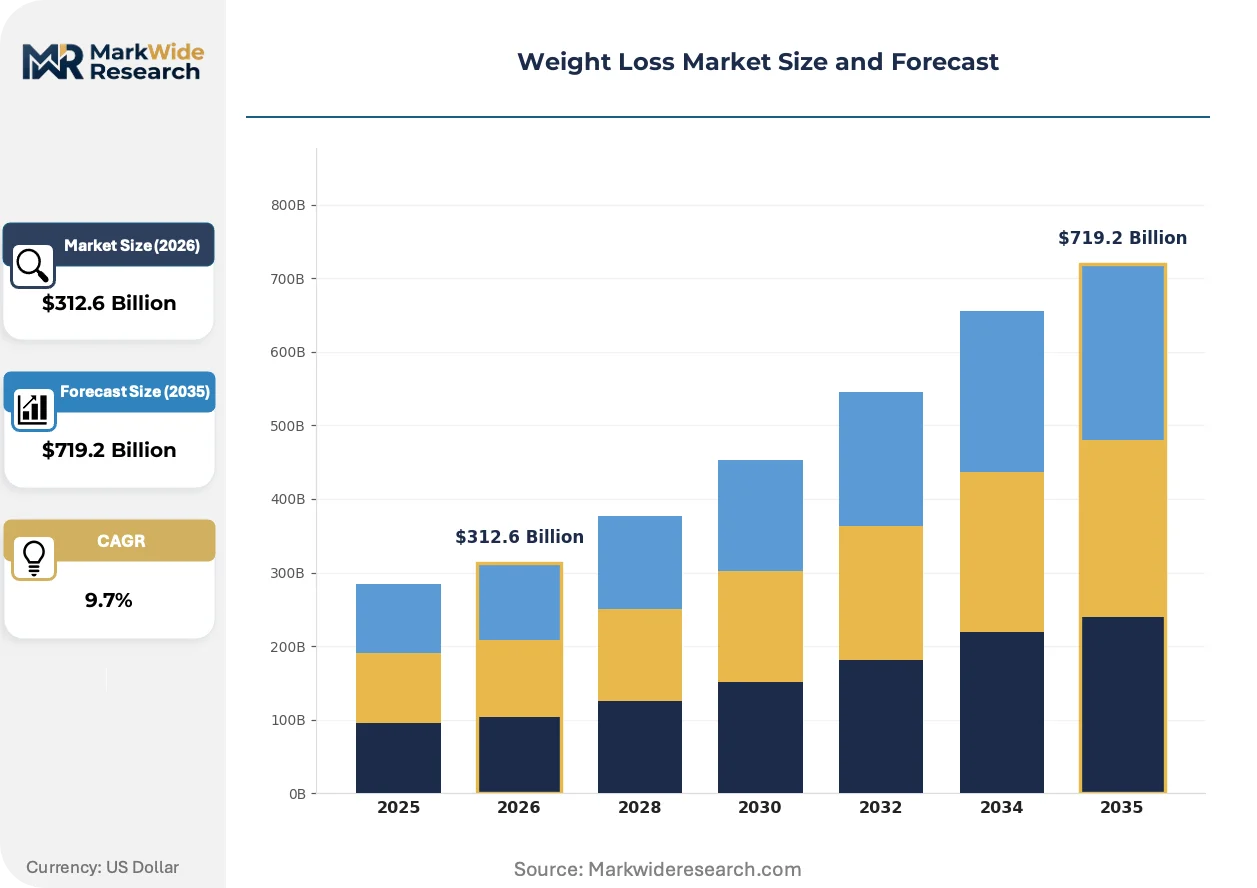
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $719.2 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Meal Replacements, Weight Loss Programs, Fitness Equipment Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies Customer Type: Fitness Enthusiasts, Overweight Individuals, Health-Conscious Consumers, Professionals Therapy Area: Obesity Management, Metabolic Health, Fitness Improvement, Nutritional Support |
| Companies Covered | It Works! Global, Noom, Eli Lilly, Nutrisystem, WeightWatchers, Novo Nordisk, Shaklee, Mayo Clinic Diet, Vida Divina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weight Loss Market Strategic Shifts & Innovations
Continuous glucose monitoring integration is reshaping how patients and clinicians calibrate dietary interventions, creating feedback-loop dependencies that privilege data-native service providers over traditional program operators.
Dual-hormone agonist formulations combining GLP-1 and GIP receptor activation are decomposing the monotherapy paradigm that has dominated anti-obesity pharmacology for two decades. Bariatric endocrinologists in academic medical centers are adopting these agents as first-line interventions for patients with BMI exceeding thirty-five. This molecular innovation is compressing demand for metabolic surgery while expanding addressable populations to include those previously excluded from surgical candidacy.
EMA's accelerated assessment pathways for new molecular entities are compressing European launch timelines relative to standard marketing authorization procedures. Manufacturers are pre-positioning real-world evidence generation infrastructure to satisfy post-authorization safety monitoring requirements. The Nordic region and Germany are experiencing the fastest formulary adoption curves as national health technology assessment bodies recalibrate cost-effectiveness thresholds for chronic disease prevention.
Patients are consolidating purchasing decisions around integrated platforms that bundle prescription fulfillment, nutritional coaching, and biomarker tracking into single-subscription offerings. Standalone dietary supplement retailers and independent dietetic practices are losing share to vertically integrated telehealth operators. This consolidation pattern is most pronounced in the United States, where direct-to-consumer advertising and pharmacy benefit manager integration create switching costs that favor platform incumbents.
Weight Loss Market Segmentation
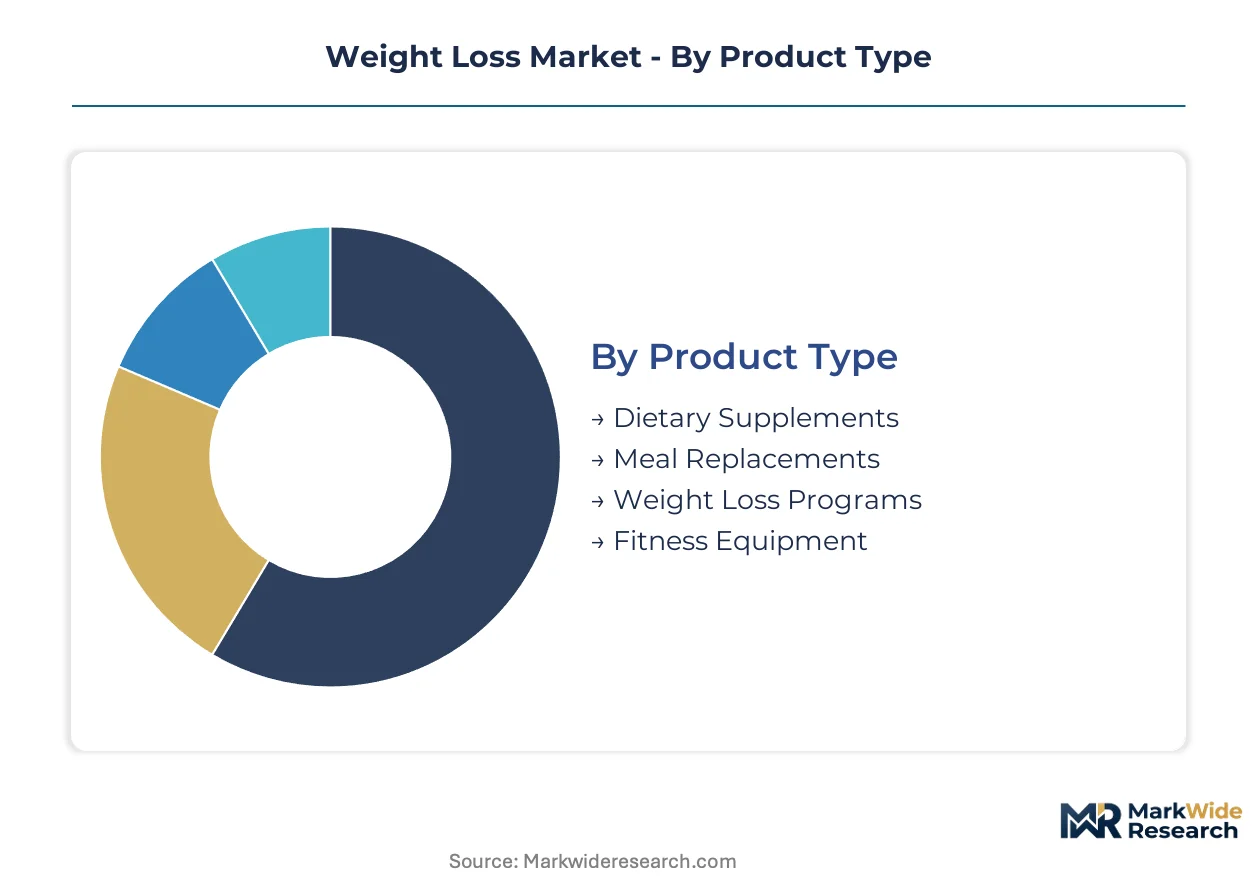
GLP-1 pharmacotherapy is compressing demand for legacy weight loss modalities, forcing segmentation strategies to distinguish between medication-adjacent services and substitutable standalone products. Manufacturers must map substitution vulnerability across product architectures to defend revenue pools.
Product Type:
Dietary supplements face the most acute substitution pressure as GLP-1 therapies displace appetite suppressants and thermogenic formulations; meal replacements and coaching platforms are repositioning around medication adherence rather than direct competition.
- Dietary Supplements:Capsule and powder formulations containing caffeine, green tea extract, and fiber complexes. Demand concentrates among self-directed consumers in the United States seeking non-prescription options, though FDA warning letters against unapproved health claims constrain marketing channels.
- Meal Replacements:Portion-controlled shakes, bars, and pre-packaged entrees with defined macronutrient profiles. European adoption accelerates in Germany and the Netherlands where EFSA-approved satiety claims support premium positioning against commoditized alternatives.
- Weight Loss Programs:Subscription-based coaching platforms integrating behavioral protocols with biometric tracking.
- Fitness Equipment:Connected home-gym hardware and wearable devices for energy expenditure monitoring.
Dietary supplements anchors the volume base while weight loss programs gains share at the steepest rate.
Distribution Channel:
Channel economics stratify by customer acquisition cost and regulatory burden, with telehealth-integrated platforms capturing lifetime value through recurring prescription fulfillment.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators with algorithmic personalization engines. United States consumers consolidate purchases through pharmacy benefit manager portals that bundle GLP-1 prescriptions with nutritional coaching subscriptions.
- Supermarkets:Mass-market retail with high-frequency foot traffic and private-label meal replacement placement. Shelf space allocation in France and the United Kingdom favors protein-enriched convenience foods over legacy diet brands.
- Specialty Stores:Dedicated nutrition retailers with certified staff consultation.
- Pharmacies:Community and chain drugstores with pharmacist-led weight management counseling.
Pharmacies anchors the volume base while online retail climbs the fastest.
Customer Type:
Employer procurement is shifting purchasing power from individual decision-makers toward benefits administrators seeking population-level metabolic outcomes.
- Fitness Enthusiasts:Recreational athletes prioritizing body composition optimization and performance metrics. United States demand clusters in metropolitan fitness studio ecosystems where continuous glucose monitoring integration drives platform stickiness.
- Overweight Individuals:Clinically defined obesity populations with BMI thresholds triggering pharmacotherapy eligibility. German statutory health insurance coverage determinations for anti-obesity drugs are expanding addressable populations beyond prior reimbursement exclusions.
- Health-Conscious Consumers:Preventive wellness adopters without clinical risk factors.
- Professionals:Occupational cohorts with employer-sponsored wellness program access.
Overweight individuals anchors the volume base while professionals gains share at the steepest rate.
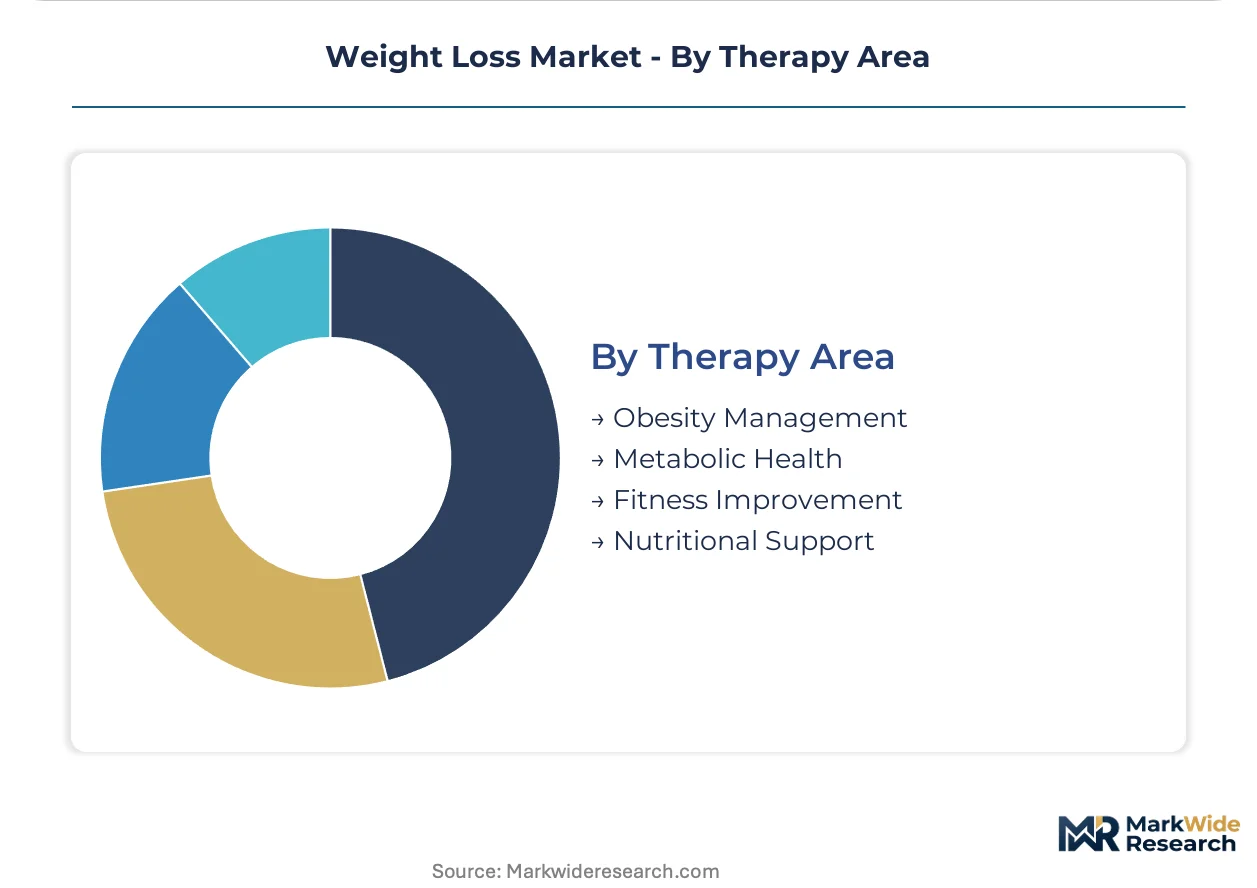
Therapy Area:
Clinical outcome requirements differentiate reimbursement-eligible interventions from discretionary wellness spending.
- Obesity Management:Clinically supervised weight reduction targeting comorbidity risk reduction. United States bariatric surgery centers in Texas and Florida are adopting GLP-1 agonists as bridging therapy to reduce perioperative risk.
- Metabolic Health:Glycemic control and lipid profile optimization through lifestyle and pharmacological intervention. Nordic health technology assessment bodies in Sweden and Denmark are recalibrating cost-effectiveness thresholds to include diabetes prevention outcomes.
- Fitness Improvement:Athletic performance and body recomposition without clinical indication.
- Nutritional Support:Micronutrient adequacy and dietary pattern correction.
Obesity management anchors the volume base while metabolic health expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish pharmaceutical exports flow into United States procurement channels through pharmacy benefit manager networks, while Swiss contract manufacturers supply active pharmaceutical ingredients to North American and European formulators.
United States
Employer-sponsored wellness programs and Medicare reimbursement debates drive institutional purchasing power toward GLP-1 therapies. FDA risk-evaluation frameworks for chronic weight management drugs compress approval timelines for new molecular entities. Texas and Florida bariatric surgery centers adopt GLP-1 agonists as bridging therapy to reduce perioperative risk.
Germany
Statutory health insurance coverage determinations for anti-obesity drugs expand addressable populations beyond prior reimbursement exclusions. EMA accelerated assessment pathways compress European launch timelines relative to standard marketing authorization. The Nordic region and Germany experience the fastest formulary adoption curves as health technology assessment bodies recalibrate cost-effectiveness thresholds.
Switzerland
Specialized contract manufacturers cluster active pharmaceutical ingredient production for peptide-based therapies, creating single-source vulnerability in supply chains. Swissmedic oversight of manufacturing quality standards shapes export eligibility for European and North American markets. Basel and Zurich host concentration of peptide synthesis capacity serving Novo Nordisk and Eli Lilly supply networks.
United Kingdom
NHS England weight management service procurement redirects toward integrated digital health platforms combining prescription fulfillment with behavioral support. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways distinct from EMA timelines. London and Southeast England concentrate telehealth platform headquarters and pharmacy benefit manager European operations.
France
ANSM pharmacovigilance requirements for anti-obesity medications shape post-market surveillance obligations across European markets. Supermarket shelf space allocation favors protein-enriched convenience foods over legacy diet brands under EFSA-approved satiety claim frameworks. Paris and Île-de-France anchor health technology assessment body influence on national reimbursement decisions.
Weight Loss Market Key Industry Players
Player mix skews toward pharmaceutical incumbents with manufacturing scale advantages, creating tiered competition between prescription drug developers and repositioned behavioral support platforms. The market structure concentrates around peptide synthesis capabilities and direct-to-consumer telehealth infrastructure. Two strategic archetypes dominate: vertically integrated drug developers controlling API-to-formulation supply chains, and platform operators bundling coaching with medication adherence protocols. Competitive moves center on strategic partnerships between pharmaceutical manufacturers and digital health platforms, plus portfolio diversification into adjacent metabolic health services.
Within the pharmaceutical developer tier, Novo Nordisk and Eli Lilly anchor prescription market positioning through GLP-1 receptor agonist and dual-hormone agonist portfolios. WeightWatchers occupies the platform operator archetype, repositioning subscription coaching around medication-adjacent behavioral support rather than direct competition with pharmacotherapy. These three companies exemplify the strategic divergence between manufacturing-scale drug developers and service-layer platform operators competing for patient lifetime value through distinct retention mechanics.
| Leading Market Players |
|---|
| It Works! Global |
| Noom |
| Eli Lilly |
| Nutrisystem |
| WeightWatchers |
| Novo Nordisk |
| Shaklee |
| Mayo Clinic Diet |
| Vida Divina |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between self-insured employers and GLP-1 manufacturers lock in supply access while anchoring annual price visibility for multi-year wellness program budgets. These contracts tether procurement volume to formulary placement, creating switching costs that insulate incumbent pharmaceutical developers from spot-market volatility.
Pricing Analysis
Next-generation dual-hormone agonist formulations command substantial premiums over legacy GLP-1 monotherapies, while prior-generation anorectics face accelerating price erosion. Subscription-based coaching platforms deploy three-tier pricing structure across premium, standard, and economy levels differentiated by biomarker tracking intensity and clinician access frequency. Cost compression in the dietary supplement tier stems from compounded peptide substitution through unregulated 503A pharmacy channels. Self-directed consumers purchasing via online retail exhibit highest price sensitivity, whereas employer-sponsored benefits administrators prioritize clinical outcome guarantees over per-unit cost.
Supply Chain Analysis
Strategic stockpiling of active pharmaceutical ingredients dominates inventory strategy among Swiss and Danish contract manufacturers serving peptide synthesis demand. API production for semaglutide and tirzepatide concentrates in Switzerland, Denmark, and select North American facilities with specialized fermentation capacity. Finished formulation draws from recombinant DNA technology, sterile fill-finish infrastructure, and cold-chain distribution assets. Single-source vulnerability in peptide synthesis creates exposure to regulatory inspection delays. Distribution runs through pharmacy benefit manager networks into employer-sponsored channels and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Employer wellness program budget cycles are driving a cyclical recovery in institutional procurement channels, redirecting purchasing power from individual consumers toward multi-year benefits contracts.
For Market Incumbents: Consolidate manufacturing scale advantages through captive peptide synthesis capacity in Basel and Copenhagen clusters to defend against compounded substitution threats. Deepen backward integration into fermentation infrastructure and secure exclusive pharmacy benefit manager formulary placement through outcome-based contracting with large self-insured employers. For New Entrants and Emerging Players: Lead with behavioral support bundling for patients initiating GLP-1 pharmacotherapy, targeting suburban and exurban geographies previously underserved by bariatric centers. Deploy hybrid care models combining remote patient monitoring with intermittent in-person metabolic assessment to penetrate Medicare-excluded populations through cash-pay channels. For Investors and Strategic Acquirers: Platform operators with integrated prescription fulfillment, nutritional coaching, and biomarker tracking capabilities represent the most defensible acquisition archetype for patient lifetime value capture. Long-term viability hinges on Medicare coverage determination outcomes for anti-obesity pharmacotherapy. Revision becomes warranted when FDA risk-evaluation frameworks expand accelerated approval pathways beyond current chronic weight management indications.| Strategic Initiative | Industry Significance |
|---|---|
| Behavioral Support Bundling | Captures recurring subscription revenue from patients initiating Novo Nordisk or Eli Lilly pharmacotherapy regimens. |
| API Manufacturing Scale-Up | Reduces single-source vulnerability in Swiss and Danish peptide synthesis clusters serving North American demand. |
| Hybrid Care Model Deployment | Penetrates suburban Texas and Florida geographies where bariatric center density remains insufficient. |
| Employer Outcome-Based Contracting | Locks in multi-year formulary placement with self-insured benefits administrators seeking metabolic risk reduction. |
| Sustainable Packaging Reformulation | Creates first-mover advantage under EU Green Deal directives targeting single-use meal replacement formats. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, formulary directors, payer access specialists, and telehealth platform operators; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and employer benefits procurement databases. Bottom-up patient population estimates triangulated against top-down pharmaceutical revenue disclosures.
Across the analysis window, the forecasting framework modeled segmentation dimensions including therapy area, distribution channel, customer type, and regional regulatory cluster. CAGRs derived from patient enrollment velocity projections, reimbursement expansion scenarios, and substitution elasticity between pharmacotherapy and legacy modalities. Forecast inputs incorporated employer wellness program adoption curves and Medicare coverage determination timelines.
The analysis sits within stated boundaries; outcomes outside FDA accelerated approval pathway parameters or EMA marketing authorization timelines would require recalibration. Forecasts reflect assumptions regarding GLP-1 supply concentration and telehealth platform regulatory compliance. Revision becomes warranted when employer-sponsored coverage expansion crosses thresholds that trigger private payer formulary cascade effects.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Clinical Nutrition Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
Advanced Glycation End Products Market