
 Clinical Nutrition Market | 2026-2036
Clinical Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Nutrition Market Intelligence
The capability gap between large-scale manufacturers and regional formulators is collapsing as automated compounding technology becomes accessible across tier-two producers. Abbott Laboratories leverages its vertically integrated supply chain to sustain cost advantages in parenteral nutrition bags. Nestlé Health Science anchors its position through specialized oncology and pediatric formulations. Fresenius Kabi dominates hospital channel contracts across acute care networks.
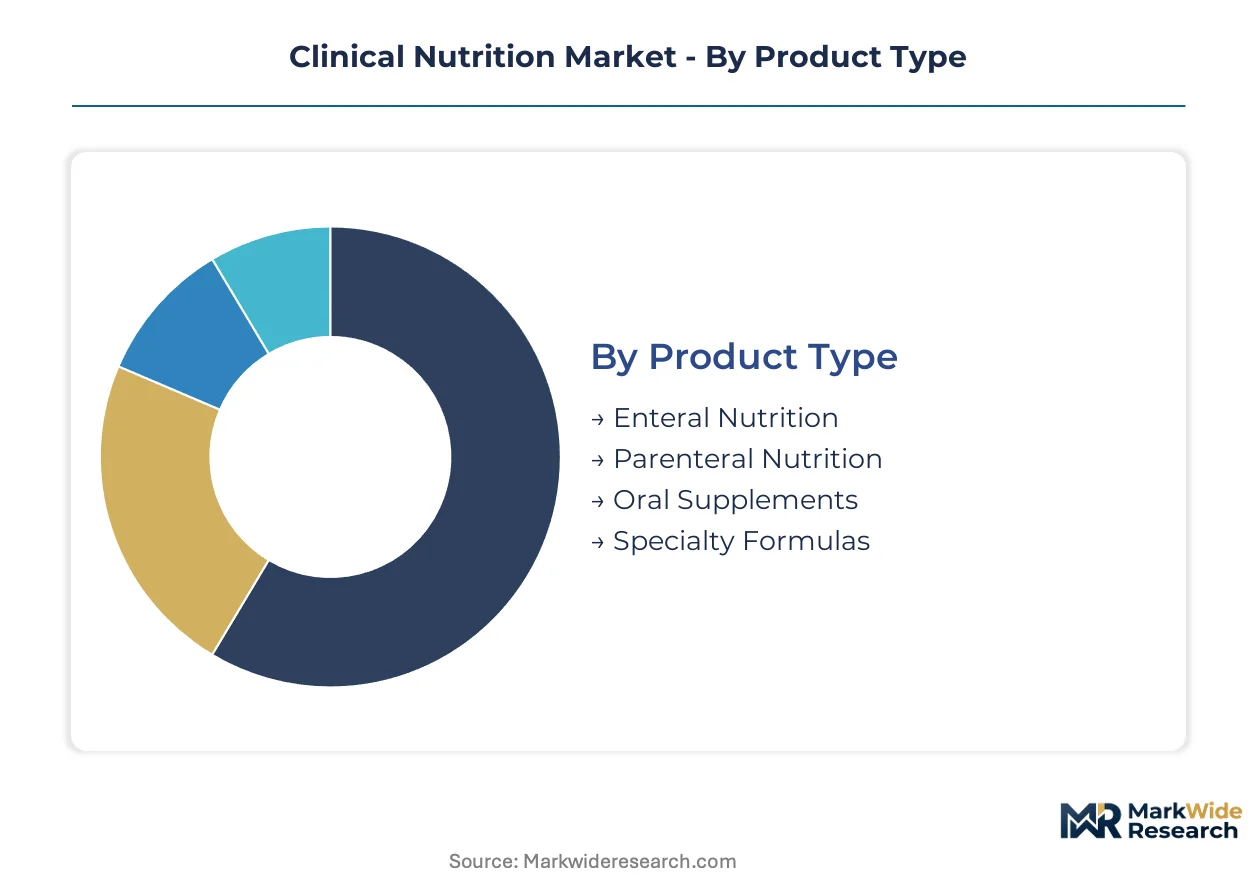
Clinical nutrition encompasses medically prescribed nutrient formulations designed to prevent or treat malnutrition in patients unable to consume adequate food orally, typically delivered through enteral tubes, intravenous infusion, or fortified oral supplements with precise macronutrient ratios and micronutrient fortification. These formulations serve therapeutic purposes in managing disease-related malnutrition, supporting recovery from surgery or chemotherapy, and maintaining nutritional status in chronic conditions. Enteral nutrition leads product type revenue due to lower complication rates and earlier hospital discharge protocols, while specialty formulas represent the fastest-expanding category driven by personalized amino acid profiles and disease-specific compositions. Oncology applications command premium pricing as immunonutrition blends gain protocol adoption in chemoradiotherapy settings.
The FDA governs medical food classifications and Good Manufacturing Practice standards for clinical nutrition products, while the European Medicines Agency oversees borderline products between foods and pharmaceuticals in EU markets. The EU Medical Device Regulation increasingly captures enteral delivery systems and feeding pumps, tightening conformity assessment requirements for manufacturers seeking CE marking. Japan's Ministry of Health, Labour and Welfare maintains distinct FOSHU and medical food categories that create separate approval pathways for functional nutrition claims. Stakeholders must monitor evolving reimbursement classifications for homecare nutrition services as payors reassess cost-effectiveness thresholds for long-term enteral support.
Market Dynamics
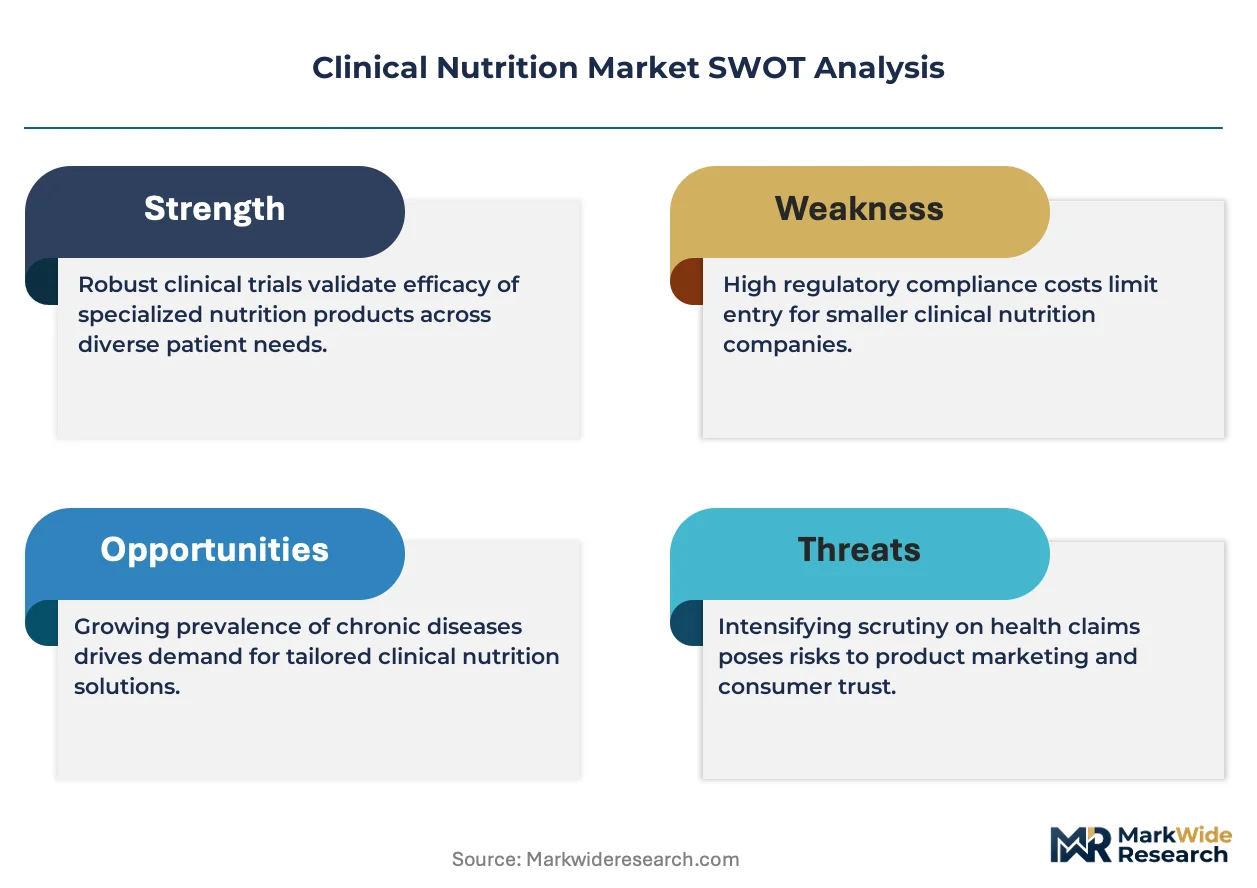
The FDA's updated labeling requirements for medical foods are compressing formulation timelines while accelerating compliance investments across manufacturer tiers. Hospital procurement teams now mandate real-time traceability systems for enteral formula lots, forcing supply chain technology upgrades before contract renewal cycles.
Growth Catalysts
- Aging Demographics:Post-surgical nutritional support demand concentrates in Medicare-eligible populations across the United States, where home-based clinical nutrition therapy reimbursement is expanding.
- Automated Compounding:Tier-two producers now access precision blending systems that previously required capital scales exclusive to multinational manufacturers.
- EU Medical Device Regulation:CE marking requirements for enteral delivery systems are consolidating hospital channel contracts toward manufacturers with integrated device-formula portfolios.
Market Restraints
- Lipid Emulsion Concentration:Parenteral nutrition supply chains depend on soybean oil and fish oil inputs subject to agricultural commodity volatility and geographic sourcing constraints.
- Hospital GPO Consolidation:Group purchasing organization mergers in North America are narrowing vendor qualification windows and compressing margin structures for regional formulators.
- Substitution Thresholds:Oral nutritional supplements face displacement from food-first protocols in European long-term care facilities where texture-modified diets achieve comparable outcomes.
Strategic Opportunities
- Personalized Amino Acid Profiles:Disease-specific oncology and pediatric compositions command premium positioning as immunonutrition blends gain protocol adoption in chemoradiotherapy settings.
- Japan FOSHU Pathway:Functional nutrition claims approval creates distinct market positioning for clinical nutrition products with demonstrated physiological effects beyond basic malnutrition management.
- Homecare Channel Expansion:Durable medical equipment suppliers are building clinical nutrition dispensing capabilities to capture Medicare reimbursement flows for long-term enteral support.
Industry Challenges
- Compounding Pharmacy Skill Gaps:Sterile parenteral nutrition preparation requires specialized pharmacy technician training that acute care networks struggle to staff at scale.
- Legacy ERP Integration:Hospital supply chain systems require custom API development to connect with manufacturer traceability platforms mandated by FDA lot-tracking rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Nutrition Market |
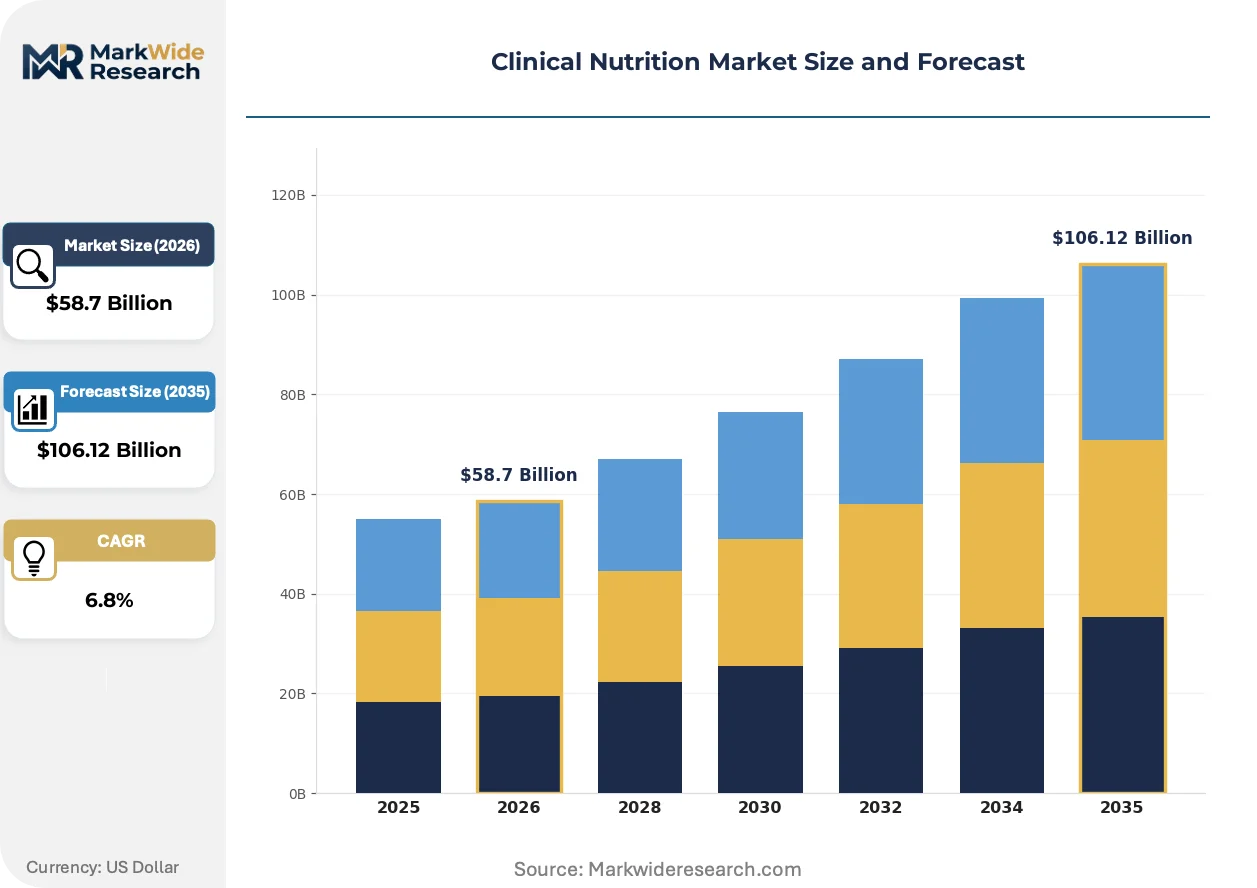
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enteral Nutrition, Parenteral Nutrition, Oral Supplements, Specialty Formulas Application: Oncology, Gastroenterology, Critical Care, Pediatrics Delivery Mode: Hospital, Homecare, Long-term Care, Nursing Facility End User: Patients, Healthcare Providers, Caregivers, Clinics |
| Companies Covered | Abbott Laboratories, Nestlé Health Science, Danone Nutricia, Fresenius Kabi, Baxter International, B. Braun Melsungen AG, Mead Johnson Nutrition Company, Pfizer Inc., Perrigo Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Nutrition Market Strategic Shifts & Innovations
Automated manufacturing systems and regulatory digitization are compressing the capability gap between multinational and regional clinical nutrition producers. Three developments are reshaping competitive positioning across formulation, delivery, and procurement layers.
Microfluidic mixing technology is decomposing traditional batch manufacturing economics in parenteral nutrition production. Mid-scale manufacturers in Germany and South Korea now deploy continuous flow reactors that achieve pharmaceutical-grade sterility without cleanroom infrastructure investments. This capability diffusion is fragmenting hospital contract concentration that previously favored integrated multinationals.
The FDA's Unique Device Identification system for enteral feeding pumps is forcing hardware-software integration investments across device portfolios. Manufacturers must embed real-time consumption tracking and automated reorder triggers to maintain hospital procurement eligibility. Pediatric and critical care units face the steepest compliance timelines due to pump replacement cycles and IT security validation requirements.
Hospital supply chains are unbundling clinical nutrition purchasing from broadline foodservice contracts. Acute care networks now operate dedicated clinical nutrition procurement desks with specialized dietetic staff evaluating formula efficacy data. This specialization is most advanced in United States academic medical centers where value-based care metrics tie reimbursement to malnutrition reduction outcomes.
Clinical Nutrition Market Segmentation
Clinical nutrition segmentation reveals distinct procurement patterns across acute care networks and home-based channels. Product formulation complexity, reimbursement pathways, and patient acuity levels create divergent margin structures within each category.
Product Type:
Domestic production dominates enteral and parenteral formulations due to sterility requirements and short shelf lives, while specialty formulas increasingly flow through cross-border licensing arrangements.
- Enteral Nutrition:Tube-delivered liquid formulations with precise macronutrient ratios and micronutrient fortification. Demand concentrates in United States academic medical centers where value-based care metrics tie reimbursement to malnutrition reduction outcomes. FDA lot-tracking rules mandate real-time traceability systems before contract renewal cycles.
- Specialty Formulas:Disease-specific compositions featuring personalized amino acid profiles and immunonutrition blends. Oncology applications command premium positioning as chemoradiotherapy protocols adopt these formulations across German and South Korean hospital networks. Microfluidic mixing technology enables mid-scale manufacturers to achieve pharmaceutical-grade sterility without cleanroom infrastructure.
- Parenteral Nutrition:Intravenous formulations for patients with non-functional gastrointestinal tracts.
- Oral Supplements:Fortified beverages and powders for patients maintaining partial oral intake capacity.
Enteral nutrition commands the established base. The steepest expansion runs through specialty formulas.
Application:
Pediatric and oncology segments sustain premium pricing tiers, while critical care volumes fluctuate with hospital admission cycles and seasonal respiratory illness patterns.
- Oncology:Immunonutrition blends designed to modulate inflammatory response during chemoradiotherapy. Demand clusters in United States Medicare-eligible populations where home-based clinical nutrition therapy reimbursement is expanding. Japanese Ministry of Health, Labour and Welfare maintains distinct approval pathways for functional nutrition claims in cancer care settings.
- Critical Care:High-protein, immune-modulating formulations for mechanically ventilated patients. European long-term care facilities increasingly deploy texture-modified diets as first-line interventions, creating substitution pressure on standard oral supplements. ICU protocols in German hospitals now mandate early enteral feeding within 24-48 hours of admission.
- Pediatrics:Age-specific macronutrient ratios for growth-impaired infants and children.
- Gastroenterology:Elemental and semi-elemental formulas for malabsorption disorders and inflammatory bowel disease.
Oncology commands the established base. The steepest expansion runs through critical care.
Delivery Mode:
Hospital procurement teams now operate dedicated clinical nutrition desks, unbundling purchasing from broadline foodservice contracts as value-based metrics take hold.
- Hospital:Acute care networks with specialized dietetic staff evaluating formula efficacy data. EU Medical Device Regulation CE marking requirements for enteral delivery systems are consolidating contracts toward manufacturers with integrated device-formula portfolios. United States academic medical centers lead this specialization trend.
- Homecare:Durable medical equipment suppliers building clinical nutrition dispensing capabilities to capture Medicare reimbursement flows. Automated reorder triggers embedded in enteral feeding pumps maintain procurement eligibility under FDA Unique Device Identification rules. Pediatric and critical care units face steepest compliance timelines due to pump replacement cycles.
- Long-term Care:Skilled nursing facilities with texture-modified diet protocols.
- Nursing Facility:Post-acute settings managing transition from hospital-based to home-based nutrition support.
Hospital commands the established base. The steepest expansion runs through homecare.
End User:
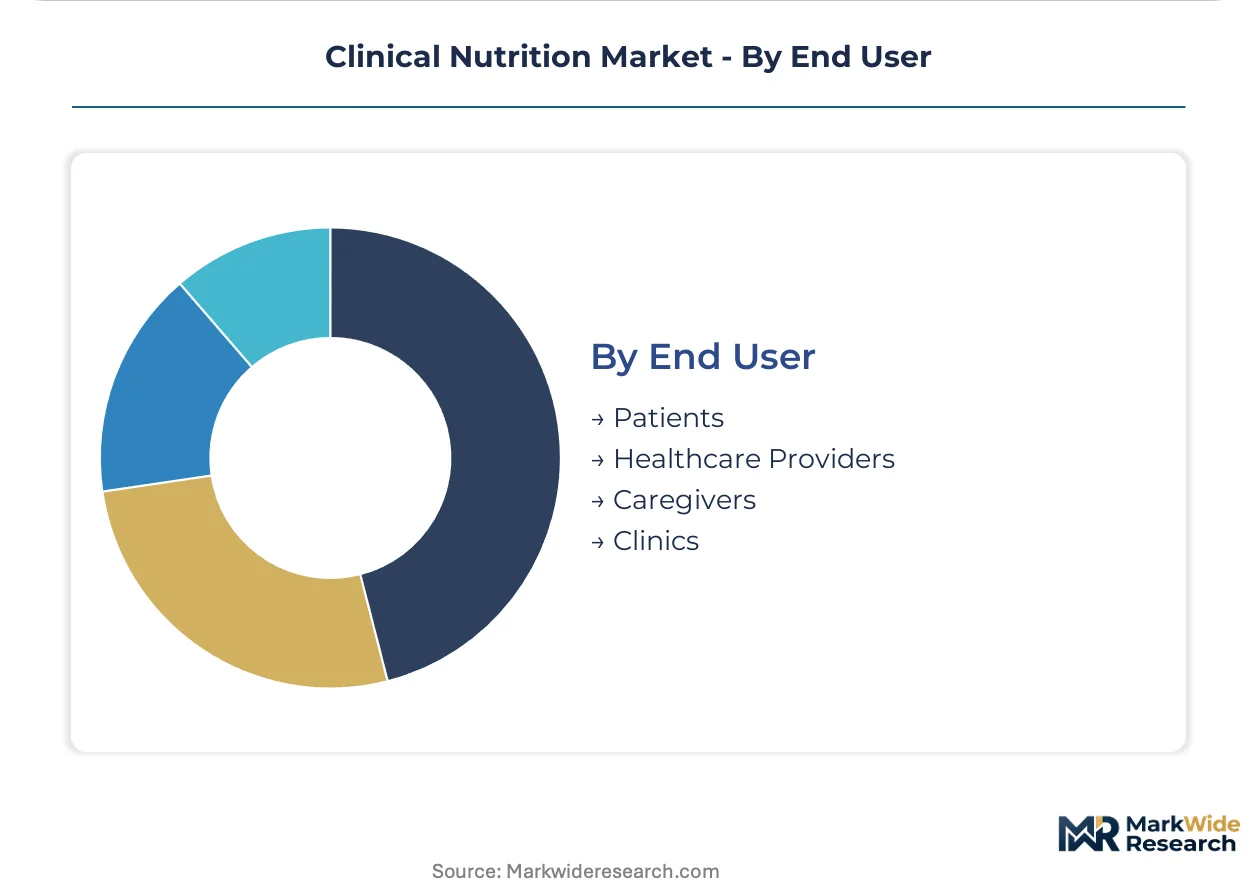
Procurement authority is fragmenting as caregivers gain reimbursement access and clinics build compounding capabilities previously restricted to hospital pharmacies.
- Healthcare Providers:Hospital systems and physician practices with formulary decision authority. Group purchasing organization mergers in North America are narrowing vendor qualification windows and compressing margin structures for regional formulators. Supply chain technology upgrades precede contract renewal cycles.
- Caregivers:Family members and home health aides administering enteral nutrition in residential settings. Medicare reimbursement policies increasingly cover training and supply costs for long-term enteral support, expanding addressable volume beyond institutional channels.
- Patients:Self-directed consumers with prescription authority for oral supplements.
- Clinics:Outpatient infusion centers and specialty practices with limited compounding capabilities.
Healthcare providers command the established base. The steepest expansion runs through caregivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where Medicare reimbursement expansion drives premium capture, while European markets face margin compression from food-first protocol adoption in long-term care facilities.
United States
Post-surgical nutritional support demand clusters in Medicare-eligible populations, with home-based clinical nutrition therapy reimbursement expanding through durable medical equipment channels. The FDA's updated labeling requirements for medical foods are compressing formulation timelines while mandating real-time traceability systems. Boston and Minneapolis academic medical centers operate dedicated clinical nutrition procurement desks with specialized dietetic staff evaluating formula efficacy data.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia mandate early enteral feeding within 24-48 hours of ICU admission, driving volume concentration in acute care channels. The EU Medical Device Regulation tightens CE marking requirements for enteral delivery systems and feeding pumps. Microfluidic mixing technology deployment in Stuttgart and Munich enables mid-scale manufacturers to achieve pharmaceutical-grade sterility without cleanroom infrastructure investments.
Japan
Aging demographics accelerate demand for disease-specific oncology and pediatric formulations with personalized amino acid profiles. The Ministry of Health, Labour and Welfare maintains distinct FOSHU and medical food categories that create separate approval pathways for functional nutrition claims. Tokyo and Osaka pharmaceutical clusters concentrate immunonutrition blend development for chemoradiotherapy protocol adoption.
South Korea
Continuous flow reactor adoption in Seoul and Busan manufacturing zones fragments hospital contract concentration previously favoring integrated multinationals. The MFDS oversees borderline product classifications between foods and pharmaceuticals, creating regulatory clarity for specialty formula entrants. Domestic producers leverage automated compounding technology to capture share in oncology and critical care segments.
Brazil
ANVISA registration pathways for medical foods create compliance barriers that favor established multinational formulators with regulatory affairs scale. São Paulo and Rio de Janeiro hospital networks consolidate procurement through group purchasing organizations, narrowing vendor qualification windows. Homecare channel expansion remains underpenetrated relative to institutional settings due to reimbursement fragmentation across private and public payor systems.
Clinical Nutrition Market Key Industry Players
Concentration sits with diversified healthcare conglomerates possessing vertically integrated supply chains and hospital channel contracting scale. The vendor base stratifies across three tiers: multinational pharmaceutical-nutrition hybrids with device-formula portfolios, regional formulators leveraging automated compounding technology, and specialized pediatric-oncology niche players. Competitive dynamics center on M&A activity targeting homecare distribution capabilities and strategic partnerships securing lipid emulsion supply security.
Among the diversified healthcare conglomerates, Abbott Laboratories, Nestlé Health Science, and Fresenius Kabi exemplify distinct strategic archetypes. Abbott represents the vertically integrated supply chain model with cost advantages in parenteral nutrition manufacturing. Nestlé Health Science occupies a position anchored through specialized oncology and pediatric formulation development. Fresenius Kabi sits within the hospital channel contracting tier, dominating acute care network agreements across multiple geographies. These three entities collectively illustrate how scale, specialization, and channel control define competitive positioning in clinical nutrition markets.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé Health Science |
| Danone Nutricia |
| Fresenius Kabi |
| Baxter International |
| B. Braun Melsungen AG |
| Mead Johnson Nutrition Company |
| Pfizer Inc. |
| Perrigo Company |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day formulation lead times for specialty formulas concentrate pricing power with manufacturers possessing integrated lipid emulsion sourcing, while standard enteral products face margin compression from group purchasing organization consolidation in United States hospital networks.
Pricing Analysis
The customization-premium spread reaches its widest point in oncology immunonutrition blends versus standard enteral formulas. A three-tier pricing structure across premium, standard, and economy levels dominates, with price differentiation driven by FDA medical food certification tier and volume scale through hospital GPO contracts. Pricing pressure stems from food-first protocol adoption in European long-term care facilities. Critical care units demonstrate lowest price sensitivity due to protocol-mandated early enteral feeding requirements, while oral supplement buyers in nursing facilities exhibit highest sensitivity.
Supply Chain Analysis
The United States and Germany anchor pharmaceutical-grade parenteral nutrition production, with South Korea emerging through microfluidic continuous flow reactor adoption. Soybean oil and fish oil lipid emulsions, plus amino acid premixes, constitute critical input dependencies. Supply chain risk centers on agricultural commodity volatility for lipid inputs. Distribution runs through hospital group purchasing organizations in North America and direct acute care network contracts in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against food-first protocol substitution in long-term care settings where texture-modified diets achieve comparable malnutrition outcomes at lower cost.
For Market Incumbents: Fortify hospital channel control through integrated device-formula portfolios that satisfy EU Medical Device Regulation CE marking requirements. Secure captive supply of soybean and fish oil lipid emulsions to insulate margin structures from agricultural commodity swings. Accelerate homecare dispensing capabilities ahead of Medicare reimbursement expansion for long-term enteral support. For New Entrants and Emerging Players: Differentiate on personalized amino acid profiles for pediatric and oncology segments where protocol adoption creates premium positioning. Target South Korean and German mid-scale manufacturing zones where automated compounding technology fragments contract concentration. Pursue Japan FOSHU functional nutrition claims pathway to establish distinct regulatory positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to monetize non-core clinical nutrition divisions. The five-to-ten-year viability window favors manufacturers with backward integration into lipid emulsion sourcing and software-embedded enteral delivery systems. Monitor FDA Unique Device Identification compliance timelines as inflection indicator for hospital procurement eligibility consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Device-Formula Portfolio Development | EU Medical Device Regulation CE marking requirements consolidate hospital contracts toward unified suppliers. |
| Homecare Channel Capability Buildout | Medicare reimbursement expansion for long-term enteral support redirects volume toward durable medical equipment suppliers. |
| Microfluidic Manufacturing Scale-Up | Continuous flow reactor adoption in Stuttgart and Seoul enables pharmaceutical-grade sterility without cleanroom capital. |
| Japan FOSHU Regulatory Pathway Investment | Functional nutrition claims approval creates distinct positioning beyond basic malnutrition management in Tokyo and Osaka markets. |
| Lipid Emulsion Supply Security Partnership | Soybean and fish oil sourcing agreements insulate margin structures from agricultural commodity volatility. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across hospital dietetic staff, enteral feeding device engineers, GPO contracts managers, and homecare reimbursement specialists. Primary interview insights were validated against FDA medical food labeling filings, EU Medical Device Regulation conformity assessment databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up volume modeling and top-down value triangulation were cross-referenced to ensure segmentation integrity.
Across the analysis window, forecasts were constructed through multivariate modeling of product type, application, delivery mode, and end user segmentation dimensions. CAGRs were derived from trend extrapolation calibrated to regulatory event timelines and reimbursement policy shifts. Forecast inputs incorporated FDA lot-tracking compliance deadlines, EU MDR implementation phases, and Japan FOSHU approval cycle durations.
Material uncertainties — reimbursement classification revisions, lipid commodity price shocks, and food-first protocol adoption rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory stability and hospital procurement centralization trajectories. Recalibration cycles align with material shifts in Medicare policy, EU device regulation enforcement, and automated manufacturing technology diffusion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Saudi Arabia Weight Loss Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Weight Loss Market