
 Peptide-Based Metabolic Disorders Therapeutics Market | 2026-2036
Peptide-Based Metabolic Disorders Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Peptide-Based Metabolic Disorders Therapeutics Market Analytics
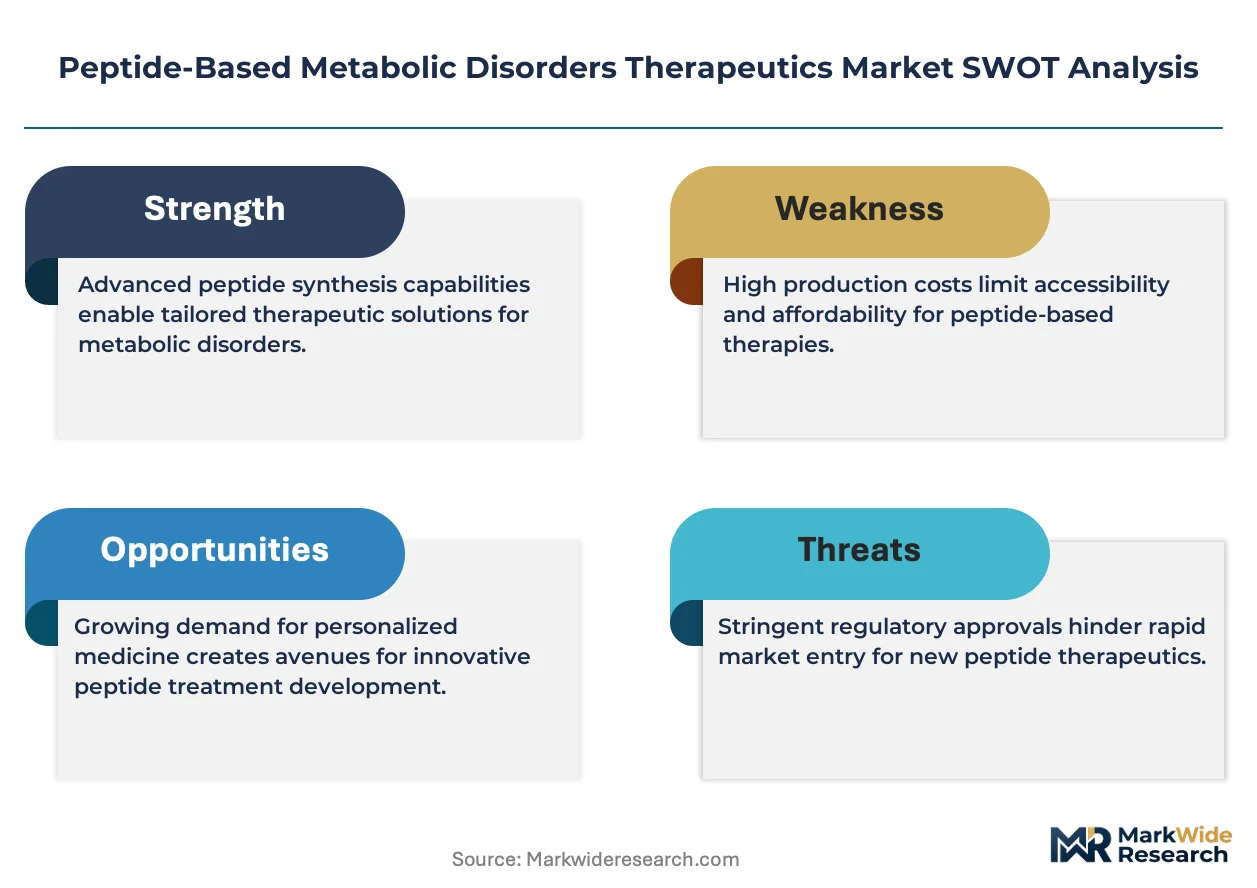
CE marking under the EU Medical Device Regulation is collapsing the window for unapproved peptide delivery systems in Europe. Novo Nordisk leverages its integrated active pharmaceutical ingredient production to sustain margin control across the GLP-1 agonist segment. Eli Lilly and Company anchors its competitive position through manufacturing scale for tirzepatide-class molecules. Sanofi competes via its established insulin analogue portfolio and channel presence in hospital and home care settings.
Peptide-based metabolic disorders therapeutics comprise synthetic or recombinant amino acid sequences engineered to modulate hormonal pathways governing glucose metabolism, lipid processing, and energy homeostasis, typically manufactured through solid-phase peptide synthesis or recombinant DNA expression in microbial or mammalian host systems with purity thresholds exceeding 95 percent. These therapeutics serve primarily to restore or augment endocrine signaling in patients whose metabolic regulation has deteriorated due to insulin resistance, beta-cell dysfunction, or adipose tissue dysregulation. GLP-1 agonists now dominate value generation as obesity indications expand beyond diabetes, while subcutaneous injection maintains its structural lock on delivery mode due to peptide instability in gastric environments. Hospital end users capture the highest acuity patient flows, though home care represents the fastest-growing administration setting as pen-device design improves.
FDA review timelines under the Center for Drug Evaluation and Research, EMA centralized procedures for biotechnology-derived medicines, and Japan's PMDA sakigake designation system collectively determine market access velocity for novel peptide entities. These frameworks incentivize developers to generate cardiovascular outcomes data early, reshaping clinical trial investment patterns. Stakeholders must monitor how CMS and national health technology assessment bodies recalibrate reimbursement for obesity-focused peptide therapies relative to legacy diabetes indications.
Market Dynamics
GLP-1 agonist capacity constraints are compressing the competitive window for peptide metabolic therapeutics, as manufacturers race to secure recombinant protein production capacity ahead of obesity label expansions.
Growth Catalysts
- Cardiovascular Outcomes Mandates:FDA guidance requiring heart safety data for obesity therapeutics is accelerating clinical trial investment in GLP-1 dual agonists. Hospital systems in Germany now prioritize formulary placement for agents with demonstrated MACE reduction.
- Japan's Sakigake Pathway:PMDA's early approval designation compresses review timelines for novel peptide entities, attracting developers seeking first-mover positioning in Asian metabolic disease management.
- Solid-Phase Peptide Synthesis Scale-Up:Contract manufacturers in Switzerland are expanding SPPS reactor capacity to address the 95-plus percent purity thresholds demanded for subcutaneous peptide formulations.
Market Restraints
- Recombinant Insulin Precursor Scarcity:Fermentation capacity for peptide expression systems concentrates among three European suppliers, creating input bottlenecks for GLP-1 analogue production.
- EMA MDR Compliance Burden:CE marking requirements for pen-injector delivery systems under the EU Medical Device Regulation extend certification timelines by 14-18 months for novel combination products.
- Oral Small-Molecule Substitution:Non-peptide GLP-1 receptor agonists in Phase III development threaten to displace injectable formulations in price-sensitive reimbursement markets.
Strategic Opportunities
- India's Metabolic Disease Burden:CDSCO's streamlined biosimilar pathway creates entry potential for peptide therapeutics targeting the country's 77 million diagnosed diabetics.
- Continuous Glucose Monitoring Convergence:Integration of peptide dosing algorithms with CGM sensor data streams enables closed-loop metabolic management systems for hospital and home settings.
- Brazil's ANVISA Fast-Track:Priority review designation for obesity therapeutics accelerates market access for peptide developers willing to generate local cardiovascular outcomes data.
Industry Challenges
- Peptide Chemist Talent Scarcity:Solid-phase synthesis expertise concentrates among aging specialist cohorts in Basel and Boston, constraining R&D expansion for emerging developers.
- Cold Chain Integrity Complexity:Temperature excursions during multi-modal distribution of refrigerated peptide formulations generate batch rejection rates that compress net margins.
- IP Thicket Navigation:Overlapping patent estates covering GLP-1 receptor binding domains and linker chemistries force licensing negotiations across multiple holder portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptide-Based Metabolic Disorders Therapeutics Market |
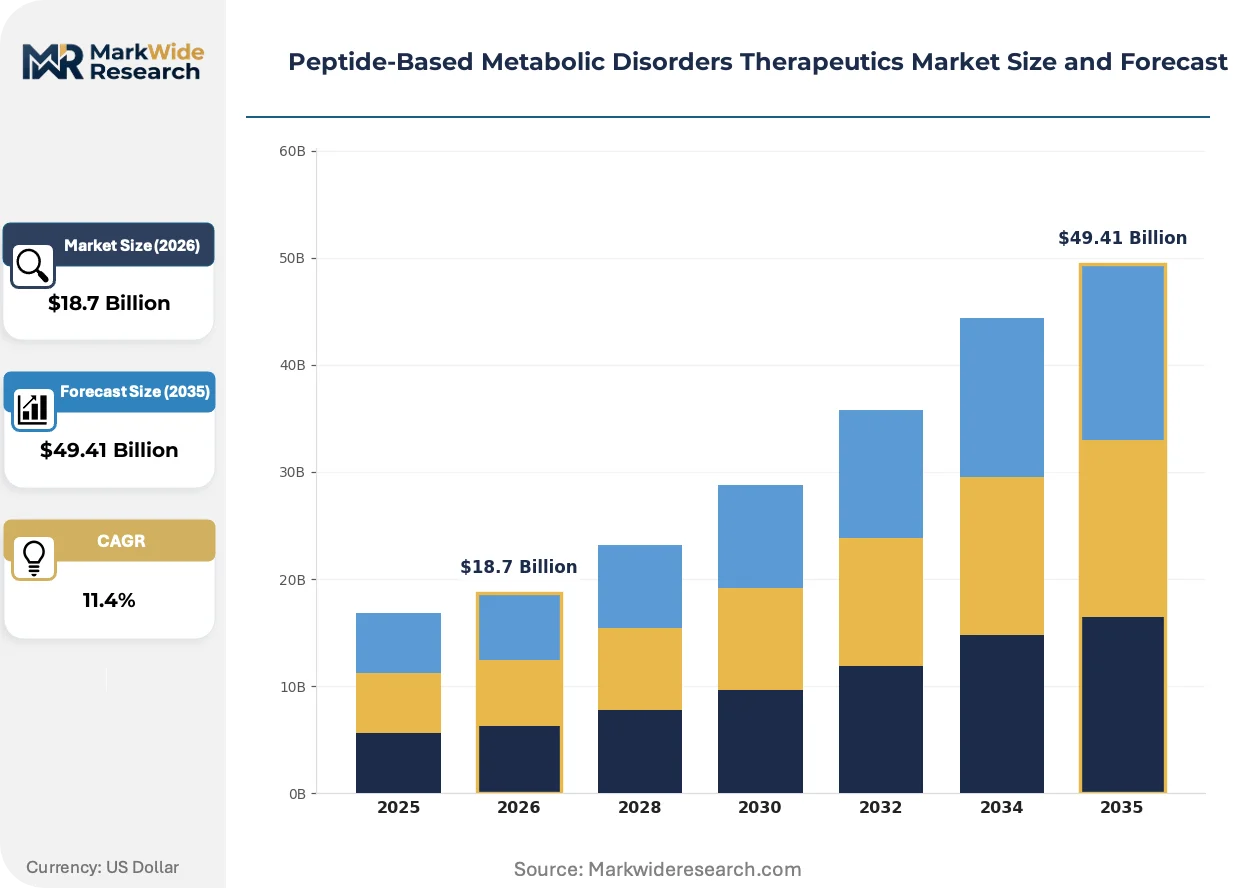
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Analogues, GLP-1 Agonists, Amylin Mimetics, Somatostatin Analogues Delivery Mode: Subcutaneous Injection, Intravenous Infusion, Oral Administration, Inhalation End User: Hospitals, Specialty Clinics, Home Care, Research Institutes Application: Type 2 Diabetes, Obesity, Hyperlipidemia, Cachexia |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Sanofi, AstraZeneca, Amgen Inc., Pfizer Inc., Takeda Pharmaceutical Company Limited, GSK plc, Ipsen Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptide-Based Metabolic Disorders Therapeutics Market Evolving Landscape
Peptide metabolic therapeutics are undergoing platform-level transformation as delivery technology, regulatory science, and care setting economics converge to reshape competitive boundaries.
Micro-needle array patches for transdermal peptide delivery are fragmenting the subcutaneous injection monopoly that has dominated GLP-1 administration for two decades. Home care providers in Japan and the United States are piloting these devices for insulin and dual-agonist classes, compressing the acute-care dependency that has structured reimbursement contracts. Hospital systems are responding by reconfiguring their metabolic disease service lines around device-mediated self-administration.
EMA's centralized procedure for biotechnology-derived medicines now mandates real-world evidence submission alongside traditional randomized trial data, altering the evidence-generation burden for peptide developers seeking European market access. Manufacturers must invest in patient registries and digital biomarker collection infrastructure to satisfy this dual-evidence standard. The requirement disproportionately affects mid-cap developers lacking existing pharmacovigilance networks.
Integrated delivery networks in the United States are consolidating peptide therapeutic procurement under pharmacy benefit manager umbrellas, displacing the physician-led prescribing autonomy that structured historical GLP-1 adoption. Hospital formularies now negotiate value-based contracts tying reimbursement to HbA1c and weight-loss thresholds. This concentration is most visible in the Midwest, where three IDNs control access for populations exceeding 12 million covered lives.
Peptide-Based Metabolic Disorders Therapeutics Market Segmentation
Channel configuration determines which peptide formulations achieve formulary placement. Hospital procurement committees, specialty clinic networks, and direct-to-patient distribution each favor distinct product specifications and delivery technologies.
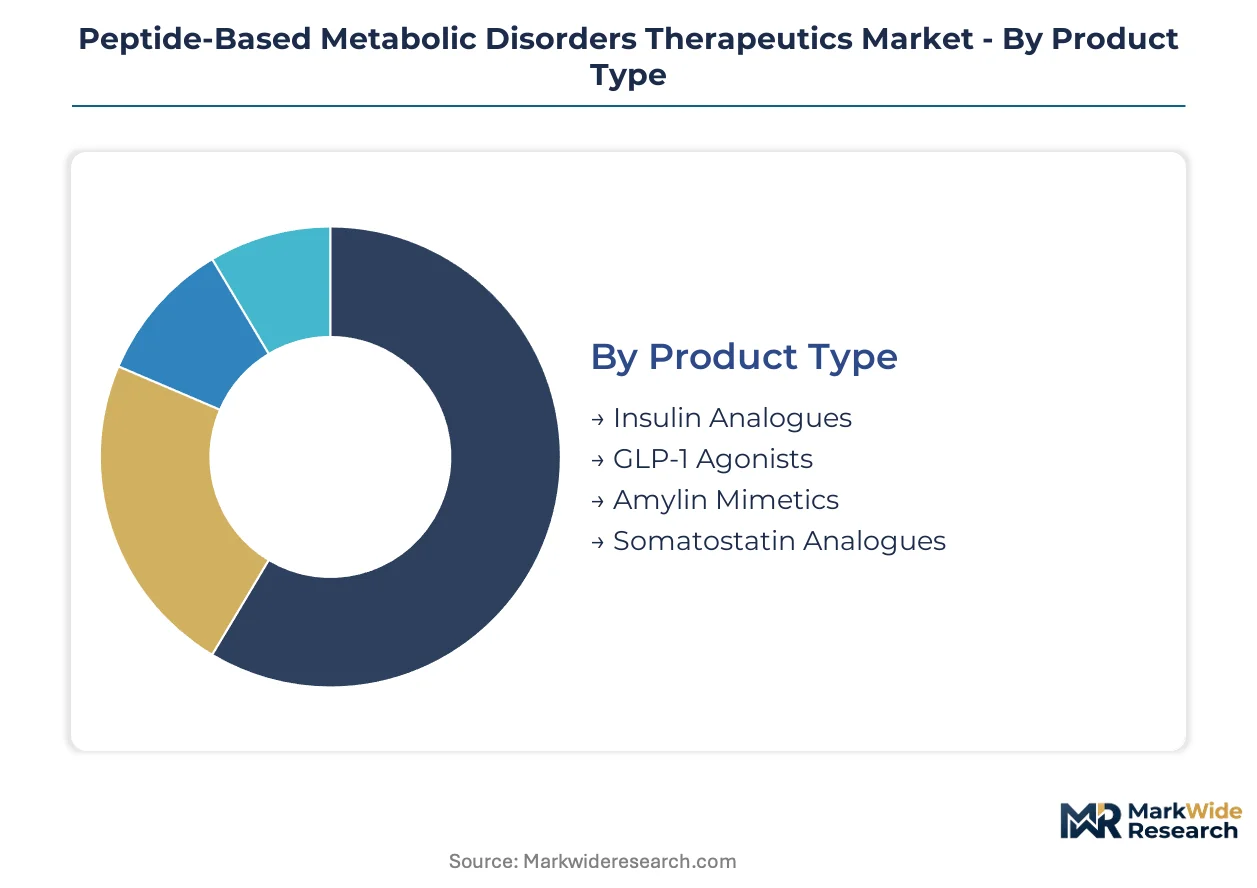
Product Type:
Channel mix varies sharply across peptide classes, with hospital formularies prioritizing GLP-1 agonists while specialty clinics manage insulin analogue titration protocols.
- Insulin Analogues:Recombinant human insulin variants with modified amino acid sequences to extend pharmacokinetic profiles or accelerate onset. Demand clusters in Germany and Japan where reimbursement frameworks support intensive insulin therapy for beta-cell failure. Manufacturing concentrates among established fermentation facilities with decades of regulatory history.
- GLP-1 Agonists:Synthetic peptides mimicking glucagon-like peptide-1 to stimulate glucose-dependent insulin secretion and suppress appetite. Hospital systems in the United States now prioritize dual-agonist formulations with cardiovascular outcomes data, while home care channels drive volume for once-weekly dosing options.
- Amylin Mimetics:Pramlintide-class adjunct therapies for mealtime glucose control in insulin-treated patients.
- Somatostatin Analogues:Cyclic peptides targeting growth hormone suppression in metabolic comorbidities.
GLP-1 agonists dominate installed base. Insulin analogues are where expansion concentrates in price-sensitive reimbursement markets.
Delivery Mode:
Cost tier stratification separates premium pen-injector systems from standard vial-and-syringe formats, with reimbursement pressure driving divergence between hospital and home care procurement.
- Subcutaneous Injection:Pen devices and pre-filled syringes delivering peptides into adipose tissue with bioavailability exceeding 90 percent. Specialty clinics in Switzerland and the United States prescribe disposable pens for GLP-1 agonists, while hospital pharmacies retain multi-dose vials for insulin analogues to minimize per-dose cost.
- Intravenous Infusion:Hospital-administered delivery for acute metabolic decompensation or perioperative glucose management. Demand concentrates in tertiary care centers managing diabetic ketoacidosis or hyperosmolar states.
- Oral Administration:Experimental peptide formulations with absorption enhancers or structural modifications to resist gastric degradation.
- Inhalation:Pulmonary delivery systems for rapid-acting insulin variants, limited by lung function screening requirements.
Subcutaneous injection commands volume leadership. Oral administration is climbing the fastest as developers overcome bioavailability barriers.
End User:
Customer type determines pricing tolerance and service intensity, with hospital systems negotiating value-based contracts while home care channels prioritize convenience features.
- Hospitals:Acute care and outpatient departments managing metabolic emergencies, perioperative glucose control, and initiation of injectable therapies. Formulary committees in Germany and Japan require cardiovascular outcomes documentation for obesity-focused peptide placement.
- Specialty Clinics:Endocrinology and diabetology practices providing dose titration, patient education, and metabolic monitoring. These settings in the United States are consolidating under integrated delivery network umbrellas.
- Home Care:Self-administration settings supported by visiting nurses or remote monitoring infrastructure.
- Research Institutes:Academic medical centers conducting investigator-initiated trials and real-world evidence generation.
Hospitals anchor revenue per patient. Home care is gaining share fastest as pen-device design improves and reimbursement shifts toward outpatient management.
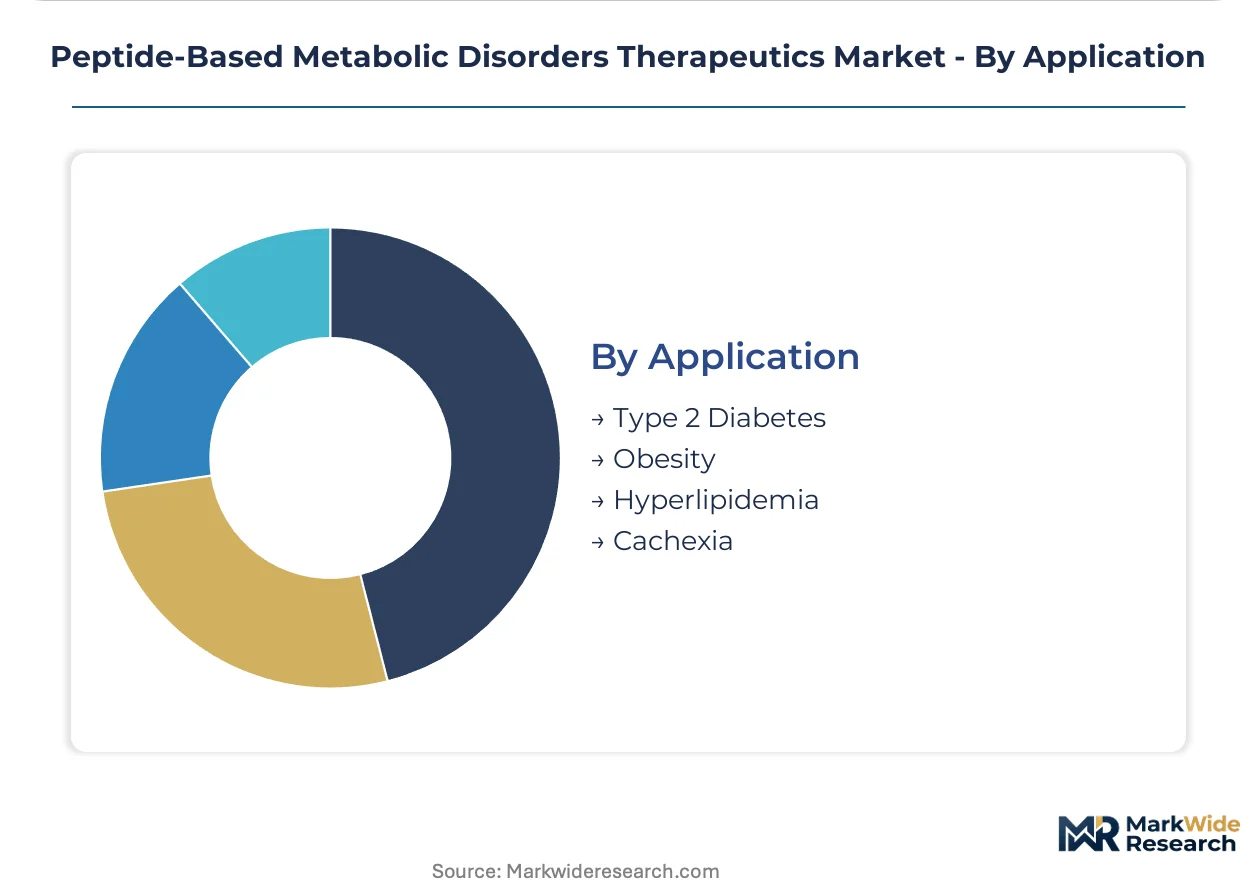
Application:
Volume-maturity dynamics separate established diabetes indications from emerging obesity applications, with regulatory pathways and evidence requirements diverging accordingly.
- Type 2 Diabetes:The foundational indication for peptide metabolic therapeutics, with decades of clinical evidence supporting HbA1c reduction endpoints. Hospital systems in Japan and the United States maintain standardized protocols for GLP-1 agonist and insulin analogue sequencing.
- Obesity:Weight management applications now driving GLP-1 agonist demand beyond diabetes populations, with FDA cardiovascular safety requirements extending trial timelines. PMDA's sakigake pathway accelerates access for agents demonstrating MACE reduction.
- Hyperlipidemia:Adjunctive peptide therapy targeting residual cardiovascular risk in statin-treated patients.
- Cachexia:Metabolic wasting disorders with limited approved peptide interventions.
Type 2 diabetes maintains installed base dominance. Obesity shows the steepest expansion trajectory as label expansions and reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites European distribution of temperature-sensitive peptide formulations, while direct rail links from Basel to Milan anchor continental manufacturing logistics for metabolic therapeutics.
United States
Hospital formulary consolidation under integrated delivery networks concentrates procurement power in the Midwest and Southeast. FDA's Center for Drug Evaluation and Research mandates cardiovascular outcomes data for obesity label expansions, extending trial timelines. The Greater Boston corridor hosts contract manufacturers expanding solid-phase peptide synthesis capacity for GLP-1 agonist production.
Germany
Statutory health insurance funds prioritize agents with demonstrated MACE reduction for metabolic disease management. EMA centralized procedures for biotechnology-derived medicines require real-world evidence alongside trial data. The Rhine-Main region around Frankfurt maintains fermentation facilities supplying recombinant insulin precursors to European peptide manufacturers.
Japan
PMDA's sakigake designation compresses review timelines for novel peptide entities targeting diabetes and obesity. The national health insurance system reimburses GLP-1 agonists for type 2 diabetes with strict HbA1c thresholds. The Kansai corridor between Osaka and Kobe concentrates pen-device manufacturing for subcutaneous peptide delivery systems.
Switzerland
Contract development and manufacturing organizations around Basel command premium pricing for 95-plus percent purity peptide synthesis. Swissmedic alignment with EMA procedures accelerates parallel market access across European and domestic channels. The Lake Geneva region maintains specialized logistics infrastructure for temperature-controlled distribution of biologic formulations.
India
CDSCO's streamlined biosimilar pathway attracts developers targeting the country's diagnosed diabetic population with peptide therapeutics. Price-controlled insulin formulations under national pharmaceutical pricing authority regulations compress margins for imported analogues. The Hyderabad-Bangalore corridor hosts active pharmaceutical ingredient manufacturers expanding recombinant expression capacity for export markets.
Peptide-Based Metabolic Disorders Therapeutics Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and therapeutic focus, producing a tiered structure where integrated pharmaceutical conglomerates anchor volume while biotechnology specialists capture premium positioning. The competitive terrain separates fermentation-based recombinant producers from synthetic peptide chemists. Three archetypes dominate: vertically integrated API-to-formulation operators, pure-play peptide synthesis specialists, and diversified diabetes care portfolios. Capacity expansion and cardiovascular outcomes data generation constitute the dominant competitive moves reshaping market access.
Among European-anchored integrated operators, Novo Nordisk and Sanofi occupy positions exemplifying fermentation-based recombinant production scale, while Eli Lilly and Company represents North American manufacturing depth for dual-agonist peptide classes. These three entities anchor distinct competitive vectors—Nordic API integration, Franco-German insulin heritage, and American trial infrastructure density—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Amgen Inc. |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| GSK plc |
| Ipsen Pharma |
| Others |
Value Network & Pricing Analysis
Solid-phase peptide synthesis capacity replacing legacy recombinant fermentation for GLP-1 agonist production is redrawing manufacturing geography toward Swiss and Boston contract manufacturers while compressing per-gram pricing premiums for high-purity sequences. This substitution simultaneously concentrates supply among specialized chemist cohorts and intensifies cost competition as purity thresholds standardize across hospital procurement committees.
Pricing Analysis
Certification level under EMA MDR and FDA quality systems creates the primary spread between premium pen-injector systems and standard vial formats. Three-tier pricing structure across premium, standard, and economy levels segments hospital formulary placement from home care direct distribution. Cost compression in economy-tier insulin analogues is intensifying because India's price-controlled formulations anchor regional reference pricing. Hospital systems in Germany demonstrate least price sensitivity due to statutory reimbursement for MACE-documented agents, while cash-pay obesity patients in Brazil exhibit highest sensitivity to per-dose out-of-pocket costs.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for temperature-controlled peptide shipments from Basel fermentation facilities to Japanese pen-device manufacturers. Supply concentrates in Switzerland for 95-plus percent purity synthesis, Germany for recombinant insulin precursors, and the United States for dual-agonist fill-finish operations. Raw material dependencies span amino acid precursors from Chinese fermentation bases, specialized resins for SPPS columns, and medical-grade elastomers for injector components. Single-source vulnerability concentrates among three European recombinant expression suppliers. Distribution runs through hospital procurement committees for acute-care volume and specialty pharmacy channels for home care self-administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GLP-1 agonist label expansion into cardiovascular risk reduction represents a regulatory inflection that will double addressable patient populations and reshape competitive economics for peptide metabolic therapeutics.
For Market Incumbents: Fortify manufacturing scale through captive solid-phase peptide synthesis capacity in Basel or Greater Boston corridors to offset recombinant precursor scarcity. Prioritize cardiovascular outcomes data generation under FDA guidance to secure hospital formulary placement against emerging oral small-molecule substitutes. Channel control through integrated delivery network contracting anchors defensive positioning. For New Entrants and Emerging Players: Home care algorithm integration with continuous glucose monitoring data streams offers white-space penetration where incumbents under-serve closed-loop metabolic management. Target India's CDSCO biosimilar pathway for peptide therapeutics addressing the country's diagnosed diabetic population with localized cardiovascular outcomes generation. Direct-to-patient distribution partnerships with Japanese home nursing networks provide go-to-market acceleration. For Investors and Strategic Acquirers: The market sits at a capacity-constrained expansion phase that favors mid-cap peptide synthesis specialists with existing EMA MDR certification infrastructure. Long-term viability across the analysis window hinges on backward integration into amino acid precursor supply and real-world evidence collection capabilities. Watch for PMDA sakigake designation awards as inflection signals for first-mover positioning in Asian metabolic disease management.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcomes Trial Investment | FDA's MACE data requirement for obesity label expansion reshapes clinical trial allocation across GLP-1 dual-agonist pipelines. |
| Solid-Phase Peptide Synthesis Scale-Up | Swiss and Boston contract manufacturers expanding SPPS reactor capacity address 95-plus percent purity thresholds for subcutaneous formulations. |
| EMA MDR Certification Pathway | CE marking compliance for pen-injector combination products extends market access timelines by 14-18 months for European hospital procurement. |
| Integrated Delivery Network Contracting | Midwestern United States IDNs consolidating peptide therapeutic procurement under pharmacy benefit manager umbrellas displace physician-led prescribing autonomy. |
| Real-World Evidence Infrastructure | Patient registries and digital biomarker collection satisfy EMA's dual-evidence standard for biotechnology-derived medicines market access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Secondary validation drew from FDA filings, EMA centralized procedure submissions, ClinicalTrials.gov protocol databases, and hospital procurement system records. Bottom-up patient-flow modeling and top-down therapeutic class revenue triangulation anchored market size estimation.
Across the analysis window, the forecasting framework modeled segmentation by product type, delivery mode, end user, and application with regional regulatory cluster overlays. CAGRs were derived from treatment-line expansion rates, reimbursement pathway maturation, and manufacturing capacity absorption curves. Industry-specific inputs included GLP-1 agonist prescription volume trajectories, cardiovascular outcomes trial completion timelines, and biosimilar pathway adoption patterns.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA review frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Asia Pacific Liver Cancer Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Nasal Polyposis Treatment Market