
 Saudi Arabia Weight Loss Market | 2026-2036
Saudi Arabia Weight Loss Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Weight Loss Market Intelligence
Telehealth integration into personalized coaching protocols is tilting service delivery toward hybrid digital-physical models. WW International Inc leverages its app-based tracking ecosystem to sustain subscriber retention across Gulf markets. Herbalife Ltd anchors its position through direct-selling networks that dominate nutrition club penetration in secondary Saudi cities. Abbott Laboratories competes in the clinical nutrition segment with hospital-formulated meal replacements tailored to metabolic screening protocols.
Weight loss encompasses calibrated caloric deficit interventions delivered through nutraceutical formulations, controlled-portion food systems, exercise apparatus, and supervised behavioral programs designed to reduce adiposity and mitigate obesity-related comorbidities. Dietary supplements and meal replacement products command the largest revenue share due to recurring purchase patterns and pharmacy shelf dominance, while fitness equipment experiences faster velocity through home-gym adoption and hotel wellness partnerships. Low-calorie food formulations remain underdeveloped relative to Western markets, signaling latent margin expansion for reformulated traditional cuisine products.
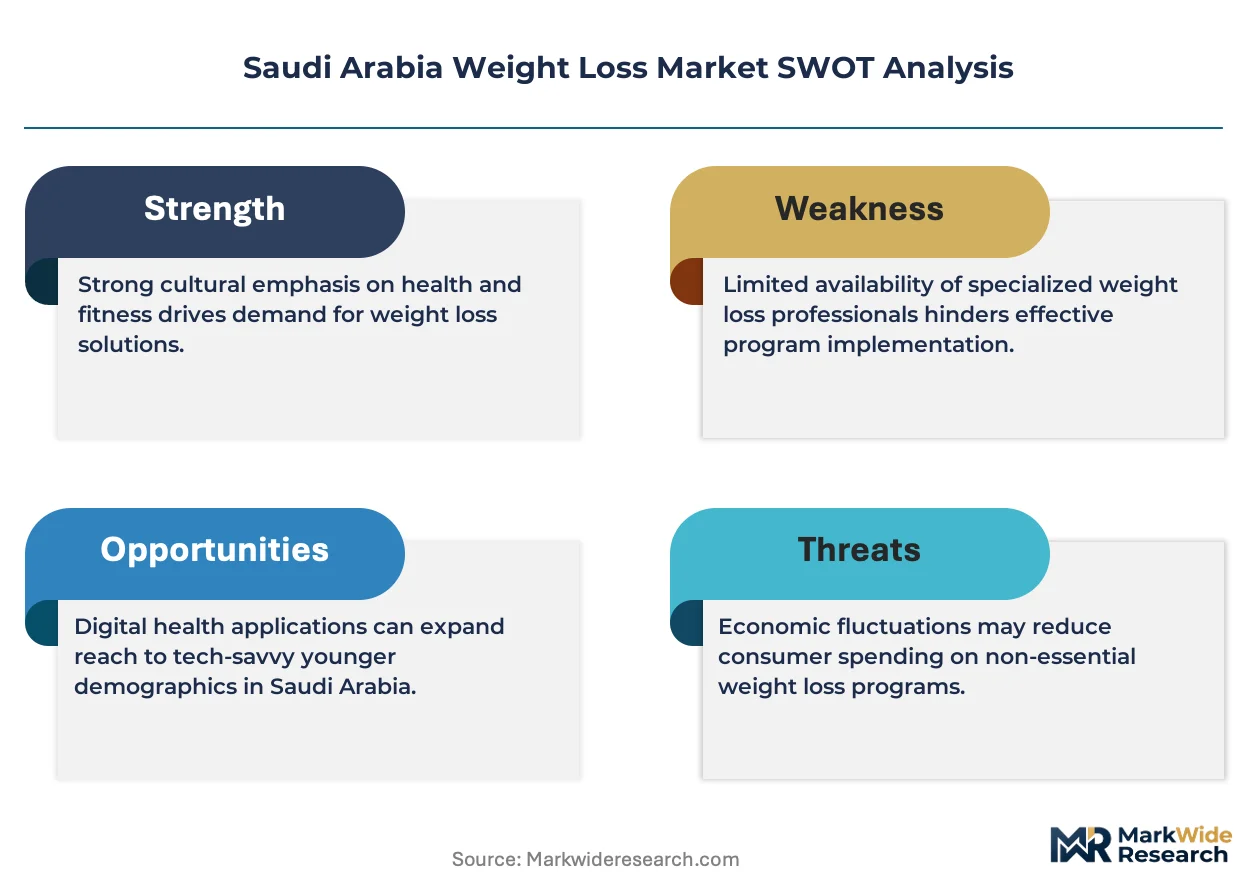
SFDA registration requirements for weight loss supplements and the Saudi Food and Drug Authority's enforcement of GMP manufacturing standards are elevating barriers for unverified imports. MOHAP licensing frameworks for bariatric surgery centers and nutritional counseling clinics restrict market access to credentialed providers. Stakeholders must monitor evolving halal certification protocols for protein sourcing and the kingdom's hospital privatization trajectory, which will redistribute patient flows between public bariatric programs and premium private operators.
Market Dynamics
SFDA enforcement of GMP manufacturing standards and halal certification protocols is restructuring competitive access, privileging domestic manufacturers with verified supply chains while elevating compliance costs for import-dependent distributors serving hospital and pharmacy channels.
Growth Catalysts
- Hospital Privatization Trajectory:The kingdom's redistribution of patient flows from public bariatric programs to premium private operators is expanding addressable market for structured weight management services and clinical nutrition protocols.
- Corporate Wellness Mandates:Saudi enterprises are expanding procurement of structured weight management services as employee health benefits, creating institutional demand anchors beyond individual consumer purchases.
- Telehealth Integration:Hybrid digital-physical coaching models are digitizing service delivery infrastructure and extending reach into secondary cities beyond Riyadh and Jeddah clinical clusters.
Market Restraints
- SFDA Registration Friction:The Saudi Food and Drug Authority's tightening oversight of dietary supplement labeling and health claims is elevating barriers for unverified imports and extending product approval timelines.
- Protein Sourcing Constraints:Evolving halal certification requirements for animal and plant-based protein inputs are constraining formulation flexibility and supplier qualification pools.
- MOHAP Licensing Restrictions:The Ministry of Health and Prevention's credentialing frameworks for bariatric surgery centers and nutritional counseling clinics restrict market access to verified providers.
Strategic Opportunities
- Traditional Cuisine Reformulation:Low-calorie food formulations remain underdeveloped relative to Western markets, signaling latent margin expansion for culturally adapted portion-controlled products.
- Secondary City Penetration:Direct-selling networks currently dominate nutrition club presence in cities beyond Riyadh and Jeddah, creating whitespace for pharmacy and retail channel expansion.
- Hotel Wellness Partnerships:Fitness equipment is experiencing accelerated velocity through hospitality sector adoption, opening B2B procurement channels distinct from traditional home-gym and clinic sales.
Industry Challenges
- Behavioral Program Adherence:Sustained engagement in supervised weight management protocols requires specialized coaching talent that remains concentrated in major metropolitan clinical clusters.
- Supply Chain Reconfiguration:Manufacturers must rebuild sourcing relationships to satisfy simultaneous SFDA compliance, halal verification, and hospital privatization procurement standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Weight Loss Market |
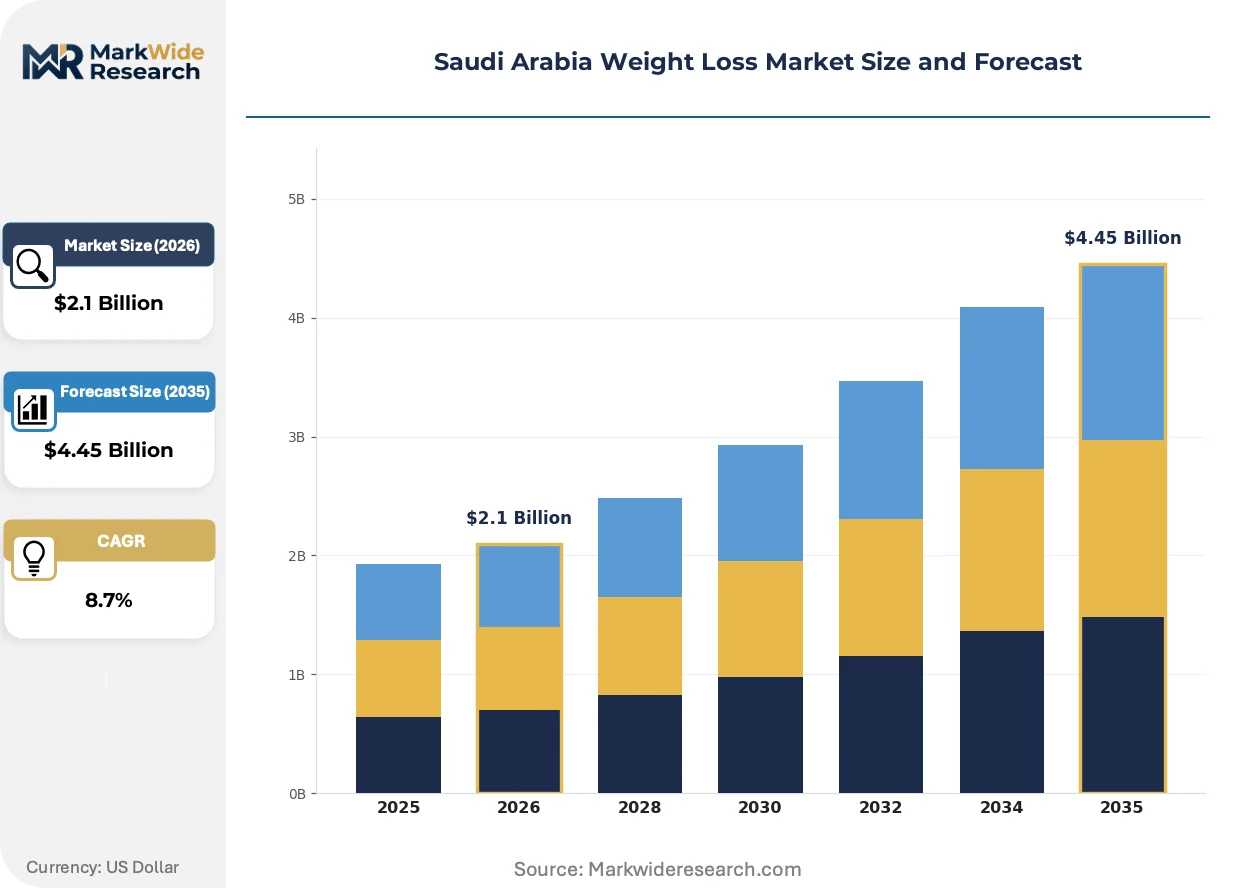
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Meal Replacement, Low-Calorie Food, Fitness Equipment Service Type: Weight Management Programs, Nutritional Counseling, Fitness Training, Personal Coaching Distribution Channel: Supermarkets, Online Retail, Pharmacies, Health Stores Customer Type: Individuals, Corporate Clients, Fitness Enthusiasts, Health-Conscious Consumers |
| Companies Covered | WW International Inc, Dr. Bernstein Diet & Health Clinics, Herbalife Ltd, Abbott Laboratories, Nestle SA, Atkins, Nutrisystem, Glanbia PLC, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Weight Loss Market Strategic Shifts & Innovations
Service delivery models are converging around measurable outcome protocols, while product formulation and distribution infrastructure undergo parallel digitization and compliance adaptation.
Continuous glucose monitoring integration with personalized coaching platforms is digitizing metabolic feedback loops for weight management subscribers. Hospital-affiliated bariatric centers in Riyadh are piloting these systems for pre- and post-surgical patients. The technology is digitizing adherence tracking and enabling real-time caloric adjustment protocols previously unavailable outside specialized metabolic clinics.
SFDA's phased implementation of digital labeling requirements and traceability mandates is compressing documentation burdens onto manufacturers while creating competitive separation between compliant domestic producers and import-dependent distributors. Secondary packaging and lot-tracking systems are receiving capital allocation priority ahead of formulation R&D in corporate budgeting cycles.
Subscription-based meal replacement procurement is displacing single-transaction pharmacy purchases among urban professional segments. Direct-to-consumer fulfillment networks are capturing volume previously routed through retail pharmacy channels, with Riyadh and Jeddah metropolitan zones showing earliest concentration of this behavioral shift.
Saudi Arabia Weight Loss Market Segmentation
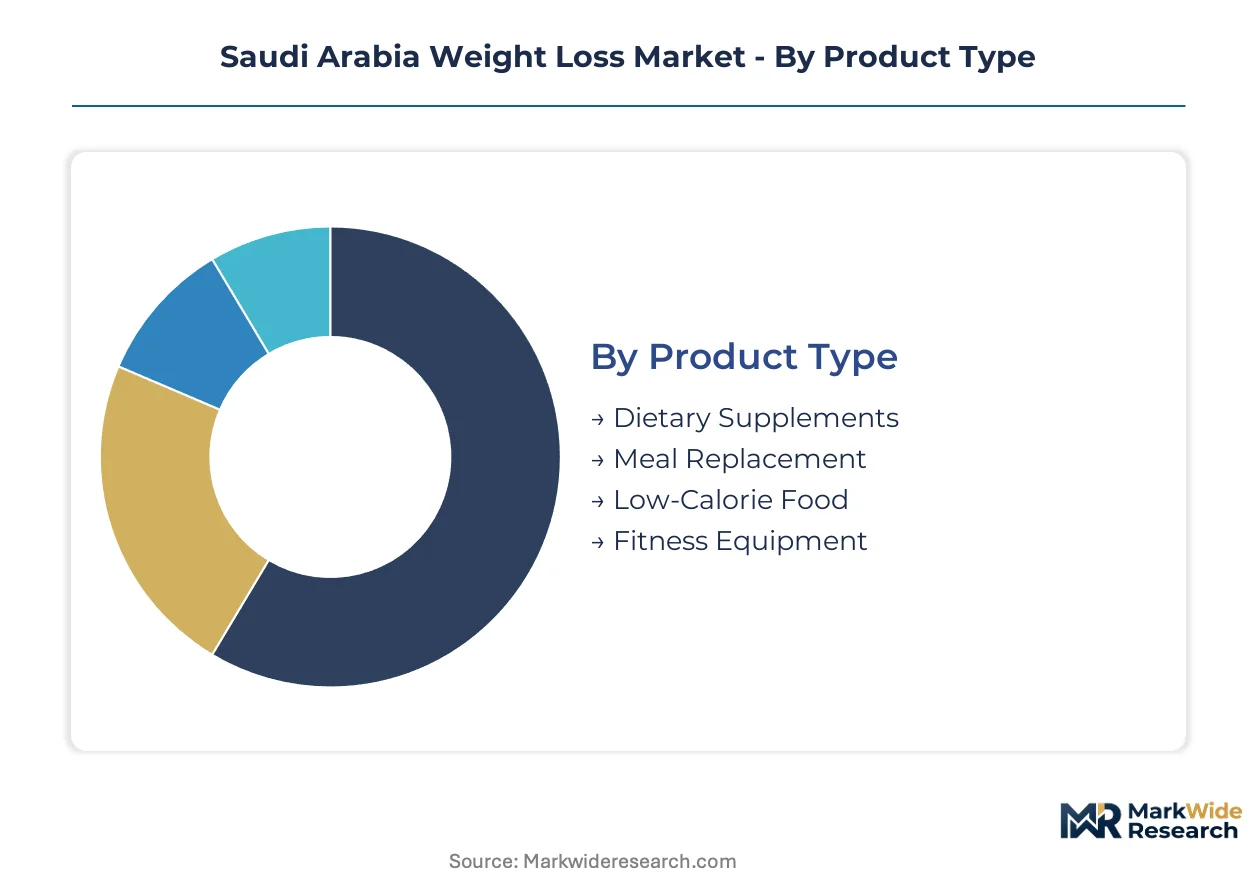
Segmentation in the Saudi Arabia weight loss market reveals distinct velocity patterns across product, service, and channel dimensions. Purchase cycles vary from daily supplement consumption to multi-year corporate wellness contracts, creating differentiated margin and retention profiles for operators.
Product Type:
Dietary supplements turn inventory fastest through pharmacy impulse purchases, while fitness equipment cycles slowest through extended B2B procurement timelines.
- Dietary Supplements:Formulations include thermogenic compounds, fiber blends, and herbal extracts delivered in capsule, powder, and liquid formats. Demand clusters in Riyadh pharmacy chains where SFDA registration requirements favor established domestic distributors with verified halal supply chains.
- Meal Replacement:Portion-controlled shakes and bars with calibrated macronutrient profiles support structured caloric deficit protocols. Hospital-affiliated bariatric centers in Jeddah drive institutional procurement as pre- and post-surgical nutrition protocols expand.
- Low-Calorie Food:Reformulated traditional Saudi dishes with reduced fat and carbohydrate content target cultural dietary adherence. Product development lags Western markets, signaling whitespace for localized formulation.
- Fitness Equipment:Home-gym apparatus and commercial-grade machines serve individual and hospitality sector buyers. Hotel wellness partnerships in secondary cities accelerate velocity beyond traditional retail channels.
Dietary supplements anchor the volume base while fitness equipment gains share at the steepest rate.
Service Type:
Cost tiers separate premium personalized coaching from standardized group programming, with reimbursement eligibility determining corporate procurement decisions.
- Weight Management Programs:Structured multi-week protocols combining dietary intervention, physical activity, and behavioral modification. Corporate wellness mandates in Riyadh-based enterprises drive B2B subscription growth.
- Nutritional Counseling:Registered dietitian consultations for metabolic screening and customized meal planning. MOHAP licensing requirements restrict provider pools to credentialed practitioners in major metropolitan clusters.
- Fitness Training:Supervised exercise protocols delivered through gym-based and digital platforms. Hybrid telehealth integration extends reach into secondary cities beyond Jeddah clinical hubs.
- Personal Coaching:One-on-one behavioral support with continuous accountability mechanisms. Premium pricing targets high-income professionals seeking sustained engagement beyond standardized programs.
Weight management programs generate the highest institutional revenue concentration while personal coaching expands most quickly among affluent urban segments.
Distribution Channel:
Volume concentration favors physical retail, though fulfillment infrastructure investment is tilting capital allocation toward direct-to-consumer platforms.
- Supermarkets:Mass-market placement of meal replacement and low-calorie food products. Shelf space competition intensifies as multinational brands expand Gulf distribution networks.
- Online Retail:Subscription-based replenishment models for supplements and specialized nutrition products. Riyadh and Jeddah metropolitan zones show earliest concentration of platform migration.
- Pharmacies:Primary channel for SFDA-registered supplements with pharmacist consultation support. Retail pharmacy chains dominate secondary city penetration where direct-selling networks face regulatory friction.
- Health Stores:Specialized retailers targeting fitness enthusiasts with premium equipment and performance nutrition. Store footprint remains concentrated in affluent urban districts.
Pharmacies retain the largest transaction volume while online retail climbs the fastest among professional consumer segments.
Customer Type:
Application context separates medical necessity from lifestyle optimization, with reimbursement pathways and discretionary budget cycles determining contract structures.
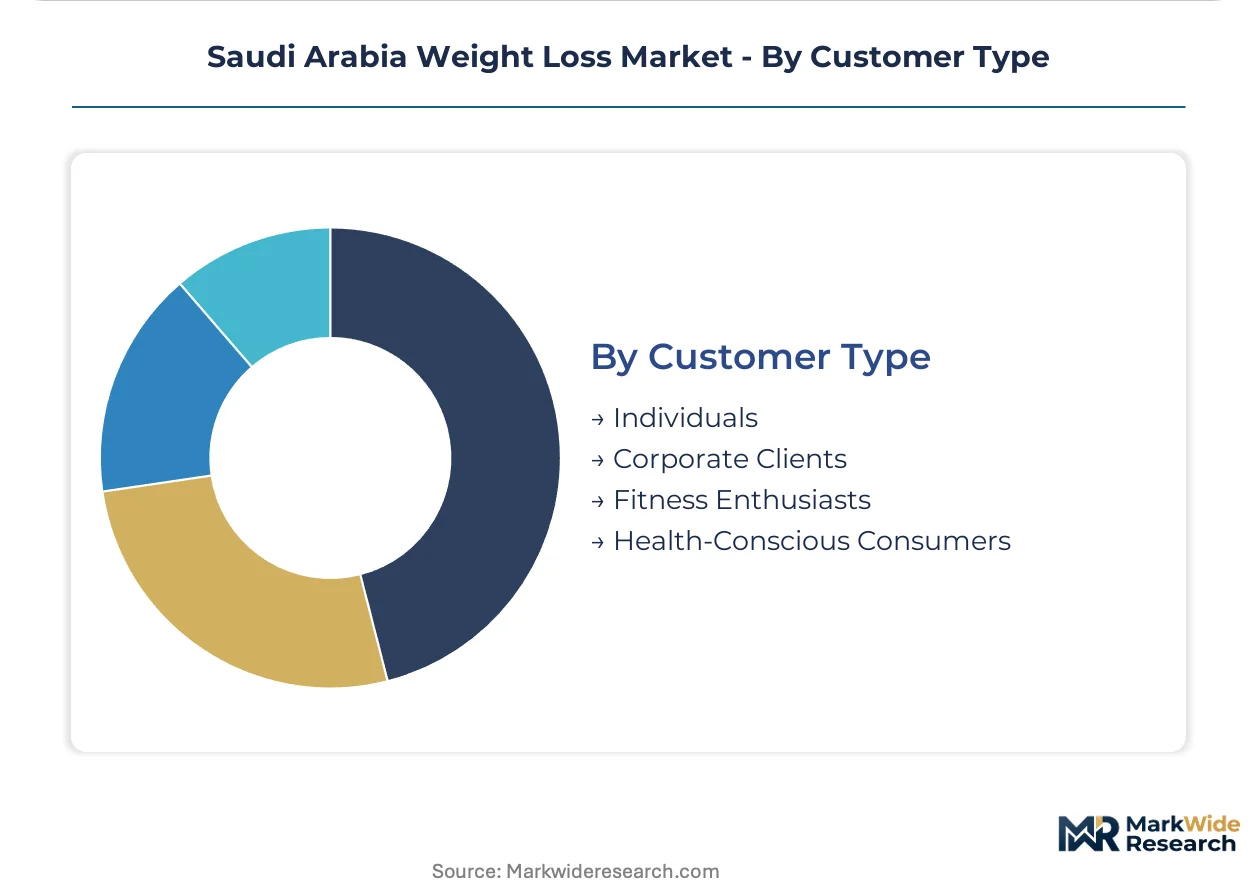
- Individuals:Self-directed consumers purchasing supplements, equipment, and coaching through retail and digital channels. Price sensitivity varies across income tiers and urban density gradients.
- Corporate Clients:Enterprises procuring structured wellness services as employee benefit programs. Procurement decisions integrate HR budget cycles and insurance reimbursement frameworks.
- Fitness Enthusiasts:Performance-oriented buyers seeking advanced equipment and specialized nutrition protocols. This segment drives premium product innovation and early technology adoption.
- Health-Conscious Consumers:Preventive-focused individuals prioritizing long-term metabolic health over acute weight reduction. Demand concentrates in educated professional demographics with sustained disposable income.
Individuals constitute the broadest addressable base while corporate clients deliver the steepest contract value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate wellness procurement concentrates in Riyadh-based enterprises, while private bariatric demand clusters in Jeddah clinical hubs. Secondary cities remain dependent on direct-selling networks for nutrition access. The kingdom's hospital privatization redistributes patient flows between public programs and premium operators.
Riyadh
Hospital-affiliated bariatric centers and corporate wellness mandates drive institutional demand for structured weight management services. SFDA registration requirements for dietary supplements favor established domestic distributors with verified halal supply chains. The Riyadh metropolitan zone shows earliest concentration of subscription-based meal replacement procurement migrating to direct-to-consumer platforms.
Jeddah
Private fitness chains and premium coaching services target high-income professionals seeking sustained behavioral engagement. MOHAP licensing frameworks for nutritional counseling clinics restrict provider pools to credentialed practitioners. Western Region clinical clusters pilot continuous glucose monitoring integration with personalized coaching platforms for pre- and post-surgical patients.
Eastern Province
Industrial workforce wellness programs create B2B demand anchors for structured weight management protocols. Corporate procurement decisions integrate HR budget cycles and insurance reimbursement frameworks. Dammam and Khobar enterprise clusters expand employee health benefit coverage to include supervised metabolic screening and meal planning services.
Secondary Cities
Direct-selling networks dominate nutrition club penetration in urban centers beyond the major metropolitan hubs. Pharmacy retail chains face whitespace opportunity as regulatory friction constrains unverified import distribution. Hotel wellness partnerships in hospitality corridors accelerate fitness equipment velocity through B2B procurement channels distinct from home-gym sales.
NEOM Northwest
Emerging wellness infrastructure development targets health-conscious professional demographics relocating to the giga-project zone. Telehealth integration extends personalized coaching reach into geographically dispersed populations. Procurement standards for clinical nutrition protocols align with hospital privatization trajectory requirements for premium private operator credentialing.
Saudi Arabia Weight Loss Market Key Industry Players
Channel-controlling players compete with product-specialist players across pharmacy retail, direct-selling networks, and digital subscription platforms. The vendor base stratifies between multinational nutrition conglomerates with Gulf distribution networks and domestic distributors with SFDA-verified halal supply chains. Two archetypes dominate: direct-selling network operators leveraging nutrition club penetration, and clinical nutrition formulators supplying hospital-affiliated bariatric centers. Competitive moves concentrate on telehealth integration for coaching retention and traditional cuisine reformulation for cultural dietary adherence.
Within the direct-selling archetype, Herbalife Ltd exemplifies network-based nutrition club expansion into secondary Saudi cities. WW International Inc occupies a position in hybrid digital-physical service delivery through app-based tracking ecosystems. Abbott Laboratories represents the clinical nutrition tier with hospital-formulated meal replacement protocols. These three anchors illustrate the competitive tension between consumer-facing subscription models and institutional procurement channels reshaping market access patterns.
| Leading Market Players |
|---|
| WW International Inc |
| Dr. Bernstein Diet & Health Clinics |
| Herbalife Ltd |
| Abbott Laboratories |
| Nestle SA |
| Atkins |
| Nutrisystem |
| Glanbia PLC |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
SFDA registration friction as a regulatory chokepoint determines both pricing tier spreads and supply chain shape by elevating compliance costs for import-dependent distributors while privileging domestic manufacturers with verified halal supply chains. This structural barrier compresses margins for unverified imports and creates three distinct pricing tiers based on certification status and channel access.
Pricing Analysis
Cost-plus contracts with halal certification indexation anchor institutional procurement between hospital-affiliated bariatric centers and clinical nutrition suppliers. Pricing stratifies across SFDA-registered premium tiers, MOHAP-licensed standard tiers, and unverified economy imports facing channel restrictions. Cost compression in the economy tier intensifies as direct-to-consumer platforms disintermediate retail pharmacy markups. Corporate wellness buyers show lowest price sensitivity due to insurance reimbursement frameworks, while individual supplement purchasers in secondary cities demonstrate highest elasticity.
Supply Chain Analysis
Tariff exposure between manufacturing hubs in China and India and the Saudi market dominates supply chain risk assessment for dietary supplement inputs. Raw material sourcing draws from Malaysian palm-derived compounds, Indian herbal extracts, and Chinese thermogenic precursors. Single-source vulnerability concentrates in specialized halal-certified protein isolates from Southeast Asian suppliers. Distribution runs through Riyadh and Jeddah pharmaceutical wholesale clusters before radiating to secondary city retail chains and direct-selling network nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia weight loss market sits in early-cycle expansion as hospital privatization redirects patient flows toward premium private operators and corporate wellness mandates institutionalize structured weight management procurement.
For Market Incumbents: Insulate market position by deepening backward integration into halal-certified protein sourcing and securing MOHAP licensing ahead of privatization-driven capacity expansion. Prioritize telehealth platform development to retain subscribers against hybrid digital-physical entrants. Defensive certification investment in SFDA digital labeling infrastructure creates competitive separation from import-dependent distributors facing extended approval timelines. For New Entrants and Emerging Players: Secondary city pharmacy retail whitespace represents the most penetrable entry point as direct-selling networks face regulatory friction and established distributors concentrate in Riyadh and Jeddah. Traditional cuisine reformulation for low-calorie Saudi dishes offers product-level differentiation with limited incumbent R&D allocation. A go-to-market angle anchored in hotel wellness partnerships bypasses crowded home-gym and clinic sales channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors clinical nutrition formulators with hospital procurement relationships and verified halal supply chains. Long-term viability hinges on positioning ahead of NEOM Northwest wellness infrastructure buildout and secondary city channel expansion. The signal to watch is MOHAP licensing velocity for nutritional counseling clinics as a proxy for regulatory access liberalization.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | SFDA registration requirements privilege domestic manufacturers with verified supply chains over import-dependent competitors. |
| Telehealth Platform Integration | Hybrid digital-physical coaching models extend subscriber retention beyond traditional clinic-based service delivery. |
| Traditional Cuisine Reformulation | Localized low-calorie product development captures whitespace in culturally adapted portion-controlled nutrition. |
| Hospital Privatization Alignment | Premium private operator credentialing redistributes patient flows from public bariatric programs. |
| Corporate Wellness Partnership | B2B procurement anchors institutional demand beyond individual consumer purchase cycles. |
Research Approach
Cross-validation between primary interviews with bariatric surgeons, hospital procurement managers, SFDA regulatory affairs specialists, and direct-selling network operators anchors the qualitative findings against secondary validation. Bottom-up and top-down triangulation incorporates SFDA registration databases, MOHAP licensing records, hospital procurement disclosures, and customs trade data for dietary supplement imports. Primary fieldwork concentrated on Riyadh and Jeddah clinical clusters with secondary city coverage through distributor interviews.
Calibration against historical adoption curves for telehealth integration and corporate wellness penetration shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, service delivery mode, distribution channel, and customer archetype. CAGRs derive from weighted average growth assumptions across these segments informed by hospital privatization timelines and regulatory enforcement trajectories. Continuous glucose monitoring adoption rates and subscription meal replacement platform migration serve as industry-specific forecast inputs.
Practitioners should monitor SFDA digital labeling implementation phases and halal certification protocol evolution for early signals of competitive access restructuring. Forecasts reflect assumptions about regulatory enforcement consistency and hospital privatization velocity that could shift with policy discontinuities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutrition and Dietetics
Medical Nutrition Market
Nutrition and Dietetics
Vitamin Deficiency Treatment Market
Nutrition and Dietetics
Obesity Management Market
Nutrition and Dietetics
US Clinical Nutrition Market
Nutrition and Dietetics
Canada Clinical Nutrition Market
Nutrition and Dietetics
Maternal Nutrition Products Market
Nutrition and Dietetics
Global Clinical Nutrition Products Market
Nutrition and Dietetics
Nutrition Apps Market
Nutrition and Dietetics
Weight Loss Market
Nutrition and Dietetics
Advanced Glycation End Products Market
Nutrition and Dietetics
Parenteral Nutrition Market
Nutrition and Dietetics
Adult Clinical Nutrition Market
Nutrition and Dietetics
North America Clinical Nutrition Market
Nutrition and Dietetics
Intravenous Nutritional Therapy Market
Nutrition and Dietetics
Global Enteral Feeding Formulas Market
Nutrition and Dietetics
Clinical Nutrition Market