
 Arthroscopy Market | 2026-2036
Arthroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Arthroscopy Market Analytics
Modular instrument bundling is realigning how ambulatory surgical centers procure arthroscopy suites, shifting capital expenditure from standalone device purchases toward integrated procedure packages. Arthrex leverages its vertical integration across implants and visualization to sustain premium positioning in high-volume knee and shoulder procedures. Stryker competes through its broad surgical instruments portfolio, while Karl Storz anchors its presence with rigid endoscope manufacturing scale that dominates European hospital supply chains.
Arthroscopy is a minimally invasive surgical technique employing a fiber-optic camera system inserted through small periarticular incisions to diagnose and treat joint pathologies; standard arthroscopes utilize rod-lens optics with 2.7 mm to 4.0 mm outer diameters and xenon or LED light sources delivering 300 to 500 watt-equivalent illumination. Visualization systems command the highest margin pools among product segments due to recurring software upgrade cycles and proprietary image processing architectures. Knee surgery occupies the largest application share, though robotic-assisted surgery represents the fastest-expanding technology segment as hospitals justify capital outlays through improved suturing precision and reduced revision rates.
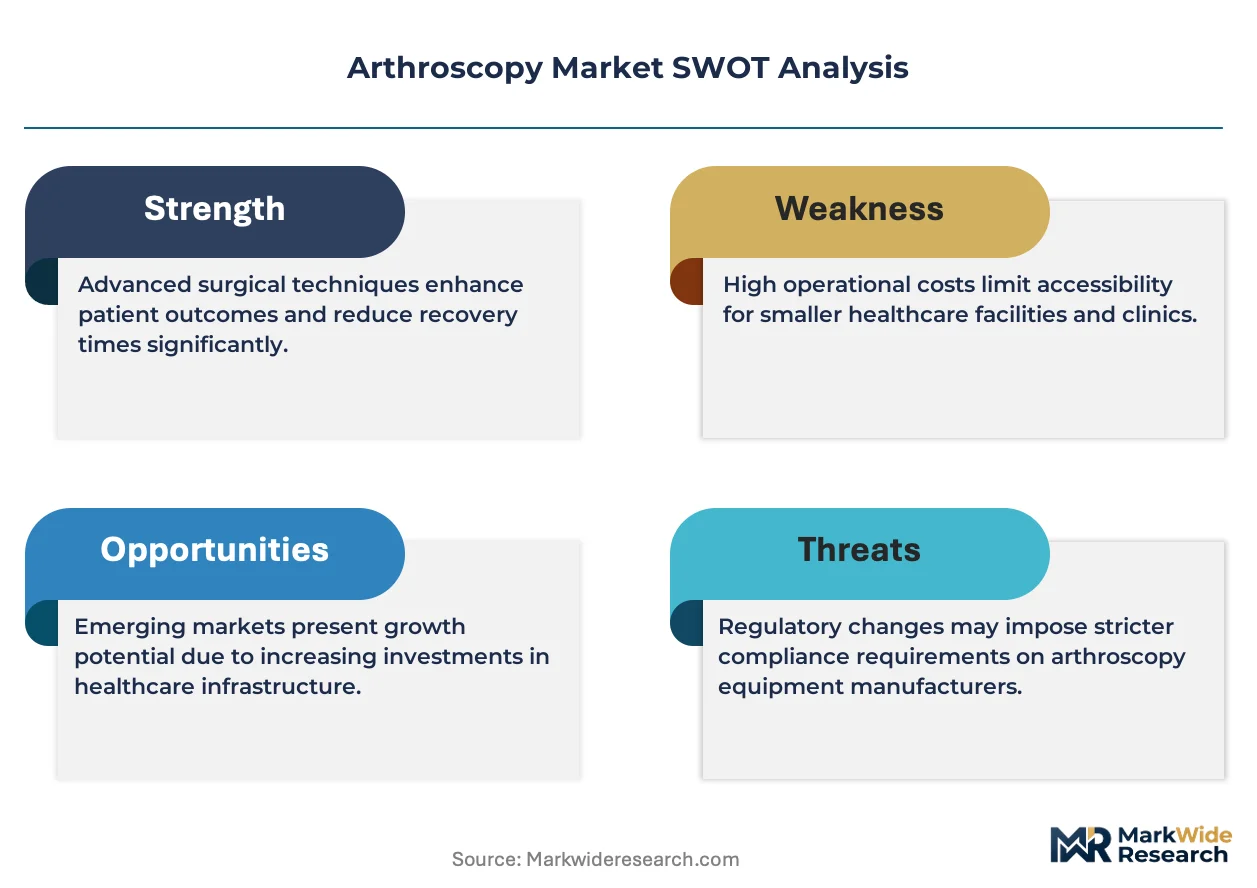
FDA 510(k) clearances govern arthroscope and shaver system approvals in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for reusable instrument revalidation that extends design dossier timelines. The European Commission's F-Gas Regulation also constrains cooling agents in laser-based visualization equipment, nudging manufacturers toward solid-state illumination alternatives. Stakeholders must monitor how reimbursement thresholds for outpatient joint procedures shift across Medicare and commercial payers, as site-of-service payment differentials will determine whether capital flows toward hospital-based robotics or clinic-grade arthroscopy towers.
Market Dynamics
Site-of-service payment differentials between hospital outpatient departments and ambulatory surgical centers are compressing procedure economics and forcing capital allocation toward clinic-grade visualization towers.
Growth Catalysts
- FDA 510(k) Pathway Compression:Streamlined clearances for 3D visualization platforms are accelerating time-to-market for arthroscope manufacturers targeting same-day surgery networks.
- LED Illumination Migration:Solid-state light sources are displacing xenon systems in ambulatory settings, reducing heat generation and maintenance cycles for high-volume knee and shoulder procedures.
- Medicare Outpatient Prospective Payment System:Reimbursement parity expansions for joint procedures performed outside hospital walls are pulling capital investment toward freestanding surgical facilities.
Market Restraints
- Rigid Endoscope Supply Concentration:German and Japanese optics manufacturers control precision glass rod-lens supply chains, creating vulnerability for visualization system assemblers.
- EU MDR Revalidation Burden:Stricter clinical evidence requirements for reusable instrument revalidation extend design dossier timelines and compress margins on legacy shaver portfolios.
- Fluorinated Gas Constraints:The European Commission's F-Gas Regulation limits cooling agents in laser-based arthroscopy equipment, forcing costly solid-state refrigeration redesigns.
Strategic Opportunities
- Robotic-Assisted Suturing Convergence:Integration of haptic feedback systems with arthroscopic visualization is expanding into shoulder instability repairs and meniscal transplantation.
- India Outpatient Network Buildout:Corporate hospital chains in Mumbai, Delhi, and Bangalore are adding dedicated sports medicine units with captive arthroscopy capacity.
- Software-Subscription Monetization:Proprietary image processing architectures are enabling recurring revenue streams through visualization system firmware upgrades and AI-powered pathology detection modules.
Industry Challenges
- Orthopedic Surgeon Training Pipeline:Fellowship programs produce insufficient arthroscopy specialists to match ambulatory surgical center expansion rates, creating procedure backlogs.
- Capital Equipment Integration Complexity:Legacy hospital information systems require expensive middleware to interface with modern 4K visualization towers and cloud-based image archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arthroscopy Market |
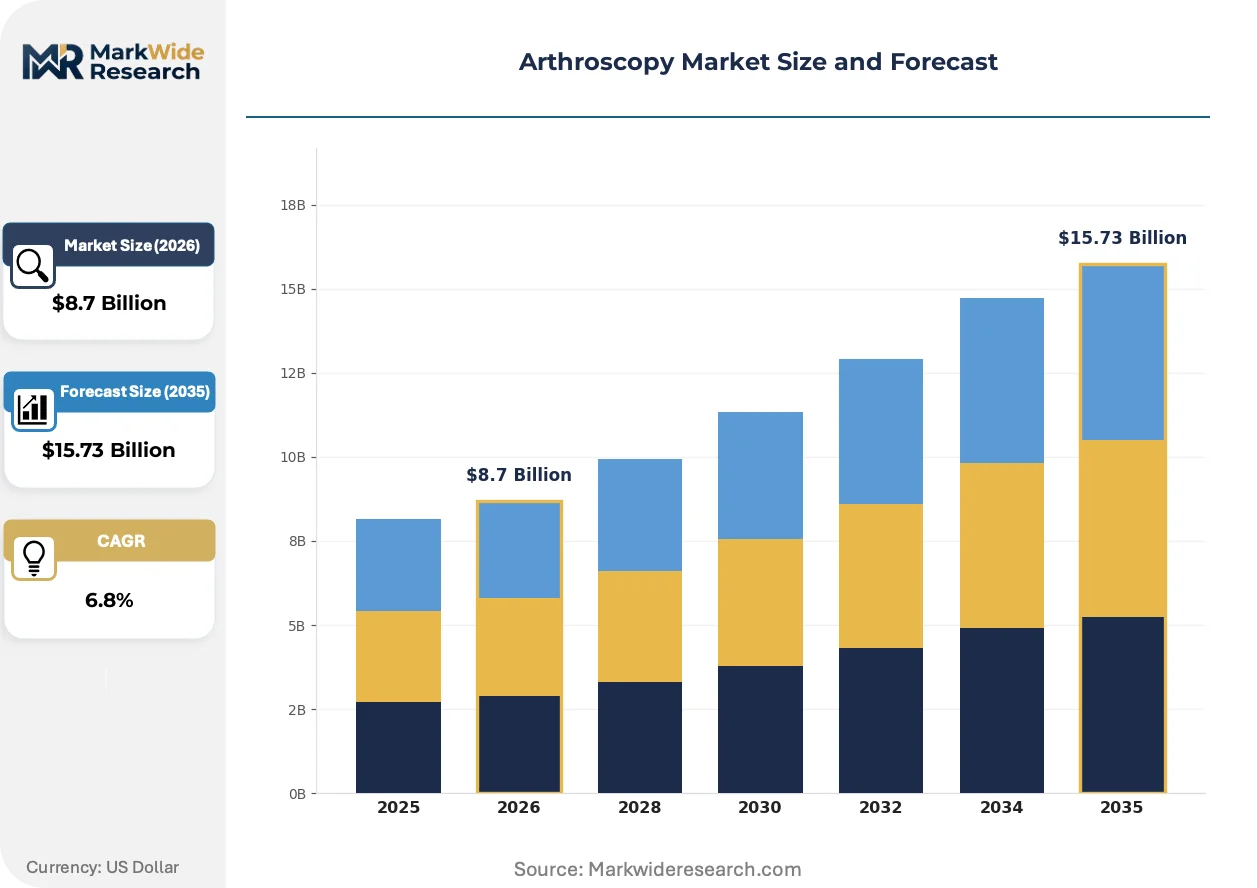
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arthroscopes, Surgical Instruments, Visualization Systems, Accessories Application: Knee Surgery, Shoulder Surgery, Hip Surgery, Ankle Surgery End User: Hospitals, Orthopedic Clinics, Ambulatory Surgical Centers, Specialty Clinics Technology: 2D Imaging, 3D Imaging, Robotic-Assisted Surgery, Single-Use Devices |
| Companies Covered | Arthrex, Stryker, Smith & Nephew, Zimmer Biomet, ConMed Corporation, Johnson & Johnson, Karl Storz, Medtronic, Richard Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arthroscopy Market Evolving Landscape
Three interconnected developments are compressing the arthroscopy value chain: illumination technology migration, regulatory evidence escalation, and procurement model consolidation around integrated procedure packages.
4K and 8K camera systems are expanding into high-volume knee arthroscopy suites as ambulatory surgical centers justify premium capital outlays through improved chondral visualization and reduced revision rates. Hospital procurement committees now prioritize single-vendor visualization towers over best-of-breed component assembly, compressing supplier margins while locking in recurring software service contracts.
The EU Medical Device Regulation imposes post-market surveillance obligations that extend reusable instrument revalidation cycles and force manufacturers to maintain larger clinical data repositories. European notified bodies have reduced capacity under MDR transition timelines, creating clearance bottlenecks that favor established players with dedicated regulatory affairs infrastructure over mid-tier competitors.
Orthopedic clinic networks are consolidating vendor relationships around modular instrument bundling that combines arthroscopes, shavers, and fixation implants under single-source agreements. This procurement compression is displacing standalone device purchasing in United States metropolitan markets, with integrated procedure packages now dominating capital expenditure decisions for new ambulatory surgical center construction.
Arthroscopy Market Segmentation
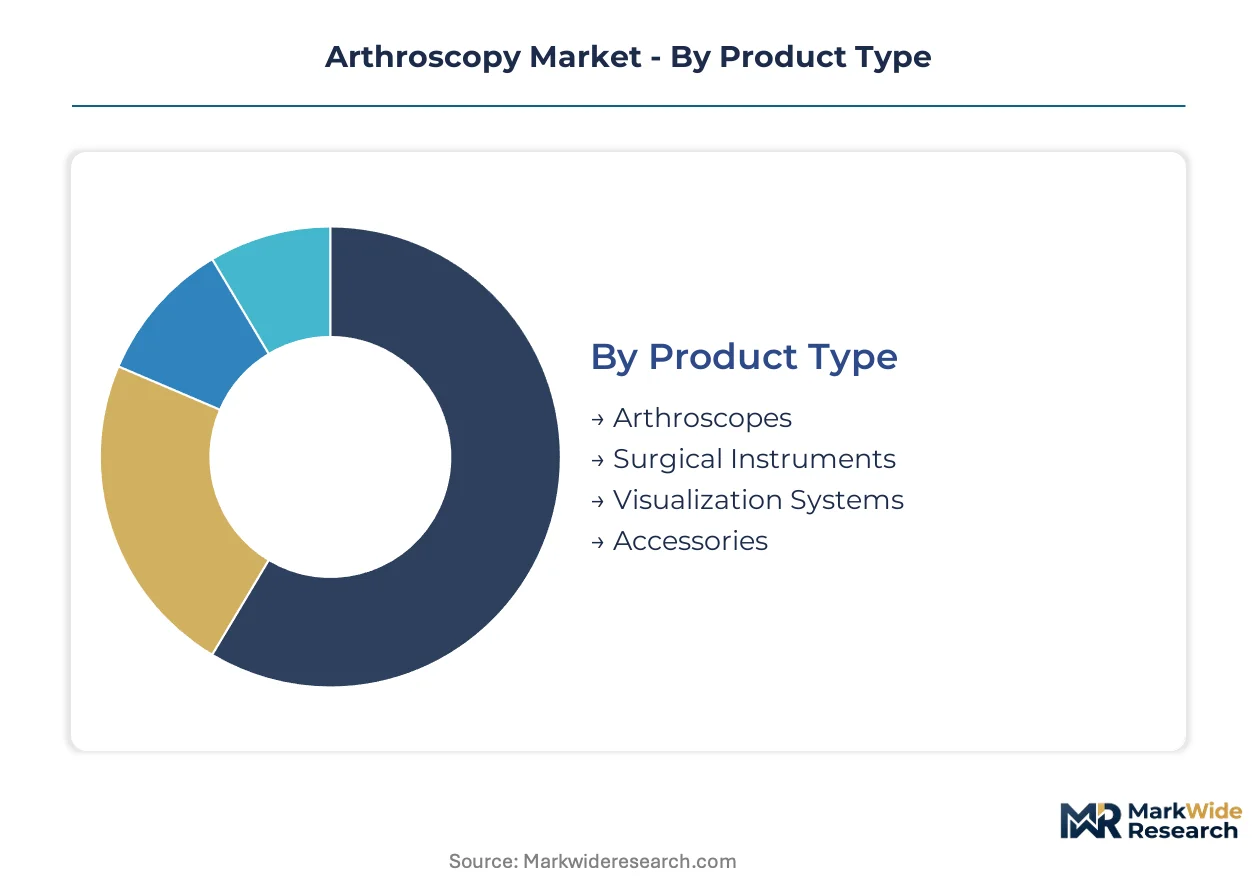
Arthroscopy equipment procurement varies sharply by setting, with capital allocation patterns diverging between high-volume hospital systems and freestanding ambulatory facilities. Understanding these segment boundaries clarifies where margin pools concentrate and which technology tiers command premium positioning.
Product Type:
Capital-intensity varies dramatically across product categories, with visualization systems requiring the steepest upfront investment due to proprietary image processing architectures and recurring software licensing structures.
- Visualization Systems:4K and 8K camera towers with integrated LED illumination and proprietary image processing command the highest capital outlays. Demand concentrates in United States metropolitan ambulatory surgical centers seeking to differentiate through superior chondral visualization and reduced revision liability.
- Arthroscopes:Rigid rod-lens optical systems with 2.7 mm to 4.0 mm outer diameters represent the procedural core, with German and Japanese optics manufacturers controlling precision glass supply chains that constrain downstream assembler margins.
- Surgical Instruments:Reusable shavers, burrs, and graspers face escalating EU MDR revalidation burdens that extend design dossier timelines and compress legacy portfolio profitability.
- Accessories:Disposable cannulas, irrigation tubing, and electrocautery probes generate recurring revenue streams with lower capital barriers to entry.
Visualization Systems absorb the bulk of installed capacity; Accessories is expanding most quickly through single-use conversion trends.
Application:
Procedure volume distribution follows orthopedic disease prevalence and reimbursement accessibility, with knee interventions maintaining structural dominance despite shoulder surgery's faster technology adoption curve.
- Knee Surgery:Meniscal repair, ACL reconstruction, and chondroplasty constitute the highest-volume arthroscopy category, with Medicare reimbursement parity for outpatient procedures pulling capital toward freestanding surgical facilities in the United States.
- Shoulder Surgery:Rotator cuff repair and instability correction demand advanced visualization precision, driving adoption of robotic-assisted suturing platforms in high-volume orthopedic clinic networks.
- Hip Surgery:Femoroacetabular impingement procedures require specialized distraction equipment and longer learning curves, limiting penetration outside academic medical centers.
- Ankle Surgery:Arthroscopic ankle fusion and loose body removal represent a niche application with concentrated demand in sports medicine referral networks.
Knee Surgery commands the dominant share of procedure economics; Shoulder Surgery is climbing the fastest as robotic platforms justify premium capital deployment.
End User:
Site-of-service payment differentials are fragmenting procurement authority, with purchasing decisions migrating from hospital supply chains toward independent ambulatory operators seeking bundled capital solutions.
- Ambulatory Surgical Centers:Freestanding facilities are accelerating adoption of clinic-grade arthroscopy towers as Medicare Outpatient Prospective Payment System expansions create reimbursement parity with hospital outpatient departments.
- Hospitals:Academic and community hospital systems maintain robotics programs through capital reserves and bundled payment contracts, though same-day surgery migration is eroding arthroscopy volume share.
- Orthopedic Clinics:Corporate clinic networks in the United States are consolidating vendor relationships around modular instrument packages that combine visualization, shavers, and fixation implants under single-source agreements.
- Specialty Clinics:Sports medicine and hand surgery focused practices represent a fragmented end-user tier with price-sensitive procurement patterns and lower equipment utilization rates.
Hospitals retain the largest installed equipment base; Ambulatory Surgical Centers are gaining share fastest as site-of-service economics shift.
Technology:
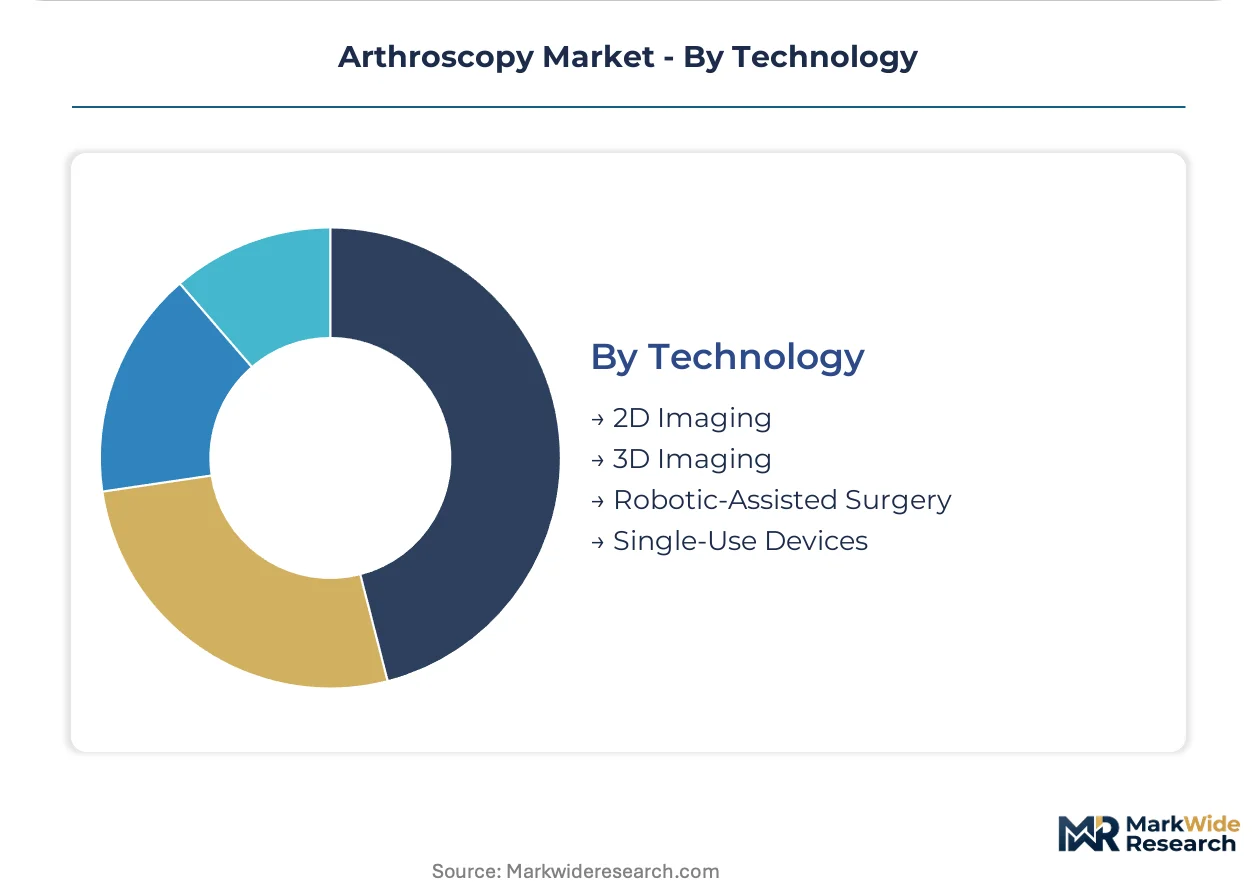
Imaging resolution and automation capabilities are stratifying the technology landscape, with 3D visualization and robotic assistance commanding capital premiums while single-use alternatives disrupt traditional reprocessing economics.
- 3D Imaging:Stereoscopic visualization platforms with depth-perception enhancement are penetrating high-volume shoulder and knee suites as FDA 510(k) pathway compression accelerates time-to-market for manufacturers targeting same-day surgery networks.
- Robotic-Assisted Surgery:Haptic feedback systems integrated with arthroscopic visualization are expanding into meniscal transplantation and shoulder instability repairs, with hospitals justifying capital outlays through improved suturing precision metrics.
- 2D Imaging:Standard high-definition camera systems face margin compression as procurement committees prioritize single-vendor 4K tower integration over best-of-breed component assembly.
- Single-Use Devices:Disposable arthroscopes and instrument sets are disrupting European reprocessing economics under EU MDR post-market surveillance obligations that elevate reusable instrument compliance costs.
2D Imaging maintains the dominant installed base; Robotic-Assisted Surgery is on the steepest expansion trajectory as precision metrics justify premium capital allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arthroscopy equipment production concentrates in German and Japanese precision optics clusters, while consumption tilts toward United States ambulatory surgical centers and European hospital networks seeking same-day surgery migration.
United States
Medicare Outpatient Prospective Payment System expansions are pulling capital toward freestanding surgical facilities in Texas, Florida, and Arizona. FDA 510(k) pathway compression accelerates time-to-market for visualization platforms targeting clinic-grade arthroscopy towers. Orthopedic clinic networks in Dallas-Fort Worth and Phoenix are consolidating vendor relationships around modular instrument bundling.
Germany
Precision glass rod-lens manufacturing from Karl Storz and Richard Wolf anchors European supply chains for rigid endoscope cores. EU MDR post-market surveillance obligations extend reusable instrument revalidation timelines and elevate compliance costs for shaver portfolios. Bavarian medical technology clusters around Tuttlingen maintain captive production of arthroscope optical assemblies.
Japan
PMDA regulatory harmonization with FDA standards streamlines dual-market submissions for 3D visualization platforms. METI industrial policy supports domestic production of solid-state LED illumination modules displacing xenon systems. Nagoya-based surgical instrument manufacturers are expanding capacity for high-definition camera tower integration.
India
Corporate hospital chains in Mumbai, Delhi, and Bangalore are adding dedicated sports medicine units with captive arthroscopy capacity. CDSCO medical device registration requirements are compressing as the regulator aligns with IMDRF standards for joint procedure equipment. Karnataka's medical device parks near Bengaluru are attracting contract manufacturers for disposable cannula production.
United Kingdom
NHS England site-of-service payment reforms are shifting knee and shoulder procedures toward independent sector treatment centers. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while streamlining UKCA transition for arthroscope manufacturers. London and Manchester orthopedic networks are prioritizing single-vendor visualization tower procurement over best-of-breed assembly.
Arthroscopy Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists controlling visualization and implant portfolios simultaneously. Market concentration remains moderate, with established optics manufacturers defending precision glass supply chains against modular assemblers. Three archetypes dominate: German-Japanese optics incumbents with captive rod-lens production, diversified surgical conglomerates leveraging broad instrument portfolios, and ambulatory-focused integrators bundling procedure packages. Competitive moves center on regulatory affairs infrastructure buildup for EU MDR compliance and software-subscription monetization through proprietary image processing architectures.
Within the visualization systems tier, Karl Storz anchors German precision optics manufacturing scale that dominates European hospital supply chains. Arthrex exemplifies the vertically integrated specialist archetype through combined implant and visualization positioning in high-volume knee and shoulder procedures. Stryker occupies a diversified surgical conglomerate position, competing through breadth across instruments and capital equipment rather than depth in arthroscopy-specific optics.
| Leading Market Players |
|---|
| Arthrex |
| Stryker |
| Smith & Nephew |
| Zimmer Biomet |
| ConMed Corporation |
| Johnson & Johnson |
| Karl Storz |
| Medtronic |
| Richard Wolf GmbH |
| Others |
Value Network & Pricing Analysis
LED illumination migration from xenon to solid-state sources is compressing maintenance economics for ambulatory surgical centers while concentrating procurement leverage around German and Japanese optics manufacturers who control precision glass rod-lens production. This technology transition simultaneously reduces heat-generation costs for high-volume knee and shoulder procedures and reinforces supply-side pricing power among captive producers of rigid endoscope optical cores.
Pricing Analysis
Cost-down pressure on visualization systems accelerates because procurement committees prioritize single-vendor 4K tower integration over best-of-breed component assembly. Three-tier pricing structure across premium visualization platforms, standard HD systems, and economy-grade 2D imaging separates academic medical centers from metropolitan ambulatory surgical centers and price-sensitive specialty clinics. Brand premium and FDA 510(k) clearance tier drive differentiation, with reimbursement parity expansions intensifying margin compression in the standard tier. Specialty clinics exhibit highest price sensitivity; hospital systems with bundled payment contracts demonstrate lowest.
Supply Chain Analysis
Dual-sourcing mandates from United States orthopedic clinic networks require qualification of at least two German or Japanese optics suppliers for rigid endoscope rod-lens assemblies, though Karl Storz and Richard Wolf maintain effective supply concentration. Precision-ground borosilicate glass, xenon arc lamp components, and CMOS image sensors constitute critical input dependencies. Single-source vulnerability in precision glass grinding capacity creates structural exposure. Distribution runs through hospital purchasing committees and GPO contracts in hospital systems, direct vendor relationships in ambulatory surgical centers, and distributor networks in emerging outpatient markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision glass rod-lens manufacturing capacity constrains visualization system output, propping pricing power among German and Japanese incumbents who control optical core production. This supply bottleneck sustains margin pools despite downstream procurement consolidation.
For Market Incumbents: Lock in ambulatory surgical center relationships through software-subscription bundling that ties visualization tower upgrades to recurring firmware licensing. Defend against single-use device disruption by accelerating EU MDR-compliant revalidation investments for reusable shaver portfolios. Backward integration into LED illumination module production reduces xenon supply dependency. For New Entrants and Emerging Players: The mid-tier pricing gap between Karl Storz premium visualization systems and economy-grade 2D imaging creates white-space opportunity in Indian corporate hospital chains adding sports medicine capacity. Target disposable cannula and irrigation accessory production near Karnataka medical device parks to bypass German-Japanese optics concentration. Pursue CDSCO registration alignment with IMDRF standards as the go-to-market pathway. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical integration plays combining visualization platforms with implant portfolios, as Arthrex demonstrates in knee and shoulder procedure bundling. Long-term viability favors specialists controlling proprietary image processing architectures that enable recurring software revenue. Monitor FDA 510(k) clearance velocity for 3D visualization platforms as the inflection signal for ambulatory surgical center capital deployment shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Subscription Monetization | Proprietary image processing architectures from Karl Storz and Arthrex enable recurring firmware upgrade revenue streams. |
| EU MDR Compliance Investment | Extended design dossier timelines for reusable shaver revalidation favor established players with dedicated regulatory infrastructure. |
| Single-Use Device Expansion | Disposable arthroscope conversion disrupts European reprocessing economics under post-market surveillance obligations. |
| Ambulatory Surgical Center Partnership | Medicare reimbursement parity pulls capital toward freestanding facilities seeking clinic-grade visualization tower procurement. |
| Robotic-Assisted Platform Integration | Haptic feedback convergence with arthroscopic visualization expands into meniscal transplantation and shoulder instability repairs. |
Research Methodology
Independent corroboration across FDA 510(k) clearance databases, EU MDR notified body filings, and CMS Medicare reimbursement records underwrites the qualitative findings on regulatory pathway compression. Primary interviews with orthopedic surgeons, ambulatory surgical center administrators, hospital purchasing committee members, and biomedical engineers combined with secondary validation from SEC 10-K filings, GPO contract databases, and precision optics trade publications. Bottom-up equipment shipment analysis triangulates against top-down procedure volume estimates from Medicare claims data.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price-mix effects in visualization system procurement. Segmentation modeling incorporates product type tiers, application categories spanning knee through ankle surgery, end-user facility economics, and technology adoption curves for 3D imaging and robotic assistance. CAGRs derive from installed base growth projections and replacement cycle analysis for LED illumination migration. Forecast inputs include Medicare Outpatient Prospective Payment System expansion schedules and EU MDR transition timelines.
Underlying measurement precision varies by segment; visualization systems and robotic-assisted platforms carry tighter precision than disposable accessories and specialty clinic procurement. Forecasts reflect documented assumptions on reimbursement parity adoption and regulatory clearance velocity. Deviation in FDA 510(k) pathway timelines or EU notified body capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Concussion Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Micro-Bypass Systems Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Defibrillator Pads Market
Medical Devices
UAE Respiratory Devices Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Single-Use Assemblies Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
US Contact Lenses Market