
 Wheelchair and Components Market | 2026-2036
Wheelchair and Components Market Size, Share, and Industry Trends Forecast 2026-2036
Wheelchair and Components Market Outlook
Subscription-based leasing and pay-per-use financing is reshaping competitive dynamics for wheelchair manufacturers and their component suppliers. Permobil AB leverages its premium positioning to sustain higher margins on recurring service contracts. Sunrise Medical anchors its presence across European reimbursement systems with localized assembly. Ottobock Healthcare GmbH competes through in-house production of electronic control modules.
A wheelchair is a wheeled mobility device comprising a chassis, seating system, wheels, and optional powered control mechanisms, engineered to ISO 7176 standards for dimensional stability, braking performance, and user safety, designed to transport individuals with impaired ambulatory function across indoor and outdoor environments. Power wheelchairs command the highest value per unit due to integrated motor drives and programmable control electronics, while lightweight manual variants occupy the highest volume tier in institutional procurement. Home care end users represent the fastest-expanding demand pool as aging-in-place policies shift reimbursement toward residential settings rather than long-term care facilities.
FDA premarket notification requirements under 21 CFR 890.3850 govern powered wheelchair safety in the United States, while the EU Medical Device Regulation mandates CE marking and post-market surveillance for mobility aids distributed in Europe. Japan's Ministry of Health, Labour and Welfare enforces Pharmaceutical and Medical Device Act standards that limit market entry to certified local distributors. Stakeholders must monitor how reimbursement code revisions in major markets alter the economic viability of smart-connected wheelchair platforms versus conventional analog designs.
Market Dynamics
Reimbursement code revisions across Medicare, statutory health insurance systems, and Japan's long-term care insurance are restructuring procurement economics, compressing margins on conventional analog wheelchairs while expanding coverage for sensor-integrated powered platforms.
Growth Catalysts
- Aging-in-place mandates:Residential care diversion policies in Germany and Japan redirect public funding toward home-based powered mobility, expanding addressable demand for programmable control systems.
- ISO 7176-4 braking performance standards:Updated testing protocols for electromagnetic compatibility are accelerating replacement cycles in institutional fleets as legacy inventory faces compliance deadlines.
- Lithium-ion cell cost curves:Battery chemistry advances are extending range specifications for mid-tier power wheelchairs, eroding the performance gap against premium motor drive configurations.
Market Restraints
- Aluminum alloy price volatility:Chassis material costs fluctuate with energy-intensive smelting economics, pressuring margin structures for lightweight manual wheelchair producers.
- Single-source actuator supply:Precision motor-gearbox assemblies concentrate among German and Japanese component specialists, creating vulnerability for assemblers without captive supply.
- FDA 510(k) pathway duration:Premarket notification timelines for powered control electronics extend development-to-revenue intervals beyond 18 months for novel sensor configurations.
Strategic Opportunities
- India's Ayushman Bharat expansion:The national health assurance scheme's assistive device coverage remains underpenetrated for motorized mobility, offering first-mover positioning for localized assembly partnerships.
- Telehealth-integrated diagnostics:Remote seating assessment protocols are converging with pressure-mapping sensor arrays, enabling virtual prescription workflows that reduce clinical visit requirements.
- Subscription maintenance models:Pay-per-use service contracts for battery replacement and control module calibration are capturing recurring revenue streams previously lost to third-party repair networks.
Industry Challenges
- Rehabilitation engineering talent scarcity:Specialized seating clinicians and ATP-certified technicians remain concentrated in urban academic medical centers, constraining rural distribution scaling.
- Legacy analog fleet interoperability:Smart-connected wheelchair platforms face integration friction with existing residential infrastructure lacking IoT gateway compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheelchair and Components Market |
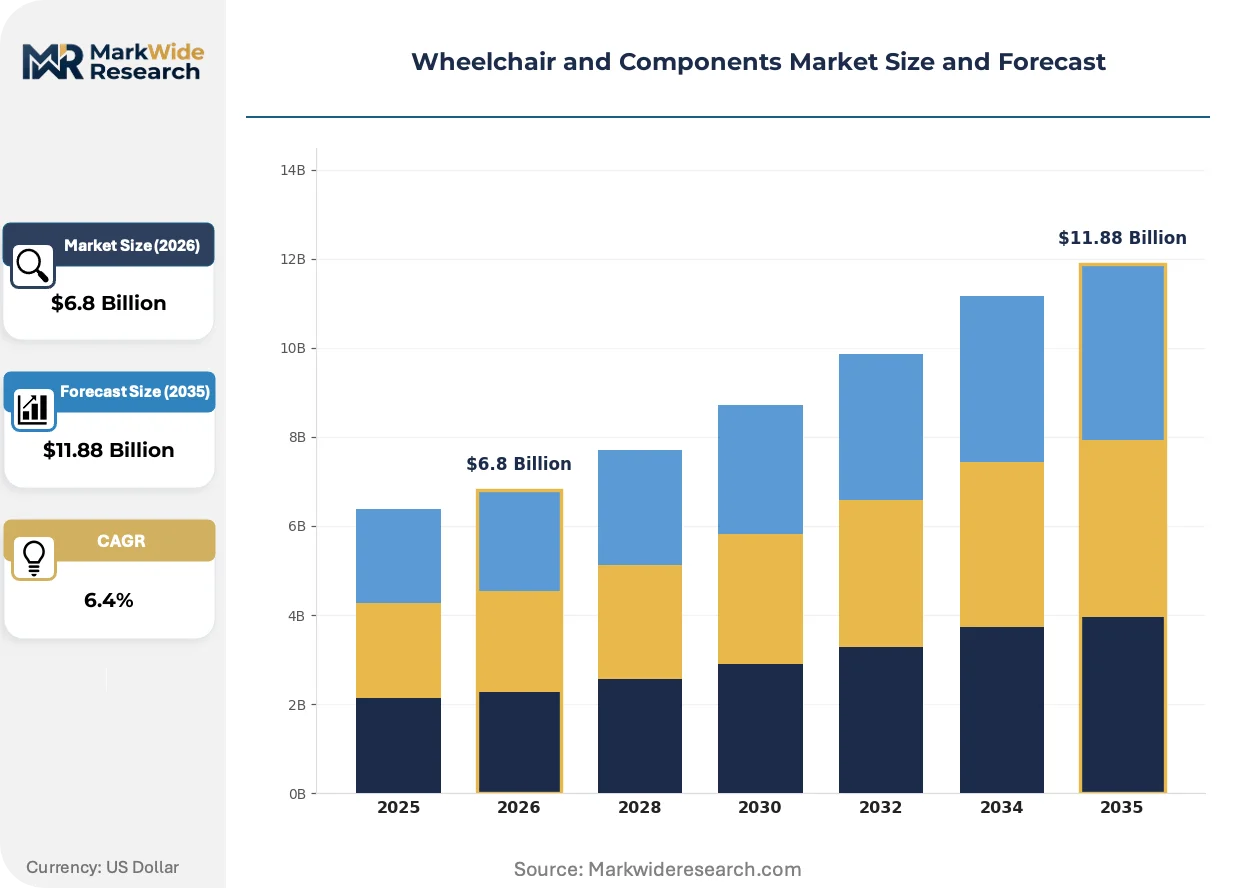
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Wheelchairs, Power Wheelchairs, Sport Wheelchairs, Lightweight Wheelchairs End User: Hospitals, Rehabilitation Centers, Home Care, Long-term Care Facilities Component: Chassis, Wheels, Seating Systems, Control Systems Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Distributors |
| Companies Covered | Invacare Corporation, Sunrise Medical, Permobil AB, Ottobock Healthcare GmbH, Pride Mobility Products Corp., Drive DeVilbiss Healthcare, Hoveround Corporation, Karman Healthcare, Numotion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheelchair and Components Market Strategic Shifts
Control electronics miniaturization and sensor fusion architectures are compressing the traditional segmentation between clinical rehabilitation equipment and consumer mobility devices, forcing recalibration of distribution channels and service expectations.
Brushless DC motor controllers with integrated torque sensing are collapsing the cost-performance boundary between standard power wheelchairs and advanced rehabilitation platforms. Veterans Affairs procurement and European home care agencies are adopting these mid-tier configurations at accelerated replacement intervals. The technology is collapsing the historical three-tier product architecture into a compressed premium-midrange spectrum.
EU Medical Device Regulation post-market surveillance requirements are mandating systematic adverse event reporting for powered mobility devices distributed in Europe. Manufacturers must maintain clinical evidence registries and periodic safety update reports, elevating compliance overhead. Class IIa device reclassification for certain joystick configurations is driving certification timeline extensions for products previously cleared under the Medical Devices Directive.
Institutional procurement consolidation is compressing vendor rosters as hospital systems and national tender authorities mandate sole-source agreements for fleet standardization. Group purchasing organizations are displacing independent dealer networks in North American acute care settings. Germany's centralized statutory health insurance procurement is most advanced in this concentration, with regional associations negotiating multi-year framework contracts.
Wheelchair and Components Market Segmentation
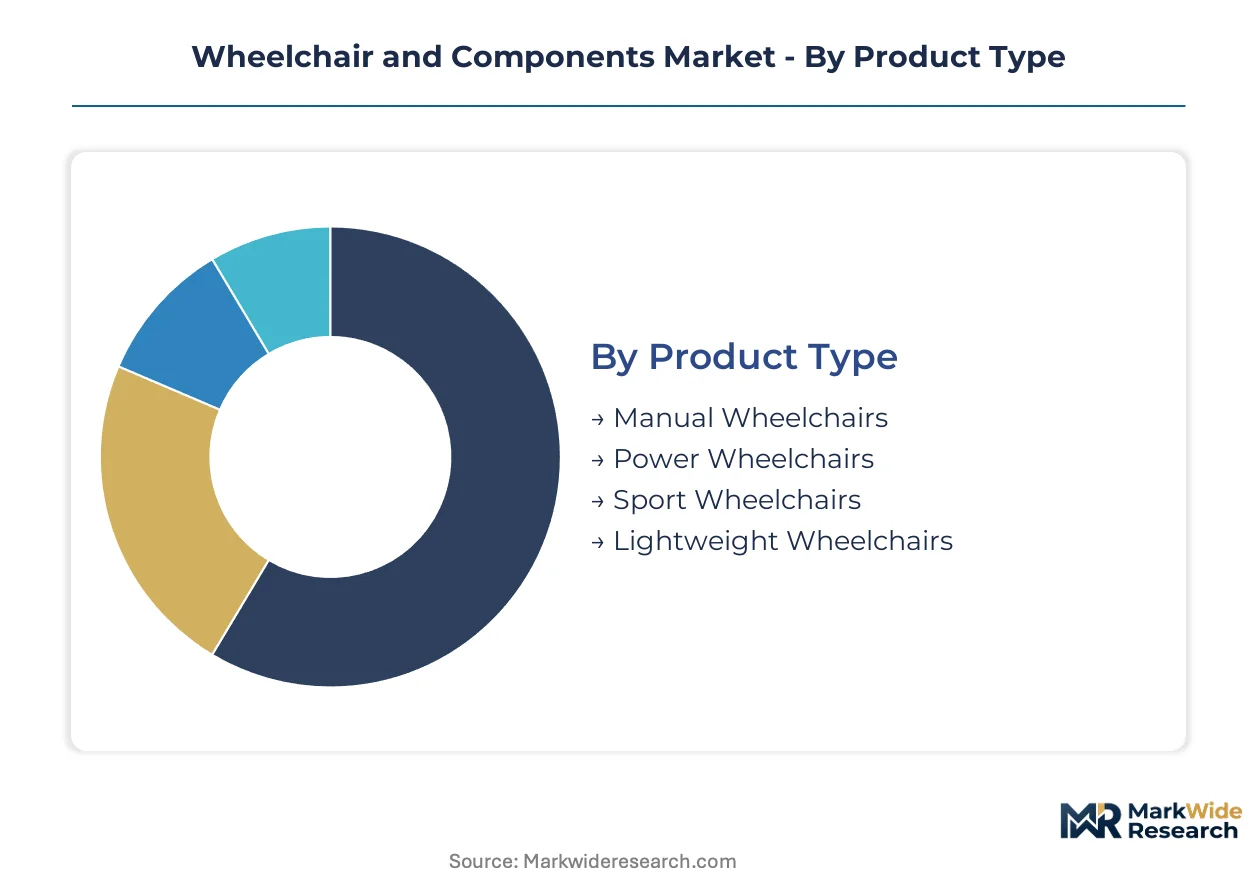
Wheelchair procurement patterns diverge sharply across institutional versus residential channels, with reimbursement codes and clinical assessment protocols determining which product configurations reach specific patient populations. Component sourcing strategies and distribution economics vary significantly by end-use setting, creating distinct competitive arenas within the broader mobility device landscape.
Product Type:
Cost tier differentiation separates commodity manual offerings from integrated powered platforms with programmable electronics.
- Manual Wheelchairs:Tubular steel or aluminum alloy frames with fixed or folding configurations dominate institutional procurement volumes. Demand concentrates in long-term care facilities across Germany and Japan, where statutory reimbursement favors durable entry-level configurations for resident mobility.
- Power Wheelchairs:Motor-driven bases with joystick or sip-and-puff control interfaces integrate brushless DC motor controllers and lithium-ion power systems. Home care providers in the United States are expanding procurement of these platforms as Medicare Advantage plans broaden coverage for aging-in-place scenarios.
- Sport Wheelchairs:Cambered wheel configurations with titanium or carbon fiber frames optimize for basketball, tennis, and racing disciplines.
- Lightweight Wheelchairs:Ultra-light aluminum or magnesium alloy constructions target active users requiring transportability.
Manual configurations command the established base. The steepest expansion runs through power wheelchair platforms with integrated control electronics.
End User:
Application setting determines product specification intensity, clinical support requirements, and reimbursement pathway complexity.
- Hospitals:Acute care settings prioritize bariatric-capable frames and pressure-relief seating for short-term patient transport and early mobilization protocols. Procurement concentrates through group purchasing organizations in the United States, with FDA 510(k) clearance status driving vendor selection criteria.
- Home Care:Residential settings require customizable seating systems and powered options for independent living. Japan's Ministry of Health, Labour and Welfare long-term care insurance expansion is redirecting demand toward home-based configurations with telehealth integration capabilities.
- Rehabilitation Centers:Outpatient and inpatient therapy facilities demand adjustable tilt-in-space and standing-frame compatibility.
- Long-term Care Facilities:Nursing homes and assisted living operators prioritize fleet standardization and maintenance contract simplicity.
Hospital procurement maintains volume leadership. Home care channels are climbing the fastest as residential diversion policies reshape public funding flows.
Component:
Supply concentration varies by subassembly complexity, with electronic control modules exhibiting the tightest vendor consolidation.
- Control Systems:Programmable motor controllers, joystick modules, and environmental control interfaces represent the highest value-added subassembly. German and Japanese precision motor-gearbox specialists concentrate supply, creating single-source vulnerability for assemblers lacking captive production.
- Seating Systems:Pressure-mapping cushions, contoured back supports, and tilt-actuation mechanisms interface directly with user clinical outcomes. Demand is concentrating among ATP-certified providers in urban United States markets where specialized rehabilitation engineering talent clusters.
- Chassis:Welded steel or extruded aluminum frame structures provide dimensional stability per ISO 7176-4 braking performance standards.
- Wheels:Spoked or mag-style configurations with pneumatic or solid tire compounds complete the mobility base.
Chassis and wheel assemblies anchor the component value chain. Control systems are gaining share fastest as smart-connected platforms displace analog configurations.
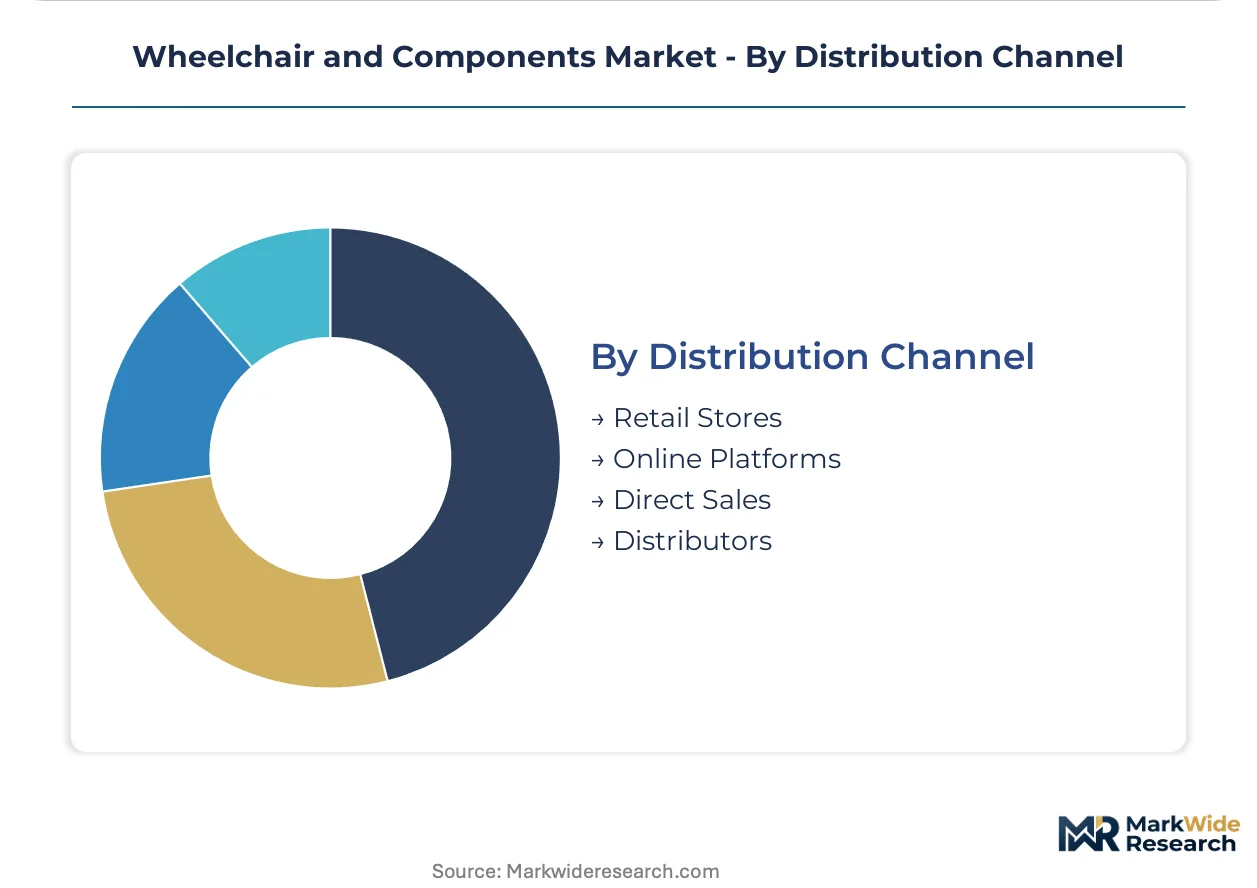
Distribution Channel:
Customer type and purchase scale determine channel economics, with institutional buyers bypassing retail intermediaries.
- Direct Sales:Manufacturer field representatives contract directly with hospital systems, Veterans Affairs procurement, and national tender authorities. Germany's statutory health insurance regional associations negotiate multi-year framework agreements through this channel, compressing vendor rosters toward sole-source arrangements.
- Distributors:Independent dealer networks and specialized durable medical equipment suppliers provide local inventory, fitting services, and maintenance support. Rural United States markets depend on this channel where ATP-certified technician scarcity constrains direct manufacturer penetration.
- Retail Stores:Pharmacy chains and medical supply storefronts serve cash-pay customers and basic mobility needs.
- Online Platforms:E-commerce channels are expanding for standard manual configurations and replacement parts.
Distributor networks retain the established infrastructure. Direct sales channels are expanding most quickly as institutional procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German statutory health insurance procurement while United States Medicare Advantage plans compress margins through competitive bidding. Reimbursement code revisions in Tokyo and Berlin are redirecting public funding toward sensor-integrated powered platforms. Manufacturing clusters in Bavaria, southern California, and Osaka Prefecture anchor component supply for programmable control systems.
United States
Medicare Advantage expansion and Veterans Affairs procurement are accelerating replacement cycles for mid-tier power wheelchairs with brushless DC motor controllers. FDA 510(k) premarket notification requirements under 21 CFR 890.3850 govern powered wheelchair safety clearance timelines. ATP-certified technician clusters in urban academic medical centers across California, Texas, and the Northeast Corridor constrain rural distribution scaling for specialized seating configurations.
Germany
Statutory health insurance regional associations negotiate multi-year framework contracts that compress vendor rosters toward sole-source arrangements for fleet standardization. EU Medical Device Regulation post-market surveillance mandates systematic adverse event reporting and clinical evidence registries for powered mobility devices. Manufacturing concentration in Bavaria and North Rhine-Westphalia hosts precision motor-gearbox specialists supplying electromagnetic braking assemblies.
Japan
Ministry of Health, Labour and Welfare long-term care insurance expansion is redirecting demand toward home-based powered configurations with telehealth integration capabilities. Pharmaceutical and Medical Device Act standards limit market entry to certified local distributors for mobility aids. Industrial clusters in Osaka Prefecture and the Kanto region concentrate supply of lithium-ion battery management systems for extended-range power wheelchair platforms.
India
Ayushman Bharat national health assurance scheme assistive device coverage remains underpenetrated for motorized mobility, offering first-mover positioning opportunities. Central Drugs Standard Control Organization regulations govern medical device import and local assembly certification pathways. Manufacturing partnerships in Maharashtra and Gujarat are emerging for localized chassis welding and seating system fabrication to serve price-sensitive institutional procurement.
United Kingdom
National Health Service wheelchair service specifications are consolidating procurement through regional specialized commissioning hubs for complex rehabilitation prescriptions. Medicines and Healthcare products Regulatory Agency oversees CE marking transition and UKCA conformity assessment for powered mobility devices post-Brexit. Clinical engineering expertise clusters in London, Birmingham, and Manchester support pressure-mapping sensor integration for custom seating configurations.
Wheelchair and Components Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in motor-gearbox and control module supply. The vendor base separates into three strategic archetypes: premium-tier rehabilitation platforms with captive electronics production, mid-scale assemblers sourcing standardized subassemblies, and regional fabricators serving price-sensitive institutional procurement. Competitive positioning hardens through M&A consolidation of independent dealer networks and backward integration into lithium-ion battery pack assembly.
Among European platform integrators, Permobil AB and Ottobock Healthcare GmbH occupy positions emphasizing premium rehabilitation configurations with in-house control electronics production. Sunrise Medical anchors presence across reimbursement systems with localized assembly strategies. United States-based Invacare Corporation and Pride Mobility Products Corp. represent scale-driven archetypes serving institutional procurement through distributor networks. Drive DeVilbiss Healthcare and Hoveround Corporation sit within the mid-tier segment addressing home care channels with standardized powered platform configurations.
| Leading Market Players |
|---|
| Invacare Corporation |
| Sunrise Medical |
| Permobil AB |
| Ottobock Healthcare GmbH |
| Pride Mobility Products Corp. |
| Drive DeVilbiss Healthcare |
| Hoveround Corporation |
| Karman Healthcare |
| Numotion |
| Others |
Value Chain & Pricing Dynamics
German and Japanese precision motor-gearbox specialists concentrate supply of electronic control modules, anchoring margin pools in downstream power wheelchair assembly where programmable configurations command premium positioning over commodity manual alternatives.
Pricing Analysis
Configured-to-order pricing for custom seating and control electronics spreads substantially above standard manual wheelchair price points. Three-tier pricing structure across premium, standard, and economy levels separates ATP-certified rehabilitation platforms from mid-tier powered configurations and institutional procurement baselines. Price differentiation stems from ISO 7176-4 certification grade and vertical integration depth in control module production. Cost compression in lightweight manual segments is intensifying because aluminum alloy smelting economics pressure chassis fabricators. Institutional buyers exhibit highest price sensitivity, while home care channels with Medicare Advantage coverage demonstrate lowest sensitivity for sensor-integrated platforms.
Supply Chain Analysis
Tariff exposure between United States and Chinese lithium-ion cell suppliers dominates supply chain risk planning for power wheelchair assemblers. Manufacturing gravity centers on Germany, Japan, and United States for precision motor-gearbox assemblies, brushless DC controllers, and battery management systems. Raw material dependencies span lithium carbonate, rare-earth magnets, and aerospace-grade aluminum alloys. Single-source vulnerability concentrates in electromagnetic braking subassemblies from Bavarian component specialists. Distribution runs through group purchasing organizations in acute care settings and independent dealer networks for residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
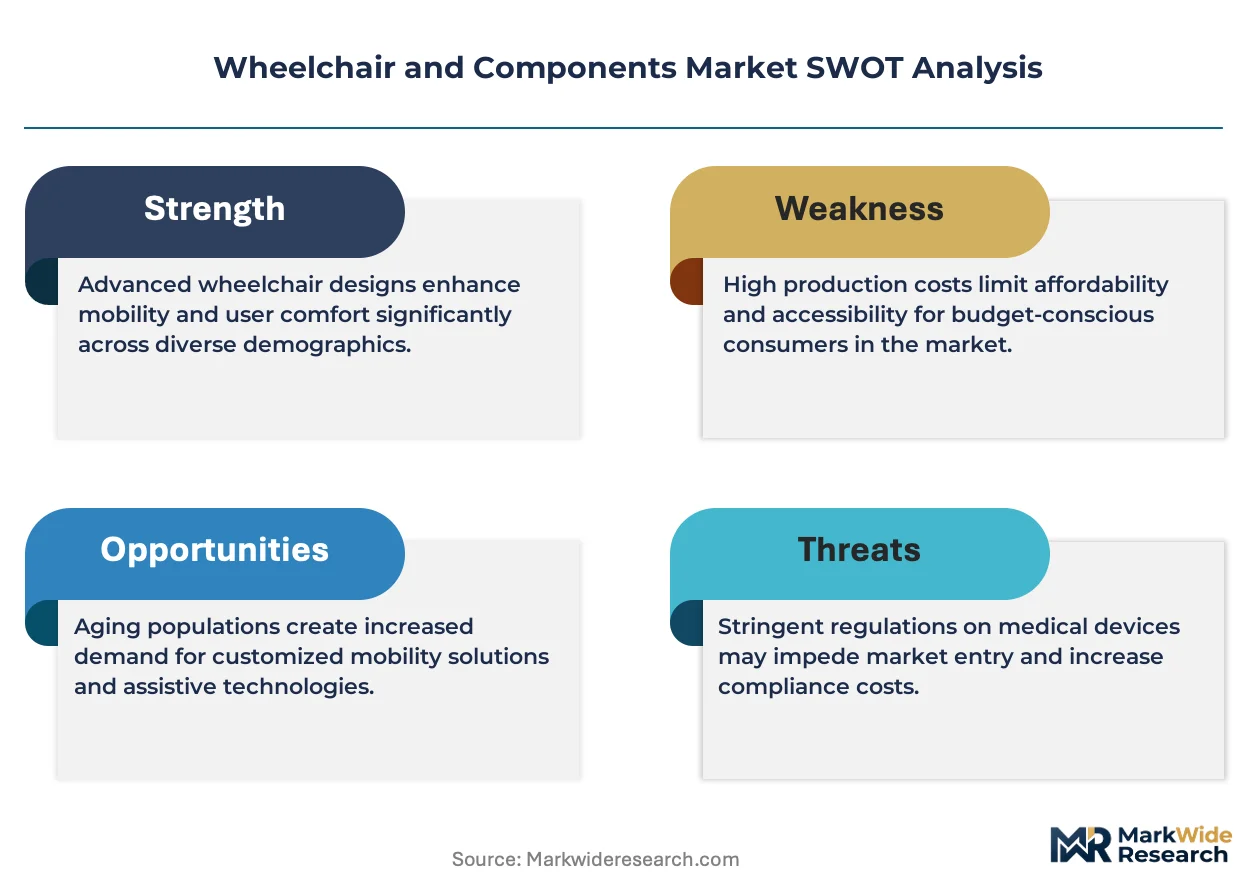
This market operates as a defensive-moat arena where regulatory entrenchment through FDA 510(k) clearance and ATP certification requirements creates substantial switching costs for institutional procurement.
For Market Incumbents: Harden market position through backward integration into lithium-ion battery pack assembly and captive production of joystick control modules. Consolidate independent dealer networks in rural United States markets where technician scarcity constrains new entrant penetration. Prioritize certification investment for ISO 7176-4 electromagnetic compatibility standards ahead of compliance deadlines.
For New Entrants and Emerging Players: India's Ayushman Bharat assistive device coverage represents the most penetrable entry point for motorized mobility platforms. Localized assembly partnerships in Maharashtra and Gujarat circumvent import duty structures while serving price-sensitive institutional procurement. Telehealth-integrated seating assessment protocols offer a differentiated go-to-market angle against established ATP-dependent distribution.
For Investors and Strategic Acquirers: Capital is best deployed toward component specialists with captive control electronics production and established reimbursement code navigation capabilities. Long-term viability hinges on positioning within Medicare Advantage and statutory health insurance procurement frameworks. Watch for FDA clearance timeline compression as an inflection indicator for novel sensor configuration viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Navigation of Medicare Advantage and statutory health insurance codes determines product access. |
| CE Marking Pathway | EU MDR post-market surveillance mandates elevate compliance overhead for powered mobility entrants. |
| Hospital System Partnership | Sole-source agreements with group purchasing organizations secure institutional procurement volumes. |
| Software Companion Development | Telehealth-integrated diagnostics reduce clinical visit requirements for seating prescriptions. |
| Backward Integration | In-house production of motor-gearbox assemblies mitigates single-source supply vulnerability. |
Study Parameters
Cross-validation between primary interviews with rehabilitation engineers, ATP-certified technicians, GPO contracts managers, and hospital procurement committees anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, CMS Medicare reimbursement databases, statutory health insurance procurement records, and ISO 7176 technical standards. Bottom-up and top-down triangulation reconciles component-level cost structures with end-user demand segmentation.
Calibration against historical replacement cycles and reimbursement code revision timelines shapes the analytical framework across the analysis window. Segmentation dimensions span product type, end-user setting, component subassembly, and distribution channel, with regional regulatory clusters as an additional modeling layer. CAGRs derive from fitted growth curves applied to procurement volume trajectories. Forecast inputs include lithium-ion cell cost curves and ISO compliance deadline schedules.
Practitioners should monitor reimbursement code revisions, aluminum alloy price volatility, and FDA clearance timeline extensions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Manual Resuscitators Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Artificial Pancreas Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
South Korea ECG Market
Medical Devices
Ehealth Devices Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
Global Infusion Pumps and Accessories Market