
 Digital Slit Lamp Market | 2026-2036
Digital Slit Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Slit Lamp Market Insights
Japanese optical equipment manufacturing is restructuring capacity toward digital ophthalmic diagnostics. Carl Zeiss Meditec AG leverages its precision optics heritage to dominate high-resolution imaging configurations. Topcon Corporation anchors its position through integrated software-hardware platforms for glaucoma assessment workflows. Haag-Streit Group specializes in premium tabletop systems for cataract surgery suites across European university hospitals.
A digital slit lamp integrates a binocular microscope with an adjustable light source to examine anterior and posterior eye structures at magnifications typically spanning 6x to 40x, with digital cameras capturing real-time images for documentation and telemedicine transmission. Its primary purpose enables clinicians to diagnose corneal disorders, monitor cataract progression, and assess retinal health through controlled illumination angles. Tabletop slit lamps occupy the dominant revenue position due to their stability and advanced imaging capabilities in hospital settings, while smartphone-based variants represent the fastest-expanding category as point-of-care screening extends into rural optometry offices. LED illumination technology leads installed bases for energy efficiency and color temperature consistency, though optical coherence tomography integration commands premium pricing in glaucoma assessment applications.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product development timelines and market access requirements for digital slit lamp manufacturers. ISO 10993 biocompatibility standards and IEC 60601 electrical safety protocols govern materials and operational specifications across all commercialized units. Stakeholders must monitor evolving reimbursement codes for digital imaging in teleophthalmology, as payer acceptance will determine whether portable and smartphone-based configurations achieve sustainable clinical adoption outside traditional hospital settings.
Market Dynamics
Smartphone-compatible digital slit lamp configurations are compressing traditional procurement cycles as tier-two hospital networks in China and rural optometry offices in India bypass capital-intensive tabletop systems for point-of-care screening workflows.
Growth Catalysts
- LED Illumination Mandates:Germany's Krankenhauszukunftsgesetz hospital modernization program incentivizes energy-efficient diagnostic equipment replacement, accelerating LED-retrofit procurement across university hospital cataract surgery suites.
- Teleophthalmology Reimbursement:Japan's Ministry of Health, Labour and Welfare expanded national health insurance coverage for remote anterior segment imaging in 2023, validating digital capture capabilities as standard-of-care infrastructure.
- Domestic Manufacturing Scale:China's NMPA streamlined Class II medical device registration for locally produced smartphone-adaptable slit lamps, reducing time-to-market for indigenous suppliers serving county-level hospital networks.
Market Restraints
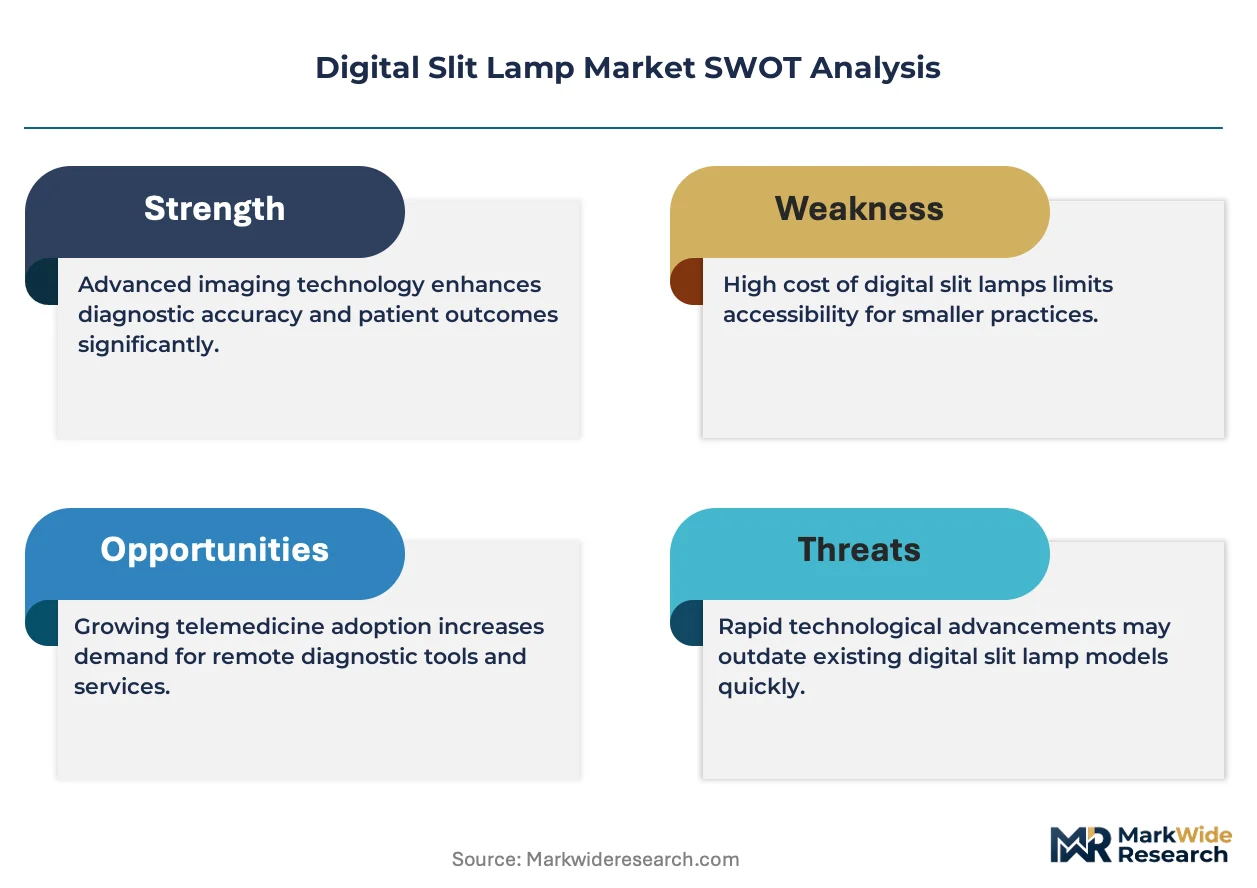
- Premium Optical Component Concentration:High-resolution objective lenses and precision micrometer stages rely on concentrated supply from German and Swiss precision optics foundries, creating vulnerability to capacity constraints.
- EU MDR Compliance Burden:The Medical Device Regulation's enhanced clinical evidence requirements for diagnostic imaging devices extend certification timelines and inflate regulatory affairs staffing costs for mid-tier manufacturers.
- Optical Coherence Tomography Substitution:Integrated OCT systems for glaucoma assessment capture overlapping diagnostic data, pressuring standalone digital slit lamp pricing in advanced hospital settings.
Strategic Opportunities
- Veterinary Ophthalmology Extension:Companion animal specialty clinics in the United States represent an underpenetrated vertical where portable digital slit lamps address unmet diagnostic workflow needs.
- 5G-Enabled Real-Time Transmission:Convergence of high-resolution digital capture with low-latency cellular networks enables synchronous teleconsultation models for rural screening programs in Brazil and Indonesia.
- India PLI Scheme Alignment:The Production Linked Incentive scheme for medical devices offers tariff and tax advantages to domestic assembly operations targeting government hospital procurement tenders.
Industry Challenges
- Biomedical Optics Talent Scarcity:The intersection of precision mechanical engineering and clinical ophthalmology knowledge creates acute hiring bottlenecks for product development teams.
- Legacy EMR Integration Complexity:Proprietary image formats from incumbent equipment vendors obstruct seamless data exchange with hospital information systems, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Slit Lamp Market |
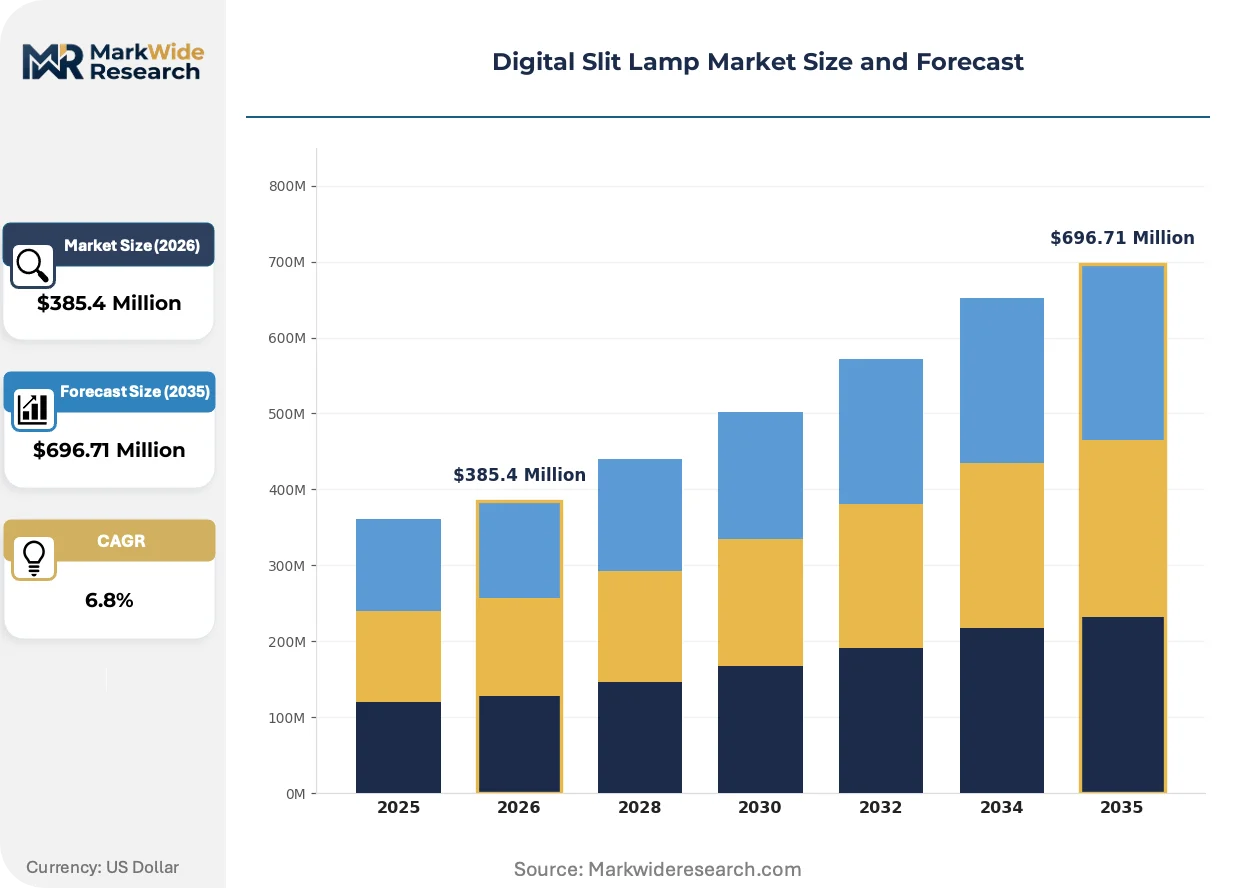
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Slit Lamp, Tabletop Slit Lamp, Smartphone-based Slit Lamp, Digital Imaging Slit Lamp End User: Ophthalmology Clinics, Hospitals, Research Institutes, Optometry Offices Technology: LED Illumination, Optical Coherence Tomography, High-resolution Imaging, Autofocus Technology Application: Routine Eye Examination, Cataract Surgery, Glaucoma Assessment, Corneal Analysis |
| Companies Covered | Haag-Streit Group, Topcon Corporation, Carl Zeiss Meditec AG, NIDEK Co., Ltd., Keeler Ltd., Huvitz, 66 Vision Tech Co., Ltd., Takagi Seiko Co., Ltd., Reichert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Slit Lamp Market Trends and Innovations
Artificial intelligence inference at the edge is restructuring diagnostic workflows by embedding automated pathology detection directly into capture devices, reducing specialist interpretation bottlenecks in high-volume screening environments.
Smartphone adapter systems are decentralizing anterior segment examination access by converting ubiquitous mobile devices into clinical-grade imaging platforms. Community health workers in sub-Saharan African outreach programs deploy these configurations for diabetic retinopathy screening. The technology is decentralizing diagnostic authority from centralized hospital ophthalmology departments to primary care touchpoints.
The EU AI Act's risk classification framework for medical device software is reshaping development roadmaps for automated image analysis modules. Manufacturers must now document algorithmic transparency and clinical validation datasets before CE marking. Glaucoma progression algorithms face the most stringent conformity assessment pathways, compressing competitive timelines for European market entry.
Hospital procurement departments are unbundling after-sales service contracts from equipment purchases, negotiating separate maintenance agreements with third-party technical service providers. This disintermediation pressures original equipment manufacturers to defend margin through proprietary spare parts access and software license structures. The shift is most pronounced in German and French university hospital consortia with centralized purchasing authority.
Digital Slit Lamp Market Segmentation
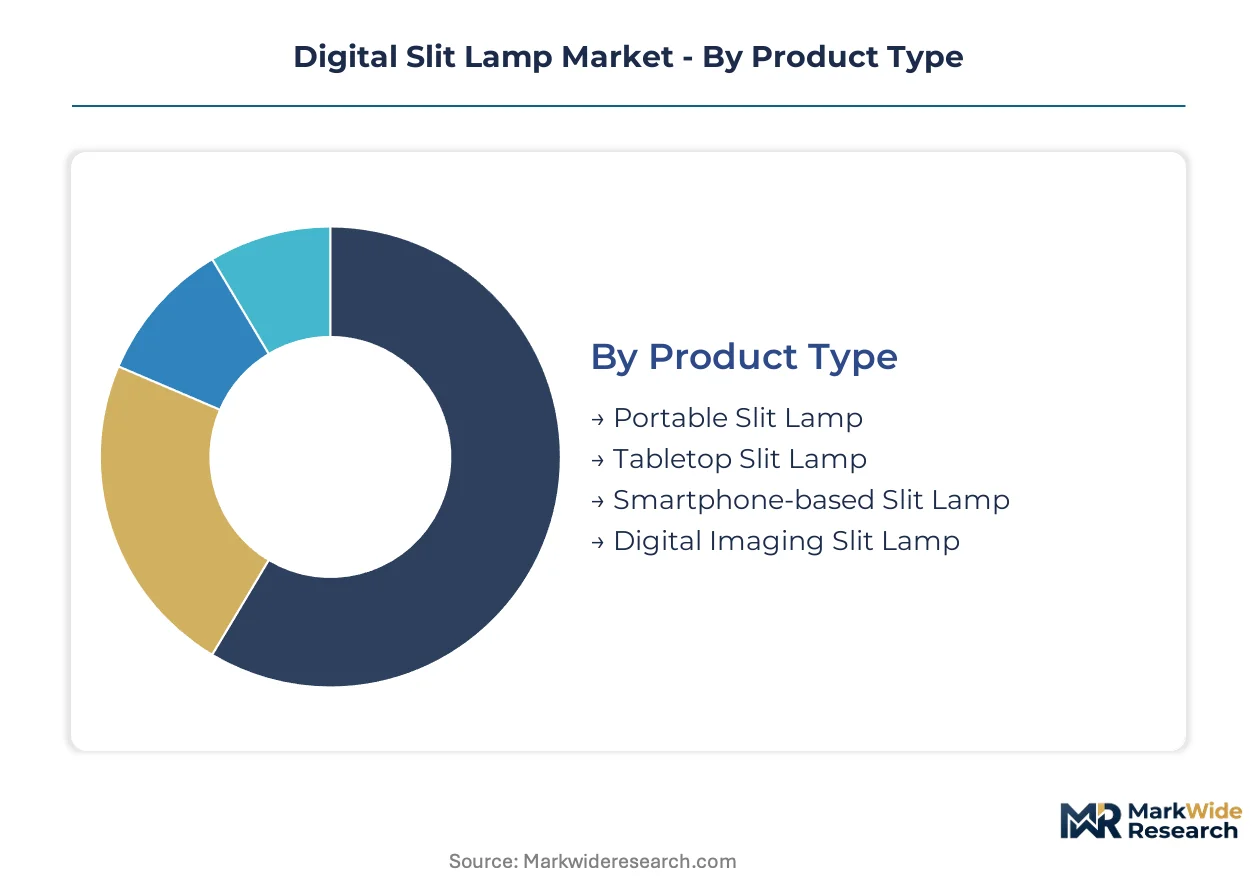
Digital slit lamp segmentation reveals divergent commercial logic across hardware configurations and clinical deployment models. Procurement patterns split between capital-intensive hospital installations and distributed point-of-care screening networks.
Product Type:
Standalone diagnostic units dominate installed bases, while embedded smartphone configurations are compressing procurement cycles in resource-constrained settings.
- Tabletop Slit Lamp:Binocular microscopes mounted on stabilized mechanical columns deliver magnifications from 6x to 40x with precision illumination control. University hospital cataract surgery suites in Germany prioritize these configurations for surgical planning workflows. LED retrofit mandates under the Krankenhauszukunftsgesetz program are accelerating replacement demand.
- Smartphone-based Slit Lamp:Adapter systems convert mobile devices into clinical-grade anterior segment imaging platforms with wireless image transmission. County-level hospital networks in China deploy these for diabetic retinopathy screening programs. NMPA streamlined Class II registration pathways reduce indigenous supplier time-to-market.
- Portable Slit Lamp:Battery-powered units with collapsible optical paths enable field deployment in veterinary and outreach settings.
- Digital Imaging Slit Lamp:Integrated camera modules capture real-time documentation for telemedicine transmission and EMR archiving.
Tabletop configurations lead volumes today; smartphone-based alternatives are gaining share fastest.
End User:
Customer archetypes diverge sharply in procurement authority, with hospital systems negotiating enterprise contracts while independent practices prioritize capital efficiency.
- Hospitals:Integrated health systems command volume purchasing leverage through centralized procurement consortia. French and German university hospital networks unbundle service contracts from equipment purchases, pressuring OEM margin structures.
- Ophthalmology Clinics:Specialty practices concentrate demand for premium imaging configurations with OCT integration. Japanese clinics expanded procurement of LED-illuminated units following teleophthalmology reimbursement expansion.
- Optometry Offices:Primary care touchpoints in rural India and Brazil adopt smartphone-adaptable systems for decentralized screening.
- Research Institutes:Academic medical centers drive demand for experimental autofocus and high-resolution configurations.
Hospitals anchor current revenue; optometry offices show the steepest expansion trajectory.
Technology:
Illumination and imaging modalities stratify across performance tiers, with premium integrations commanding substantial price multiples over baseline configurations.
- LED Illumination:Solid-state light sources deliver consistent color temperature and energy efficiency across 10,000+ hour operational lifespans. Germany's hospital modernization program explicitly incentivizes LED-equipped diagnostic replacements.
- Optical Coherence Tomography:Cross-sectional imaging modules capture retinal and anterior segment morphology at micron-scale resolution. Glaucoma assessment workflows command premium pricing for integrated OCT-digital slit lamp combinations.
- High-resolution Imaging:Digital camera sensors exceeding 5 megapixels enable teleconsultation-grade documentation.
- Autofocus Technology:Automated optical alignment reduces operator dependency in high-volume screening environments.
LED illumination dominates installed bases; OCT integration carries the highest revenue per unit.
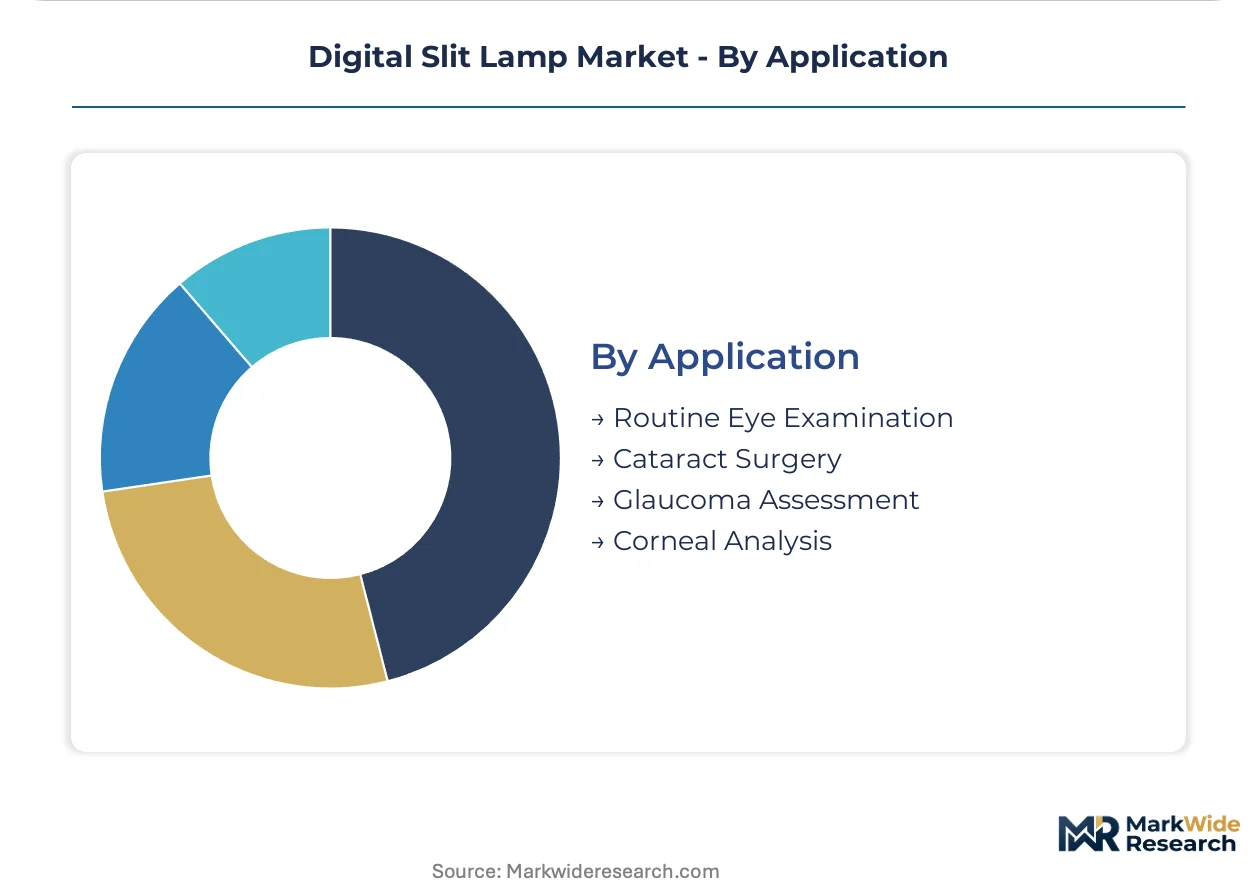
Application:
Clinical use cases determine specification requirements, from rapid throughput screening to precision surgical planning.
- Cataract Surgery:Preoperative biometry and IOL power calculation demand precise anterior chamber depth measurement. European university hospitals specify premium tabletop systems with integrated imaging for surgical suite workflows.
- Glaucoma Assessment:Gonioscopy and optic nerve head evaluation require adjustable illumination angles and documentation capabilities. The EU AI Act's risk classification framework imposes stringent validation requirements on automated progression algorithms.
- Routine Eye Examination:High-volume screening programs prioritize throughput and operator efficiency.
- Corneal Analysis:Specialized illumination techniques assess endothelial cell density and topography.
Cataract surgery drives the largest equipment budgets; glaucoma assessment shows expanding software attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration follows divergent regulatory compliance costs, with China's NMPA streamlining Class II device pathways while EU MDR obligations extend European certification timelines. Production capacity is reallocating toward jurisdictions offering faster time-to-market without sacrificing quality benchmarks.
China
County-level hospital networks drive procurement of smartphone-adaptable slit lamps for diabetic retinopathy screening programs. NMPA's simplified registration for locally manufactured Class II devices compresses indigenous supplier launch schedules. Yangtze River Delta optical component clusters scale output of LED illumination modules for domestic and export markets.
Germany
University hospital cataract surgery suites prioritize premium tabletop configurations with integrated imaging capabilities. The Krankenhauszukunftsgesetz hospital modernization program mandates energy-efficient diagnostic equipment replacement, accelerating LED-retrofit demand. Precision optics foundries in Baden-Württemberg concentrate supply of high-resolution objective lenses for global OEM integration.
Japan
Ophthalmology clinics expanded LED-illuminated unit procurement following 2023 national health insurance coverage expansion for remote anterior segment imaging. METI coordinates domestic manufacturing capacity restructuring toward digital ophthalmic diagnostics. Kanto region precision equipment manufacturers anchor integrated software-hardware platform development for glaucoma assessment workflows.
United States
Veterinary ophthalmology specialty clinics represent an underpenetrated vertical for portable digital slit lamp deployment. FDA 510(k) clearance pathways shape product development timelines for diagnostic imaging device market access. Greater Boston academic medical centers drive experimental demand for autofocus and high-resolution imaging configurations.
India
Rural optometry offices adopt smartphone-based systems for decentralized screening workflows bypassing capital-intensive tabletop procurement. The Production Linked Incentive scheme for medical devices offers tariff and tax advantages to domestic assembly operations targeting government hospital tenders. Maharashtra and Karnataka medical device manufacturing zones attract component sourcing for regional supply chain localization.
Digital Slit Lamp Market Competitive Landscape
German and Swiss precision optics producers anchor the premium component tier; East Asian specialists hold integrated system assembly advantages. Market structure consolidates around three to five dominant equipment vendors with established regulatory track records, while mid-tier competitors face margin compression from certification cost inflation. Strategic archetypes separate heritage optics houses from software-integrated platform developers and volume-scale domestic manufacturers. Competitive moves concentrate on M&A for regulatory dossier acquisition and geographic expansion through distributor network consolidation.
Within the heritage optics tier, Carl Zeiss Meditec AG and Haag-Streit Group exemplify precision engineering lineage translated into clinical-grade diagnostic platforms. Topcon Corporation occupies a position bridging hardware manufacturing with integrated software ecosystems for specialty ophthalmology workflows. These three entities represent divergent strategic postures: German-engineered component supremacy, Swiss surgical-suite specialization, and Japanese platform integration.
| Leading Market Players |
|---|
| Haag-Streit Group |
| Topcon Corporation |
| Carl Zeiss Meditec AG |
| NIDEK Co., Ltd. |
| Keeler Ltd. |
| Huvitz |
| 66 Vision Tech Co., Ltd. |
| Takagi Seiko Co., Ltd. |
| Reichert |
| Others |
Pricing and Supply Chain Analysis
Precision optics foundry capacity in Baden-Württemberg and Jura feeds directly into three-tier pricing stratification across premium, standard, and economy equipment tiers, with LED illumination module costs transmitting downstream through distributor markups to university hospital procurement desks in Germany and Japan.
Pricing Analysis
Distributor margins compress between 15 and 25 points depending on after-sales bundling and OEM brand equity. Three-tier pricing structure across premium, standard, and economy levels separates integrated OCT configurations from standalone digital imaging units and smartphone-adaptable entry systems. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification grade, with cost compression in the economy tier intensifying as Chinese domestic manufacturers scale NMPA-registered production. Independent optometry offices in rural India exhibit highest price sensitivity; European university hospital consortia with unbundled service contracts show lowest.
Supply Chain Analysis
Dual-sourcing requirements from German and Swiss OEMs mandate multi-supplier qualification for high-resolution objective lenses and precision micrometer stages. Geographic supply concentration centers on Germany, Switzerland, and Japan for optical components, with China scaling LED illumination module and smartphone adapter assembly. Raw material dependencies include rare-earth doped glass, aluminum alloy housings, and CMOS imaging sensors. Single-source vulnerability concentrates in Swiss precision optics foundries for sub-micron tolerance lens grinding. Distribution runs through specialized medical device distributors with regulatory dossier expertise, anchored by GPO contracts in US hospital systems and centralized procurement consortia in France and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital slit lamp market compounds steadily as chronic ophthalmic disease prevalence rises with aging demographics across developed economies, sustaining replacement demand for LED-retrofit configurations and software-integrated platforms.
For Market Incumbents: Extend software-hardware integration depth to defend attach rates against standalone OCT substitution in glaucoma assessment workflows. Deepen backward integration into precision optics component supply through captive production or long-term offtake agreements with Baden-Württemberg foundries. Lock hospital system procurement through bundled EMR integration and proprietary image format ecosystems that obstruct middleware disintermediation. For New Entrants and Emerging Players: NMPA's streamlined Class II registration in China opens a window for indigenous suppliers to capture county-level hospital procurement through smartphone-adaptable configurations priced below tabletop import equivalents. Target veterinary ophthalmology specialty clinics in the United States as the most penetrable vertical, where portable battery-powered units address unmet diagnostic workflow needs outside human healthcare reimbursement complexity. Pursue direct-to-practice digital marketing with teleophthalmology software companion bundles. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs inflate regulatory affairs staffing beyond mid-tier manufacturer cash flow capacity. Long-term viability favors heritage optics houses with established 510(k) and CE marking track records, integrated software platforms, and distributor network density across three or more major geographies. Watch for inflection where teleophthalmology reimbursement expansion in additional national health insurance systems validates portable configuration clinical adoption outside traditional hospital settings.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance timelines determine competitive entry windows for automated pathology detection modules. |
| Hospital System Partnership | French and German university hospital consortia unbundle service contracts, pressuring OEM margin defense through software licensing. |
| Software Companion Development | AI inference at the edge reduces specialist interpretation bottlenecks in high-volume diabetic retinopathy screening programs. |
| Reimbursement Strategy | Japan's Ministry of Health, Labour and Welfare coverage expansion validates digital capture as standard-of-care infrastructure. |
| Backward Integration | Captive supply of precision optics components insulates margin from Swiss and German foundry capacity constraints. |
Research Methodology
Coverage spans Germany, Japan, China, the United States, and India, with primary inputs from each market gathered through structured interviews with hospital purchasing committee members, biomedical optics engineers, ophthalmology clinic directors, GPO contracts managers, and regulatory affairs specialists at device manufacturers. Secondary validation draws from FDA 510(k) filings, NMPA Class II registration databases, EU MDR notified body documentation, hospital procurement tender records, and national health insurance reimbursement code updates. Bottom-up equipment shipment data triangulates against top-down healthcare expenditure modeling across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, end user, technology, and application dimensions. The analytical framework projects demand through the projection horizon by modeling cataract surgery volume trends, glaucoma prevalence trajectories, and teleophthalmology reimbursement expansion patterns. CAGRs derive from logistic diffusion curves fitted to technology adoption histories in comparable diagnostic imaging categories, with cross-validation against capital expenditure plans from major hospital systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement intensity and optical component supply disruption scenarios. Deviation in teleophthalmology payer acceptance timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transseptal Access Systems Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Corneal Implants Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Cranial Closure and Fixation Devices Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Fracture Fixation Products Market
Medical Devices
Embolic Protection Systems Market
Medical Devices
Global Thermodilution Catheter Market
Medical Devices
Global Smart Contact Lenses Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
United States Drug Delivery Devices Market