
 Hospital Outsourcing Market | 2026-2036
Hospital Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Outsourcing Market Analysis
Multi-source contracting for non-clinical hospital functions is pivoting as health systems seek operational resilience after pandemic-era supply disruptions. Sodexo S.A. leverages its integrated facility management platform to anchor large academic medical center relationships across France and the United Kingdom. Aramark Corporation competes through specialized food service and environmental services contracts that sustain margin pools in the North American hospital segment. Compass Group PLC differentiates via technology-enabled patient dining and retail operations that dominate the premium private hospital channel.
Hospital outsourcing encompasses the delegation of ancillary, administrative, and select clinical support functions to third-party vendors under governed service agreements, typically governed by performance-based SLAs covering response times, staffing ratios, and quality benchmarks. Its primary purpose is to reduce fixed cost structures while preserving clinical focus and regulatory compliance within acute care environments. Facility management and medical staffing command the largest contract value pools, while IT services represent the fastest-growing segment as Epic and Cerner migrations drive demand for specialized implementation labor. Managed services contracts are displacing fixed-price arrangements where outcome-based metrics align vendor incentives with hospital operational targets.
FDA oversight of hospital laboratory operations, HIPAA security rule enforcement by the Office for Civil Rights, and OSHA workplace safety standards collectively elevate compliance costs for in-house operations and expand the vendor addressable market. The EU AI Act and GDPR frameworks in Europe impose additional data governance requirements on IT outsourcing contracts that process patient information across borders. Stakeholders must monitor how CMS reimbursement rule changes and state-level staffing ratio mandates reshape the economics of insourcing versus outsourcing for clinical support functions.
Market Dynamics
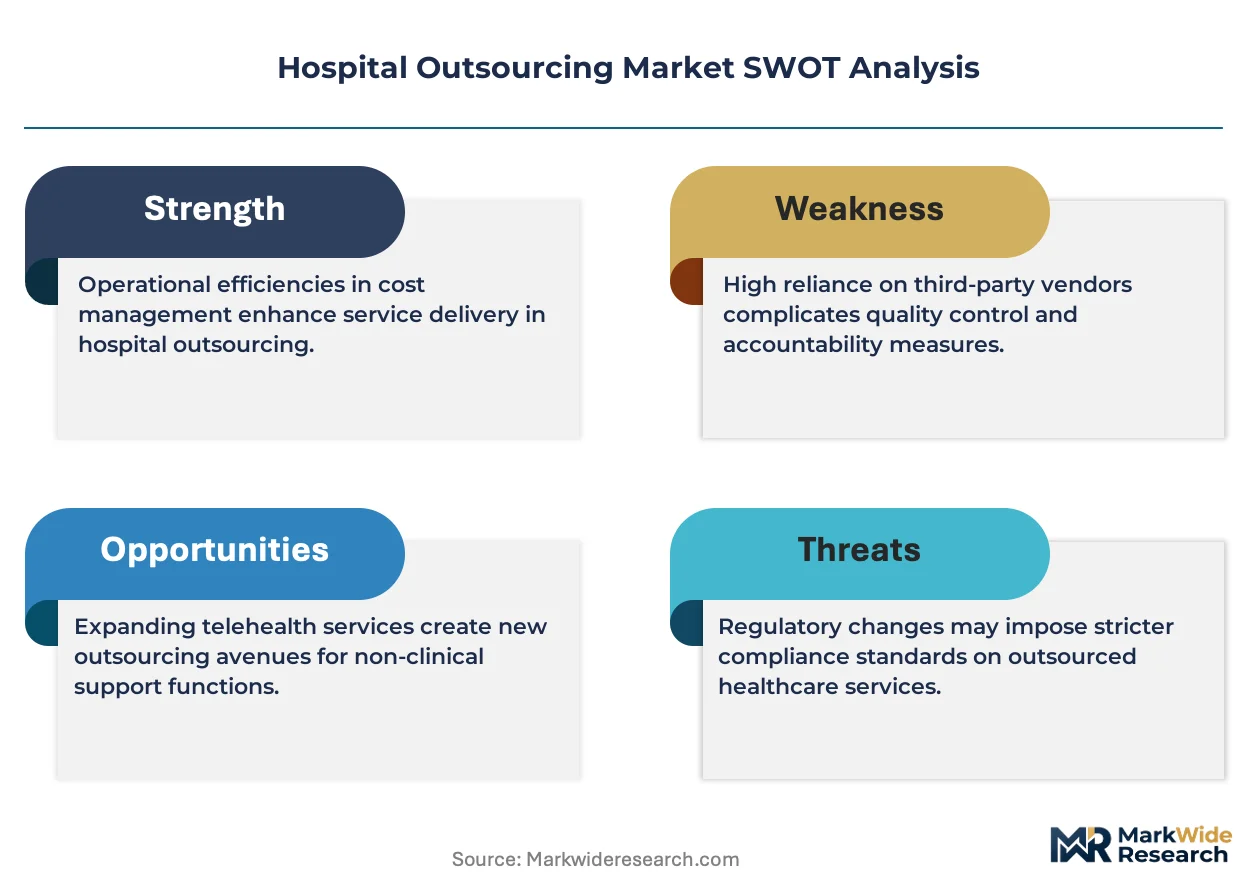
Hospital outsourcing is absorbing structural pressure from workforce shortages and interoperability mandates that force health systems to externalize non-core functions while maintaining clinical governance.
Growth Catalysts
- HIPAA Security Rule enforcement:The Office for Civil Rights has intensified audit frequency for covered entities, pushing hospitals toward specialized vendors with dedicated compliance infrastructure rather than building in-house security operations centers.
- EHR migration waves:Epic and Cerner implementation cycles create surge demand for certified technical labor that hospital IT departments cannot staff permanently, expanding the addressable market for specialized implementation partners.
- Germany's hospital reform legislation:The country's 2022 Hospital Structures Act mandates efficiency targets that academic medical centers meet through facility management outsourcing to Sodexo and Aramark.
Market Restraints
- Labor cost volatility:Nursing wage inflation in the United States and United Kingdom compresses margins on medical staffing contracts where rate escalation clauses lag market movements by 12-18 months.
- Vendor concentration risk:Three integrated facility management groups control 60% of large hospital contracts in France and the United Kingdom, limiting competitive tension and procurement leverage for health systems.
- Data localization requirements:India's Digital Personal Data Protection Act restricts cross-border patient data flows, fragmenting IT service delivery models that relied on offshore processing centers.
Strategic Opportunities
- India's tier-2 city hospital expansion:Private hospital chains in Lucknow, Jaipur, and Kochi lack scale for in-house biomedical engineering and environmental services, creating first-mover advantages for outsourced asset management.
- EU AI Act compliance services:Risk classification requirements for clinical decision support tools open specialized consulting and validation services for vendors serving European hospital networks.
- Remote patient monitoring integration:Convergence of IoT sensor platforms and cloud-based analytics enables outsourced chronic care management that extends vendor relationships beyond hospital walls into post-acute settings.
Industry Challenges
- Epic certification scarcity:The limited pipeline of credentialed implementation specialists creates project bottlenecks and wage spirals that erode contract profitability for IT service providers.
- Legacy system interoperability:Hospitals running 1990s-era patient accounting platforms require expensive middleware development to connect with modern cloud-based outsourcing platforms, delaying ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Outsourcing Market |
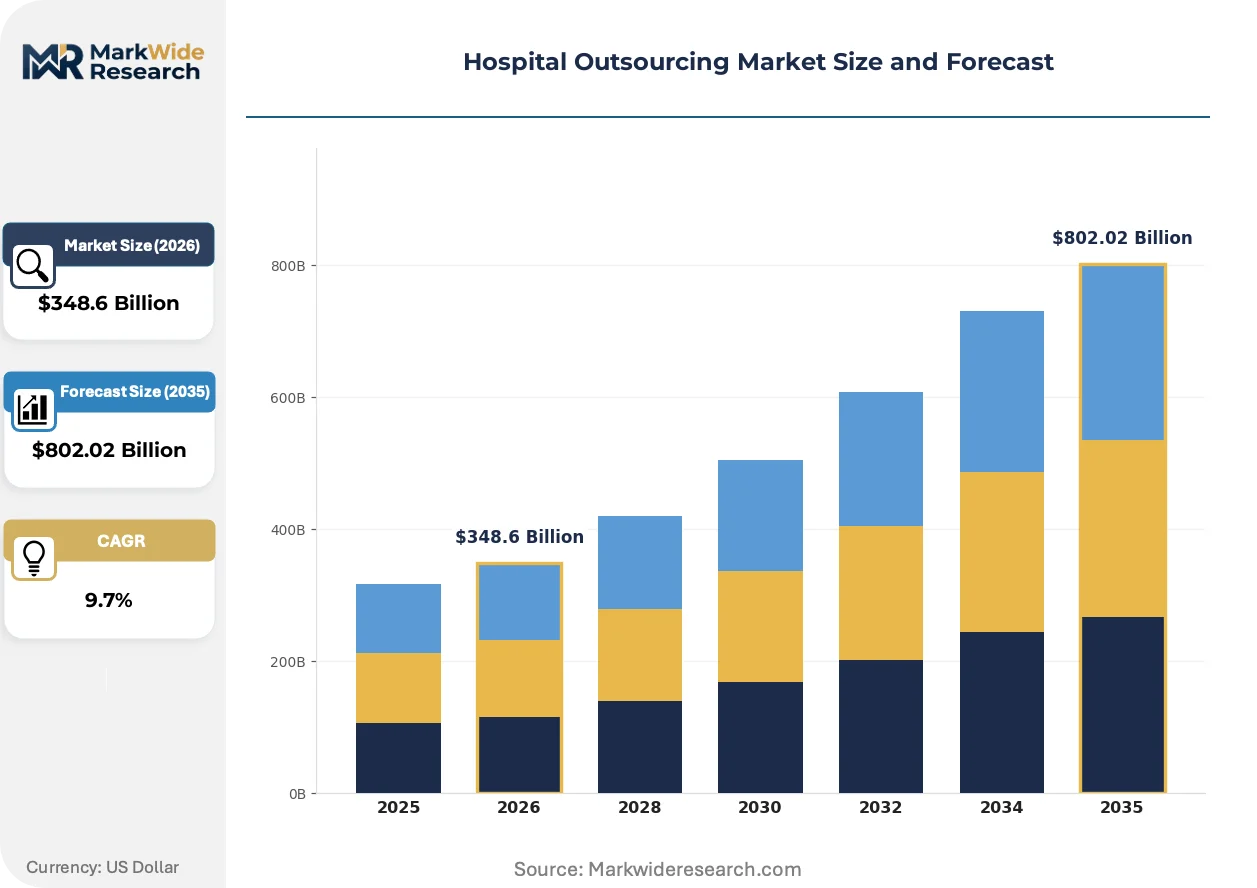
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $802.02 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Facility Management, Medical Staffing, IT Services, Procurement Services End User: Public Hospitals, Private Hospitals, Specialty Clinics, Rehabilitation Centers Contract Type: Fixed-Price, Cost-Plus, Time and Materials, Managed Services Functionality: Billing Services, Patient Management, Supply Chain Management, Laboratory Services |
| Companies Covered | Sodexo S.A., Aramark Corporation, Compass Group PLC, ABM Industries Incorporated, Cerner Corporation, Allscripts Healthcare Solutions Inc., LogistiCare Solutions LLC, The Allure Group, ModivCare Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Outsourcing Market Emerging Trajectories
Artificial intelligence and automation are restructuring how hospitals procure and manage outsourced services, shifting from cost-based vendor selection to outcome-governed partnerships that align payment with operational metrics.
Robotic process automation is absorbing repetitive revenue cycle tasks previously handled by offshore business process outsourcing teams. Large integrated delivery networks in Texas and Florida are deploying RPA for prior authorization and claims status checking, compressing the headcount requirements that defined traditional medical billing contracts. The technology is absorbing labor arbitrage value and forcing vendors to reprice contracts around exception-handling expertise rather than transaction volume.
The EU AI Act's risk-based classification system for healthcare algorithms is restructuring vendor liability frameworks. Medical device software that supports clinical decisions now requires conformity assessment procedures that few outsourcing providers have built, creating competitive separation between certified and uncertified service tiers. European hospital procurement teams are embedding AI governance requirements into IT outsourcing RFPs, favoring vendors with established quality management systems.
Subscription-based staffing models are displacing traditional per-diem arrangements in North American nursing labor markets. Health systems in California and New York now purchase guaranteed FTE blocks through platform intermediaries that manage credentialing, scheduling, and compliance, replacing fragmented agency relationships. This shift concentrates purchasing power among larger hospital systems and compresses margins for regional staffing agencies that lack platform scale.
Hospital Outsourcing Market Segmentation
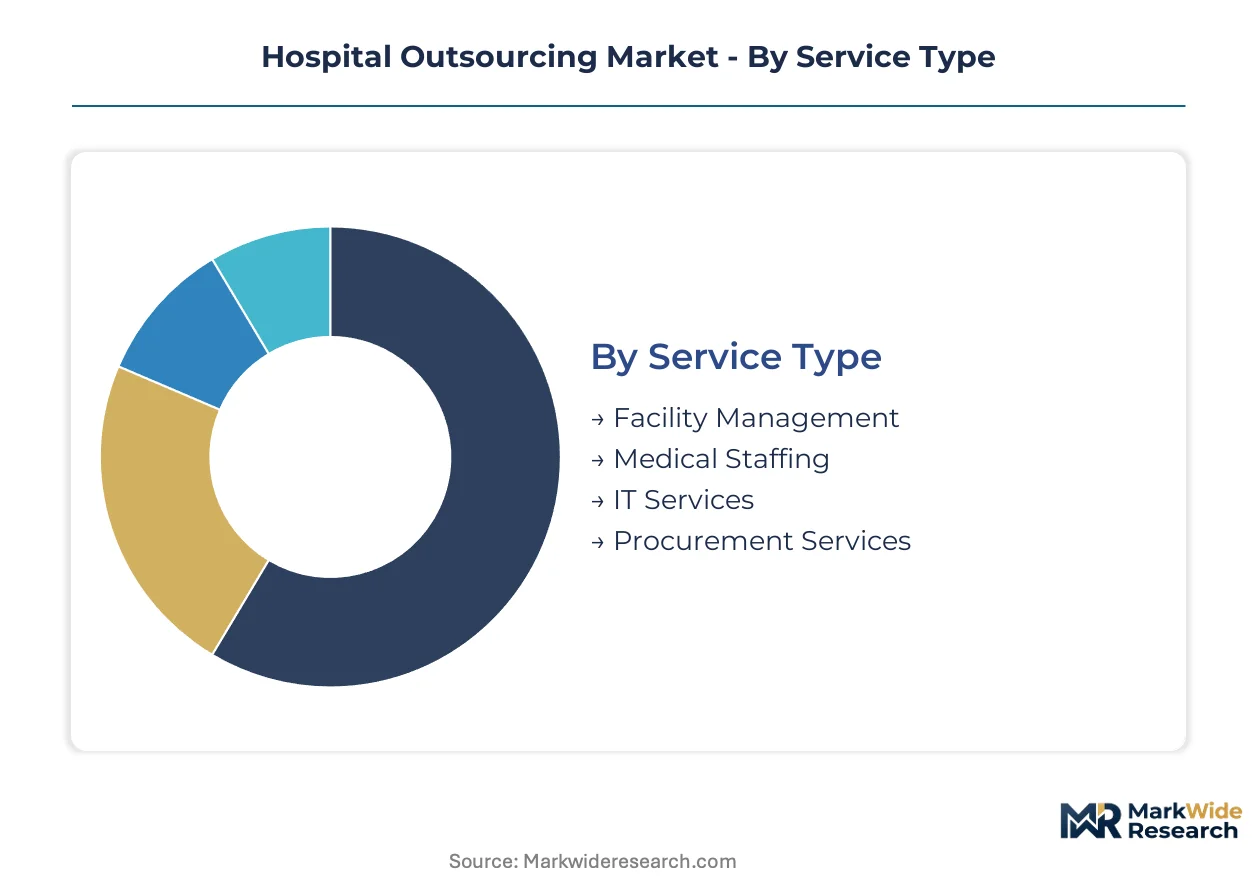
Hospital outsourcing contracts fragment across service depth and governance models. Procurement teams weigh standalone vendor relationships against integrated platforms that bundle multiple functions under unified performance frameworks.
Service Type:
Integration depth varies sharply — some services embed within hospital operational workflows while others operate as parallel vendor-managed systems.
- Facility Management:Encompasses environmental services, food operations, and physical plant maintenance through integrated service platforms. Academic medical centers in the United States and Germany anchor demand as deferred maintenance backlogs and energy efficiency mandates force externalization of capital-intensive infrastructure functions.
- Medical Staffing:Supplies credentialed nursing, allied health, and clinical support personnel under flexible engagement structures. California and New York health systems drive volume through subscription-based FTE blocks that replace fragmented per-diem agency relationships.
- IT Services:Epic and Cerner implementation, cybersecurity operations, and legacy system integration.
- Procurement Services:Medical supply sourcing, vendor management, and spend analytics.
Facility management leads volumes today; IT services is gaining share fastest.
End User:
Contract complexity scales with institutional scale and regulatory exposure.
- Private Hospitals:Premium facilities with consolidated vendor relationships and outcome-based SLAs.
- Public Hospitals:Government-funded institutions with rigid procurement frameworks and compliance-heavy contracting.
- Specialty Clinics:Focused care centers outsourcing discrete functions like laboratory services or revenue cycle management.
- Rehabilitation Centers:Post-acute facilities with specialized staffing and equipment maintenance needs.
Public hospitals dominate contract count; private hospitals command the steepest expansion trajectory.
Contract Type:
Payment structures align vendor incentives with operational outcomes through varying risk allocation mechanisms.
- Managed Services:Comprehensive outsourcing with performance-based pricing tied to quality benchmarks and cost reduction targets. Large integrated delivery networks prefer this model for facility management and IT functions where vendor accountability spans multiple operational metrics.
- Fixed-Price:Predetermined fees for defined scope with limited flexibility for scope changes.
- Cost-Plus:Reimbursement of actual costs plus margin, common in construction and capital projects.
- Time and Materials:Hourly or daily rates for staff augmentation and project-based technical labor.
Fixed-price contracts anchor current procurement; managed services is climbing the fastest.
Functionality:
Process automation and interoperability requirements reshape which functions hospitals externalize versus retain in-house.
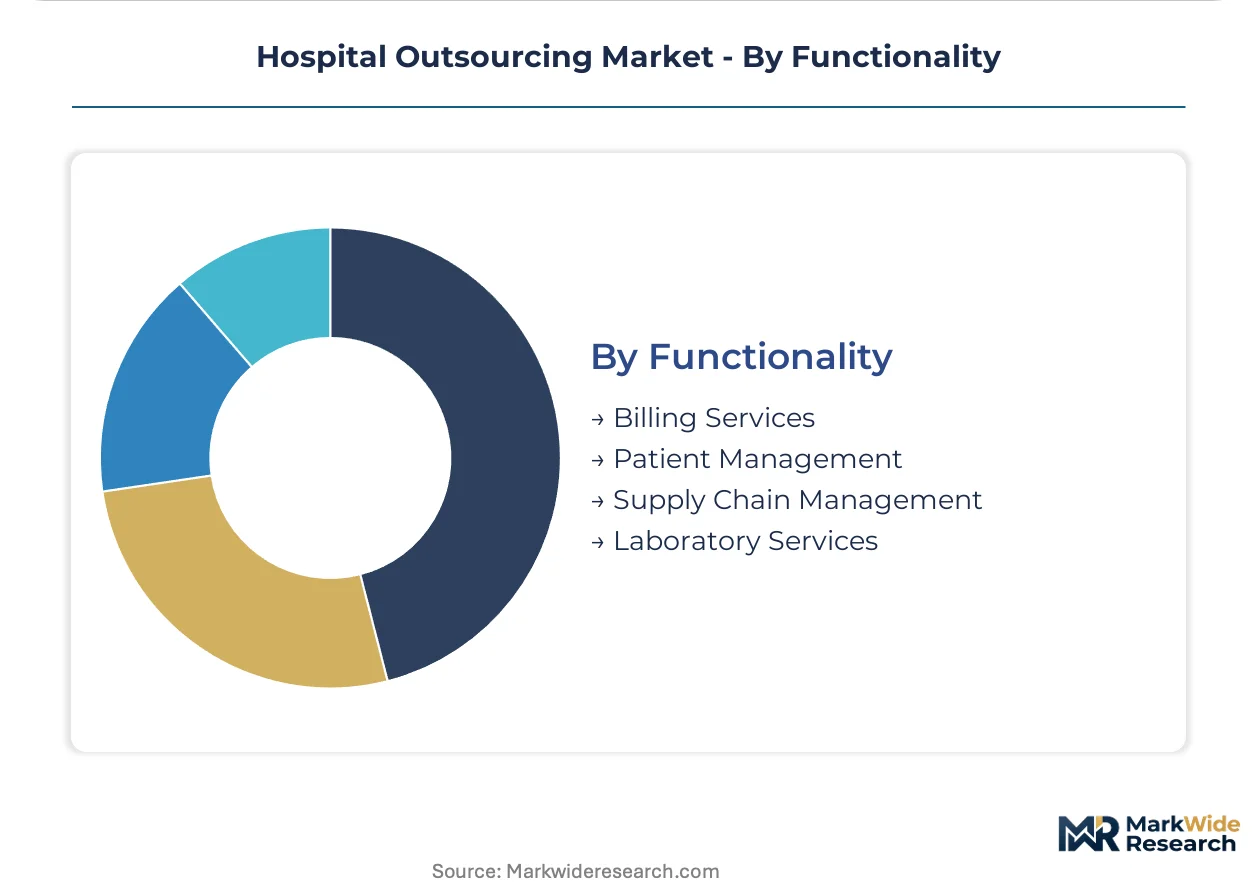
- Billing Services:Revenue cycle management, claims processing, and denial management through robotic process automation. Texas and Florida health systems deploy RPA for prior authorization and eligibility verification, compressing headcount requirements that defined traditional offshore medical billing contracts.
- Patient Management:Scheduling, registration, and care coordination workflows.
- Supply Chain Management:Inventory optimization, procurement analytics, and vendor consolidation.
- Laboratory Services:Clinical and anatomic pathology, reference testing, and point-of-care coordination.
Billing services leads functional outsourcing volumes; patient management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting hospital outsourcing contracts toward jurisdictions where compliance infrastructure costs less to maintain. Vendors relocate service delivery to exploit gaps between HIPAA enforcement intensity in the United States and emerging data localization requirements in India.
United States
Epic and Cerner migration cycles sustain demand for certified implementation specialists that hospital IT departments cannot retain permanently. HIPAA Security Rule enforcement by the Office for Civil Rights intensifies audit frequency, pushing health systems toward vendors with dedicated compliance operations centers. Texas and Florida integrated delivery networks deploy robotic process automation for prior authorization, compressing headcount requirements in traditional medical billing contracts.
Germany
The 2022 Hospital Structures Act mandates efficiency targets that academic medical centers meet through facility management externalization. GDPR frameworks impose data governance requirements on IT outsourcing contracts processing patient information across borders. Munich and Berlin anchor vendor relationships with Sodexo and Aramark for integrated environmental services and food operations.
India
Private hospital chains in Lucknow, Jaipur, and Kochi lack scale for in-house biomedical engineering and environmental services. The Digital Personal Data Protection Act restricts cross-border patient data flows, fragmenting IT service delivery models that relied on offshore processing centers. Hyderabad and Bengaluru concentrate technology-enabled patient management platform development for domestic hospital networks.
United Kingdom
Subscription-based staffing models displace per-diem arrangements in nursing labor markets across England. NHS procurement frameworks favor managed services contracts with outcome-based pricing tied to quality benchmarks. London academic medical centers consolidate vendor relationships under unified performance frameworks for facility management and IT functions.
France
EU AI Act risk classification requirements for clinical decision support tools open specialized consulting services for hospital networks. ANSM oversight of hospital laboratory operations elevates compliance costs for in-house functions and expands the vendor addressable market. Paris and Lyon concentrate integrated facility management contracts where three vendor groups control the majority of large hospital relationships.
Hospital Outsourcing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue technology-enabled service layers that automate revenue cycle and patient management workflows. Three integrated facility management groups control the majority of large hospital contracts in Western Europe, limiting competitive tension for academic medical center procurement teams. The market organizes around three strategic archetypes: integrated facility management platforms, specialized IT implementation partners, and subscription-based staffing intermediaries. Dominant competitive moves include vendor consolidation to achieve HIPAA compliance scale and strategic partnerships with EHR vendors to anchor implementation labor pools.
Within the integrated facility management tier, Sodexo S.A. and Aramark Corporation exemplify archetypes that anchor large academic medical center relationships across France, the United Kingdom, and Germany. Compass Group PLC occupies a position representing technology-enabled patient dining and retail operations that dominate premium private hospital channels. Cerner Corporation sits within the IT implementation specialist archetype, though its positioning reflects broader patterns of certified technical labor scarcity affecting Epic migration cycles.
| Leading Market Players |
|---|
| Sodexo S.A. |
| Aramark Corporation |
| Compass Group PLC |
| ABM Industries Incorporated |
| Cerner Corporation |
| Allscripts Healthcare Solutions Inc. |
| LogistiCare Solutions LLC |
| The Allure Group |
| ModivCare Inc |
| Others |
Supply Flow & Price Mechanics
Captive labor pools in India and the Philippines anchor IT service delivery for North American hospital outsourcing contracts, creating pricing power for vendors with established HIPAA-compliant infrastructure while squeezing margins for regional competitors lacking scale. This integration pattern concentrates supply-side leverage among three facility management groups in Western Europe and fragments procurement options for academic medical centers seeking bundled services.
Pricing Analysis
Distributor margins on medical staffing contracts compress as subscription-based FTE blocks displace per-diem arrangements in California and New York health systems. Pricing stratifies across premium certified tiers, standard compliance-ready tiers, and economy non-clinical support tiers, with Epic-certified implementation specialists commanding substantial premiums over uncredentialed technical labor. Cost compression in standard-tier facility management contracts is intensifying because Germany's Hospital Structures Act mandates efficiency targets that force rate renegotiations. Public hospitals exhibit highest price sensitivity due to rigid procurement frameworks, while premium private hospitals prioritize outcome-based SLAs over unit cost.
Supply Chain Analysis
Workforce availability constraints in Hyderabad and Bengaluru limit the pipeline of credentialed EHR implementation specialists, forcing vendors to source from secondary hubs in Pune and Chennai. Supply concentrates in India for IT-enabled patient management platforms, the United States for cybersecurity operations centers, and Germany for integrated facility management engineering. Raw material dependencies include specialized healthcare IT hardware, food service commodities, and biomedical equipment parts. Single-source vulnerability around Epic-certified labor creates project bottlenecks that delay contract delivery. Distribution runs through direct vendor-hospital relationships for managed services contracts and platform intermediaries for staffing subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital outsourcing has matured into a late-cycle quality story where vendor consolidation favors operators with proven HIPAA compliance infrastructure and certified technical labor pools. Demand is shifting toward premium managed services contracts with outcome-based pricing as health systems prioritize operational resilience over lowest-unit-cost procurement.
For Market Incumbents: Cement market position by acquiring regional staffing agencies in India's tier-2 cities to secure first-mover advantage in Lucknow and Jaipur hospital expansions. Invest in backward integration into Epic certification training programs to address labor scarcity that threatens contract profitability. Channel control through exclusive EHR vendor partnerships represents the critical defensive lever against IT implementation specialists. For New Entrants and Emerging Players: Launch via platform-based subscription models that aggregate fragmented per-diem nursing relationships into guaranteed FTE blocks for California and New York health systems. Target laboratory services outsourcing in French academic medical centers where ANSM compliance requirements elevate barriers for unaccredited competitors. White-space opportunity concentrates in EU AI Act consulting services for clinical decision support tool validation. For Investors and Strategic Acquirers: Consolidation pressure builds where three integrated facility management groups control sixty percent of large hospital contracts in France and the United Kingdom, limiting competitive tension and compressing returns for sub-scale operators. Long-term viability favors vendors with technology-enabled service layers automating revenue cycle workflows. Acquisition target archetype: mid-cap IT implementation partners with established Epic labor pools and HIPAA-compliant infrastructure. Practitioners should monitor CMS reimbursement rule changes and state-level staffing ratio mandates for early signals of insourcing versus outsourcing economics shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Epic Certification Program Investment | Addresses credentialed specialist scarcity that constrains EHR migration project delivery. |
| HIPAA Compliance Infrastructure Expansion | Office for Civil Rights audit intensity makes dedicated security operations centers mandatory. |
| Managed Services Contract Conversion | Outcome-based pricing aligns vendor incentives with hospital cost reduction targets. |
| India Tier-2 City Market Entry | Lucknow and Jaipur private hospital chains lack scale for in-house biomedical engineering. |
| EU AI Act Consulting Service Launch | Risk classification requirements for clinical algorithms create specialized validation demand. |
Methodological Framework
Coverage spans the United States, Germany, India, the United Kingdom, and France, with primary inputs from each market informing demand-side validation. The research combines structured interviews with hospital procurement managers, GPO contracts managers, biomedical engineers, and facility operations directors with secondary validation from CMS Medicare data, hospital procurement databases, EHR vendor implementation disclosures, and SEC filings from publicly traded outsourcing providers. Bottom-up contract value analysis triangulates against top-down market sizing from regulatory filings and industry association reports.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price mix effects within each service type segment. The analytical framework models segmentation dimensions including service depth, contract governance structure, end-user institutional type, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to base-year contract value estimates, with cross-checks against EHR migration cycle timing and hospital efficiency mandate implementation schedules. Industry-specific forecast inputs include Epic certification pipeline constraints and GDPR data localization compliance costs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt CMS reimbursement rule changes or accelerated nursing wage inflation scenarios. Forecasts reflect assumptions about EHR vendor market concentration and HIPAA enforcement intensity that could shift with federal policy transitions. Practitioners should monitor state-level staffing ratio mandate expansions and EU AI Act implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
Europe Pharmaceutical Cold Chain Logistics Market
Healthcare Services
Acute Care Market
Healthcare Services
Long Term Care Market
Healthcare Services
Contract Manufacturing Services Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Michigan Urgent Care Center Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
Global Medical Affairs Outsourcing Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
Funeral Products and Services Market
Healthcare Services
US Retail Clinics Market