
 Medical Cyclotron Market | 2026-2036
Medical Cyclotron Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Cyclotron Market Intelligence
Multi-source procurement for superconducting magnets and RF cavities is recalibrating supply chain economics for cyclotron builders. GE Healthcare leverages captive sourcing for precision magnet assemblies to sustain delivery reliability. Siemens Healthineers anchors its European installed base through dedicated service networks. Ion Beam Applications SA differentiates by specializing in compact systems for hospital deployment.
A medical cyclotron is a particle accelerator that produces short-lived positron-emitting radioisotopes such as fluorine-18, typically operating at proton energies between 9 and 30 MeV for clinical applications. These machines generate radiotracers used in positron emission tomography to detect cancer, neurological disorders, and cardiovascular disease. Compact cyclotrons lead installation volumes among product types due to lower shielding requirements and reduced footprint for hospital integration. Radioisotope production dominates application demand because fluorine-18 supplies the backbone of FDG-PET imaging workflows worldwide. RF acceleration technology occupies the mainstream for commercial systems given its proven reliability and simpler maintenance protocols compared to emerging alternatives.
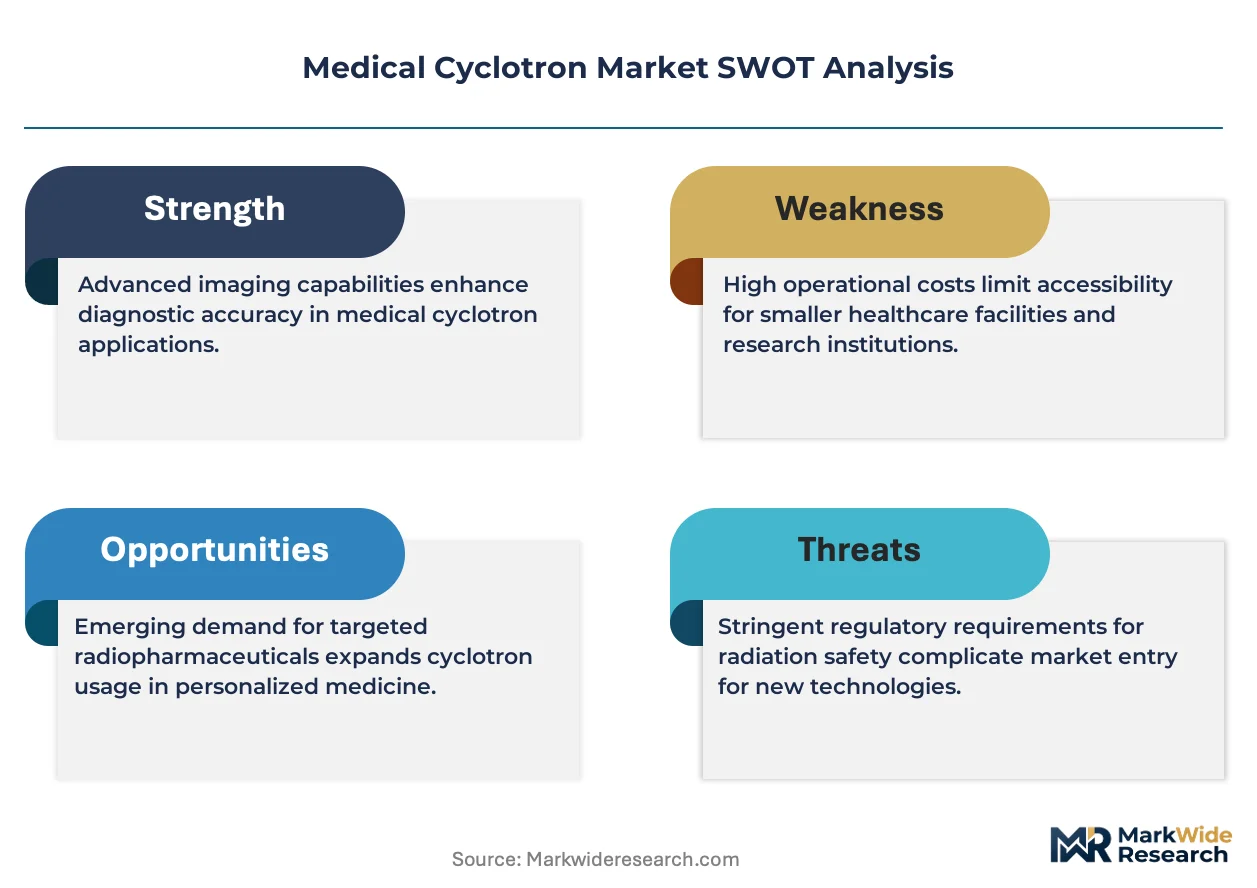
FDA oversight of radiopharmaceutical current good manufacturing practice compels cyclotron operators to validate production batches under 21 CFR Part 212, raising capital requirements for quality infrastructure. EMA's GMP Annex guidelines for radiopharmaceuticals similarly constrain market entry across European member states. The EU F-Gas Regulation limits coolant options for superconducting systems, pushing manufacturers toward closed-loop helium recovery architectures. Stakeholders must weigh regulatory compliance costs against the strategic value of controlling isotope supply chains as regional production mandates intensify.
Market Dynamics
Superconducting magnet supply concentration and tightening radiopharmaceutical purity mandates are forcing cyclotron manufacturers to reconfigure sourcing strategies and validation infrastructure simultaneously.
Growth Catalysts
- FDG-PET imaging expansion:Oncology departments in the United States and Germany are scaling fluorodeoxyglucose production capacity to meet diagnostic backlogs. Hospital-based cyclotron installations accelerate as centralized isotope supply proves unreliable.
- EMA GMP Annex enforcement:Radiopharmaceutical manufacturing standards across European member states now require automated batch validation systems. Compliance investments pull demand for integrated quality-control cyclotron platforms.
- Helium recovery architectures:Closed-loop cooling systems address EU F-Gas Regulation constraints on superconducting magnet coolants. Manufacturers embedding recovery modules gain regulatory clearance advantages.
Market Restraints
- Superconducting magnet supply concentration:Niobium-titanium wire fabrication concentrates among Japanese and German specialty suppliers. Cyclotron builders face 18-24 month lead times for precision magnet assemblies.
- FDA 21 CFR Part 212 compliance costs:Current good manufacturing practice validation for radiopharmaceutical production demands dedicated cleanroom infrastructure and environmental monitoring systems. Capital thresholds exclude smaller hospital operators.
- Technician specialization scarcity:Cyclotron maintenance requires cross-trained personnel combining vacuum system, RF engineering, and radiochemistry expertise. Training pipelines remain underdeveloped outside established nuclear medicine clusters.
Strategic Opportunities
- India nuclear medicine infrastructure:CDSCO regulatory pathways for medical cyclotron imports are stabilizing. Diagnostic networks in Mumbai, Delhi, and Bangalore present first-mover installation potential for compact systems.
- Therapeutic isotope diversification:Alpha-emitting radiometals for targeted radionuclide therapy require higher-energy proton beams. Cyclotron manufacturers extending energy ranges capture emerging theranostic workflows.
- Service network unbundling:Third-party technical service providers are fragmenting traditional OEM maintenance monopolies. Independent servicing contracts reduce total cost of ownership for mid-sized hospital buyers.
Industry Challenges
- RF cavity refurbishment cycles:Deuterium implantation degradation in accelerating electrodes demands precision re-machining capabilities. In-house RF engineering teams remain rare outside major academic medical centers.
- Legacy cyclotron integration:Hospital IT infrastructure and radiochemistry hot cells designed for 1990s-era systems require costly retrofitting to accommodate modern automated isotope extraction modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Cyclotron Market |
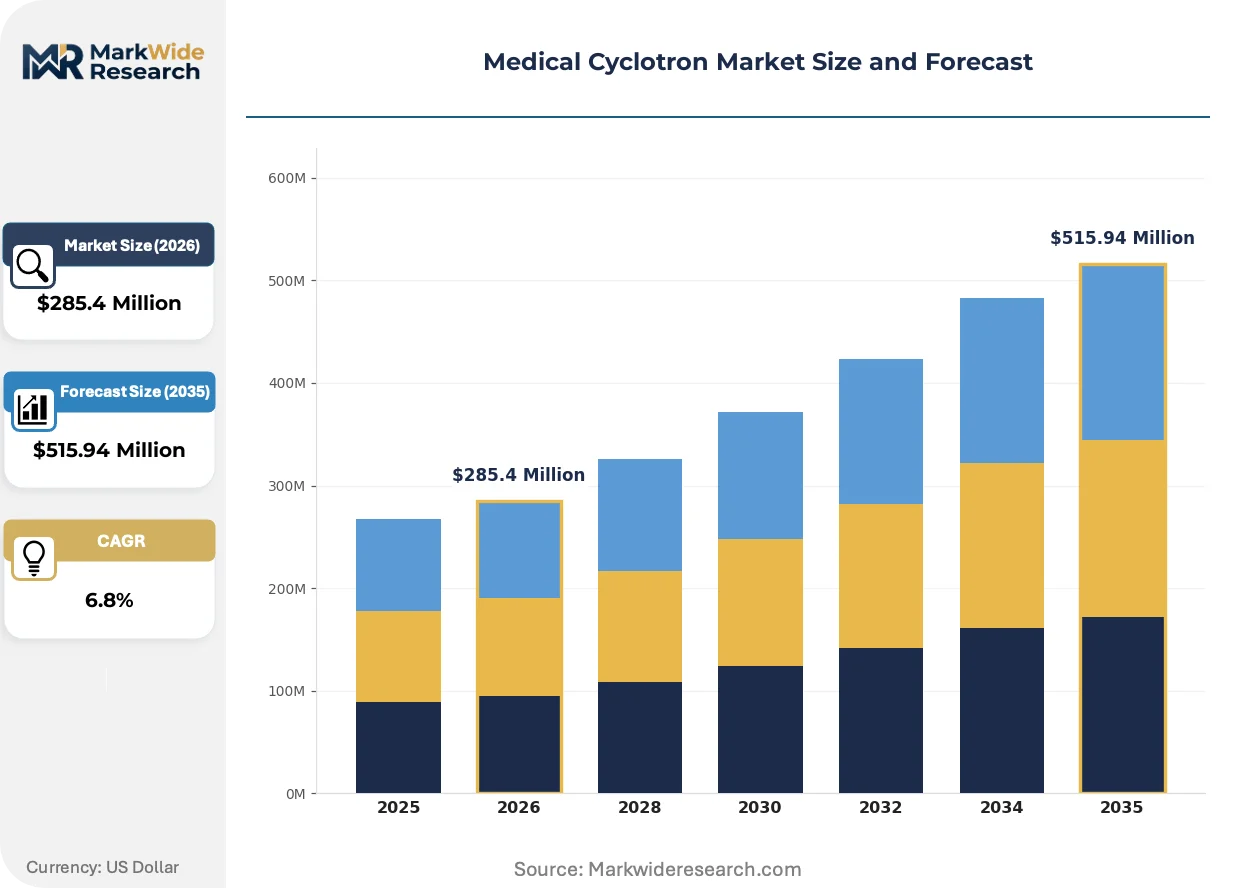
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Cyclotron, Heavy Ion Cyclotron, Variable Energy Cyclotron, Compact Cyclotron Technology: Magnetic Separation, Electromagnetic Acceleration, Particle Beam Technology, RF Acceleration Application: Radioisotope Production, Cancer Therapy, Diagnostic Imaging, Research Facilities End User: Hospitals, Research Institutions, Diagnostic Labs, Radiopharmaceutical Manufacturers |
| Companies Covered | Ion Beam Applications SA, GE Healthcare, Siemens Healthineers, Advanced Cyclotron Systems Inc., Sumitomo Heavy Industries Ltd., Best Medical International Inc., ALCENT, Ionetix Corp, Trasis SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Cyclotron Market Strategic Shifts & Innovations
Compact system architectures and regulatory automation are converging to reshape how hospitals deploy and operate particle accelerator infrastructure for clinical isotope production.
Superconducting cyclotron designs utilizing niobium-tin magnets are electrifying the hospital deployment landscape by slashing footprint and shielding mass by half compared to conventional copper-coil systems. Community hospitals and regional cancer centers previously excluded by space constraints are now entering procurement cycles. This technology compression is enabling distributed isotope production networks that reduce reliance on centralized commercial radiopharmacy supply.
EMA's F-Gas Regulation phase-down schedule is compelling manufacturers to eliminate sulfur hexafluoride insulation from high-voltage power feedthroughs. Industrial consequence includes accelerated R&D investment in solid-dielectric alternatives and vacuum-insulated bushing designs. European-installed systems face retrofit obligations by decade-end, creating aftermarket component demand distinct from new equipment sales.
Hospital procurement departments are consolidating cyclotron acquisitions through multi-year managed equipment service agreements rather than capital purchase models. OEMs and independent service organizations compete to bundle hardware, isotope production software, and predictive maintenance under per-dose pricing structures. This financing transformation is most visible in United States integrated delivery networks seeking to convert fixed capital burdens into operational expenditures aligned with PET scan volume growth.
Medical Cyclotron Market Segmentation
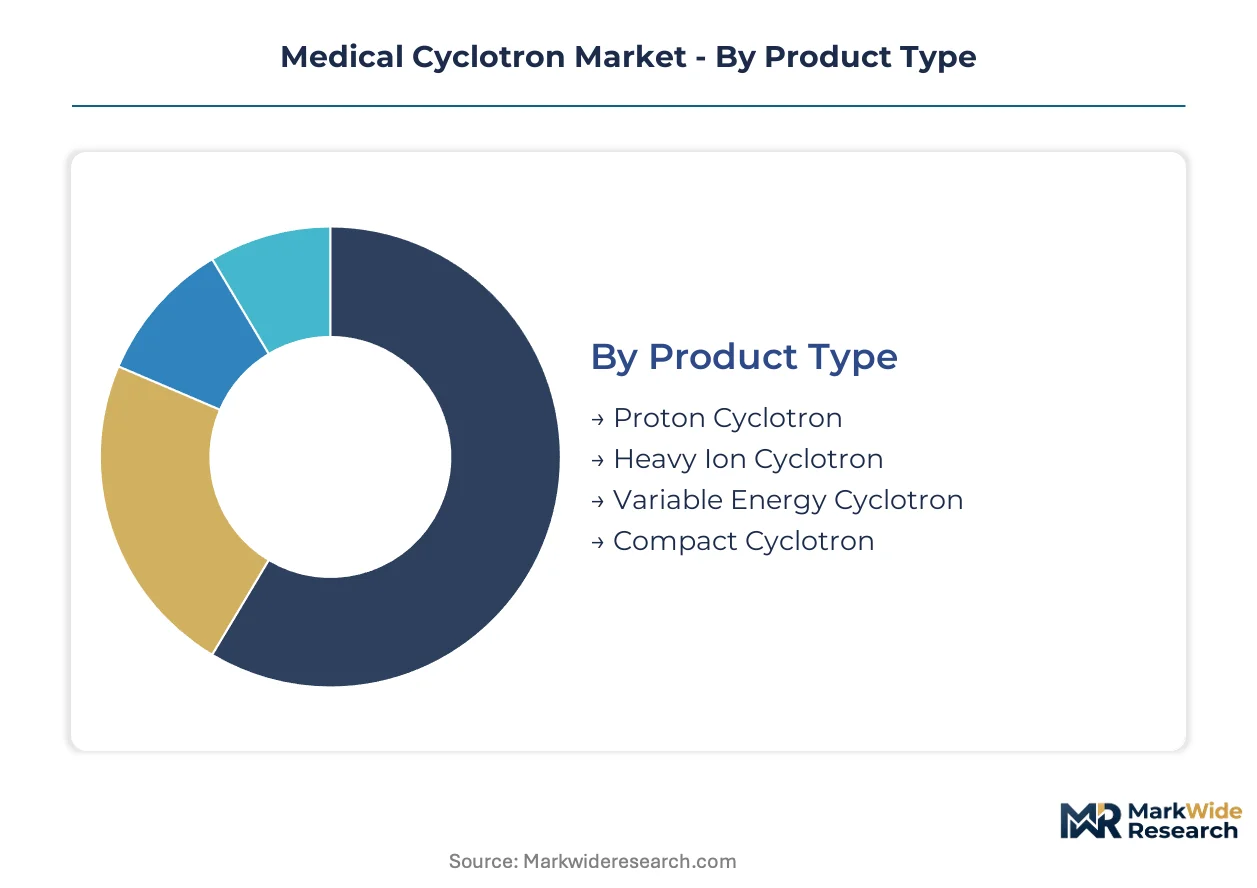
Cyclotron procurement decisions split sharply between high-volume hospital installations and premium research-grade systems. Understanding segment boundaries clarifies where capital concentrates and which technology specifications dominate purchasing criteria across clinical versus scientific end-uses.
Product Type:
Volume deployment favors shielding-minimal designs, while premium positioning attaches to beam energy flexibility and ion species range.
- Compact Cyclotron:Self-shielded architectures with integrated vault designs reduce facility construction costs by eliminating external radiation barriers. Hospital installations in the United States and Germany favor these systems for FDG production within existing oncology wings where space constraints block conventional accelerator footprints. Demand concentrates among community cancer centers seeking to bypass commercial radiopharmacy supply chains.
- Variable Energy Cyclotron:Tunable proton beam outputs between 9 MeV and 30 MeV enable simultaneous production of fluorine-18, carbon-11, and nitrogen-13 without hardware reconfiguration. Academic medical centers in Japan deploy these platforms for multi-tracer research programs alongside clinical workloads. Premium pricing reflects the beam optics complexity required for stable energy modulation.
- Proton Cyclotron:Fixed-energy systems dominate legacy installed bases with proven reliability for single-isotope production workflows.
- Heavy Ion Cyclotron:Specialized platforms for carbon and neon beam therapy occupy niche positions in proton therapy centers.
Mature deployment sits with Proton Cyclotron systems. Newer deployment is concentrated in Compact Cyclotron configurations.
Technology:
Reliability engineering and maintenance accessibility differentiate commercial winners from experimental alternatives.
- RF Acceleration:Resonant cavity designs operating at 100-200 MHz frequencies deliver stable proton beams with minimal phase slip. Siemens Healthineers and GE Healthcare anchor their product lines on this technology for hospital customers requiring predictable uptime. Service networks spanning vacuum engineering and RF tuning expertise concentrate in the United States, Germany, and Japan.
- Electromagnetic Acceleration:Classical magnet coil configurations with copper windings persist in budget-sensitive installations where superconducting infrastructure costs prove prohibitive. Research institutions in India and Southeast Asia favor these systems for training programs and isotope development work. Lower capital thresholds offset higher electrical consumption over operational life.
- Magnetic Separation:Beam purification subsystems for isotope extraction integrate with primary acceleration platforms rather than standalone cyclotron categories.
- Particle Beam Technology:Broad descriptor encompassing extraction optics and targetry systems rather than distinct acceleration methodology.
RF Acceleration commands the largest installed base. Electromagnetic Acceleration is expanding most quickly in emerging nuclear medicine markets.
Application:
Revenue concentration follows diagnostic procedure volumes rather than therapeutic utilization.
- Radioisotope Production:Fluorine-18 generation for FDG-PET imaging consumes over eighty percent of clinical cyclotron operating hours worldwide. Hospital radiochemistry suites integrate automated synthesis modules directly downstream of target extraction systems. FDA 21 CFR Part 212 compliance requirements drive capital allocation toward validated production platforms with batch documentation capabilities.
- Cancer Therapy:Proton and heavy ion beam delivery for radiation oncology requires higher energy ranges and sophisticated gantry systems beyond conventional medical cyclotron specifications. Dedicated proton therapy centers in the United States and Japan operate these platforms as capital-intensive standalone facilities rather than hospital-integrated deployments.
- Diagnostic Imaging:PET scanner operations consume cyclotron output without constituting direct cyclotron application segmentation.
- Research Facilities:Isotope development and radiochemistry method validation occupy academic and government laboratory installations.
Radioisotope Production represents mature commercial deployment. Cancer Therapy claims the steepest expansion trajectory as proton therapy insurance coverage broadens.
End User:
Procurement authority and financing structures diverge between integrated health systems and independent operators.
- Hospitals:Integrated delivery networks in the United States negotiate multi-system managed equipment service agreements converting capital expenditure to per-dose operational models. EMA GMP Annex compliance investments favor automated platforms with integrated quality control documentation.
- Radiopharmaceutical Manufacturers:Commercial suppliers including Cardinal Health and Curium operate centralized production facilities serving multiple hospital customers. Scale economics drive preference for high-capacity systems with redundant target stations.
- Research Institutions:University medical centers and national laboratories prioritize beam energy flexibility over production throughput for tracer development programs.
- Diagnostic Labs:Independent imaging centers without radiochemistry capabilities rely on external isotope supply rather than direct cyclotron ownership.
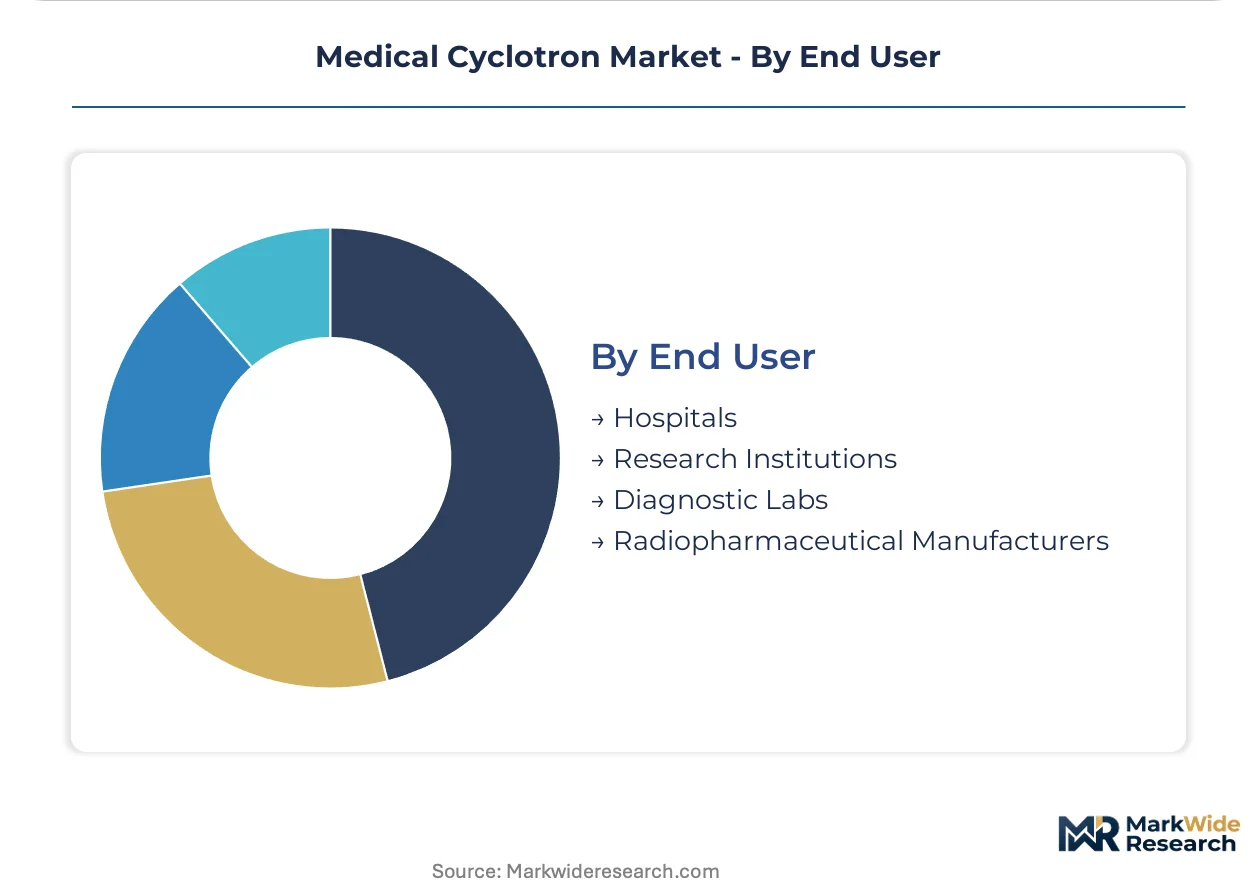
Radiopharmaceutical Manufacturers anchor mature large-scale deployment. Hospital-based installation is concentrating fastest as supply chain reliability concerns mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Niobium-titanium wire fabrication concentrates in Japanese and German specialty suppliers, anchoring cyclotron manufacturing geography to these precision magnet clusters while hospital demand radiates across nuclear medicine infrastructure in the United States, Germany, and Japan.
United States
Oncology departments are scaling FDG-PET production capacity to address diagnostic backlogs. FDA 21 CFR Part 212 compliance requirements compel operators to validate production batches under current good manufacturing practice standards. Hospital installations concentrate in the Northeast Corridor and California where integrated delivery networks negotiate managed equipment service agreements.
Germany
EMA GMP Annex enforcement mandates automated batch validation systems for radiopharmaceutical manufacturing. EU F-Gas Regulation constraints push manufacturers toward closed-loop helium recovery architectures. Bavaria and North Rhine-Westphalia host the densest clusters of hospital-based cyclotron deployments serving regional cancer networks.
Japan
Academic medical centers deploy variable energy platforms for multi-tracer research programs alongside clinical workloads. METI oversight stabilizes import pathways for superconducting magnet components. The Kanto region around Tokyo anchors the national installed base with concentrated proton therapy and PET imaging infrastructure.
India
CDSCO regulatory pathways for medical cyclotron imports are stabilizing as diagnostic networks expand. BIS standards alignment accelerates hospital procurement cycles. Mumbai, Delhi, and Bangalore present first-mover installation potential for compact self-shielded systems targeting community cancer centers.
Switzerland
Swissmedic oversight maintains stringent radiopharmaceutical purity standards that favor integrated quality-control platforms. Research institutions in the Basel and Zurich clusters prioritize beam energy flexibility for tracer development. The country's precision engineering ecosystem supports specialized magnet refurbishment capabilities serving European installed bases.
Medical Cyclotron Market Key Industry Players
Global majors compete with regional champions across service network density and magnet supply chain integration. The vendor base stratifies into three tiers: diversified healthcare conglomerates with captive magnet sourcing, dedicated cyclotron specialists with compact system expertise, and regional fabricators serving emerging nuclear medicine markets. Consolidation pressure concentrates among mid-scale operators lacking backward integration into superconducting wire supply. Dominant competitive moves include strategic partnerships with radiopharmaceutical distributors and technology licensing agreements for helium recovery architectures.
Within the diversified healthcare conglomerate tier, GE Healthcare and Siemens Healthineers exemplify global-scale positioning anchored by integrated service networks spanning vacuum engineering and RF tuning expertise. Ion Beam Applications SA occupies a specialist position emphasizing compact system architectures for hospital deployment. These three entities represent the dominant archetypes: captive-sourced conglomerates, dedicated acceleration technology specialists, and regional champions leveraging proximity to emerging diagnostic networks.
| Leading Market Players |
|---|
| Ion Beam Applications SA |
| GE Healthcare |
| Siemens Healthineers |
| Advanced Cyclotron Systems Inc. |
| Sumitomo Heavy Industries Ltd. |
| Best Medical International Inc. |
| ALCENT |
| Ionetix Corp |
| Trasis SA |
| Others |
Cost & Logistics Intelligence
Hospital procurement committees demanding per-dose managed equipment service agreements are compressing capital expenditure thresholds and forcing OEMs to unbundle hardware from long-term maintenance contracts, reshaping how cyclotron builders recover margin across extended operational lifecycles.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium cyclotron offerings from stripped-down capital-sale configurations. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service depth and FDA 21 CFR Part 212 validation documentation completeness. Cost compression in economy tiers is intensifying because radiopharmaceutical manufacturers negotiate volume-based hardware discounts. Community cancer centers exhibit highest price sensitivity; academic medical centers with research grants demonstrate lowest.
Supply Chain Analysis
CE marking and FDA premarket notification pathways gate access to niobium-titanium wire feedstock from Japanese and German specialty metallurgists. Superconducting magnet fabrication draws from precision wire drawing, cryogenic vessel manufacturing, and RF cavity machining capabilities concentrated in Japan, Germany, and Switzerland. Single-source vulnerability persists for superconducting wire given limited qualified suppliers. Distribution runs through OEM direct sales teams serving hospital integrated delivery networks and regional service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 212 current good manufacturing practice mandates erect substantial compliance infrastructure barriers that protect incumbent cyclotron operators with validated quality systems while excluding undercapitalized challengers.
For Market Incumbents: Deepen captive sourcing relationships for niobium-titanium wire to secure magnet assembly delivery reliability against 18-24 month supplier lead times. Expand dedicated service network density in India's emerging diagnostic clusters before regional champions establish maintenance footholds.
For New Entrants and Emerging Players: The price-point gap between premium variable-energy systems and economy compact cyclotrons creates entry space for mid-tier hospital buyers in Southeast Asia seeking self-shielded FDG production without research-grade beam flexibility. Target India's CDSCO-stabilized import pathways for first-mover installation contracts.
For Investors and Strategic Acquirers: The window for entry favors independent service organizations with RF engineering and vacuum system cross-training capabilities as hospital buyers unbundle maintenance from OEM monopolies. Monitor EMA F-Gas Regulation retrofit obligation timelines as aftermarket component demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery Architecture Licensing | EU F-Gas Regulation compliance accelerates closed-loop cooling adoption across European installed bases. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate procurement through per-dose managed service agreements. |
| CE Marking Pathway Investment | EMA GMP Annex enforcement mandates automated batch validation systems for radiopharmaceutical manufacturing. |
| Service Network Expansion | Third-party technical providers fragment traditional OEM maintenance monopolies in mid-sized hospital segments. |
| Theranostic Workflow Development | Alpha-emitting radiometal production requires cyclotron energy range extension beyond conventional FDG specifications. |
Research Approach
Independent corroboration across cyclotron OEM product managers, hospital biomedical engineering directors, and radiopharmaceutical manufacturing executives underwrites the qualitative findings. Primary interviews with GPO contracts managers, nuclear medicine department chairs, and superconducting magnet procurement leads combined with secondary validation from FDA 510(k) filings, EMA GMP inspection reports, and hospital procurement databases. Bottom-up installation tracking and top-down healthcare capital expenditure analysis triangulate market sizing.
Rate-of-change decomposition separates volume growth from average selling price evolution across the analysis window. Segmentation modeling incorporates product type, proton energy range, RF acceleration technology, application workflow, and end-user procurement authority. CAGRs derive from logistic diffusion curves fitted to hospital PET imaging expansion rates and regulatory compliance investment cycles. Forecast inputs include superconducting magnet delivery lead times and technician training pipeline development.
Inputs from OEM order backlogs and hospital capital budget disclosures were available through the study window; gaps in independent service organization revenue capture introduce uncertainty bands around aftermarket sizing. Forecasts reflect documented assumptions regarding EMA enforcement consistency and FDA inspection prioritization. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down acceleration or niobium-titanium supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pessary Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Aerosol Drug Delivery Devices Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
United Kingdom Minimally Invasive Surgery Devices Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Surgical Display Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Global Medical Suction Devices Market