
 Digital Sphygmomanometer Market | 2026-2036
Digital Sphygmomanometer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Sphygmomanometer Market Analysis
Retail pharmacy and direct-to-consumer channels are rewriting how digital sphygmomanometers reach end users, with e-commerce platforms now capturing significant volume previously flowing through medical distributors. OMRON Corporation leverages its decades-long brand strength in cardiovascular monitoring to sustain premium positioning across multiple continents. A&D Company Limited anchors its competitive stance through precision sensor manufacturing and hospital-grade calibration standards. Microlife Corporation specializes in wrist-form factor innovation, competing aggressively for space-constrained home users.
A digital sphygmomanometer is an automated blood pressure measurement device employing oscillometric detection—sensing arterial wall vibrations via a pressure transducer and microprocessor—to compute systolic, diastolic, and pulse readings without manual cuff inflation or stethoscope auscultation. These instruments serve primary commercial purposes in hypertension management, clinical triage, and longitudinal cardiovascular risk tracking across ambulatory and domiciliary settings. Automatic arm-cuff devices dominate installed base volumes, while Bluetooth-connected models represent the fastest-expanding segment as telehealth reimbursement codes mature. Home healthcare applications command the deepest margin pools due to recurring consumable sales and subscription-based data analytics services.
The FDA regulates digital sphygmomanometers as Class II medical devices under 510(k) premarket notification requirements, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance through notified bodies. Japan's PMDA enforces JIS T 1115 accuracy standards that exceed ISO 81060-2 tolerances, creating a technical barrier for non-compliant imports. Stakeholders must monitor evolving software-as-a-medical-device classifications that could reclassify smartphone-integrated blood pressure applications and trigger additional validation burdens.
Market Dynamics
Bluetooth-enabled connectivity is collapsing the boundary between clinical-grade accuracy and consumer accessibility, forcing manufacturers to reengineer hardware architectures around smartphone-integrated data pipelines rather than standalone device logic.
Growth Catalysts
- Telehealth reimbursement codes:CMS in the United States expanded remote patient monitoring billing categories, directly monetizing connected blood pressure data streams for physician practices.
- Japan's PMDA JIS T 1115 standards:Stringent accuracy tolerances exceeding ISO 81060-2 create technical moats that reward precision engineering investments and filter low-quality imports.
- Home healthcare migration:Post-acute care discharge protocols now mandate self-monitoring capabilities, embedding digital sphygmomanometers into chronic disease management workflows outside hospital walls.
Market Restraints
- Pressure sensor supply concentration:MEMS transducer fabrication concentrates among Taiwanese and German foundries, exposing manufacturers to single-source vulnerability during capacity crunches.
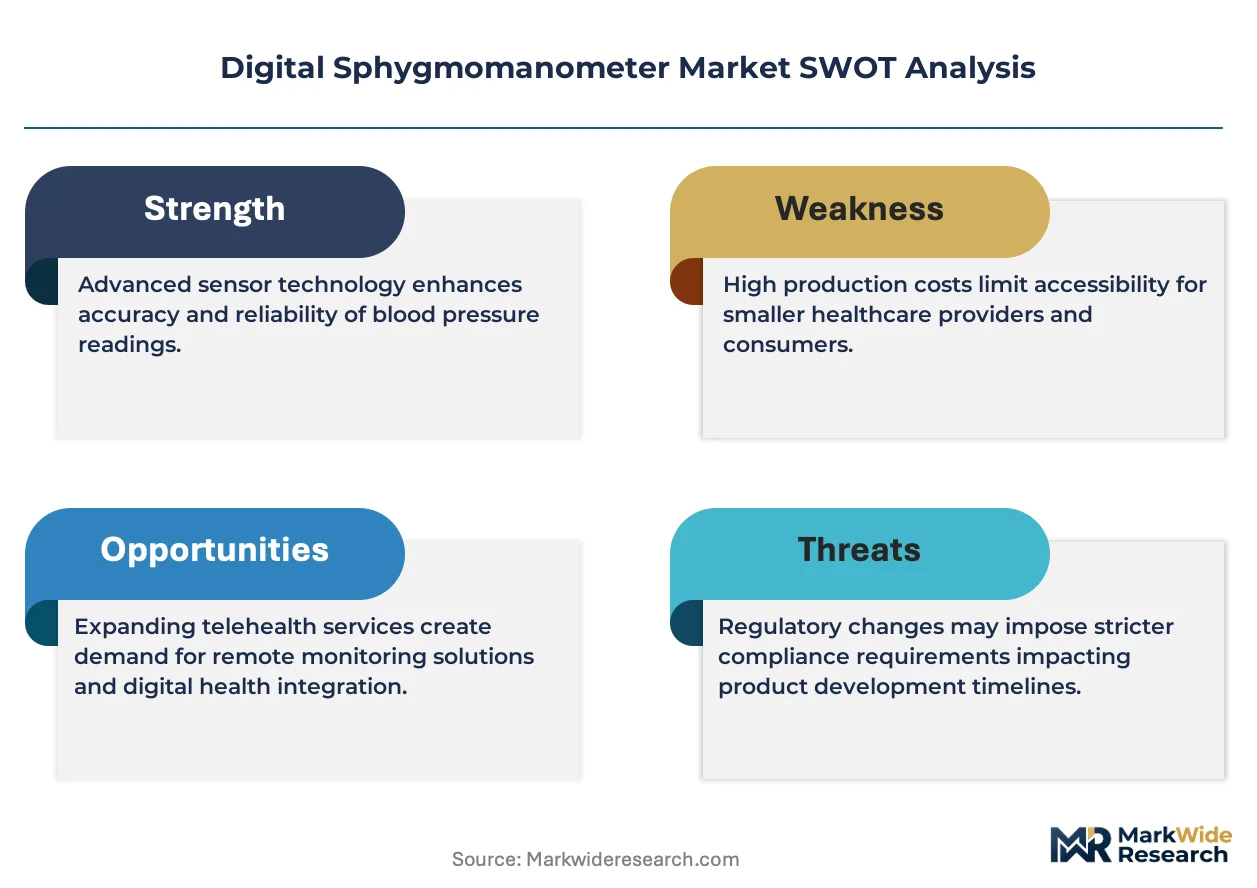
- Software-as-a-medical-device reclassification risk:FDA draft guidance on algorithm-driven blood pressure applications threatens additional clinical validation burdens for smartphone-integrated offerings.
- Wearable photoplethysmography substitution:Smartwatch-based optical pulse monitoring satisfies casual wellness tracking demand, compressing addressable market for dedicated cuff devices among fitness-oriented consumers.
Strategic Opportunities
- Subscription-based data analytics services:Recurring revenue models bundling longitudinal cardiovascular risk scoring with device hardware are penetrating Medicare Advantage plans seeking HEDIS measure improvements.
- Retail pharmacy clinic integration:CVS MinuteClinic and Walgreens Health models are embedding validated home monitoring protocols into hypertension management programs, creating institutional procurement channels.
- EU Medical Device Regulation Article 10 post-market surveillance:Mandated clinical follow-up obligations favor manufacturers with established real-world evidence infrastructure, disadvantaging smaller competitors.
Industry Challenges
- Embedded firmware cybersecurity certification:IEC 62304 medical device software lifecycle compliance demands specialized engineering talent scarce outside established cardiovascular device hubs.
- Legacy electronic health record integration:HL7 FHIR interoperability implementation requires substantial professional services investment to achieve seamless data flow into Epic and Cerner environments.
- Calibration drift management:Oscillometric algorithm validation across diverse patient populations necessitates continuous clinical study expenditure to maintain accuracy claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Sphygmomanometer Market |
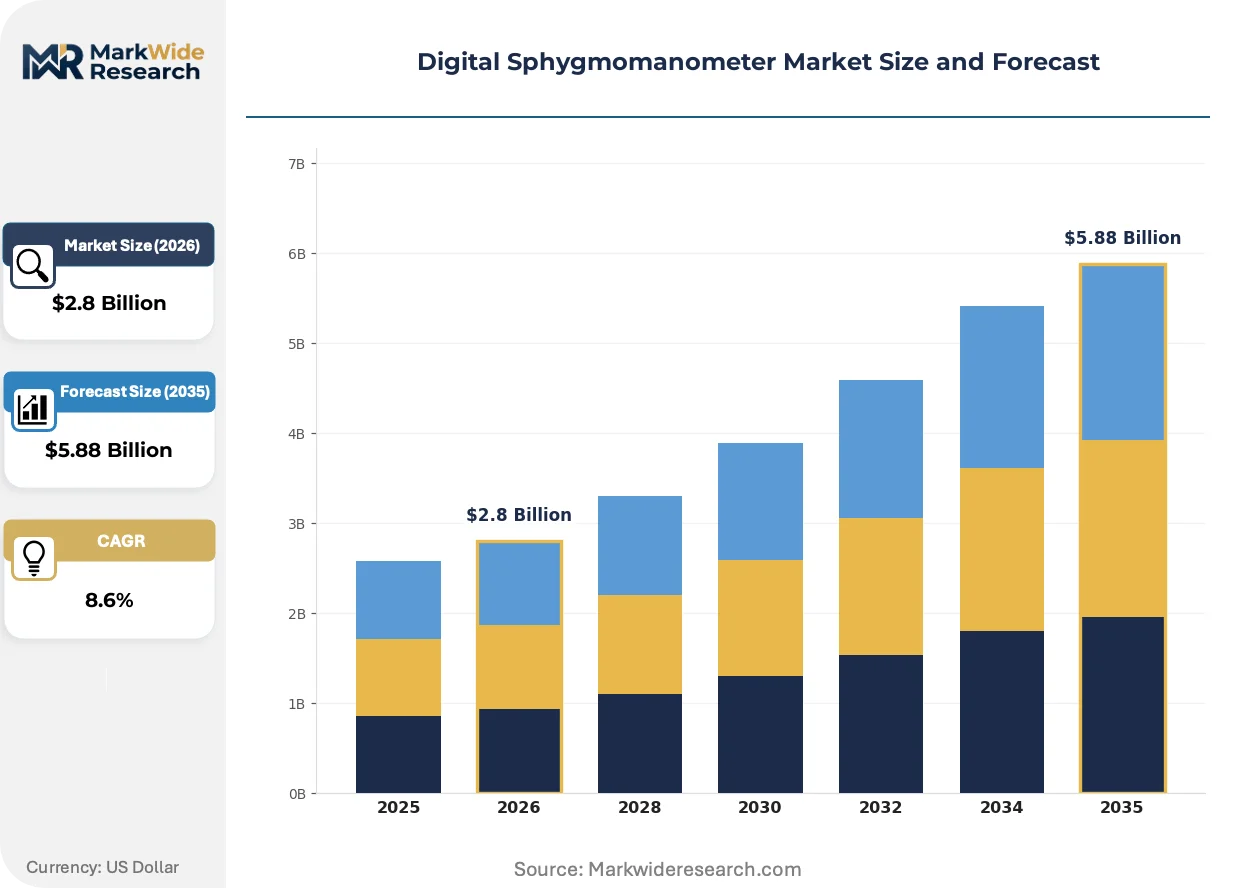
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Wrist Application: Home Healthcare, Hospitals, Clinics, Remote Monitoring Technology: Oscillometric, Auscultatory, Digital, Bluetooth End User: Patients, Healthcare Providers, Caregivers, Telehealth Services |
| Companies Covered | OMRON Corporation, A&D Company Limited, Microlife Corporation, Rossmax International Ltd, American Diagnostic Corporation, Panasonic Holdings Corporation, Contec Medical Systems Co. Ltd, Beurer GmbH, Welch Allyn Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Sphygmomanometer Market Emerging Trajectories
Device architecture is converging around sensor fusion and edge computing, compressing the traditional separation between measurement hardware and diagnostic interpretation into unified portable systems.
Photoplethysmography-oscillometry hybrid sensing is collapsing the distinction between cuff-based and cuffless blood pressure estimation, enabling continuous monitoring form factors. Cardiology outpatient departments are piloting wrist-worn validation studies against ambulatory blood pressure monitoring gold standards. This convergence is compressing reimbursement distinctions between diagnostic and wellness device categories.
EU Medical Device Regulation clinical evidence requirements are tightening post-market surveillance obligations for Class IIa cardiovascular devices. Notified body capacity constraints are extending certification timelines by eight to fourteen months. Manufacturers with pre-MDR legacy device portfolios are accelerating technical documentation remediation to avoid supply interruptions.
Direct-to-consumer channel expansion is fragmenting traditional medical distributor relationships. Amazon and specialized telehealth platforms are capturing volume previously flowing through hospital supply chains. Germany and Japan exhibit strongest resistance to this shift due to entrenched statutory insurance reimbursement pathways favoring pharmacy dispensing.
Digital Sphygmomanometer Market Segmentation
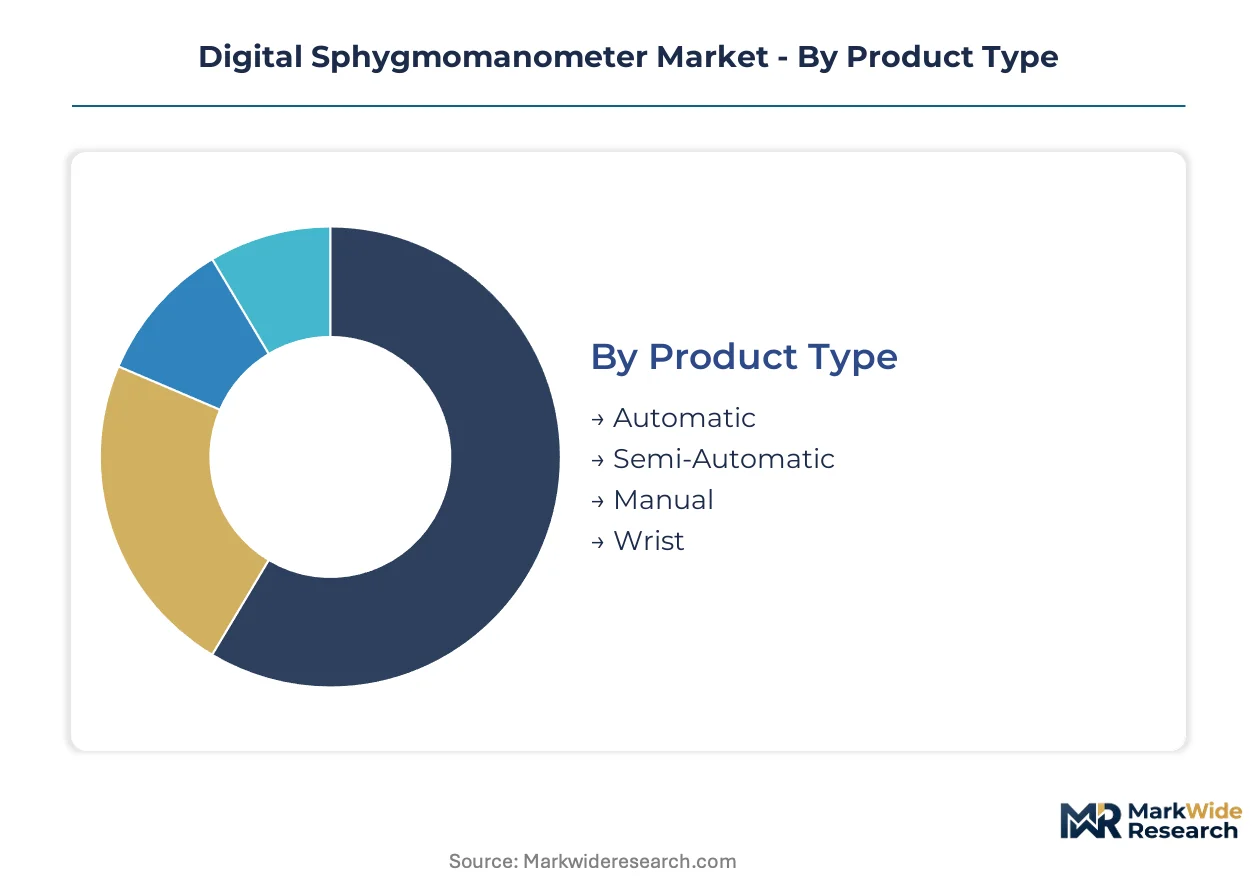
Digital sphygmomanometer segmentation reveals divergent hardware replacement cycles across use environments, with clinical-grade devices enduring 5-7 years while consumer units turn over every 2-3 years. Understanding these temporal patterns helps manufacturers align inventory planning with channel-specific demand rhythms and warranty provisioning.
Product Type:
Automatic arm-cuff devices command the longest replacement cycles in clinical settings, while wrist-form factors and semi-automatic variants experience accelerated turnover in consumer channels driven by style obsolescence and battery degradation.
- Automatic:Oscillometric detection with motorized cuff inflation eliminates user technique variability, satisfying ISO 81060-2 accuracy requirements for hypertension diagnosis. Hospital procurement in Germany and Japan concentrates demand here, with reimbursement codes favoring validated clinical-grade hardware over consumer alternatives.
- Semi-Automatic:Requires manual bulb inflation while automating detection and display, occupying a narrowing price-performance niche between full automation and manual alternatives. Demand persists in cost-constrained clinic environments across India and Southeast Asia where technician labor remains inexpensive.
- Manual:Aneroid gauge with manual inflation persists in low-resource settings and veterinary applications where electronic power reliability is uncertain.
- Wrist:Compact oscillometric units with radial artery positioning target space-constrained home users and travel-oriented consumers, though positioning sensitivity limits clinical acceptance.
Automatic devices dominate installed base. Wrist is where expansion concentrates.
Application:
Cost tier stratification separates premium clinical systems from economy home units, with remote monitoring commanding intermediate pricing supported by recurring data service fees.
- Home Healthcare:Bluetooth-enabled devices with smartphone integration enable longitudinal tracking outside clinical supervision, attracting Medicare Advantage plan subsidies seeking HEDIS measure improvements. Japan's aging population and statutory long-term care insurance create concentrated demand for validated home monitoring protocols.
- Hospitals:Multi-parameter integration with electronic health record systems demands HL7 FHIR interoperability and IEC 60601-1-2 electromagnetic compatibility certification, filtering out consumer-grade entrants.
- Clinics:Rapid throughput requirements favor automatic arm-cuff devices with single-button operation and disposable cuff compatibility for infection control.
- Remote Monitoring:CMS reimbursement expansion in the United States directly monetizes connected blood pressure data streams, embedding hardware into chronic disease management workflows.
Hospital procurement anchors premium pricing. Home healthcare is climbing the fastest.
Technology:
Volume concentration favors mature oscillometric platforms, while Bluetooth integration represents the steepest expansion trajectory as telehealth infrastructure matures.
- Oscillometric:Pressure transducer detection of arterial wall vibrations enables cuff-based measurement without stethoscope auscultation, forming the technical foundation of virtually all automated devices. FDA 510(k) predicate device pathways and ISO 81060-2 validation requirements create regulatory moats around established algorithm portfolios.
- Auscultatory:Electronic microphone replacement of human hearing preserves Korotkoff sound methodology for validation studies and regulatory reference measurements.
- Digital:Microprocessor-based computation and LCD display supplanted analog gauges across all price tiers.
- Bluetooth:Low-energy wireless connectivity collapsing the boundary between measurement hardware and smartphone-integrated data pipelines, forcing architectural reengineering around cloud-connected ecosystems rather than standalone device logic.
Oscillometric platforms dominate installed base. Bluetooth integration is gaining share fastest.
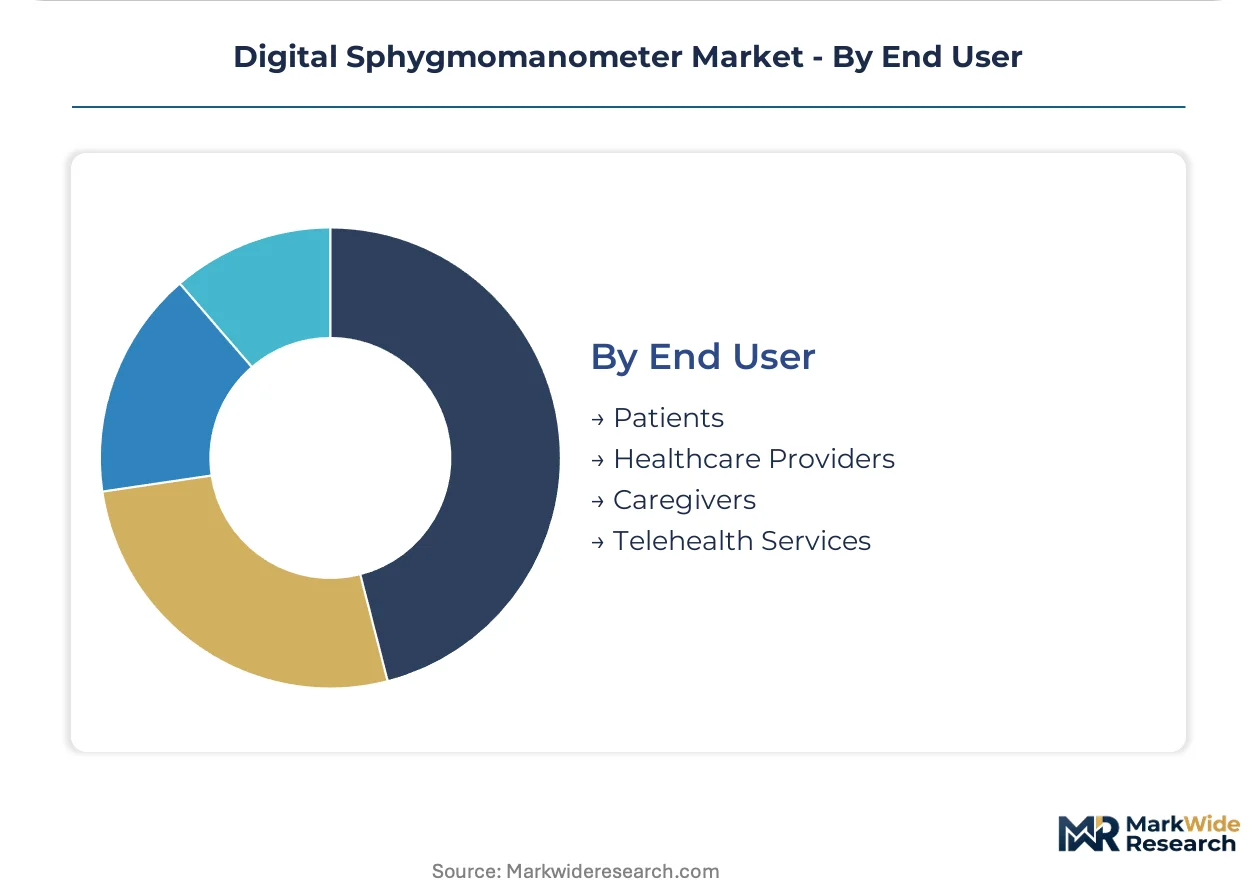
End User:
Customer type determines purchasing authority and decision criteria, with healthcare providers prioritizing accuracy validation while patients respond to convenience and design aesthetics.
- Patients:Self-monitoring consumers in the United States and Germany drive direct-to-channel volume through Amazon and pharmacy retail, with subscription bundling emerging in Medicare Advantage segments.
- Healthcare Providers:Physician practices and hospital systems demand FDA-cleared or CE-marked devices with documented accuracy against mercury sphygmomanometer references, insulating this segment from consumer-grade price competition.
- Caregivers:Family members and home health aides require simplified single-button operation and large-format displays for elderly patient assistance.
- Telehealth Services:Platform operators like Teladoc and Amwell procure validated devices for patient kit distribution, creating institutional procurement channels distinct from retail pharmacy flows.
Healthcare provider procurement anchors premium tier. Patient direct purchasing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japan and Germany where regulatory validation creates technical moats, while cost-sensitive procurement in India and Southeast Asia compresses margins for unconnected devices. This asymmetry shapes manufacturer portfolio strategies across geographies.
United States
Medicare Advantage plan subsidies for remote patient monitoring drive demand for Bluetooth-enabled devices with longitudinal data analytics. FDA 510(k) premarket notification requirements filter out low-accuracy imports. The Minneapolis medical device cluster hosts precision sensor calibration facilities serving hospital procurement networks.
Germany
Statutory health insurance reimbursement pathways favor pharmacy-dispensed clinical-grade hardware over direct-to-consumer alternatives. EU Medical Device Regulation notified body oversight extends certification timelines and rewards established technical documentation portfolios. The Baden-Württemberg precision engineering corridor concentrates oscillometric algorithm development and MEMS transducer integration capabilities.
Japan
Aging demographics and long-term care insurance create concentrated demand for validated home monitoring protocols. PMDA enforcement of JIS T 1115 accuracy standards exceeding ISO 81060-2 tolerances filters non-compliant imports. Tokyo-based cardiovascular device manufacturers anchor regional supply chains for pressure sensor assemblies.
China
Domestic production scale advantages serve cost-conscious clinic procurement across tier-two and tier-three cities. NMPA medical device registration requirements are tightening clinical evidence standards for Class II cardiovascular instruments. Shenzhen's electronics manufacturing ecosystem dominates Bluetooth module integration and cloud-connected device assembly.
India
Technician labor availability sustains demand for semi-automatic devices in cost-constrained primary health centers. CDSCO medical device rules mandate registration for imported electronic sphygmomanometers, creating compliance barriers for unestablished brands. The Maharashtra pharmaceutical and medical device corridor hosts regional distribution hubs serving Southeast Asian export markets.
Digital Sphygmomanometer Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying pressure transducers and Bluetooth modules. Market structure tilts toward consolidation among validated clinical-grade manufacturers, with fragmentation persisting in consumer-direct channels. Three archetypes dominate: precision sensor specialists, connectivity platform builders, and retail brand licensors. Competitive moves concentrate on M&A for algorithm portfolios and strategic partnerships for EHR interoperability.
Among Japan-based precision instrument manufacturers, OMRON Corporation and A&D Company Limited exemplify the sensor-integrated platform archetype with decades-long cardiovascular monitoring specialization. Microlife Corporation anchors the wrist-form factor innovation tier, competing for space-constrained home users through compact industrial design.
| Leading Market Players |
|---|
| OMRON Corporation |
| A&D Company Limited |
| Microlife Corporation |
| Rossmax International Ltd |
| American Diagnostic Corporation |
| Panasonic Holdings Corporation |
| Contec Medical Systems Co. Ltd |
| Beurer GmbH |
| Welch Allyn Inc. |
| Others |
Supply Flow & Price Mechanics
Shenzhen's electronics manufacturing ecosystem anchors Bluetooth module integration capacity, with foundry utilization rates directly transmitting into component pricing leverage for downstream device assemblers. MEMS pressure transducer fabrication concentrates among Taiwanese and German specialty houses, creating asymmetric bargaining power that compresses margins for manufacturers lacking multi-source qualification.
Pricing Analysis
Configured-to-order pricing for hospital-integrated systems with HL7 FHIR interoperability commands substantial premiums over standard consumer-direct units. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and ISO 81060-2 validation depth. Cost compression in the economy segment intensifies as smartwatch photoplethysmography substitutes erode dedicated device willingness-to-pay. Medicare Advantage plan procurement exhibits lowest price sensitivity due to HEDIS measure bundling, while Southeast Asian clinic buyers prioritize per-unit minimization.
Supply Chain Analysis
Upstream feedstock for oscillometric pressure sensors draws from Taiwan, Germany, and Japan specialty foundries, with MEMS wafer fabrication and piezoresistive element processing forming critical dependencies. Bluetooth Low Energy chipsets, lithium-polymer cells, and medical-grade silicone cuff materials constitute secondary input concentrations. Single-source vulnerability around Taiwanese MEMS capacity exposes manufacturers to allocation risk during semiconductor cycle upturns. Distribution runs through medical device distributors in Germany and Japan, while Amazon and telehealth platforms capture direct-to-patient volume in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable photoplethysmography substitution threatens dedicated sphygmomanometer relevance among fitness-oriented consumers, compelling incumbents to fortify clinical validation moats and telehealth reimbursement integration.
For Market Incumbents: Build algorithm portfolio moats through continuous oscillometric validation studies across diverse patient phenotypes to defend against software-as-a-medical-device reclassification. Secure backward integration into MEMS pressure sensor calibration capabilities or captive supply agreements with Taiwanese foundries to mitigate single-source exposure. Deepen Epic and Cerner EHR interoperability investment to lock in hospital procurement preference against consumer-grade entrants. For New Entrants and Emerging Players: India's cost-constrained primary health centers present underpenetrated demand for semi-automatic devices where technician labor substitutability sustains viable pricing. Southeast Asian clinic procurement channels offer white-space expansion with lower regulatory barriers than Japanese PMDA or German EU MDR pathways. Pursue telehealth platform partnership models bypassing traditional medical distributor relationships to accelerate patient kit penetration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision sensor specialists with established ISO 81060-2 algorithm portfolios and real-world evidence infrastructure compliant with EU MDR Article 10 obligations. Long-term viability hinges on subscription-based data analytics bundling penetration into Medicare Advantage and statutory insurance reimbursement schemes. Monitor FDA draft guidance finalization on smartphone-integrated blood pressure applications as inflection signal for validation burden redistribution across the competitive set.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance under FDA Class II medical device requirements unlocks hospital procurement and Medicare reimbursement eligibility. |
| CE Marking Pathway | EU MDR notified body certification enables German statutory insurance pharmacy dispensing and Baden-Württemberg cluster access. |
| Hospital System Partnership | Epic EHR integration agreements embed devices into hypertension management workflows and GPO contract portfolios. |
| Software Companion Development | Smartphone-integrated data pipelines satisfy CMS remote patient monitoring billing categories and Medicare Advantage HEDIS requirements. |
| Reimbursement Strategy | Telehealth platform kit distribution and pharmacy clinic integration secure institutional procurement channels beyond retail price competition. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and telehealth platform procurement leads. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare remote patient monitoring billing data, EU MDR notified body certification records, and Japanese PMDA JIS T 1115 compliance filings. Bottom-up device shipment modeling and top-down healthcare expenditure allocation were triangulated against hospital procurement database benchmarks.
Calibration against historical ISO 81060-2 validation study outcomes and oscillometric algorithm accuracy literature anchored projection parameters across the analysis window. Segmentation dimensions modeled include product type tier, application environment, connectivity technology, and end-user purchasing authority. CAGRs were derived from logistic diffusion curves fitted to telehealth reimbursement code expansion patterns and aging demographic penetration rates. Bluetooth module cost trajectories and MEMS foundry capacity utilization formed industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by consumer electronics giants or wearable platform operators would shift outcomes beyond modeled bounds. Cross-checking against CMS Medicare Advantage plan remote monitoring adoption benchmarks and Japanese long-term care insurance device dispensing data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endoscope Flushing Pumps Market
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Contact Thermometer Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
Mexico Artificial Organs and Bionic Implants Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Cardiopulmonary Bypass System Market