
 Global Sphygmomanometer Market | 2026-2036
Global Sphygmomanometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sphygmomanometer Market Foresight
Home care is realigning the end-use vertical mix as patients shift from clinic-based monitoring to daily self-measurement routines. Omron Healthcare leverages its brand strength across retail pharmacy channels in multiple continents. Microlife Corporation specializes in oscillometric algorithms for ambulatory blood pressure tracking. A&D Company anchors Japanese domestic demand while extending manufacturing scale into Southeast Asian facilities.
A sphygmomanometer is a medical instrument that measures arterial blood pressure through inflatable cuff compression and controlled deflation, with digital variants employing oscillometric sensors detecting vibration amplitudes in the brachial artery. The device serves clinical screening, chronic hypertension management, and cardiovascular risk stratification across inpatient and outpatient settings. Digital product types lead volume shipments due to ease of use, while ambulatory segments capture premium pricing for continuous monitoring protocols. Oscillometric technology dominates home care applications, whereas auscultatory methods retain diagnostic laboratory preference for validation studies. Telemedicine application demand is accelerating as remote patient monitoring platforms integrate connected sphygmomanometer peripherals.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development cycles and market access timelines for manufacturers. ISO 81060-2 validation protocols for automated measurement accuracy create compliance barriers that favor established players with dedicated clinical trial capabilities. WHO prequalification standards influence procurement decisions in emerging health systems across Africa and South Asia. Stakeholders must monitor evolving telehealth reimbursement codes and data interoperability mandates that will determine which connected device platforms achieve sustainable adoption.
Market Dynamics
Telemedicine integration is compressing the traditional boundary between clinical-grade and consumer-grade blood pressure monitoring, forcing manufacturers to recalibrate accuracy validation protocols for dual-use environments.
Growth Catalysts
- EU MDR technical documentation obligations:The tightened accuracy standards for automated devices are filtering substandard competitors from European distribution channels, consolidating procurement toward validated manufacturers.
- Home care self-monitoring routines:Patients with chronic hypertension are adopting daily measurement protocols that sustain replacement demand for cuff consumables and connectivity subscriptions.
- Japan's aging demographic concentration:The country's super-aged population structure generates sustained volume demand for ambulatory monitoring systems in both institutional and residential settings.
Market Restraints
- ISO 81060-2 clinical trial costs:The validation protocol requires substantial investment in controlled accuracy studies, creating capital barriers for new market entrants without established clinical research infrastructure.
- Semiconductor sensor supply concentration:Oscillometric pressure transducers depend on specialized MEMS fabrication capacity concentrated in East Asian foundry networks, exposing manufacturers to geographic supply risk.
- Wrist-worn optical photoplethysmography substitutes:Smartwatch-based blood pressure estimation is capturing preventive screening occasions that previously required dedicated sphygmomanometer purchase.
Strategic Opportunities
- India's tier-two urban expansion:Diagnostic center networks in cities such as Pune and Jaipur remain underpenetrated by automated device distribution, creating whitespace for pharmacy retail partnerships.
- Remote patient monitoring reimbursement codes:CMS and analogous national payers are expanding coverage for connected peripheral devices, directly subsidizing patient acquisition costs for telehealth-integrated systems.
- Bluetooth Low Energy and cellular convergence:The integration of direct-to-cloud transmission with smartphone-agnostic pairing is expanding into elderly user segments previously excluded by smartphone dependency.
Industry Challenges
- FDA 510(k) predicate device navigation:Manufacturers face extended timeline risk when substantial equivalence determinations require additional clinical data beyond original submissions.
- Legacy electronic health record interoperability:Hospital procurement committees are demanding HL7 FHIR compliance that many established device platforms have not yet implemented, forcing delayed certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sphygmomanometer Market |
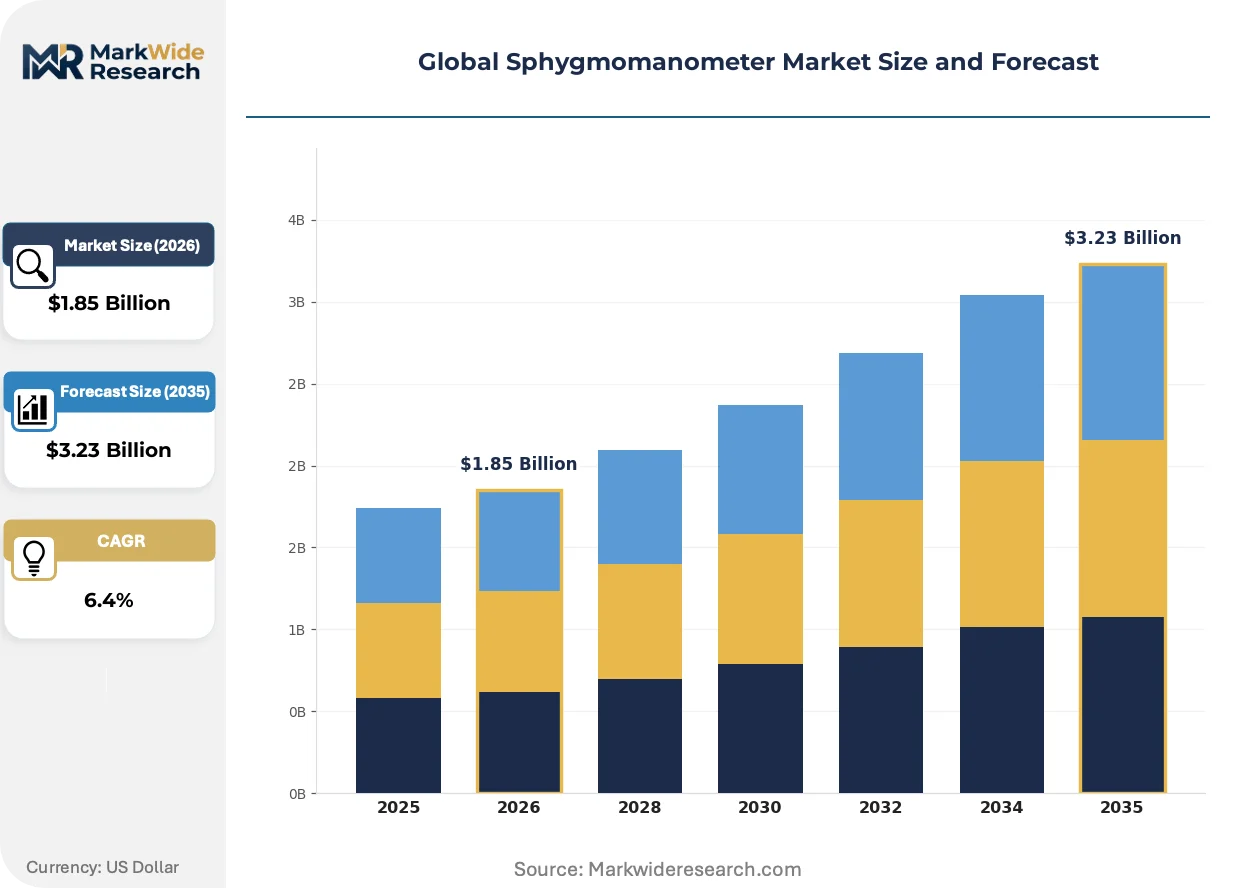
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Digital, Aneroid, Electronic, Ambulatory Technology: Oscillometric, Auscultatory, Palpatory, Capacitive, Piezoelectric Application: Home Care, Primary Care Centers, Specialist Clinics, Telemedicine, Emergency Services End User: Hospitals, Diagnostic Laboratories, Outpatient Facilities, Rehabilitation Centers |
| Companies Covered | Omron Healthcare, Microlife Corporation, A&D Company, GE Healthcare, American Diagnostic Corporation, Beurer, Rossmax International, Baxter International, Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sphygmomanometer Market Shifts & Advancements
Connected device architecture is displacing standalone measurement as the default product configuration, with data transmission capability becoming a baseline expectation rather than a premium feature tier.
Photoplethysmography-integrated hybrid systems are expanding into cuffless blood pressure estimation for screening applications. Wearable manufacturers in the United States and South Korea are adopting semiconductor-based optical sensors that enable continuous waveform capture without brachial compression. This technology is expanding into employer wellness programs and insurance risk assessment protocols where intermittent clinical-grade validation suffices.
Japan's PMDA has accelerated review timelines for software-as-a-medical-device submissions that incorporate artificial intelligence-based arrhythmia detection alongside pressure measurement. The regulatory pathway compresses time-to-market for algorithm-enhanced products while imposing post-market surveillance obligations that favor manufacturers with established pharmacovigilance systems. Cardiology clinics in Tokyo and Osaka are prioritizing these cleared devices for ambulatory monitoring contracts.
Direct-to-consumer subscription models are restructuring how patients acquire measurement hardware. German pharmacy chains and United States telehealth platforms are unbundling device costs into monthly monitoring service fees that include physician interpretation and medication adjustment recommendations. This pattern is most visible in Medicare Advantage plan enrollee populations seeking integrated chronic care management.
Global Sphygmomanometer Market Segmentation
Device configuration directly shapes replacement frequency and upgrade incentives across the sphygmomanometer market. Segmentation reveals how oscillometric automation, telemedicine connectivity, and ambulatory monitoring protocols are restructuring procurement patterns and margin distribution.
Product Type:
Upgrade cycles diverge sharply between manual legacy systems and connected digital platforms, with replacement demand concentrated in cuff consumables and sensor modules.
- Manual:Mercury-column and aneroid gauge mechanisms persist in diagnostic laboratories requiring calibration traceability. Demand concentrates in Germany and Japan where clinical validation protocols still mandate auscultatory reference standards for hypertension staging protocols.
- Digital:Automated oscillometric devices with LCD displays and memory functions dominate pharmacy retail channels. Home care adoption in the United States sustains volume through cuff replacement and battery refresh cycles.
- Aneroid:Dial-face mechanical systems serve resource-limited settings requiring battery-independent operation. Compact portability drives placement in mobile health screening programs across South Asian municipalities.
- Electronic:Hospital-grade automated systems with programmable protocols and multi-patient memory banks anchor institutional procurement. Japanese super-aged care facilities prioritize these units for nurse-station workflow integration.
- Ambulatory:Wearable cuff systems programmed for 24-hour automated measurement intervals capture premium positioning. Cardiology practices in Tokyo and Berlin contract these devices for white-coat hypertension differential diagnosis.
Volume placements concentrate in Digital; the faster expansion belongs to Ambulatory.
Technology:
Measurement methodology determines accuracy validation requirements and regulatory pathway complexity, with cost tiering separating clinical-grade from screening-grade applications.
- Oscillometric:Pressure transducer arrays detect arterial wall vibration amplitudes during cuff deflation. Home care markets in the United States and Germany standardize on this approach for unsupervised patient operation.
- Auscultatory:Stethoscope-assisted Korotkoff sound detection remains the diagnostic gold standard. Specialist clinics and research hospitals mandate this technique for protocol validation and device calibration studies.
- Palpatory:Manual radial pulse detection during systolic pressure estimation serves emergency triage and field screening. Military and expedition medical kits specify these lightweight systems for austere environments.
- Capacitive:Semiconductor-based pressure sensing enables miniaturization in wrist-worn and finger-cuff configurations. South Korean wearable manufacturers integrate these sensors for employer wellness program deployments.
- Piezoelectric:Crystal-based force transduction delivers rapid pressure response in high-throughput clinical settings. Automated hospital admission stations in Japanese acute care facilities specify this technology for patient intake workflows.
Application concentration favors Oscillometric for volume; Capacitive platforms are climbing the fastest through wearable integration.
Application:
End-use setting dictates connectivity requirements, with customer type determining whether standalone measurement or integrated data transmission commands procurement priority.
- Home Care:Self-monitoring patients perform daily measurement protocols without clinical supervision. United States Medicare Advantage chronic care management programs subsidize connected device acquisition for enrolled hypertensive populations.
- Primary Care Centers:General practitioner offices require rapid-cuff systems with immediate result documentation. German Hausarzt practices prioritize HL7 FHIR-compliant devices for seamless electronic health record integration.
- Specialist Clinics:Cardiology and nephrology departments demand ambulatory monitoring capability and arrhythmia detection algorithms. Tokyo and Osaka clinics specify PMDA-cleared AI-enhanced systems for hypertension subtype classification.
- Telemedicine:Remote patient monitoring platforms require automatic data transmission to cloud-based care coordination dashboards. United States CMS reimbursement expansion directly subsidizes patient acquisition costs for these integrated systems.
- Emergency Services:Pre-hospital and acute triage settings prioritize rapid-cycle measurement with shock-resistant construction. Japanese fire and emergency medical services specify automated systems for ambulance-based stroke protocol activation.
Volume concentrates in Home Care; Telemedicine segments are gaining share fastest through reimbursement tailwinds.
End User:
Procurement scale and decision-making authority vary dramatically across institutional settings, with geography influencing whether centralized purchasing or departmental autonomy prevails.
- Hospitals:Acute care systems specify enterprise-grade devices with fleet management and calibration tracking. German university hospital networks consolidate procurement through shared service organizations demanding ISO 81060-2 validation documentation.
- Diagnostic Laboratories:Reference standards and device calibration services require mercury-sphygmomanometer or validated automated systems. Japanese clinical laboratory accreditation bodies mandate traceable measurement protocols for hypertension research studies.
- Outpatient Facilities:Ambulatory surgery centers and urgent care clinics prioritize rapid-turnover automated cuffs with disposable sleeve compatibility. United States multi-site operator chains standardize on single-vendor platforms for supply chain efficiency.
- Rehabilitation Centers:Post-acute and cardiac rehabilitation settings integrate blood pressure monitoring into exercise prescription protocols. German post-stroke rehabilitation facilities specify ambulatory-capable systems for activity-linked pressure variation assessment.
Procurement volume clusters in Hospitals; Rehabilitation Centers show the steepest expansion trajectory as post-acute care extends into residential settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Malaysia and Costa Rica concentrate contract manufacturing capacity for North American and European brand holders seeking FDA and EU MDR proximity.
United States
Medicare Advantage chronic care management programs subsidize connected sphygmomanometer acquisition for hypertensive enrollees. FDA 510(k) clearance timelines shape product launch sequencing for oscillometric device developers. Minneapolis and Boston medical technology clusters host validation laboratories serving domestic manufacturers.
Germany
Hausarzt practices demand HL7 FHIR-compliant devices for seamless electronic health record integration. EU MDR technical documentation obligations filter substandard competitors from distribution channels. Stuttgart and Munich anchor precision sensor fabrication for automated blood pressure systems.
Japan
Super-aged population structure generates sustained volume demand for ambulatory monitoring in institutional and residential settings. PMDA accelerated review timelines compress software-as-a-medical-device pathways for AI-enhanced arrhythmia detection. Tokyo and Osaka cardiology clinics prioritize cleared devices for hypertension subtype classification contracts.
China
Tier-two urban diagnostic center networks in Chengdu and Wuhan remain underpenetrated by automated device distribution. NMPA medical device registration requirements establish compliance barriers favoring manufacturers with established clinical trial infrastructure. Yangtze River Delta electronics clusters supply MEMS pressure transducers to regional device assemblers.
India
Pharmacy retail partnerships in Pune and Jaipur create whitespace for automated device distribution expansion. CDSCO medical device rules impose quality management system requirements on imported and domestic manufacturers. Bangalore and Hyderabad diagnostic center networks drive replacement demand for cuff consumables.
Global Sphygmomanometer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail pharmacy channels consolidating around validated oscillometric platforms while hospital procurement committees demand enterprise-grade fleet management capabilities. The vendor base concentrates among Japanese precision electronics houses, Taiwanese OEM fabricators, and European wellness device specialists. Three archetypes dominate: vertically integrated healthcare conglomerates, dedicated cardiovascular monitoring specialists, and diversified consumer appliance manufacturers extending into medical-grade certification. Competitive moves center on M&A for regulatory predicate device acquisition and capacity expansion into Southeast Asian medical device free trade zones.
Among Japanese precision electronics houses, Omron Healthcare and A&D Company exemplify the vertically integrated archetype with captive sensor fabrication and domestic regulatory navigation expertise. Microlife Corporation represents the dedicated cardiovascular monitoring specialist model with focused oscillometric algorithm development. These three anchors occupy positions across retail pharmacy, hospital procurement, and ambulatory monitoring contract segments respectively.
| Leading Market Players |
|---|
| Omron Healthcare |
| Microlife Corporation |
| A&D Company |
| GE Healthcare |
| American Diagnostic Corporation |
| Beurer |
| Rossmax International |
| Baxter International |
| Panasonic Holdings Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists with multi-generational sensor fabrication expertise anchor pricing discipline through captive MEMS production and long-term hospital procurement contracts. Their ownership structure insulates margin targets from quarterly earnings pressure, allowing sustained investment in ISO 81060-2 validation infrastructure that commodity assemblers cannot match.
Pricing Analysis
Short lead-time premiums command substantial markups in hospital emergency procurement channels, while spot inventory liquidations through pharmacy retail compress margins for standard digital units. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-cleared AI-enhanced systems from FDA 510(k) baseline devices and unvalidated direct-import alternatives. Price differentiation hinges on certification tier and after-sales calibration service bundling. Pricing pressure stems from wrist-worn photoplethysmography substitutes capturing preventive screening occasions. Home care patients exhibit highest price sensitivity; cardiology clinics demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's NMPA localization requirements are reshaping sourcing patterns toward Yangtze River Delta and Bangalore electronics clusters. MEMS pressure transducer fabrication concentrates in Taiwan, South Korea, and Japan; final assembly draws from Malaysian and Costa Rican medical device free trade zones. Raw material dependencies include semiconductor-grade silicon wafers, medical-grade rubber compounds, and lithium battery cells. Single-source vulnerability in East Asian foundry networks threatens continuity. Distribution runs through GPO contracts for hospital systems and pharmacy retail chains for consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as EU MDR technical documentation obligations and ISO 81060-2 clinical trial costs filter substandard competitors from validated distribution channels. Weaker players without dedicated regulatory affairs infrastructure face forced exit or distressed acquisition.
For Market Incumbents: Extend algorithm development partnerships into arrhythmia detection and software-as-a-medical-device pathways to defend against wearable photoplethysmography substitution. Secure backward integration into MEMS pressure transducer fabrication to reduce foundry concentration risk. Prioritize HL7 FHIR interoperability certification to capture hospital procurement committee mandates for electronic health record integration. For New Entrants and Emerging Players: Telemedicine platform partnerships offer the most penetrable entry vector, as CMS reimbursement expansion subsidizes patient acquisition costs for connected peripheral devices. Target India's tier-two urban diagnostic centers in Pune and Jaipur where automated device distribution remains underpenetrated. Pursue white-label manufacturing contracts with established oscillometric algorithm licensors to bypass ISO 81060-2 validation capital barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with captive sensor fabrication in Japan and Taiwan as valuation multiples compress under semiconductor supply uncertainty. Five-to-ten-year viability hinges on regulatory predicate device portfolios and telehealth reimbursement code positioning. Watch CMS remote patient monitoring code expansion velocity as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Device Acquisition | Accelerates market entry by leveraging existing clinical validation data for substantial equivalence determinations. |
| CE Marking Pathway Investment | EU MDR technical documentation capabilities filter competitors and consolidate procurement toward validated manufacturers. |
| Hospital System Partnership | GPO contract penetration secures fleet management revenue and calibration service annuities in acute care settings. |
| Software Companion Development | PMDA-accelerated SaMD pathways for AI-enhanced arrhythmia detection command premium positioning in cardiology clinics. |
| Reimbursement Strategy | CMS remote patient monitoring code alignment directly subsidizes patient acquisition costs for telehealth-integrated systems. |
Research Methodology
FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, and hospital procurement contract registries formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with biomedical engineers, hospital GPO contracts managers, and regulatory affairs directors at oscillometric device manufacturers validated shipment estimates and pricing tier assumptions. Bottom-up and top-down triangulation reconciled unit volume projections with value-based market aggregates.
Bottom-up modeling segmented the market by product type, technology, application, and end user across the analysis window. Oscillometric automation penetration, ambulatory monitoring protocol adoption, and telemedicine connectivity integration served as industry-specific forecast inputs. CAGRs derived from regression analysis of historical shipment data against demographic and reimbursement policy drivers.
Caveats apply where semiconductor supply disruptions, telehealth reimbursement code reversals, or photoplethysmography accuracy breakthroughs could materially shift the outlook. Forecasts reflect assumptions about regulatory pathway stability and chronic disease prevalence trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Prescription Goggles Market
Medical Devices
Medical Device Coating Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
Refurbished Medical Devices Market
Medical Devices
Embolization Plugs Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Operating Room Integration Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Smart Stairlift Market