
 Asia-Pacific Electrophysiology Market | 2026-2036
Asia-Pacific Electrophysiology Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electrophysiology Market Analysis
A shortage of trained cardiac electrophysiologists is reorganizing how device manufacturers deploy clinical support teams across the Asia-Pacific region. Johnson & Johnson leverages its extensive physician training networks to embed specialists within key hospital accounts. Abbott Laboratories sustains competitive advantage through deep catheter portfolio specialization that addresses complex arrhythmia substrates. Medtronic anchors its presence via integrated mapping and ablation platforms that reduce procedure variability.
Asia-Pacific electrophysiology encompasses the diagnostic and therapeutic technologies used to identify, map, and ablate cardiac arrhythmias, including multi-electrode catheters operating at 3-8 mm tip diameters and 3D electroanatomic mapping systems achieving sub-millimeter spatial resolution. Catheters dominate product type revenue due to recurring procedural consumption, while mapping systems capture concentrated margin pools from high-acuity tertiary centers. Radiofrequency technology leads technology adoption across mature markets, though cryoablation gains traction in pediatric and pulmonary vein isolation applications where tissue preservation matters.
Japan's PMDA, Australia's TGA, and China's NMPA each enforce distinct electrophysiology device classification and clinical evidence requirements that shape manufacturer registration strategies and timeline planning. India's CDSCO has begun aligning with international standards for active implantable devices, opening pathways for imported ablation systems. Stakeholders must monitor how harmonization efforts across these regulators affect portfolio prioritization and localization investments.
Market Dynamics
Catheter miniaturization below 3 mm tip diameters is compressing procedure times and expanding treatable patient populations across Asia-Pacific electrophysiology, forcing manufacturers to reconfigure R&D roadmaps around microfabrication capabilities.
Growth Catalysts
- Japan's PMDA accelerated approval pathway:Streamlined electrophysiology device registration reduces market entry timelines for novel ablation systems, incentivizing manufacturers to prioritize Japanese launch sequencing.
- Hospital-based electrophysiology lab construction:Cardiology departments in China and India are dedicating capital budgets to dedicated arrhythmia treatment suites, creating installed base demand for mapping platforms.
- Radiofrequency generator portability:Compact 50-150W systems enable catheter ablation outside tertiary centers, extending service reach into secondary hospitals across Southeast Asia.
Market Restraints
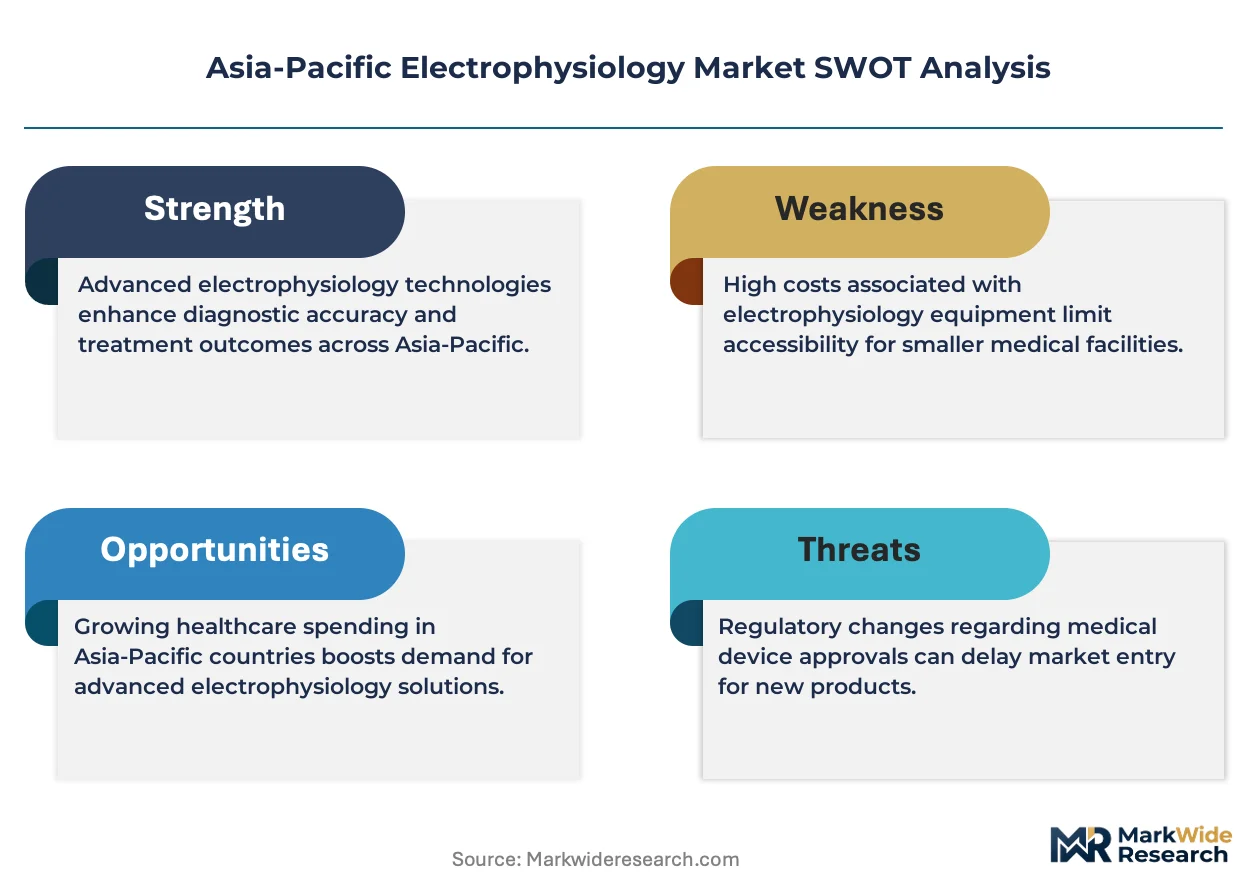
- Platinum-iridium electrode material costs:Precious metal price volatility in catheter tip electrodes compresses gross margins on consumable devices, particularly affecting high-density mapping catheter portfolios.
- Single-source dependency for cryoablation balloons:Concentrated manufacturing of nitrous oxide-based cryogenic systems creates supply vulnerability for pediatric and pulmonary vein isolation procedures.
- China NMPA Class III device clinical evidence requirements:Extended local trial mandates for novel energy modalities delay product registration by 18-36 months versus comparable TGA or PMDA pathways.
Strategic Opportunities
- India's CDSCO alignment with international standards:Harmonization of active implantable device regulations opens import pathways for advanced ablation systems previously blocked by divergent testing protocols.
- Artificial intelligence-integrated electroanatomic mapping:Machine learning algorithms for automatic arrhythmia source detection converge with cloud-based procedural databases to enable remote proctoring and outcome benchmarking.
- Direct-to-hospital catheter consignment models:Inventory-light supply arrangements reduce working capital burdens for mid-tier cardiology clinics in Indonesia and Vietnam expanding ablation services.
Industry Challenges
- Electrophysiologist training pipeline gaps:Fellowship programs across Asia-Pacific produce insufficient catheter ablation specialists to match lab expansion rates, forcing device manufacturers to deploy clinical field teams for procedural support.
- Legacy mapping system interoperability:Proprietary data formats from installed 3D electroanatomic platforms complicate hospital upgrades, requiring costly middleware development or complete system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electrophysiology Market |
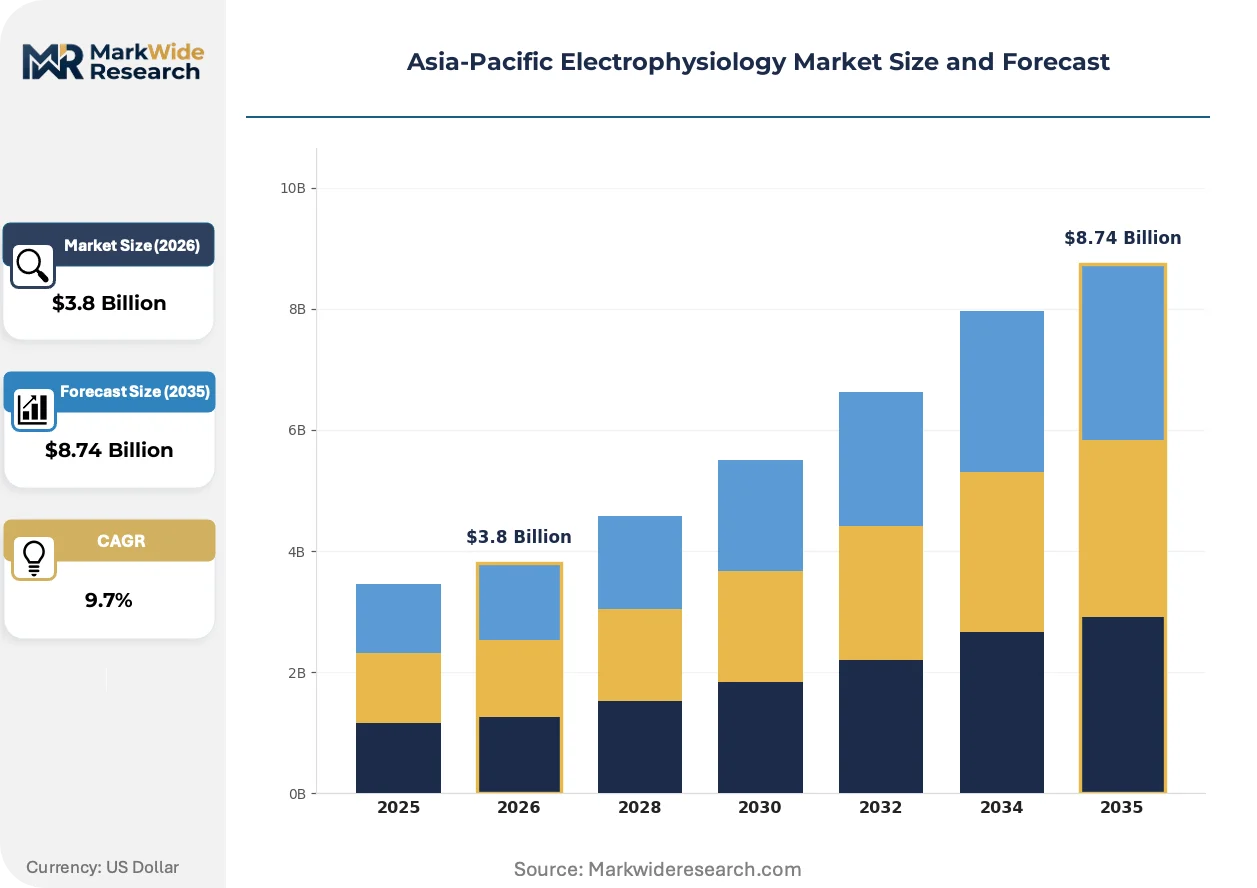
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Mapping Systems, Ablation Devices, Electrophysiology Software End User: Hospitals, Cardiology Clinics, Research Institutes, Diagnostic Laboratories Technology: Radiofrequency, Cryoablation, Laser, Hybrid Systems Application: Arrhythmia Treatment, Diagnostic Procedures, Cardiac Monitoring, Device Implantation |
| Companies Covered | Johnson & Johnson, GE Healthcare, Abbott Laboratories, BIOTRONIK, Microport Scientific Corporation, Boston Scientific Corporation, Koninklijke Philips, Japan Lifeline, Medtronic, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electrophysiology Market Emerging Trajectories
Electrophysiology technology trajectories center on precision enhancement, regulatory pathway optimization, and service model restructuring across Asia-Pacific cardiac care networks.
High-density microelectrode arrays with 64-256 mapping points are miniaturizing catheter tip geometries below 2.5 mm while maintaining signal fidelity. Tertiary electrophysiology labs in Japan and South Korea are adopting these platforms for complex atrial tachycardia cases. The technology is miniaturizing diagnostic catheter specifications, compressing the distinction between diagnostic and therapeutic device categories.
Australia's TGA has implemented parallel assessment agreements with Japan's PMDA for electrophysiology device registrations, reducing duplicate clinical study requirements. This regulatory convergence accelerates product launch sequencing across Asia-Pacific markets. High-acuity catheter portfolios targeting paroxysmal atrial fibrillation are prioritizing TGA-PMDA joint submissions to capture early adopter hospital networks.
Hospital procurement committees are consolidating electrophysiology device purchasing under cardiology service line budgets rather than capital equipment silos. This budget reallocation shifts vendor relationships toward multi-year consumable supply agreements with integrated mapping system placements. The restructuring is most visible in China's provincial hospital networks, where centralized purchasing platforms aggregate demand across affiliated facilities.
Asia-Pacific Electrophysiology Market Segmentation
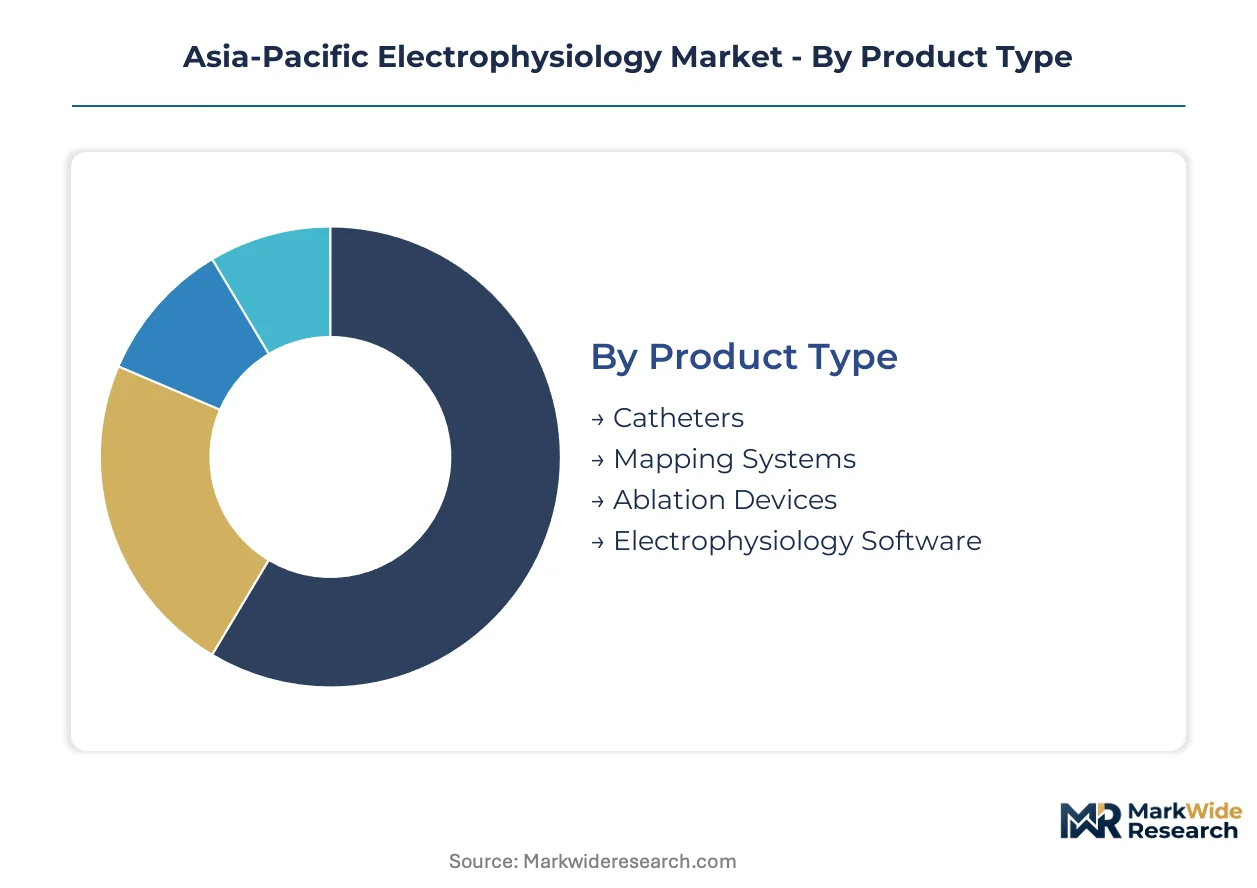
Segmentation in Asia-Pacific electrophysiology reveals how regulatory pathways, procedure economics, and clinical infrastructure interact across distinct product and customer categories. Each dimension carries specific implications for manufacturer positioning and capital deployment priorities.
Product Type:
Japan's PMDA and China's NMPA enforce divergent clinical evidence standards for catheter-based versus capital equipment categories, shaping registration sequencing and localization investments.
- Catheters:Multi-electrode diagnostic and therapeutic catheters with 3-8 mm tip diameters constitute the procedural consumable backbone. Demand concentrates in China's provincial hospital networks building dedicated electrophysiology labs, where recurring catheter purchases anchor vendor relationships against mapping system competition.
- Mapping Systems:3D electroanatomic platforms achieving sub-millimeter spatial resolution command concentrated margin pools from Japan and South Korea's tertiary centers. PMDA's streamlined approval pathway for novel mapping technologies accelerates product launch sequencing relative to NMPA's extended trial mandates.
- Ablation Devices:Radiofrequency generators and cryoablation consoles represent capital-intensive therapeutic infrastructure.
- Electrophysiology Software:Cloud-based procedural databases and AI-integrated analysis tools enable remote proctoring across electrophysiologist-scarce markets.
Catheters handle the majority of throughput; mapping systems are the fastest mover on share.
End User:
Customer economics vary sharply between capital-equipped hospitals and procedure-focused clinics, with Australia's TGA and India's CDSCO setting distinct facility licensing requirements.
- Hospitals:Tertiary cardiac centers in Japan, South Korea, and China's tier-1 cities host integrated electrophysiology suites with full mapping and ablation capabilities. These facilities concentrate complex arrhythmia caseloads and drive premium technology adoption.
- Cardiology Clinics:Southeast Asia's expanding catheter-based ablation services operate through dedicated arrhythmia treatment units. Compact 50-150W radiofrequency generators enable procedure migration from tertiary centers into secondary hospital settings across Indonesia and Vietnam.
- Research Institutes:Academic medical centers in Japan and Australia conduct clinical trials for novel energy modalities under PMDA-TGA parallel assessment agreements.
- Diagnostic Laboratories:Standalone cardiac monitoring facilities support pre-procedural workup and post-ablation surveillance.
Hospitals absorb the capital equipment volume; cardiology clinics are expanding most quickly as service reach extends.
Technology:
Energy modality selection reflects tissue preservation priorities, procedure time economics, and regulator-specific approval timelines across Asia-Pacific markets.
- Radiofrequency:Thermal ablation via 50-150W generators dominates mature markets with established reimbursement pathways. China's NMPA Class III device requirements for novel energy modalities reinforce radiofrequency's incumbent position through faster registration timelines.
- Cryoablation:Nitrous oxide-based balloon systems target pulmonary vein isolation and pediatric applications where tissue preservation matters. Single-source manufacturing concentration creates supply vulnerability that shapes hospital procurement contingency planning.
- Laser:Optical energy delivery systems address specific substrate anatomies with precision thermal control.
- Hybrid Systems:Multi-modality platforms integrating mapping and varied energy sources reduce procedure variability.
Radiofrequency handles the majority of procedures; cryoablation is climbing the fastest as pediatric and paroxysmal AF applications expand.
Application:
Procedure type segmentation aligns with Asia-Pacific's atrial fibrillation burden distribution and electrophysiologist training pipeline constraints.
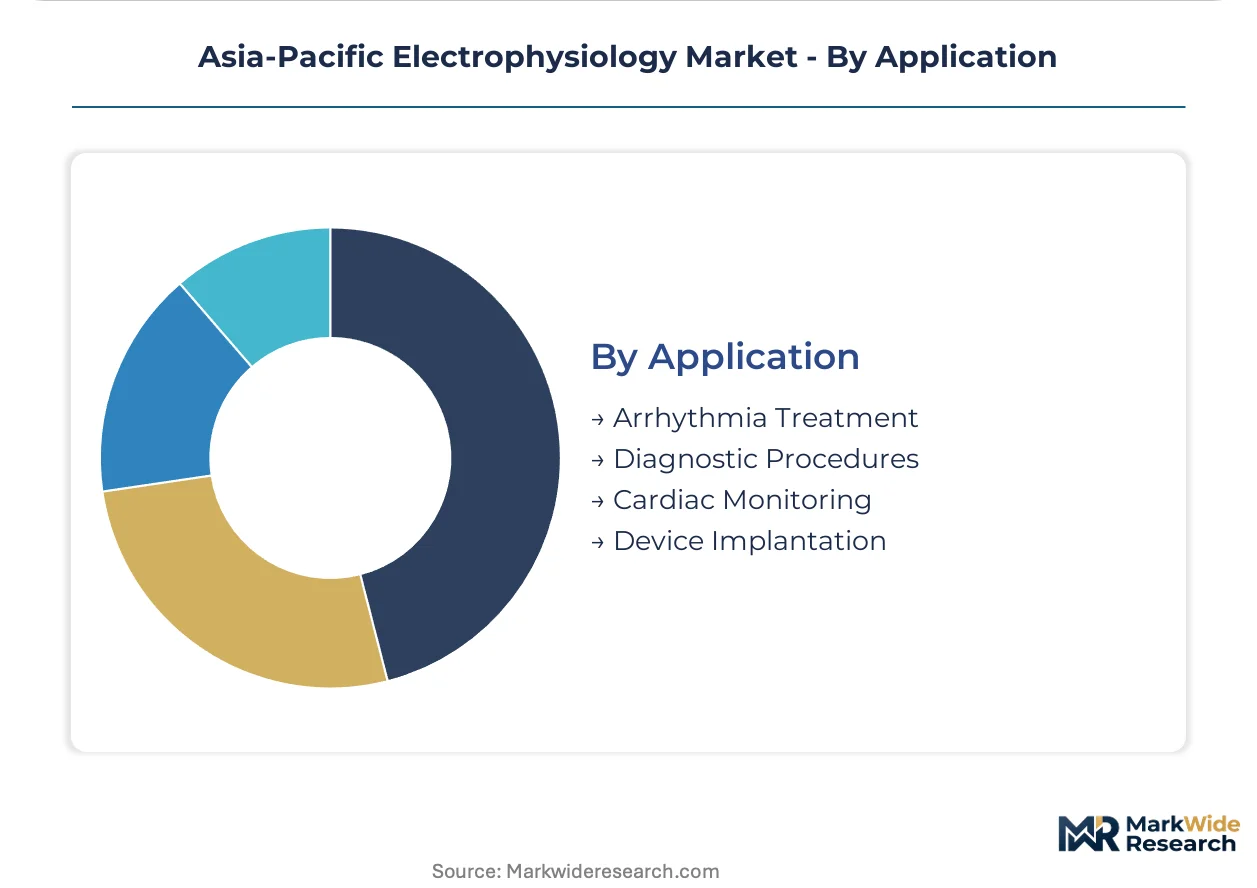
- Arrhythmia Treatment:Catheter ablation for atrial fibrillation, atrial flutter, and ventricular tachycardia constitutes the core revenue driver. India's rising AF caseloads and expanding hospital networks building dedicated electrophysiology labs concentrate demand growth.
- Diagnostic Procedures:Electrophysiology study and mapping for arrhythmia substrate characterization supports treatment planning. High-density microelectrode arrays with 64-256 mapping points miniaturize diagnostic capabilities below 2.5 mm tip geometries.
- Cardiac Monitoring:Long-term rhythm surveillance via implantable and external devices guides ablation candidacy.
- Device Implantation:Pacemaker and ICD procedures intersect with electrophysiology lab capabilities.
Arrhythmia treatment captures the procedural volume; diagnostic procedures are gaining share fastest as mapping technology miniaturization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's tertiary centers consume high-resolution mapping systems for complex arrhythmia substrates, while China's provincial hospitals prioritize catheter throughput over capital equipment sophistication.
Japan
PMDA's accelerated approval pathway draws novel ablation system launches ahead of other Asia-Pacific markets. Tokyo and Osaka host concentrated electrophysiology lab networks performing complex atrial tachycardia procedures. Kanto region medical centers adopt high-density microelectrode arrays with 64-256 mapping points for substrate characterization.
China
Provincial hospital networks in Jiangsu and Guangdong dedicate capital budgets to dedicated electrophysiology suites for rising atrial fibrillation caseloads. NMPA Class III device requirements extend registration timelines for novel energy modalities versus cryoablation balloons. Yangtze River Delta tertiary centers concentrate installed base demand for 3D electroanatomic mapping platforms.
India
CDSCO alignment with international standards for active implantable devices opens import pathways for advanced ablation systems. Maharashtra and Karnataka hospital chains build dedicated arrhythmia treatment units with compact radiofrequency generators. Delhi-NCR cardiology clinics expand catheter-based services through direct-to-hospital consignment inventory models.
Australia
TGA parallel assessment agreements with Japan's PMDA reduce duplicate clinical study requirements for electrophysiology device registrations. Sydney and Melbourne tertiary cardiac centers concentrate premium technology adoption for paroxysmal atrial fibrillation portfolios. Southeast Queensland hospital procurement committees consolidate device purchasing under cardiology service line budgets.
South Korea
Seoul Capital Area medical centers adopt miniaturized diagnostic catheters below 2.5 mm tip geometries for complex substrate mapping. MFDS regulatory pathways support accelerated market entry for AI-integrated electroanatomic mapping systems. Busan-Ulsan regional hospitals expand electrophysiology lab capacity to capture referral flows from secondary centers.
Asia-Pacific Electrophysiology Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in Asia-Pacific electrophysiology. Johnson & Johnson, Medtronic, and Abbott Laboratories anchor the upper tier through catheter portfolio breadth and mapping system integration. Specialist manufacturers concentrate in cryoablation balloons and high-density diagnostic catheters. Competitive dynamics center on physician training network deployment and multi-year consumable supply agreements with integrated system placements.
Among diversified healthcare conglomerates, Johnson & Johnson and GE Healthcare occupy positions spanning diagnostic imaging through therapeutic devices. Abbott Laboratories exemplifies the catheter specialization archetype through deep portfolio investment in complex arrhythmia substrates. Medtronic anchors the integrated platform tier with combined mapping and ablation system offerings. Japan Lifeline represents regional specialist positioning within Asia-Pacific electrophysiology supply chains. Boston Scientific Corporation and Koninklijke Philips sit within the diversified medical technology tier with electrophysiology as one vertical among broader cardiac care portfolios.
| Leading Market Players |
|---|
| Johnson & Johnson |
| GE Healthcare |
| Abbott Laboratories |
| BIOTRONIK |
| Microport Scientific Corporation |
| Boston Scientific Corporation |
| Koninklijke Philips |
| Japan Lifeline |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Platinum-iridium electrode fabrication scale in Japan and Germany anchors catheter tip production economics, compressing unit costs for high-density mapping arrays while simultaneously concentrating supplier pricing power over mid-tier manufacturers in Southeast Asia.
Pricing Analysis
Long-term catheter consignment contracts dominate hospital procurement in China and India, locking in multi-year consumable supply agreements with integrated mapping system placements. Three-tier pricing structure across premium, standard, and economy levels differentiates by electrode density and tip miniaturization capability. Pricing pressure stems from precious metal volatility in platinum-iridium electrodes, squeezing margins on high-density portfolios. Secondary hospitals in Indonesia and Vietnam exhibit highest price sensitivity, while Japan's tertiary centers prioritize signal fidelity over unit cost.
Supply Chain Analysis
Japan and the United States anchor precision electrode and microfabrication component production, while China concentrates radiofrequency generator assembly and cryoablation balloon manufacturing. Raw material flows draw from South African platinum mines, German precision wire suppliers, and Japanese ceramic substrate fabricators. Single-source dependency for nitrous oxide-based cryogenic systems creates supply vulnerability for pediatric procedures. Distribution runs through hospital procurement committees consolidating cardiology service line budgets rather than capital equipment silos.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained cardiac electrophysiologist scarcity across Asia-Pacific markets creates persistent capability gaps that reshape competitive dynamics, forcing device manufacturers to embed clinical support teams within hospital accounts and restructure service models around procedural assistance rather than pure equipment sales.
For Market Incumbents: Secure electrophysiologist training network density in Japan and South Korea before China's NMPA registration timelines compress competitive windows. Lock in multi-year catheter consignment agreements with provincial hospital networks in Jiangsu and Guangdong to defend against mapping system displacement. Invest in backward integration into platinum-iridium electrode supply to offset precious metal volatility squeezing high-density catheter margins. For New Entrants and Emerging Players: Lead with AI-integrated electroanatomic mapping software targeting India's CDSCO-aligned import pathways for advanced ablation systems previously blocked by divergent testing protocols. Capture white-space in direct-to-hospital consignment models for mid-tier cardiology clinics in Vietnam and Indonesia expanding ablation services. Deploy cloud-based remote proctoring platforms to circumvent electrophysiologist training pipeline gaps limiting procedure volume growth. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors catheter portfolio specialists with deep complex arrhythmia substrate capabilities over diversified medical technology conglomerates. Long-term viability hinges on regulatory pathway optimization across PMDA-TGA parallel assessment agreements accelerating product launch sequencing. Watch for MFDS accelerated approvals for AI-integrated mapping systems as inflection signal for technology-cycle maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Physician Training Network Expansion | Johnson & Johnson's embedded specialist model addresses electrophysiologist scarcity in Chinese provincial hospitals. |
| Regulatory Parallel Assessment Filing | TGA-PMDA joint submissions reduce duplicate clinical study requirements for novel ablation system launches. |
| Catheter Consignment Model Deployment | Inventory-light supply arrangements reduce working capital burdens for Indonesian and Vietnamese cardiology clinics. |
| High-Density Microelectrode Array Development | 64-256 mapping point catheters below 2.5 mm tip geometries miniaturize diagnostic capabilities for complex substrates. |
| Cloud-Based Remote Proctoring Platform | Machine learning algorithms for automatic arrhythmia source detection enable outcome benchmarking across electrophysiologist-scarce markets. |
Methodological Framework
Initial hypotheses were tested against primary input from cardiac electrophysiologists, hospital procurement committee members, biomedical engineers, and GPO contracts managers, and refined through secondary validation against PMDA registration filings, TGA device approvals, NMPA clinical trial databases, and hospital capital expenditure records. Bottom-up catheter shipment modeling and top-down electrophysiology lab installation tracking were triangulated against provincial health ministry infrastructure spending disclosures.
Variance decomposition across product type, end user, energy modality, and application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates and procedure volume elasticity to catheter consumption. Forecast inputs incorporated NMPA Class III device registration timelines, CDSCO harmonization progress with international standards, and platinum-iridium price trajectory assumptions.
The analysis sits within stated boundaries; outcomes outside sustained government cardiac care infrastructure investment or accelerated electrophysiologist training program expansion would require recalibration. Forecasts reflect documented assumptions about regulatory pathway convergence and precious metal supply stability. Recalibration cycles align with material shifts in PMDA-TGA parallel assessment adoption rates and provincial hospital network capital budget allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implantable Port Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Patellar Implant Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Global Nasal Spray Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
United Kingdom Respiratory Devices Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Global Trauma Devices Market