
 Facial Injector Market | 2026-2036
Facial Injector Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Injector Market Analysis
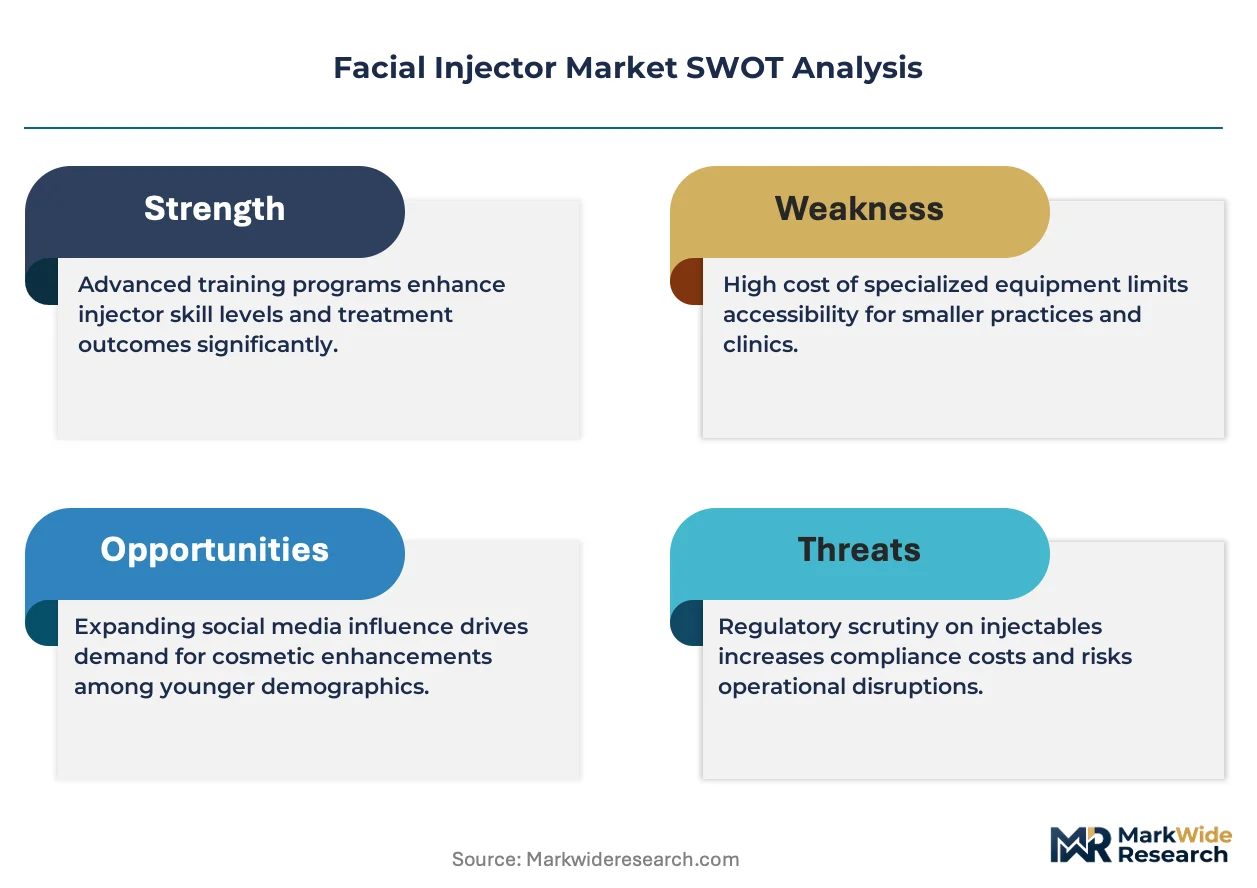
Hyaluronic acid is repositioning calcium hydroxylapatite in mid-face volume applications due to superior reversibility and lower adverse event profiles. AbbVie Inc. leverages its Allergan heritage to dominate the botulinum toxin segment through entrenched physician training networks. Galderma SA anchors its competitive stance with integrated dermatology channel control spanning prescription skincare and injectable portfolios. Merz Pharma specializes in microcannula delivery systems that reduce vascular occlusion risks during procedure administration.
A facial injector constitutes a precision delivery instrument engineered to administer dermal fillers or neuromodulators at controlled depths between 0.5 mm and 5.0 mm with dosage accuracy within 0.01 mL increments, designed to achieve targeted tissue plane placement for aesthetic or therapeutic outcomes. Botulinum toxin products command the largest revenue pool given chronic reinjection cycles and established therapeutic indications beyond cosmetics. Hyaluronic acid formulations represent the fastest-expanding category as cross-linking innovations extend duration from six to eighteen months. Pre-filled syringe technology captures disproportionate margin concentration by eliminating compounding steps and reducing contamination exposure in clinical settings.
The FDA regulates facial injectors as combination products when paired with biologic fillers, requiring dual Center for Biologics Evaluation and Research and Center for Devices and Radiological Health oversight that lengthens approval timelines. The EU Medical Device Regulation imposes unique device identification and post-market surveillance obligations that elevate compliance costs for European market participants. Stakeholders must monitor evolving FDA guidance on real-world evidence requirements for extended-duration filler claims, as this determination will reshape competitive positioning between established hyaluronic acid portfolios and emerging poly-L-lactic acid entrants.
Market Dynamics
Cross-linking chemistry advances in hyaluronic acid formulations are compressing reinjection cycles and reshaping competitive positioning between temporary and semi-permanent filler categories. Physician training network density now determines market access more than product differentiation alone.
Growth Catalysts
- EU Medical Device Regulation post-market surveillance mandates:Elevated compliance costs are filtering out marginal manufacturers and consolidating shelf space for established portfolios in European medical spas and dermatology clinics.
- Microcannula delivery systems:Reduced vascular occlusion risk during mid-face volumization procedures is expanding the addressable patient base to anticoagulated populations previously excluded from needle-based treatments.
- United States clinic density concentration:Disposable income polarization in coastal metropolitan corridors sustains premium procedure uptake despite macroeconomic headwinds affecting discretionary healthcare spending.
Market Restraints
- Dual Center oversight timelines:FDA combination product classification requiring simultaneous Center for Biologics Evaluation and Research and Center for Devices and Radiological Health review extends approval durations by eighteen to thirty-six months versus standalone device pathways.
- Hyaluronic acid raw material concentration:Fermentation-derived sodium hyaluronate supply chains cluster in Chinese and Japanese bioproduction hubs, creating geographic single-point vulnerability for Western formulators.
- Reversibility limitation of calcium hydroxylapatite:The absence of enzymatic dissolution agents restricts corrective intervention options, driving patient preference migration toward reversible alternatives despite superior duration profiles.
Strategic Opportunities
- Medical spa channel expansion in Germany:Regulatory harmonization under EU MDR is enabling cross-border franchise models to penetrate underserved secondary cities with standardized training protocols.
- Biostimulatory filler convergence with energy-based devices:Sequential treatment protocols combining poly-L-lactic acid with fractional radiofrequency are creating bundled service revenue streams in aesthetic dermatology practices.
- India's Central Drugs Standard Control Organization streamlined import pathways:Reduced registration timelines for pre-filled syringe formats are opening access to a physician base previously reliant on compounded preparations.
Industry Challenges
- Microvascular anatomy certification requirements:Vascular occlusion recognition and hyaluronidase administration competency now represent mandatory continuing education burdens for clinic operators in jurisdictions adopting enhanced safety standards.
- Cold chain integrity for botulinum toxin storage:Temperature excursion risk during last-mile distribution to satellite clinic networks demands redundant monitoring infrastructure that compresses per-unit margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Injector Market |
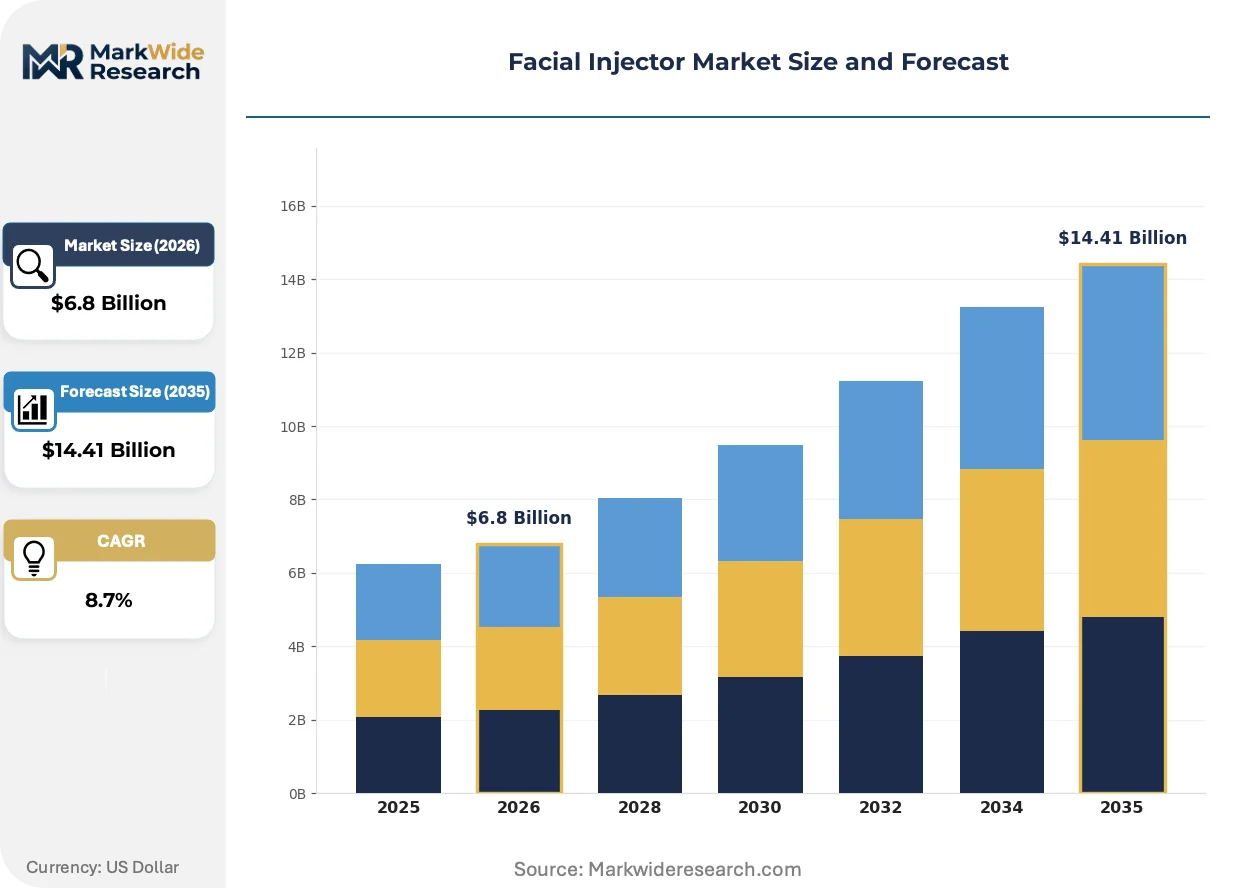
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-lactic Acid End User: Clinics, Dermatology Centers, Medical Spas, Hospitals Application: Wrinkle Reduction, Volume Restoration, Facial Contouring, Skin Hydration Technology: Needle-Free Injectors, Traditional Syringe, Microcannula, Pre-Filled Syringes |
| Companies Covered | AbbVie Inc., Galderma SA, Merz Pharma, Ipsen SA, Revance Therapeutics Inc., Medytox Inc., Suneva Medical Inc., Sinclair Pharma, Bloomage BioTechnology Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Injector Market Emerging Trajectories
Product differentiation is migrating from filler chemistry to delivery precision, with instrumentation and technique protocols capturing margin previously concentrated in formulation intellectual property. This shift is redistributing value capture across the supply chain.
Pre-filled syringe technology is absorbing the compounding function previously performed in clinic settings, eliminating batch variability and contamination exposure while enabling manufacturer-controlled viscosity calibration. Medical spas and dermatology groups in the United States and Germany are standardizing procurement around these formats. The consolidation of preparation steps is compressing per-procedure labor allocation and shifting liability exposure upstream to device manufacturers.
The EU Medical Device Regulation unique device identification requirements are forcing serialization infrastructure investments across European distribution networks. Manufacturers serving the European market must now maintain traceability databases linking individual syringe units to patient outcomes. Smaller formulators lacking enterprise resource planning integration are exiting the market, concentrating supply among portfolios with compliant labeling and post-market surveillance systems.
Consumer preference in South Korea and Japan is rotating toward preventive, low-volume maintenance protocols rather than corrective high-volume interventions. Younger patient cohorts are initiating neuromodulator treatments in their late twenties with fractional dosing schedules. This behavioral pivot is extending lifetime value calculations for clinic operators while compressing average revenue per visit metrics and demanding reconfigured appointment scheduling density.
Facial Injector Market Segmentation
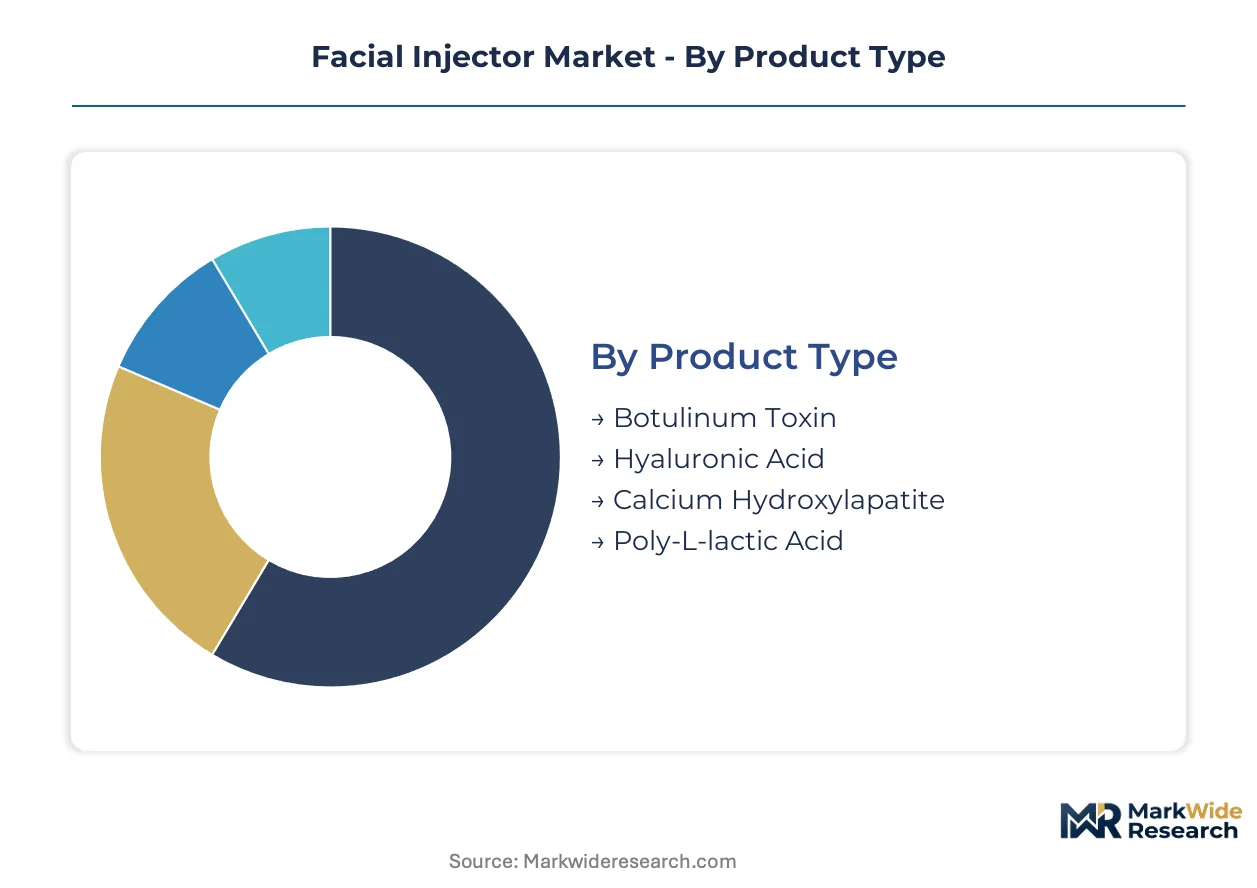
Product chemistry, delivery mechanism, and treatment setting each command distinct procurement workflows and margin structures in facial injectors. Understanding how demand fragments across these dimensions reveals where formulation intellectual property yields to instrumentation control.
Product Type:
Capital intensity peaks with biologic fermentation infrastructure for botulinum toxin, while hyaluronic acid demands cross-linking reactor investment and poly-L-lactic acid requires extended polymerization cycles.
- Botulinum Toxin:Neurotoxic protein produced through Clostridium botulinum fermentation at multi-thousand liter scale with stringent cold chain requirements from production through point-of-care. Chronic reinjection cycles in United States metropolitan corridors sustain premium pricing despite biosimilar pressure.
- Hyaluronic Acid:Cross-linked sodium hyaluronate gels varying in particle size and G-prime elasticity for targeted tissue plane placement. Germany's medical spa channel is absorbing the fastest volume growth as reversible profiles reduce physician liability exposure.
- Calcium Hydroxylapatite:Biosynthetic mineral microspheres suspended in aqueous gel carrier for deep dermal and subdermal placement.
- Poly-L-lactic Acid:Biostimulatory polymer requiring reconstitution and extended hydration protocols before administration.
Most installed capacity flows through botulinum toxin. Expansion is steepest in hyaluronic acid.
End User:
Facility licensing tier determines reimbursement access and procedure complexity ceilings, with hospital outpatient departments commanding the highest capital equipment standards.
- Clinics:Independent physician practices with procedure room infrastructure and direct-to-consumer marketing capacity. United States coastal metropolitan clusters concentrate the highest-value patient cohorts with disposable income polarization sustaining premium uptake.
- Dermatology Centers:Specialist-anchored facilities with integrated diagnostic and therapeutic service lines. South Korea's channel is standardizing around preventive maintenance protocols with fractional dosing schedules for younger patient entry.
- Medical Spas:Non-physician supervised settings with delegated injection authority under medical director oversight.
- Hospitals:Academic and community-based outpatient departments with emergency response capability for adverse event management.
Procedure volume concentrates in dermatology centers. Patient acquisition costs are climbing fastest in medical spas.
Application:
Treatment indication shapes filler viscosity selection and injection depth protocols, with volume restoration demanding the highest product volumes per session.
- Wrinkle Reduction:Neuromodulator-dominant category targeting dynamic rhytids through muscle relaxation at 2.5-5.0 mm depth. Japan's younger demographic entry in late twenties is compressing average revenue per visit while extending lifetime value calculations.
- Volume Restoration:Hyaluronic acid and calcium hydroxylapatite deployment for mid-face, temple, and perioral hollowing. Microcannula adoption in anticoagulated populations is expanding the addressable base beyond traditional needle-eligible cohorts.
- Facial Contouring:Structural augmentation of jawline, chin, and cheek projection using high G-prime formulations.
- Skin Hydration:Superficial dermal placement of low-crosslink density hyaluronic acid for epidermal quality improvement.
Revenue per procedure peaks in volume restoration. Injection frequency is accelerating most quickly in skin hydration.
Technology:
Delivery precision now determines competitive differentiation more than formulation chemistry, with pre-filled formats eliminating compounding liability and microcannula systems reducing vascular risk.
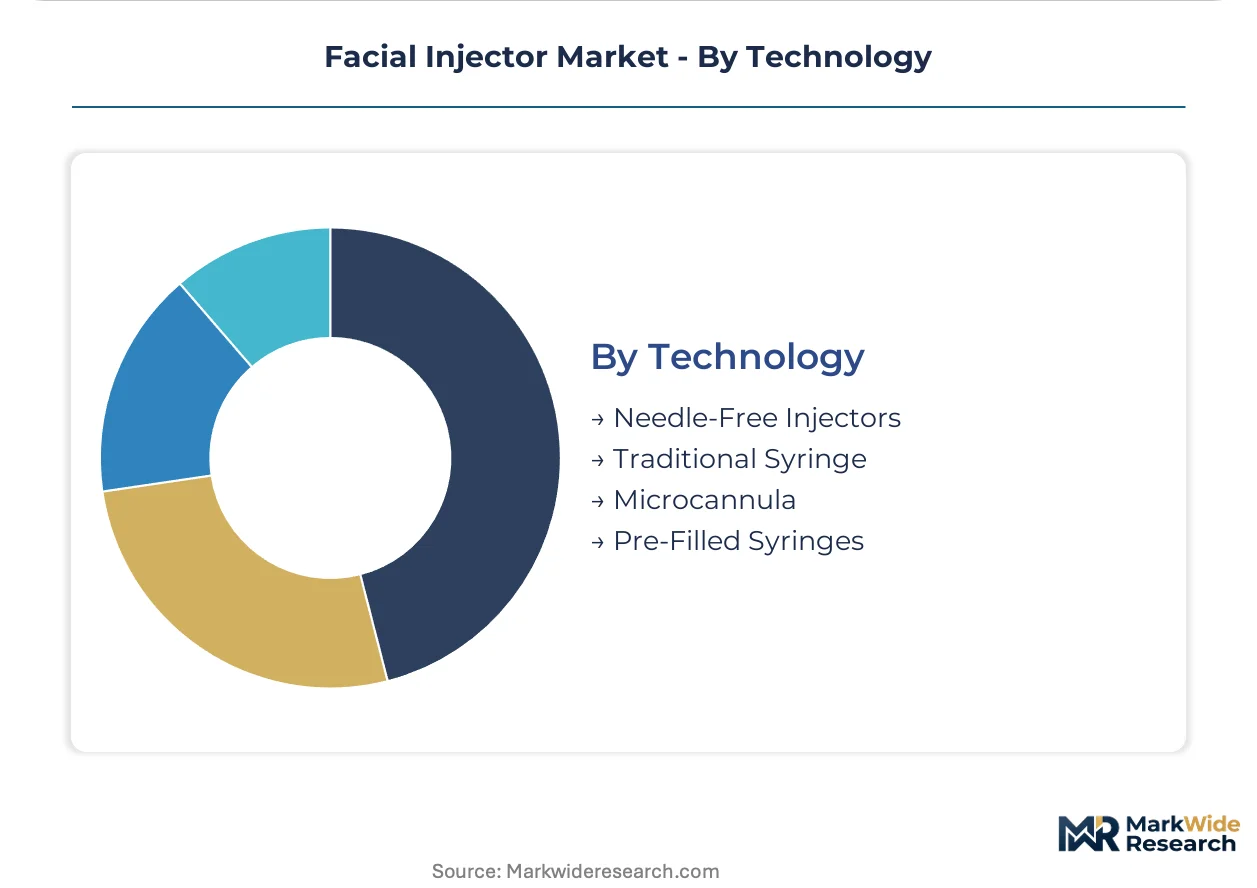
- Pre-Filled Syringes:Manufacturer-sealed units with viscosity-calibrated gel and integrated Luer-lock connectivity eliminating clinic-side preparation. EU MDR unique device identification mandates are forcing serialization infrastructure investments that filter out smaller formulators.
- Microcannula:Blunt-tipped flexible instruments for subdermal placement with reduced vessel penetration probability. India's CDSCO streamlined import pathways are opening access to physician bases previously reliant on compounded preparations.
- Traditional Syringe:Standard hypodermic needle systems requiring clinician-controlled draw-up from vial or compounding.
- Needle-Free Injectors:Pressure-driven or jet-based systems for superficial product deposition without sharp instrument penetration.
Procurement standardization is concentrating in pre-filled syringes. Training investment is expanding most rapidly in microcannula.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal metropolitan corridors in the United States concentrate the highest-value patient cohorts and clinic density for facial injector procedures. Disposable income polarization in these clusters sustains premium procedure uptake despite broader macroeconomic pressures on discretionary healthcare spending.
United States
FDA dual Center oversight for combination products extends approval timelines, filtering out smaller device manufacturers. The Center for Biologics Evaluation and Research and Center for Devices and Radiological Health review processes add eighteen to thirty-six months versus standalone pathways. Los Angeles and New York Metro medical spa networks standardize procurement around pre-filled syringe formats to eliminate compounding liability.
Germany
EU Medical Device Regulation unique device identification mandates force serialization infrastructure investments across distribution networks. Post-market surveillance obligations elevate compliance costs and consolidate shelf space for established portfolios. Munich and Frankfurt secondary cities absorb cross-border franchise expansion with standardized training protocols under harmonized EU MDR frameworks.
South Korea
Younger demographic entry into neuromodulator treatments in late twenties compresses average revenue per visit while extending lifetime value calculations. MFDS streamlined pathways for pre-filled formats accelerate product registration versus compounded alternatives. Seoul dermatology centers standardize around preventive maintenance protocols with fractional dosing schedules.
India
CDSCO reduced registration timelines for pre-filled syringe formats open access to physician bases previously reliant on compounded preparations. Central Drugs Standard Control Organization import pathway streamlining eliminates prior reliance on local compounding infrastructure. Mumbai and Delhi-NCR clinic networks adopt microcannula delivery systems for expanded anticoagulated patient eligibility.
Japan
PMDA post-market surveillance requirements align with global standards while maintaining distinct documentation protocols for biologic-device combinations. Preventive aesthetic protocol adoption among younger cohorts shifts demand toward low-volume maintenance schedules. Tokyo and Osaka aesthetic dermatology practices bundle poly-L-lactic acid with energy-based devices for sequential treatment revenue streams.
Facial Injector Market Vendor Landscape
Global majors compete with regional champions across physician training network density and channel control dimensions. Market structure tilts toward consolidation at the formulation level with fragmentation in delivery instrumentation. Three archetypes dominate: diversified pharmaceutical conglomerates with aesthetic divisions, pure-play dermatology specialists, and bioproduction-focused formulators. Competitive moves concentrate on M&A for channel access and vertical integration into raw material fermentation capacity.
Within the pharmaceutical conglomerate tier, AbbVie Inc. and Galderma SA occupy positions anchored by entrenched physician education infrastructure and integrated dermatology channel control. Merz Pharma exemplifies the delivery specialization archetype through microcannula system development. These three entities represent distinct strategic vectors—formulation scale, channel integration, and instrumentation precision—that define competitive positioning in this market.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Galderma SA |
| Merz Pharma |
| Ipsen SA |
| Revance Therapeutics Inc. |
| Medytox Inc. |
| Suneva Medical Inc. |
| Sinclair Pharma |
| Bloomage BioTechnology Corporation Limited |
| Others |
Supply Flow & Price Mechanics
Pre-filled syringe premiumization against compounded commodity alternatives bifurcates procurement economics, with manufacturer-sealed formats commanding price multiples that reflect cold chain integrity investments and liability transfer upstream while clinic-side preparation concentrates cost compression in non-standardized settings. This tier divergence maps directly onto supply chain configurations: premium tiers anchor in FDA and EU MDR compliant serialization infrastructure, while economy tiers depend on fragmented compounding networks with variable input sourcing.
Pricing Analysis
Fermentation-derived sodium hyaluronate and Clostridium botulinum culture media costs pass through variably across formulation tiers, with cross-linked hyaluronic acid absorbing bioproduction volatility more directly than neuromodulator portfolios buffered by multi-thousand liter scale efficiencies. Pricing stratifies across premium, standard, and economy tiers based on G-prime elasticity calibration and FDA Center for Biologics Evaluation and Research approval status. Pricing pressure stems from biosimilar entry in botulinum toxin and Chinese hyaluronic acid raw material oversupply. Medical spa networks exhibit highest price sensitivity; academic hospital outpatient departments show lowest.
Supply Chain Analysis
Specialized fermentation workforce availability concentrates manufacturing gravity in Switzerland, Germany, and South Korea for botulinum toxin, while hyaluronic acid bioproduction clusters in Chinese and Japanese sodium hyaluronate hubs. Supply chains draw from porcine and avian tissue extraction, bacterial fermentation substrates, and cross-linking agent chemical synthesis. Single-source vulnerability pervades Chinese raw material concentration for Western formulators. Distribution runs through cold chain logistics networks with redundant temperature monitoring to satellite clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-filled syringe format standardization enables margin expansion through compounding elimination and liability transfer, while EU MDR compliance investments filter competition and consolidate shelf space for serialization-capable portfolios.
For Market Incumbents: Extend physician training network density into secondary German cities and Indian metropolitan corridors before regulatory harmonization completes. Defend against microcannula delivery specialists by integrating instrumentation portfolios through acquisition or partnership. Prioritize backward integration into sodium hyaluronate fermentation capacity to neutralize Chinese supply concentration risk. For New Entrants and Emerging Players: Begin with India's CDSCO streamlined import pathways for pre-filled formats, where compounded preparation reliance creates immediate substitution opportunity. Target anticoagulated patient populations excluded from needle-based protocols through microcannula specialization. Establish go-to-market through medical spa franchise standardization rather than independent clinic direct sales. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR serialization mandates exceed smaller formulator enterprise resource planning capabilities. Long-term viability favors portfolios with integrated dermatology channel control spanning prescription skincare through injectable delivery. Acquisition targets include microcannula delivery specialists and regional bioproduction assets. Monitor FDA real-world evidence guidance for extended-duration filler claims as inflection signal between hyaluronic acid and poly-L-lactic acid competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Microcannula Delivery System Development | Reduces vascular occlusion risk and expands anticoagulated patient eligibility in mid-face procedures. |
| Pre-Filled Syringe Format Conversion | Eliminates clinic-side compounding liability and enables manufacturer-controlled viscosity calibration. |
| EU MDR Serialization Infrastructure Investment | Forces traceability database compliance that filters out smaller formulators from European distribution. |
| Backward Integration into Fermentation Capacity | Captures sodium hyaluronate supply security and neutralizes Chinese bioproduction concentration risk. |
| Physician Training Network Expansion | Determines market access more than product differentiation in botulinum toxin and filler categories. |
Methodological Framework
Bottom-up medical spa and dermatology center procedure volume modeling reconciled against top-down bioproduction capacity and import tracking forms the analytical core of this study. Primary interviews with aesthetic clinic medical directors, pharmaceutical regulatory affairs specialists, GPO contracts managers, and cold chain logistics operators combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CDSCO import registration records, and customs trade data. Cross-referencing bottom-up demand signals against top-down supply registrations ensures triangulation integrity.
Input-output matrices map hyaluronic acid cross-linking reactor utilization, botulinum toxin fermentation batch yields, and microcannula import volumes against procedure frequency projections across the analysis window. Segmentation dimensions include product chemistry tier, delivery technology format, end-user facility licensing level, and application indication. CAGRs derive from elasticity-adjusted price trajectories and volume penetration curves. Forecast inputs incorporate EU MDR compliance cost pass-through and FDA dual Center review timeline variability.
Several conditions sit outside the modeled scope, including PMDA regulatory pathway divergence for Japan-specific biologic-device combinations and unforeseen hyaluronidase shortage events affecting reversal protocol availability. Forecasts reflect documented assumptions regarding physician training network expansion rates and cold chain infrastructure investment continuity. Material deviation in FDA real-world evidence requirements or Chinese sodium hyaluronate export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
Japan Hair Transplant Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market
Medical Aesthetics
Germany Hair Transplant Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
South Korea Hair Transplant Market