
 Global Medical Injection Molding Market | 2026-2036
Global Medical Injection Molding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Injection Molding Market Foresight
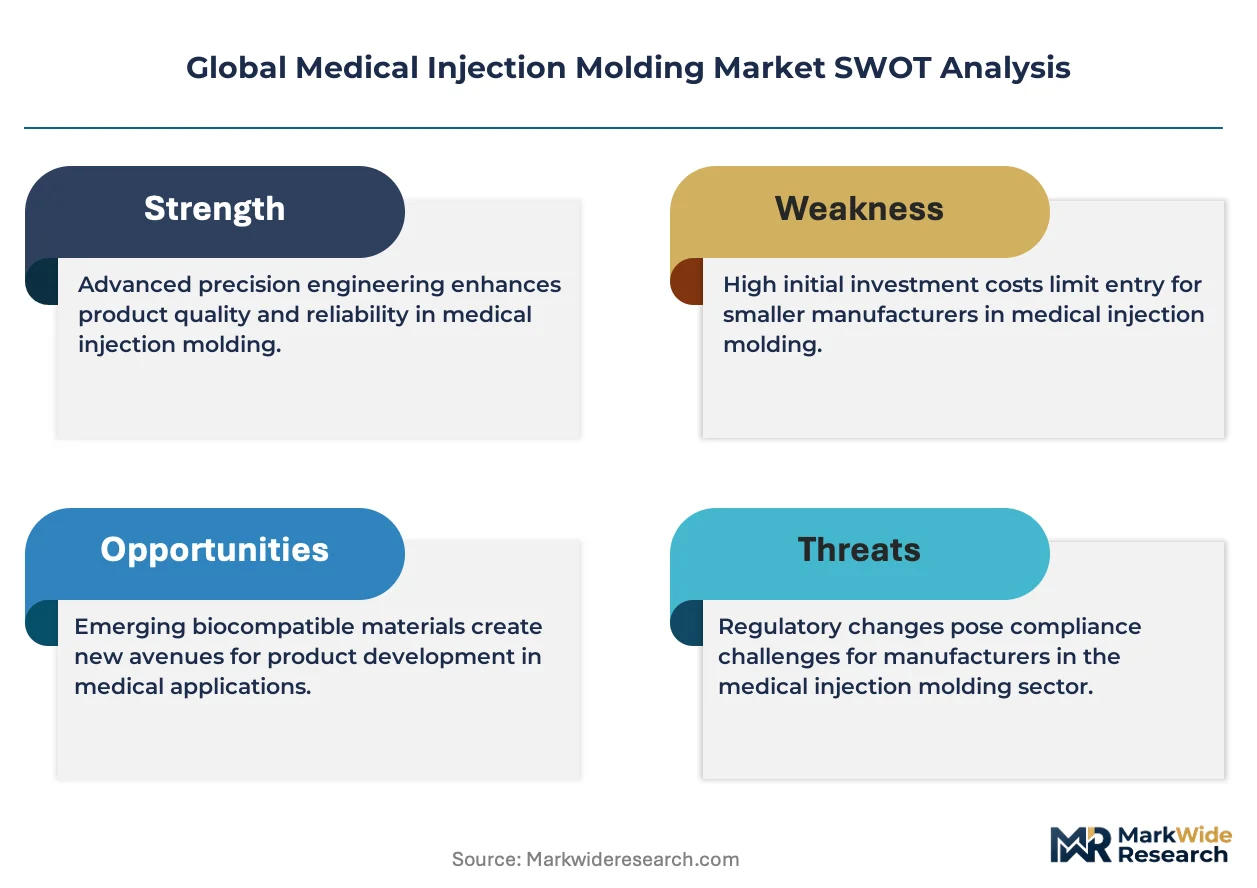
ISO 13485-grade cleanroom specifications are rotating through the supplier base as medical device OEMs raise incoming quality protocols. Tessy Plastics anchors its position through vertically integrated toolmaking and automated assembly. Röchling Medical specializes in high-performance polymer selection for long-term implantable devices. Spectrum Plastics Group extends its reach via geographic diversification across North American and European manufacturing sites.
Medical injection molding is the precision fabrication process wherein thermoplastic or elastomeric resins are heated, injected under pressure into precision-machined steel molds, and cooled to produce dimensionally stable components with tolerances often held to ±0.001 inches, serving primarily the sterile device and diagnostic industries. Syringes and infusion devices dominate volume throughput due to recurring hospital and home-care consumption, while micro molding captures disproportionate margin pools as minimally invasive surgical tools proliferate. Liquid silicone rubber injection is displacing thermoplastic alternatives in respiratory and sealing applications where biocompatibility and autoclavability are non-negotiable.
FDA's Quality System Regulation and the EU Medical Device Regulation enforce lot traceability, validation protocols, and post-market surveillance that filter out non-compliant molders. China's NMPA now mandates domestic clinical evidence for Class III device registrations, reshaping where multinational molders locate captive production. Japan's PMDA maintains stringent foreign manufacturer accreditation requirements that limit supplier turnover. Stakeholders must monitor how divergent sterilization validation standards across these jurisdictions affect tooling amortization and site qualification timelines.
Market Dynamics
Medical device OEMs are consolidating supplier panels around ISO 13485-certified molders with captive toolmaking and automated inspection, compressing qualified vendor pools while raising technical barriers for mid-tier competitors.
Growth Catalysts
- EU MDR lot traceability mandates:Device manufacturers must document material genealogy through molding operations, favoring molders with integrated ERP and serialization systems.
- Home-care infusion expansion:Disposable pump cartridges and wearable injector housings require high-volume precision molding with biocompatible resins.
- Silicone liquid injection molding:Respiratory device manufacturers are converting sealing components from thermoplastics to autoclavable LSR for improved biocompatibility profiles.
Market Restraints
- Medical-grade resin cost volatility:Specialized polymers such as PEEK and PSU face supply tightness from limited compounders in Germany and the United States.
- Tool steel lead times:Precision mold fabrication concentrates in Japanese and German machine shops with 16-24 week delivery schedules.
- Validation protocol rigidity:FDA process validation requirements lock molders into fixed cavity layouts, constraining flexibility for design iterations.
Strategic Opportunities
- India's Class III device manufacturing:CDSCO regulatory alignment with IMDRF standards is attracting diagnostic device assembly with local molding content.
- Micro molding for neuromodulation:Implantable pulse generator housings and lead connectors demand sub-gram precision with tight tolerances.
- Carbon-neutral polymer mandates:EU Green Deal procurement criteria are creating preference for molders with bio-based resin processing capabilities and renewable energy sourcing.
Industry Challenges
- Multi-cavity validation complexity:Qualifying 32-64 cavity molds for FDA submission requires extensive design of experiments and statistical process control documentation.
- Cleanroom technician scarcity:ISO Class 7 and 8 environments require specialized gowning and aseptic handling skills with limited training pipeline capacity.
- Legacy ERP integration:Molders with decades-old MRP systems face costly upgrades to meet OEM electronic data interchange and real-time traceability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Injection Molding Market |
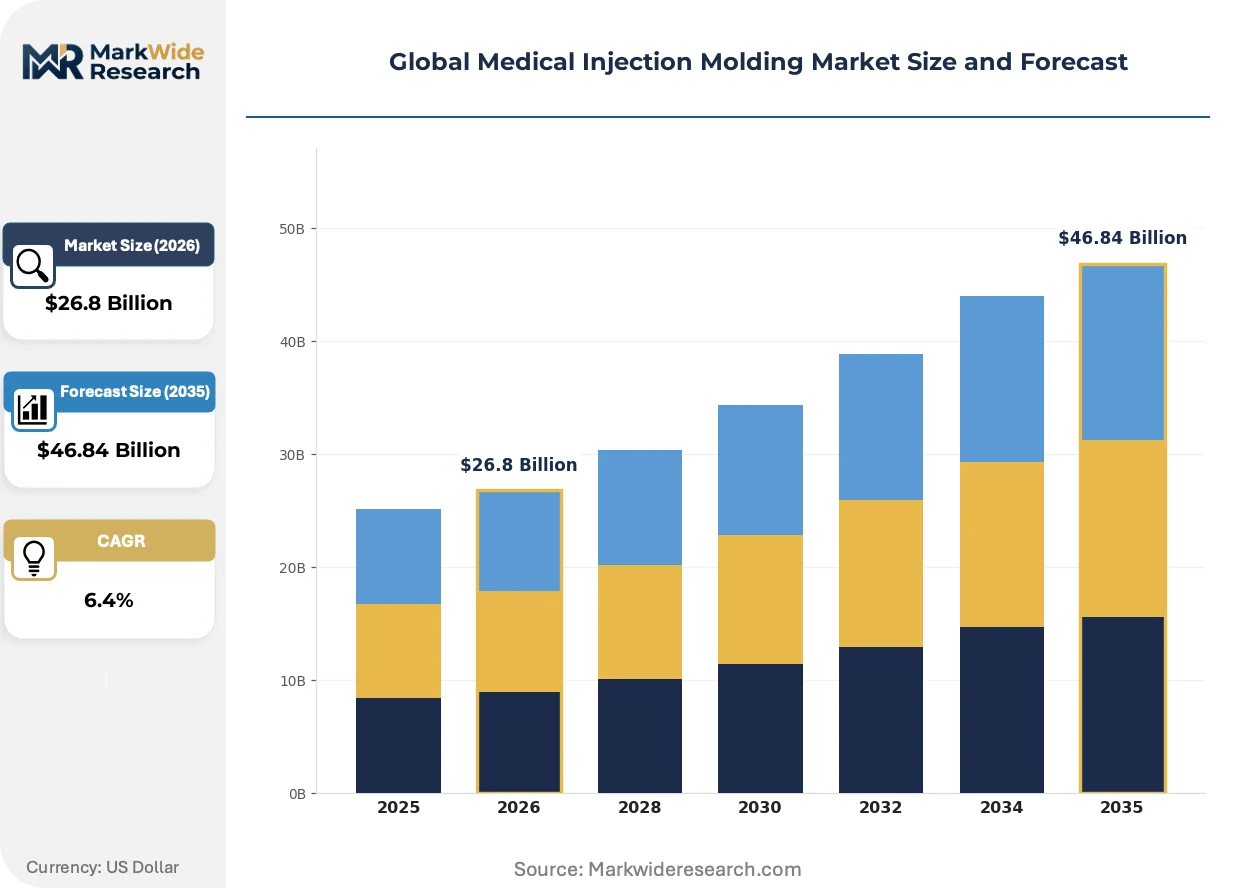
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $46.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Infusion Devices, Surgical Instruments, Diagnostic Components, Prosthetic Parts Technology: Thermoplastic Injection, Liquid Silicone Rubber Injection, Micro Molding, Multi-Shot Molding, Insert Molding Application: Drug Delivery, Catheters, Orthopedic Devices, Cardiovascular Devices, Dental Equipment End User: Medical Device Manufacturers, Pharmaceutical Companies, Research Laboratories, Ambulatory Surgical Centers, Diagnostic Clinics |
| Companies Covered | Proto Labs, C&J Industries, EVCO Plastics, Tessy Plastics, Biomerics, HTI Plastics, The Rodon Group, Spectrum Plastics Group, Röchling Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Injection Molding Market Shifts & Advancements
Automation and digital thread technologies are reconfiguring how medical molders validate processes, manage quality documentation, and interface with device OEM enterprise systems.
All-electric injection presses with integrated cavity pressure sensing and real-time SPC feedback are supplanting hydraulic machines in cleanroom environments. Cardiovascular device manufacturers specify electric molding for stent delivery system components where shot-to-shot consistency affects clinical outcomes. The shift is compressing process validation windows while raising capital intensity for molders serving Class III device segments.
China's NMPA now mandates domestic clinical evidence for Class III device registrations, compelling multinational device firms to establish captive molding operations or joint ventures with licensed Chinese molders. The regulation is redirecting investment toward Suzhou and Shenzhen medical device clusters. European and American molders with existing China footprints are expanding local toolmaking capabilities to meet NMPA site inspection requirements.
Hospital procurement consortia are consolidating purchasing of disposable infusion sets and syringes into multi-year sole-source agreements with molding-integrated device manufacturers. Traditional distribution through medical product wholesalers is contracting as IDNs negotiate direct supply relationships. The concentration is most pronounced in Germany's university hospital networks and United States-based GPOs serving acute care systems.
Global Medical Injection Molding Market Segmentation
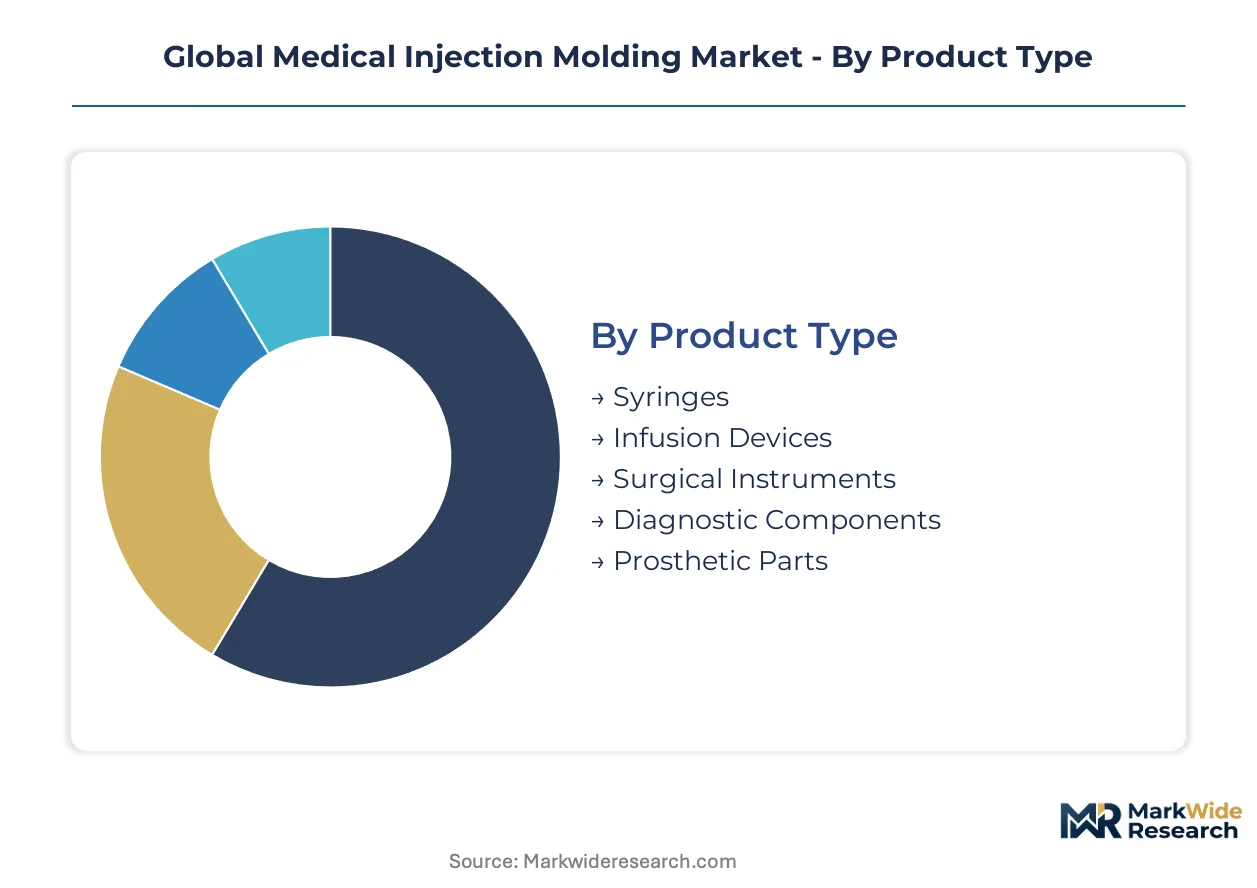
Medical injection molding segments fragment across precision requirements, biocompatibility grades, and regulatory validation intensity. Each category carries distinct margin profiles and capital barriers that reshape competitive positioning among molders serving device OEMs.
Product Type:
Liquid silicone rubber and bioabsorbable polymers exert substitution pressure on thermoplastic alternatives in sealing and short-term implant applications.
- Syringes:High-volume disposable barrels and plungers molded in polypropylene and cyclic olefin polymers dominate hospital procurement contracts. Demand concentrates in Germany and the United States where GPOs and university hospital networks consolidate purchasing into multi-year sole-source agreements with molding-integrated manufacturers.
- Infusion Devices:Pump cartridges, wearable injector housings, and IV set components require ISO 13485-certified cleanroom production with automated cavity pressure monitoring. Home-care expansion and ambulatory surgical center growth in China and India drive volume acceleration for disposable infusion platforms.
- Surgical Instruments:Scalpel handles, forceps grips, and retractor components molded in reinforced thermoplastics replace metal alternatives where weight reduction matters.
- Diagnostic Components:Microplates, cuvettes, and assay cartridges demand tight dimensional tolerances for optical clarity and reagent containment.
- Prosthetic Parts:Socket liners, knee housing components, and finger joint mechanisms utilize fiber-reinforced polymers for fatigue resistance.
Syringes retain volume leadership; infusion devices hold the steepest expansion curve.
Technology:
Capital intensity and validation protocol complexity stratify technology tiers, with electric press platforms commanding premium positioning over hydraulic alternatives.
- Thermoplastic Injection:Conventional polypropylene, polycarbonate, and PEEK processing remains the volume foundation across device categories. FDA process validation requirements for 32-64 cavity molds lock molders into fixed layouts, constraining flexibility for design iterations.
- Liquid Silicone Rubber Injection:Two-part platinum-cured LSR systems displace thermoplastic seals in respiratory masks, valve components, and implantable devices where autoclavability and biocompatibility are mandatory. EU MDR lot traceability mandates favor molders with integrated ERP and serialization systems for LSR batch genealogy.
- Micro Molding:Sub-gram precision for neuromodulation leads and stent delivery components captures disproportionate margin pools.
- Multi-Shot Molding:Hard-soft combinations for ergonomic surgical grips and drug-device combination products reduce assembly steps.
- Insert Molding:Metal and ceramic component encapsulation for electronic medical device housings and sensor packages.
Thermoplastic injection anchors volume throughput; micro molding delivers the steepest margin expansion.
Application:
Regulatory pathway intensity and sterilization validation requirements create distinct commercial profiles across therapeutic areas.
- Drug Delivery:Autoinjector housings, inhaler canisters, and transdermal patch components require combination product expertise bridging device and pharmaceutical regulations. China's NMPA domestic clinical evidence mandate for Class III registrations redirects investment toward Suzhou and Shenzhen captive molding operations.
- Catheters:Multi-lumen extrusion overmolding and hub assembly demand tight tolerances for flow dynamics and kink resistance. Cardiovascular and urological catheter manufacturers in Germany and the United States specify electric molding platforms for shot-to-shot consistency affecting clinical outcomes.
- Orthopedic Devices:Instrument handles, trial implants, and fixation housing components prioritize sterilization durability.
- Cardiovascular Devices:Stent delivery system components and pacemaker housings command the most stringent validation protocols.
- Dental Equipment:Impression trays, orthodontic brackets, and surgical guide components balance aesthetics with autoclave resistance.
Drug delivery retains volume leadership; cardiovascular devices hold the steepest regulatory barrier premium.
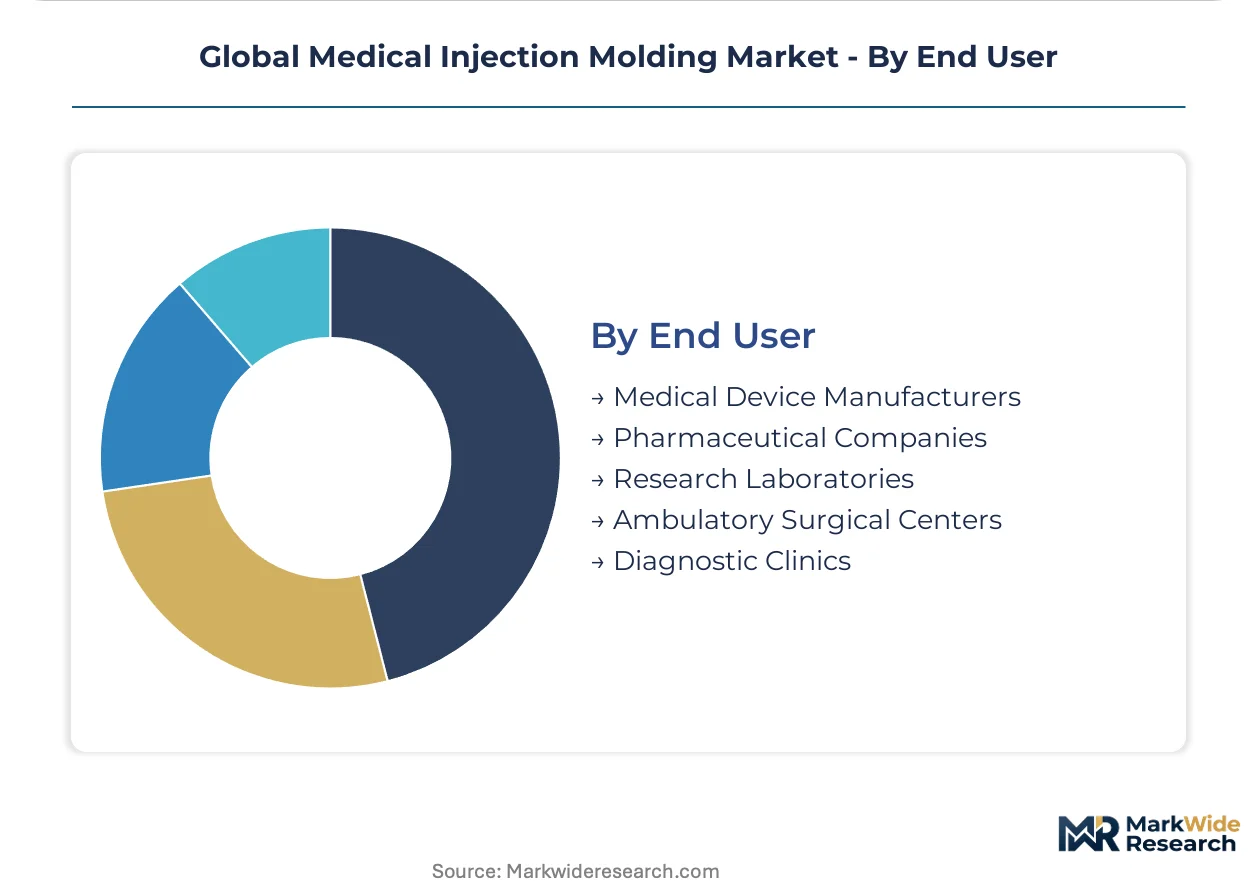
End User:
Procurement consolidation and in-sourcing decisions reshape demand concentration across customer categories.
- Medical Device Manufacturers:Large OEMs consolidate supplier panels around ISO 13485-certified molders with captive toolmaking and automated inspection, compressing qualified vendor pools. IDN direct contracting in the United States and Germany is contracting traditional distribution channels.
- Pharmaceutical Companies:Combination product divisions demand molders with drug-primary packaging expertise and FDA Type V DMFs for resin systems.
- Research Laboratories:Low-volume, high-mix prototyping and clinical trial supply requirements favor molders with rapid tooling capabilities.
- Ambulatory Surgical Centers:Cost-sensitive disposable instrument procurement drives standard-grade polymer specifications.
- Diagnostic Clinics:Point-of-care device housing and consumable demand scales with decentralized testing expansion.
Medical device manufacturers retain volume leadership; pharmaceutical companies hold the steepest compliance-driven premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German molders export precision components to United States cardiovascular device manufacturers, establishing the primary transatlantic trade corridor in medical-grade polymer fabrication.
United States
Hospital procurement consortia and integrated delivery networks consolidate disposable infusion set purchasing into multi-year sole-source agreements. FDA Quality System Regulation enforces lot traceability and process validation that filter out non-compliant molders. Minneapolis and Boston medical device clusters drive demand for micro-molded neuromodulation components.
Germany
University hospital networks concentrate purchasing power for syringes and surgical instruments. EU Medical Device Regulation tightens material genealogy documentation through molding operations. Freiburg and Stuttgart host specialized molders serving orthopedic and cardiovascular OEMs with captive toolmaking capabilities.
China
Home-care infusion expansion and ambulatory surgical center growth accelerate disposable pump cartridge demand. NMPA mandates domestic clinical evidence for Class III device registrations, redirecting multinational investment toward Suzhou and Shenzhen captive molding operations with local toolmaking.
Japan
PMDA maintains stringent foreign manufacturer accreditation requirements that limit supplier turnover in implantable device segments. Tokyo and Osaka medical device clusters specify electric molding platforms for stent delivery system components requiring shot-to-shot consistency.
India
CDSCO regulatory alignment with IMDRF standards attracts diagnostic device assembly with local molding content. Maharashtra and Gujarat pharmaceutical manufacturing corridors expand Class III device production with integrated polymer processing capabilities.
Global Medical Injection Molding Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where ISO 13485-certified molders with captive toolmaking capture premium positioning while mid-tier competitors face technical barriers. The vendor base concentrates around three archetypes: vertically integrated specialists with automated assembly, high-performance polymer selectors for long-term implants, and geographically diversified multi-site operators. Consolidation proceeds through supplier panel compression by medical device OEMs and strategic capacity expansion in China to satisfy NMPA site inspection requirements.
Among North American fabricators, Tessy Plastics and Spectrum Plastics Group exemplify the vertically integrated archetype with multi-continental manufacturing footprints. Röchling Medical represents the polymer specialization tier with European-centered operations. These three occupy positions across the premium-to-standard spectrum, anchoring competitive dynamics in distinct capability zones rather than direct segment overlap.
| Leading Market Players |
|---|
| Proto Labs |
| C&J Industries |
| EVCO Plastics |
| Tessy Plastics |
| Biomerics |
| HTI Plastics |
| The Rodon Group |
| Spectrum Plastics Group |
| Röchling Medical |
| Others |
Supply & Pricing Matrix
Liquid silicone rubber substitution for thermoplastic seals simultaneously concentrates resin procurement toward German and Japanese compounders while compressing margins on commodity-grade thermoplastic molding. This material transition rewards molders with backward integration into LSR compounding and punishes those tethered to volatile polypropylene spot markets.
Pricing Analysis
Electric press generation gaps separate pricing tiers, with all-electric platforms commanding premiums over hydraulic alternatives and next-generation servo-hydraulic hybrids occupying a narrowing mid-market. Three-tier pricing structure across ISO 13485-certified premium, standard medical-grade, and economy non-certified tiers reflects validation depth and cleanroom classification. Cost compression in standard thermoplastic syringe molding intensifies as hospital GPOs consolidate procurement into sole-source contracts. Ambulatory surgical centers exhibit highest price sensitivity; cardiovascular device OEMs show least sensitivity due to clinical outcome liability.
Supply Chain Analysis
Sixteen-to-twenty-four-week tool steel lead times from Japanese and German machine shops strain inventory buffers for multi-cavity mold qualification timelines. Precision mold fabrication concentrates in Germany, Japan, and Switzerland; medical-grade resin compounding clusters in the United States and Germany. Supply chain risk centers on single-source vulnerability for PEEK and PSU polymers from limited compounders. Distribution runs through direct OEM contracts rather than distributor networks, with IDN procurement consortia bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence across FDA, EU MDR, and NMPA jurisdictions fragments compliance requirements, creating specialization niches for regionally anchored molders with captive regulatory expertise.
For Market Incumbents: Consolidate supplier panel positions by acquiring captive toolmaking capabilities in Suzhou and Shenzhen to satisfy NMPA site inspection mandates. Deepen ISO 13485 certification moats through automated cavity pressure monitoring investments that mid-tier competitors cannot replicate. Threat substitution from LSR-capable specialists demands polymer processing diversification beyond commodity thermoplastics. For New Entrants and Emerging Players: Anchor in India's CDSCO-aligned Class III diagnostic device corridor, where local molding content requirements outpace qualified domestic supply. Neuromodulation micro-molding for implantable pulse generators offers the most penetrable premium segment given tolerance requirements and limited qualified vendors. Go-to-market angle: rapid clinical trial supply partnerships with research laboratories seeking low-volume, high-mix prototyping capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed molders lacking electric press fleets or China regulatory footprints. Five-to-ten-year viability hinges on NMPA captive production positioning and LSR processing capabilities. Signal to watch: OEM supplier panel compression announcements indicating acquisition-ready mid-tier targets losing qualification status.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO Class 7 certification unlocks cardiovascular and implantable device contracts with Minneapolis OEMs. |
| Backward Integration into Toolmaking | Captive mold fabrication compresses NMPA qualification timelines for Suzhou captive operations. |
| LSR Processing Capability Addition | Platinum-cured silicone lines access respiratory device contracts requiring autoclavable sealing components. |
| Multi-Site Geographic Diversification | North America-Europe-Asia manufacturing triad hedges tariff exposure and regulatory jurisdiction risk. |
| ERP and Serialization System Upgrade | Integrated lot traceability satisfies EU MDR material genealogy mandates for device OEM audits. |
Research Methodology
The analysis maps syringe, infusion device, surgical instrument, diagnostic component, and prosthetic part sub-sectors, each validated through injection molding operations directors, medical device OEM procurement managers, GPO contracts specialists, and cleanroom quality engineers. Primary interview insights triangulate against FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and hospital procurement contract disclosures. Bottom-up capacity estimates from molder facility assessments reconcile with top-down device OEM spend allocation models.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology tier, application area, end-user category, and regional regulatory cluster. CAGRs derive from installed press capacity utilization trajectories, resin price elasticity assumptions, and device OEM outsourcing ratio trends. Industry-specific inputs incorporate multi-cavity validation protocol timelines and NMPA site inspection approval rates.
Material uncertainties — regulatory timeline delays, resin supply disruptions, and sterilization validation standard divergence — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from jurisdiction-specific policy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Organ Preservation Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Microdebrider Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Gamma Knife Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Surgical Mesh Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Engine-Driven Endodontic File Market