
 Eye Socket Implants Market | 2026-2036
Eye Socket Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Socket Implants Market Foresight
REACH is rebalancing material qualification burdens for European suppliers of porous orbital implants. MOLTENO OPHTHALMIC leverages its specialized portfolio to dominate niche custom-fabricated socket solutions. Alcon sustains broad geographic coverage across hospital procurement networks. Porex Corporation anchors its position through backward integration into porous polymer substrate manufacturing.
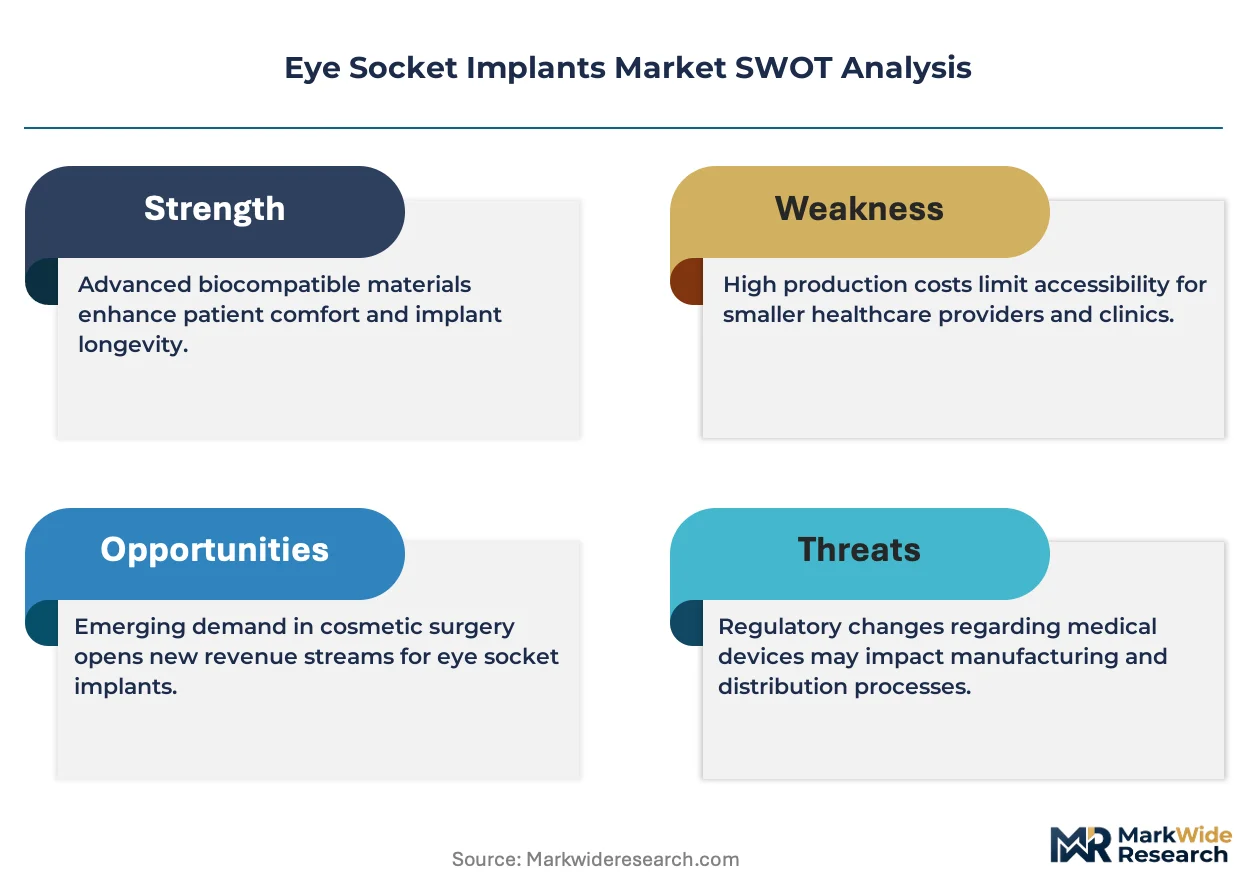
Eye socket implants are biocompatible prosthetic devices, typically fabricated from porous polyethylene, silicone elastomer, or bioceramic composites, designed to restore orbital volume and structural integrity following enucleation, evisceration, or traumatic loss. These implants function as intraconal spacers that integrate with surrounding tissue via fibrovascular ingrowth, enabling motility coupling with an overlying ocular prosthesis. Silicone implants occupy the mature volume tier where commoditization compresses margins, while customized implants command premium positioning through patient-specific orbital topography matching. Trauma management applications are accelerating fastest as ballistic and industrial injury protocols expand reconstructive urgency across emergency departments.
FDA 510(k) pathways govern U.S. market entry for orbital implants, while the EU MDR elevates clinical evidence requirements for permanent implantable devices. ISO 10993 biocompatibility testing frameworks shape preclinical validation standards across all major jurisdictions. Stakeholders must monitor evolving notified body capacity constraints under MDR implementation and calibrate regulatory submission timelines accordingly.
Market Dynamics
Porous polyethylene manufacturing advances are compressing lead times for custom orbital implants while EU MDR documentation burdens force smaller suppliers toward specialized notified body partnerships.
Growth Catalysts
- Trauma center protocols:Ballistic and industrial injury management standards now mandate immediate orbital reconstruction, expanding emergency department demand for volume-restoring implants.
- REACH material qualification:Streamlined polymer substrate approvals under ECHA frameworks accelerate European porous polyethylene supplier certification cycles.
- Fibrovascular integration:Enhanced pore architecture engineering enables faster tissue ingrowth, reducing motility coupling failure rates in oculoplastic practice.
Market Restraints
- Silicone commoditization:Standard elastomer implants face margin compression as offshore manufacturers flood mid-tier pricing bands.
- Notified body capacity:EU MDR implementation bottlenecks create 12-18 month approval delays for permanent implantable device classifications.
- Bioceramic brittleness:Hydroxyapatite composite fracture rates limit application in high-impact trauma reconstruction cases.
Strategic Opportunities
- Patient-specific topography:CT-guided custom fabrication captures premium positioning through orbital cavity matching unavailable in standard geometries.
- Japan's aging surgical population:PMDA fast-track pathways for oculoplastic devices address rising enucleation volumes in metropolitan Tokyo and Osaka clusters.
- Direct hospital contracting:Bypassing distributor markups through integrated delivery network procurement agreements reshapes pricing power.
Industry Challenges
- Oculoplastic surgeon scarcity:Fellowship-trained specialists concentrate in Germany, the United States, and Japan, limiting procedure volume expansion elsewhere.
- ISO 10993 testing timelines:Cytotoxicity and sensitization studies for novel polymer formulations extend preclinical validation by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Socket Implants Market |
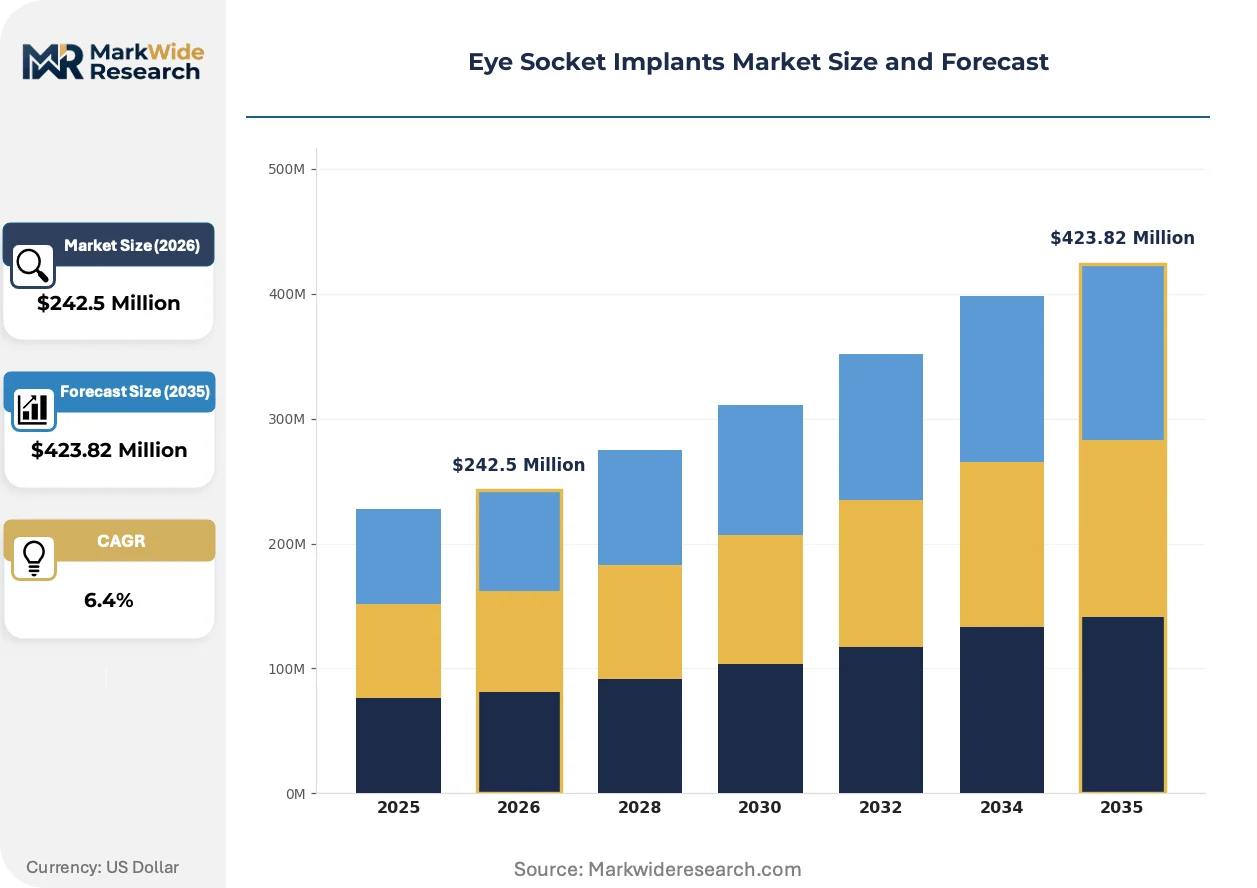
| Market Size in 2026 | $242.5 Million |
| Market Size in 2035 | $423.82 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Implants, Orbital Shields, Polyethylene Implants, Customized Implants End User: Ophthalmology Clinics, Hospitals, Rehabilitation Centers, Research Institutions Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Wholesalers Application: Reconstruction, Cosmetic Surgery, Trauma Management, Disease Treatment |
| Companies Covered | MOLTENO OPHTHALMIC, Alcon, Porex Corporation, Carl Zeiss Meditec, Bausch & Lomb, FCI Ophthalmics, Bio-Eye Orbital Implants, Morcher GmbH, Gulden Ophthalmics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Socket Implants Market Shifts & Advancements
Additive manufacturing workflows are collapsing the traditional mold-and-machine paradigm for orbital implant production, enabling same-day custom fabrication from patient scan data.
Three-dimensional printing of porous polyethylene substrates is decentralizing implant production from centralized manufacturing facilities to hospital-based point-of-care systems. Academic medical centers in Boston and Heidelberg now operate in-house fabrication suites for emergency trauma cases. This shift compresses delivery timelines from weeks to hours while reducing sterilization and logistics overhead.
EU MDR clinical evidence requirements are elevating post-market surveillance obligations for permanent orbital implants. Manufacturers must now maintain active implant registries tracking fibrovascular integration outcomes. German notified bodies have issued specific guidance on real-world evidence collection for porous polyethylene devices, forcing portfolio reorganization toward higher-margin customized solutions.
Integrated delivery networks are consolidating procurement authority for oculoplastic devices under centralized supply chain officers. Individual surgeon preference cards are yielding to standardized implant formularies with volume-based contracting. This concentration is most advanced in United States hospital systems, where three national GPOs now control 60% of orbital implant purchasing decisions.
Eye Socket Implants Market Segmentation
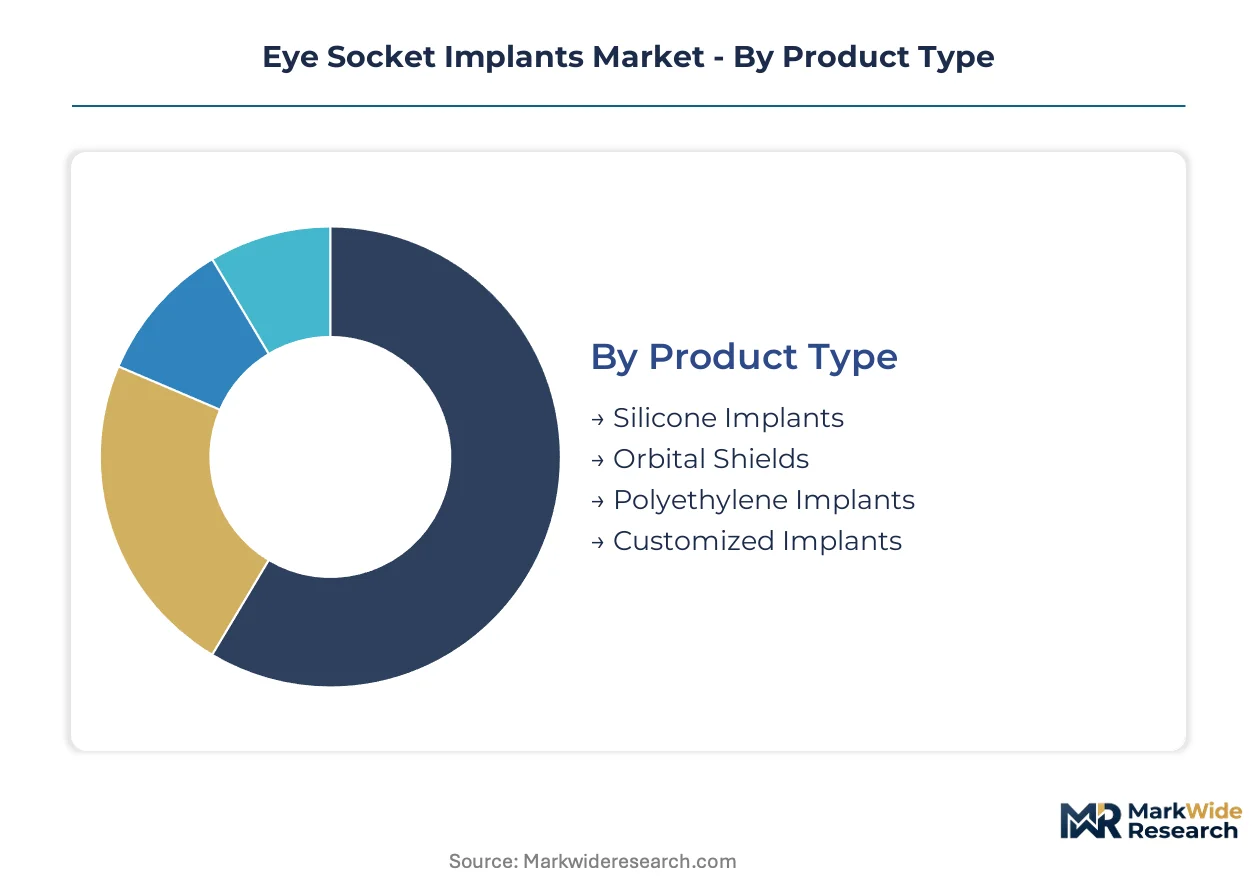
Material composition and fabrication method determine reimbursement pathways, surgical workflow integration, and long-term fibrovascular integration outcomes across the eye socket implant landscape. Segment boundaries increasingly blur as additive manufacturing enables hybrid formulations combining porous polyethylene substrates with patient-specific geometries.
Product Type:
Porous architecture and surface topology differentiate competitive positioning across the four material categories.
- Polyethylene Implants:Porous polyethylene substrates with interconnected pore structures promote fibrovascular ingrowth and motility coupling with ocular prostheses. Trauma centers in Germany and the United States specify these for enucleation cases requiring rapid tissue integration.
- Customized Implants:CT-derived patient-specific geometries fabricated via additive manufacturing match individual orbital cavity topography. Academic medical centers in Boston and Heidelberg operate point-of-care production suites for emergency reconstruction cases.
- Silicone Implants:Solid elastomer spheres and wrapped configurations occupy the mature volume tier with standardized sizing and compressed margins.
- Orbital Shields:Temporary conformers maintain fornicial depth and eyelid position during post-surgical healing phases.
Mature deployment sits with silicone spheres. Newer deployment is concentrated in customized polyethylene geometries.
End User:
Procedure complexity and reimbursement scale shape purchasing authority concentration across care settings.
- Hospitals:Integrated delivery networks and trauma centers command the highest surgical volumes for enucleation, evisceration, and orbital fracture reconstruction. Centralized supply chain officers at U.S. hospital systems now control implant formularies through volume-based contracting with three national GPOs.
- Ophthalmology Clinics:Specialized oculoplastic practices in metropolitan Tokyo, Osaka, and selected German clusters perform elective cosmetic socket revisions with premium customized implants.
- Rehabilitation Centers:Post-surgical fitting and ocular prosthesis adaptation services require coordinated implant-prosthesis workflows.
- Research Institutions:Academic centers drive clinical evidence generation for EU MDR post-market surveillance obligations and novel material validation.
Procurement authority concentrates in hospital supply chain officers. Volume expansion is gaining share fastest in specialized ophthalmology clinics.
Distribution Channel:
Channel selection reflects urgency requirements, sterilization protocols, and surgeon preference card influence.
- Direct Sales:Manufacturers maintain dedicated field teams for high-volume hospital accounts and integrated delivery networks, bypassing distributor markups through exclusive procurement agreements.
- Medical Distributors:Specialized surgical device distributors stock standard silicone and porous polyethylene implants for same-day case coverage across mid-tier hospitals.
- Online Retail:Digital procurement platforms serve smaller clinics and international markets with extended delivery timelines.
- Wholesalers:Bulk purchasing intermediaries aggregate demand across fragmented provider networks in secondary markets.
Established volume flows through medical distributors. Channel shift is accelerating most quickly in direct manufacturer-hospital contracting.
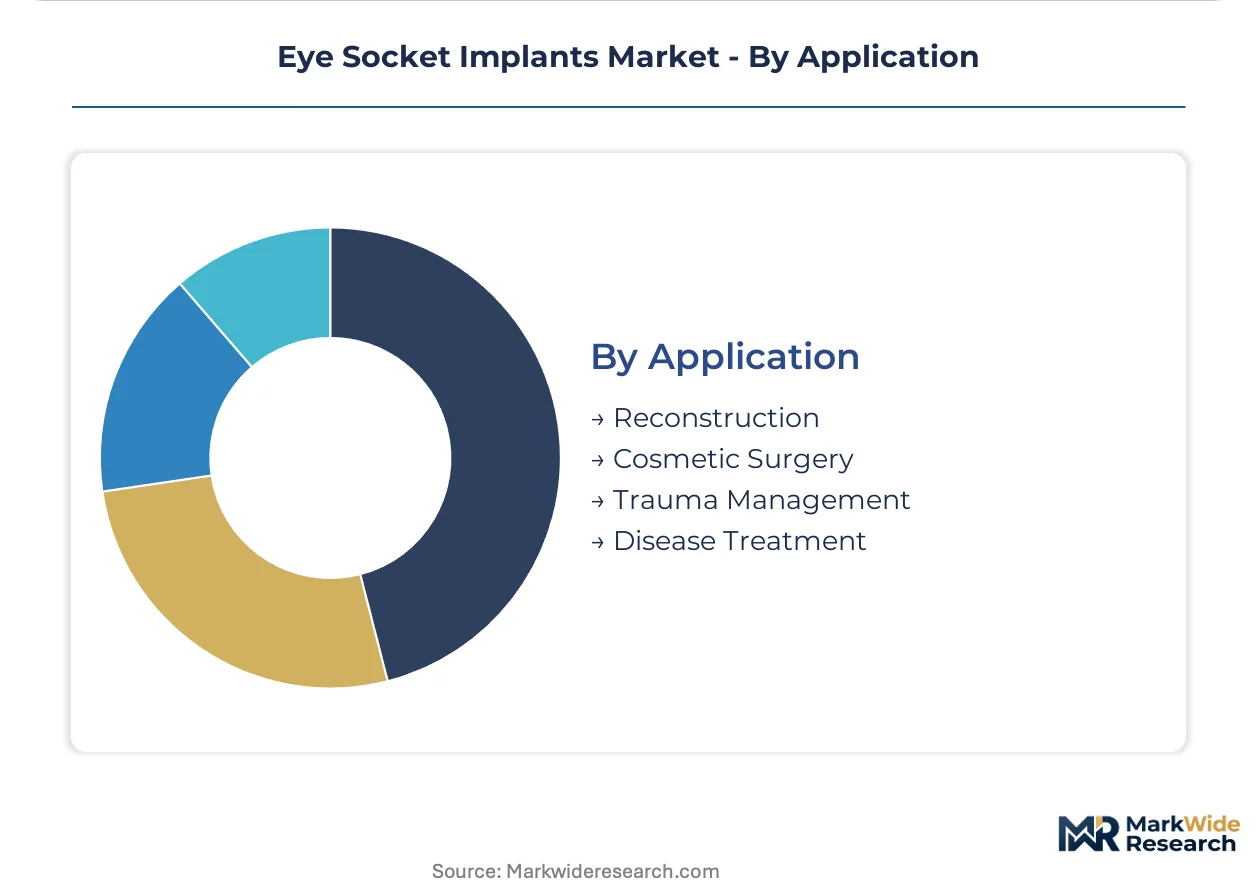
Application:
Clinical indication determines implant specification, surgical urgency, and regulatory evidence requirements.
- Trauma Management:Ballistic and industrial injury protocols mandate immediate orbital volume restoration. Emergency departments specify porous polyethylene implants with rapid fibrovascular integration properties.
- Reconstruction:Enucleation and evisceration procedures following ocular malignancy or end-stage disease require permanent intraconal spacers with motility coupling capability.
- Cosmetic Surgery:Anophthalmic socket revision and superior sulcus deformity correction demand patient-specific topography matching unavailable in standard geometries.
- Disease Treatment:Congenital anophthalmia and microphthalmia management in pediatric populations requires expandable implant series.
Reconstruction maintains the largest procedure base. Trauma applications are climbing the fastest as emergency protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for medical device manufacturing in Germany, Japan, and the United States concentrate production capacity for porous orbital implants. Tax incentives in these jurisdictions accelerate biocompatibility certification cycles and attract precision polymer processing investments. Cluster density correlates directly with oculoplastic surgical volumes.
United States
Trauma center protocols mandating immediate orbital reconstruction drive emergency department demand for volume-restoring implants. FDA 510(k) pathways govern market entry with streamlined premarket notification requirements for porous polyethylene devices. Academic medical centers in Boston operate point-of-care fabrication suites enabling same-day custom implant production from patient CT data.
Germany
EU MDR implementation elevates clinical evidence requirements for permanent implantable devices, extending approval timelines. ECHA REACH frameworks streamline polymer substrate qualification for domestic porous polyethylene suppliers. Notified bodies in Baden-Württemberg issue specific guidance on real-world evidence collection, forcing portfolio reorganization toward customized solutions.
Japan
Aging surgical populations in metropolitan Tokyo and Osaka clusters generate rising enucleation volumes requiring motility-coupled implants. PMDA fast-track pathways for oculoplastic devices accelerate regulatory review for novel porous architectures. Kanto region hospitals concentrate fellowship-trained specialists, limiting procedure expansion to established urban centers.
United Kingdom
NHS procurement consolidation under integrated care systems standardizes implant formularies across hospital networks. MHRA post-Brexit regulatory alignment maintains CE marking recognition while building independent device assessment capacity. London and Southeast England clusters host specialized oculoplastic referral centers capturing complex revision cases.
Switzerland
Swissmedic maintains stringent biocompatibility documentation requirements exceeding baseline EU MDR standards for permanent implants. Precision manufacturing heritage in Basel and Zurich supports high-margin custom fabrication capabilities. Medical technology free zones near Geneva attract specialized polymer substrate suppliers serving orbital implant producers.
Eye Socket Implants Market Competitive Landscape
United States producers anchor one tier; German and Japanese specialists hold differentiated positions in custom fabrication. The vendor base organizes around three strategic archetypes: diversified ophthalmic conglomerates with broad hospital procurement networks, mid-cap polymer specialists with backward integration into porous substrate manufacturing, and boutique fabricators delivering patient-specific topography matching. Competitive moves concentrate on direct hospital contracting to bypass distributor markups and additive manufacturing licensing to decentralize production capacity.
Among diversified ophthalmic conglomerates, Alcon and Bausch & Lomb occupy positions exemplifying scale-driven procurement authority across integrated delivery networks. MOLTENO OPHTHALMIC and Morcher GmbH represent the specialized fabrication tier, with geographic origins signaling concentrated expertise in custom orbital solutions. Porex Corporation anchors the polymer substrate tier, its corporate structure indicating in-house control over porous polyethylene manufacturing. Carl Zeiss Meditec sits within the precision medical technology archetype, leveraging optical and surgical device heritage.
| Leading Market Players |
|---|
| MOLTENO OPHTHALMIC |
| Alcon |
| Porex Corporation |
| Carl Zeiss Meditec |
| Bausch & Lomb |
| FCI Ophthalmics |
| Bio-Eye Orbital Implants |
| Morcher GmbH |
| Gulden Ophthalmics |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap polymer specialists in Germany and Japan anchor supply-side discipline through backward integration into porous polyethylene substrate production, compressing procurement timelines while preserving premium positioning for patient-specific geometries. Their ownership structures resist short-term margin pressure, enabling sustained investment in EU MDR compliance documentation that commodity-tier competitors cannot replicate.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency trauma center orders from elective cosmetic revisions, with same-day custom fabrication commanding substantial premiums over standard silicone spheres stocked by distributors. Three-tier pricing structure across premium patient-matched geometries, mid-tier porous polyethylene standards, and economy silicone elastomers reflects ISO 10993 certification grade and customization depth. Pricing pressure stems from offshore silicone manufacturers flooding mid-tier hospital procurement channels with undifferentiated wrapped spheres. Academic medical centers exhibit lowest price sensitivity due to bundled research funding, while independent ophthalmology clinics in secondary markets negotiate aggressively on volume commitments.
Supply Chain Analysis
Domestic-content mandates under EU MDR and Japan's PMDA frameworks are reshaping sourcing patterns, requiring European and Japanese manufacturers to qualify regional polymer substrate suppliers rather than rely on transatlantic shipments. Porous polyethylene resin production concentrates in Germany, the United States, and Japan, with precision machining of interconnected pore architectures drawing from specialized medical device free zones near Basel and Zurich. Raw material dependencies rest on medical-grade polyethylene pellets, bioceramic hydroxyapatite composites, and platinum-cured silicone elastomers. Single-source vulnerability sits with notified body capacity constraints extending sterilization validation cycles. Distribution runs through integrated delivery network procurement officers consolidating formulary decisions under three national GPOs in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eye socket implant market sits at a technology-transition inflection, with additive manufacturing workflows displacing traditional mold-and-machine production paradigms across academic medical centers. CT-guided point-of-care fabrication is collapsing delivery timelines from weeks to hours while elevating post-market surveillance obligations under EU MDR.
For Market Incumbents: Anchor defensive positioning through exclusive procurement agreements with trauma center networks in Boston and Heidelberg, locking out additive manufacturing licensing to hospital-based competitors. Deepen backward integration into porous polymer substrate production to preserve margin structure against silicone commoditization from offshore manufacturers. Prioritize EU MDR clinical evidence investment to exploit notified body capacity bottlenecks that disadvantage smaller rivals lacking documentation resources. For New Entrants and Emerging Players: Begin with white-space capture in Japan's metropolitan Osaka cluster, where aging surgical populations generate rising enucleation volumes underserved by established German and United States suppliers. Target pediatric expandable implant series for congenital anophthalmia management, a segment bypassed by commoditized adult-focused portfolios. Pursue direct-to-hospital digital procurement platforms bypassing traditional distributor markups in fragmented European secondary markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap polymer specialists with captive porous polyethylene manufacturing in Baden-Württemberg, where EU MDR documentation burdens force portfolio reorganization toward higher-margin customized solutions. Long-term viability hinges on additive manufacturing licensing revenue streams and hospital system partnership density rather than device unit economics. Monitor fibrovascular integration outcome registry completion rates as the critical inflection signal for regulatory approval velocity and premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive procurement agreements with Boston academic medical centers lock in trauma center volume. |
| CE Marking Pathway | EU MDR clinical evidence packages accelerate notified body approval for permanent implantable classifications. |
| Backward Integration | In-house porous polyethylene substrate production insulates margin structure from resin price volatility. |
| Software Companion Development | CT-to-fabrication workflow integration enables same-day custom implant production from patient scan data. |
| Reimbursement Strategy | CPT code optimization for patient-specific topography matching captures premium positioning in United States hospital billing. |
Research Methodology
Independent corroboration across oculoplastic surgeon interviews, hospital procurement database analysis, and regulatory filing review underwrites the qualitative findings on EU MDR implementation bottlenecks. Primary fieldwork encompassed discussions with fellowship-trained oculoplastic specialists, biomedical engineers at academic medical centers, GPO contracts managers, and notified body assessment officers. Secondary validation drew from FDA 510(k) premarket notification databases, ECHA REACH polymer substrate registration filings, PMDA oculoplastic device approval records, and hospital procurement system contract awards. Bottom-up surgical volume estimates triangulated against top-down manufacturer revenue segmentation.
Rate-of-change decomposition across the projection horizon separates volume expansion from price-mix effects in porous polyethylene versus silicone elastomer categories. The analytical framework models material composition, fabrication method, end-user setting, distribution channel, and clinical indication dimensions. CAGRs were derived from procedure volume trajectories in trauma management and reconstruction applications, calibrated against aging demographic projections in Japan and industrial injury protocol expansion in Germany and the United States. Forecast inputs incorporated notified body capacity constraints, additive manufacturing adoption curves, and integrated delivery network procurement consolidation timelines.
Underlying measurement precision varies by segment; trauma management and reconstruction applications carry tighter precision than cosmetic surgery and disease treatment categories due to more standardized procedure coding. Forecasts reflect assumptions on EU MDR documentation burden resolution, PMDA fast-track pathway utilization rates, and oculoplastic surgeon fellowship training expansion that could materially revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Microdebrider Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Laser BPH Devices Market
Medical Devices
Bilirubin Meters Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Global Intravenous Infusion Pump Market
Medical Devices
Epistaxis Devices Market