
 Transcranial Doppler Devices Market | 2026-2036
Transcranial Doppler Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Transcranial Doppler Devices Market Analytics
A shortage of certified neurosonographers is unwinding installation timelines at stroke centers across multiple countries. GE Healthcare leverages its imaging ecosystem to bundle Doppler systems with CT and MRI workflows. Koninklijke Philips sustains channel dominance through long-term service contracts with European hospital networks. Nihon Kohden Corporation anchors its position in Asia-Pacific through localized training academies for technicians.
Transcranial Doppler devices emit pulsed or continuous ultrasonic waves through the temporal bone to measure blood velocity in the basal cerebral arteries, typically operating at 2 MHz frequency for optimal cranial penetration. Portable devices command the largest revenue pool due to emergency department deployment and intraoperative monitoring needs, while wearable devices represent the fastest-expanding category as ambulatory stroke risk stratification gains clinical traction. Pulsed wave Doppler technology leads in installed base but advanced imaging integration is capturing premium margin pools through 3D flow reconstruction capabilities.
FDA 510(k) premarket notification and EU MDR Class IIa requirements shape device design standards, software validation protocols, and post-market surveillance obligations for manufacturers. The EPA regulates disposal of ultrasound gel and electronic components, adding compliance layers to product lifecycle management. Stakeholders must monitor reimbursement coding changes for transcranial Doppler procedures across Medicare, NHS England, and Japan's MHLW to anticipate volume shifts in hospital procurement cycles.
Market Dynamics
The transcranial Doppler devices market is experiencing structural pressure from the convergence of portable diagnostics and ambulatory stroke surveillance, compressing traditional hospital-centric procurement cycles while elevating software validation requirements under tightened FDA and EU MDR pathways.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States are expanding national stroke surveillance programs that mandate cerebrovascular monitoring in emergency departments and post-operative units.
- EU MDR Class IIa requirements:Stricter performance benchmarks for transcranial Doppler devices are accelerating replacement cycles for legacy equipment across European hospital networks.
- Wearable form factor innovation:Ambulatory stroke risk stratification is gaining clinical traction through continuous monitoring capabilities that extend beyond acute care settings.
Market Restraints
- Input cost volatility:Piezoelectric crystal supply chains concentrate in East Asian manufacturing hubs, exposing device margins to raw material price swings and logistics disruptions.
- Technical penetration barriers:The temporal bone's anatomical variability limits ultrasonic wave transmission in approximately fifteen percent of elderly patients, constraining addressable populations.
- Substitution pressure:CT angiography and MR angiography systems are capturing diagnostic workflows where comprehensive anatomical imaging supersedes velocity-based functional assessment.
Strategic Opportunities
- Underpenetrated rural networks:India's tier-two and tier-three cities lack certified neurosonographers, creating whitespace for telemedicine-integrated portable Doppler deployments.
- Technology convergence:Artificial intelligence algorithms paired with 2 MHz pulsed wave Doppler are enabling automated emboli detection without specialist interpretation.
- Regulatory tailwind:Japan's MHLW reimbursement coding revisions for transcranial Doppler procedures are expanding eligible procedure volumes in stroke prevention protocols.
Industry Challenges
- Certified neurosonographer scarcity:Training pipeline bottlenecks are extending installation timelines at stroke centers across the United States, Germany, and Japan.
- FDA 510(k) software validation:Computational fluid dynamics integration and 3D flow reconstruction capabilities are prolonging premarket notification timelines for advanced imaging systems.
- Legacy EMR integration:Proprietary data formats from established device manufacturers are creating interoperability friction with hospital information systems during procurement evaluations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcranial Doppler Devices Market |
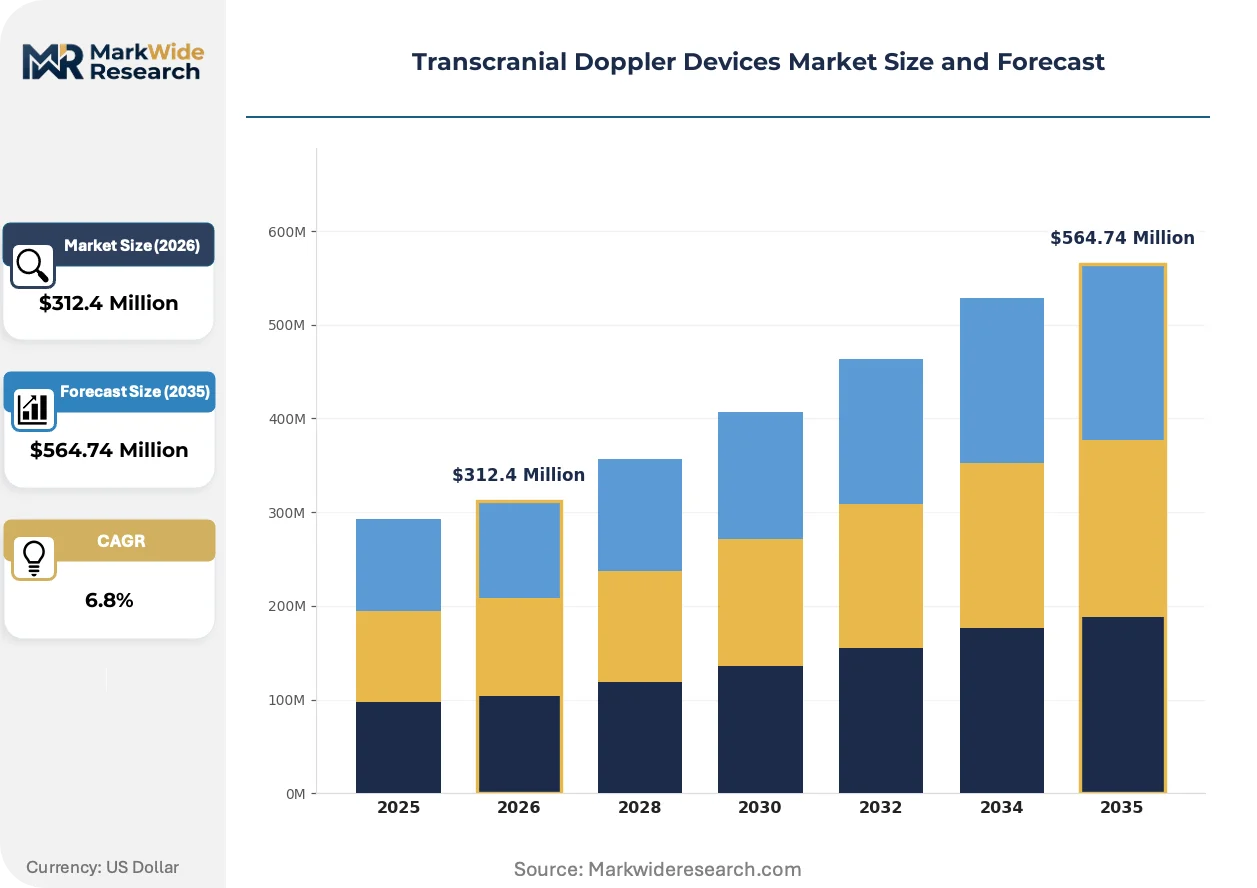
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Handheld Devices, Fixed Devices, Wearable Devices Technology: Pulsed Wave Doppler, Continuous Wave Doppler, Transient Technology, Advanced Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Rehabilitation Centers Application: Stroke Detection, Cerebral Blood Flow Monitoring, Vascular Assessment, Neurological Research |
| Companies Covered | GE Healthcare, Koninklijke Philips, Mindray Medical International, Nihon Kohden Corporation, Compumedics Limited, Natus Medical Incorporated, Atys Medical, Viasonix, Rimed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcranial Doppler Devices Market Evolving Landscape
Wearable transcranial Doppler technology is compressing the boundary between acute care and ambulatory monitoring, forcing manufacturers to recalibrate software architectures for continuous data streams rather than episodic clinical encounters.
Portable device platforms are bifurcating the installed base between emergency department deployments and intraoperative monitoring suites. Stroke centers in the United States and Germany are adopting battery-powered units for rapid bedside assessment. This form factor shift is compressing revenue concentration among manufacturers with integrated service networks capable of supporting distributed device fleets.
EU MDR post-market surveillance obligations are mandating real-world performance data collection from transcranial Doppler devices already in clinical use. Manufacturers must now maintain clinical follow-up registries that track diagnostic accuracy across diverse patient populations. European hospital procurement committees are prioritizing vendors with established MDR technical documentation and notified body relationships.
Subscription-based service models are displacing capital expenditure purchasing for transcranial Doppler systems in United States outpatient neurology practices. Per-procedure leasing arrangements bundle device access with technician training and maintenance coverage. This shift is most visible in Florida and Arizona markets where independent stroke prevention clinics are proliferating outside hospital networks.
Transcranial Doppler Devices Market Segmentation
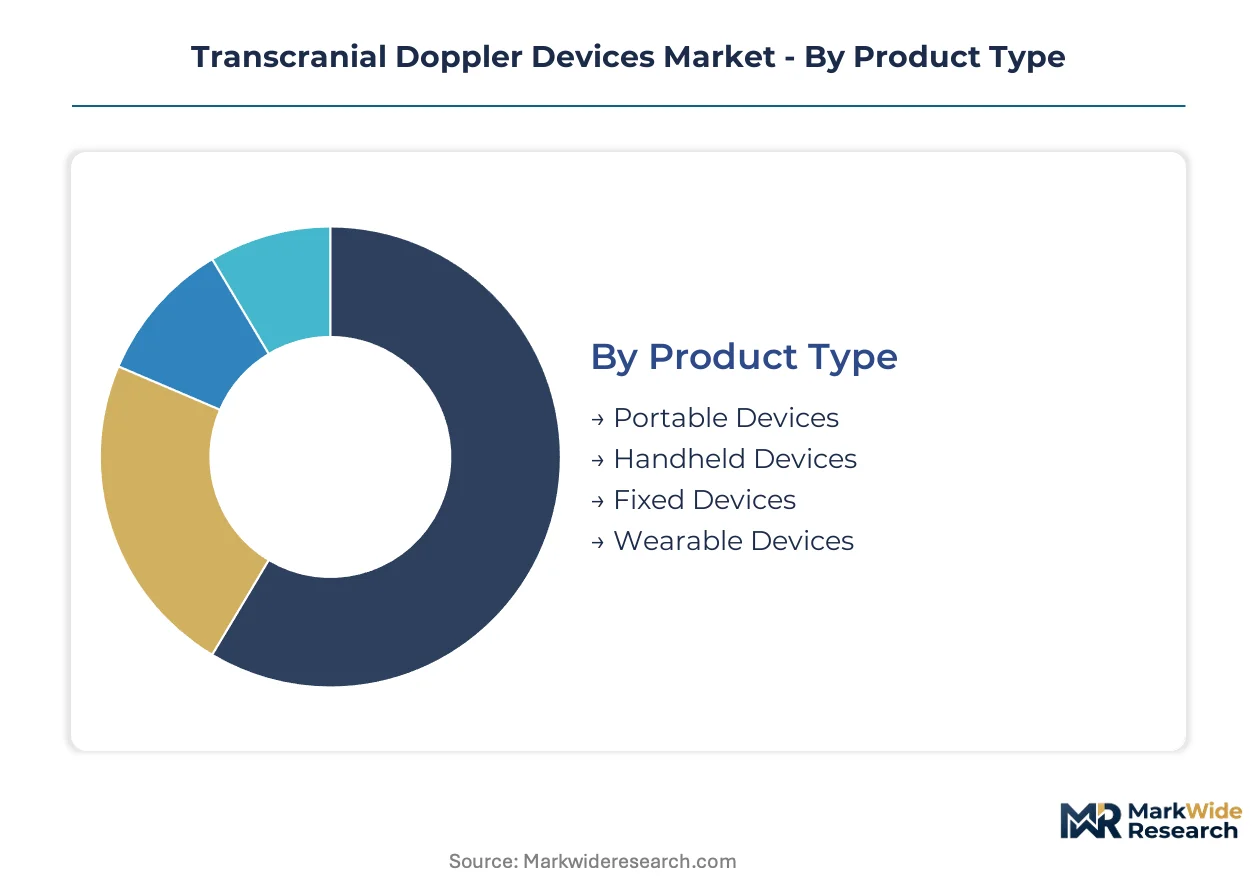
Transcranial Doppler device procurement splits across four distinct dimensions, each reflecting divergent clinical workflows and reimbursement environments. Understanding these fault lines clarifies where CT angiography and MR angiography exert substitution pressure versus where velocity-based functional assessment retains irreplaceable value.
Product Type:
Portable and wearable form factors face intensifying substitution pressure from point-of-care ultrasound systems, while fixed installations defend their position through integration with hospital imaging ecosystems.
- Portable Devices:Battery-powered units operating at 2 MHz frequency dominate emergency department deployments and intraoperative monitoring suites across stroke centers in the United States and Germany. Demand concentrates where rapid bedside assessment trumps comprehensive anatomical imaging, though reimbursement coding for portable procedures lags fixed-system rates in several markets.
- Wearable Devices:Continuous-monitoring form factors enabling ambulatory stroke risk stratification are gaining clinical traction through extended monitoring beyond acute care settings. Japan's MHLW reimbursement revisions and United States Medicare coding changes are expanding eligible procedure volumes for outpatient stroke prevention protocols.
- Handheld Devices:Compact units target resource-constrained settings where certified neurosonographer scarcity limits adoption of more complex platforms.
- Fixed Devices:Permanent installations anchor cerebrovascular monitoring in tertiary hospital neurology departments with established CT and MRI workflow integration.
Portable devices anchor the volume base while wearable devices gain share at the steepest rate.
Technology:
Technology stratification tracks the cost tier from basic velocity measurement to premium 3D flow reconstruction capabilities, with higher tiers capturing margin pools through software-integrated diagnostic confidence.
- Pulsed Wave Doppler:The dominant installed base technology emits gated ultrasonic pulses to sample blood velocity at specific depths within basal cerebral arteries. United States stroke centers and German hospital networks rely on 2 MHz pulsed systems for standard-of-care monitoring, though FDA 510(k) software validation timelines are prolonging premarket notification for advanced iterations.
- Advanced Imaging:3D flow reconstruction and computational fluid dynamics integration command premium pricing through enhanced diagnostic specificity for complex cerebrovascular anomalies. EU MDR Class IIa post-market surveillance obligations are mandating real-world performance registries that favor established vendors with notified body relationships.
- Continuous Wave Doppler:Uninterrupted wave transmission suits specific intraoperative monitoring scenarios where depth discrimination matters less than velocity trend tracking.
- Transient Technology:Emerging signal processing approaches target microemboli detection without continuous operator presence.
Pulsed wave Doppler anchors the volume base while advanced imaging climbs the fastest.
End User:
End user segmentation maps directly to procurement authority concentration, with hospital networks leveraging scale against fragmented independent practice purchasing patterns.
- Hospitals:Tertiary neurology departments and stroke centers represent the dominant procurement channel, particularly in Japan where aging demographics are expanding national surveillance programs. United States hospital networks are prioritizing vendors with established EMR interoperability and long-term service contract capabilities.
- Diagnostic Centers:Independent imaging facilities in Florida and Arizona markets are adopting subscription-based service models that bundle device access with technician training, displacing traditional capital expenditure purchasing.
- Research Institutions:Academic medical centers drive early adoption of artificial intelligence-integrated emboli detection algorithms before clinical validation.
- Rehabilitation Centers:Post-acute facilities represent emerging demand for portable monitoring during recovery protocols.
Hospitals anchor the volume base while diagnostic centers expand most quickly.
Application:
Application segmentation reveals where functional velocity assessment defends against anatomical imaging substitution versus where it cedes ground to CT angiography comprehensiveness.
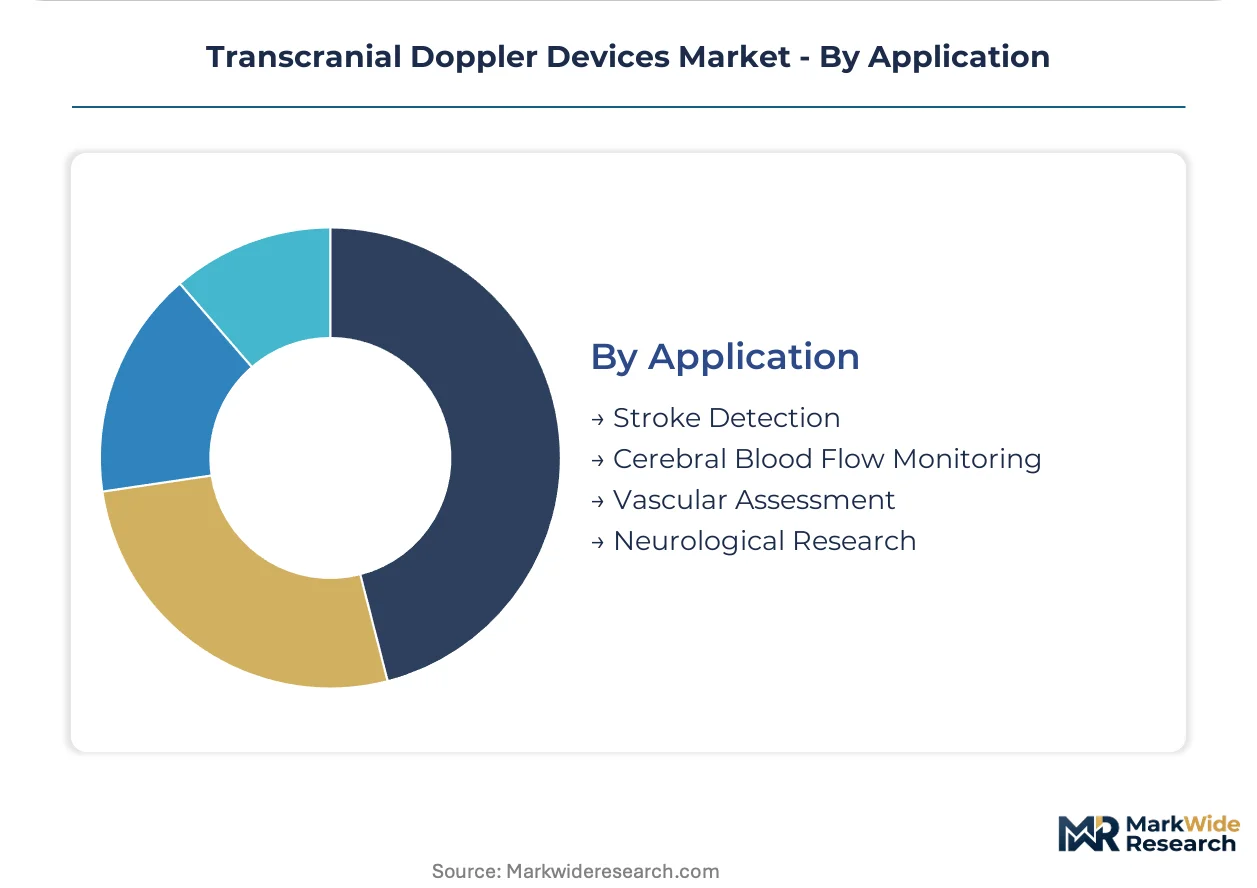
- Stroke Detection:Emergency department triage protocols in the United States, Germany, and Japan mandate cerebrovascular velocity assessment for rapid ischemic event identification. Temporal bone anatomical variability limits ultrasonic penetration in approximately fifteen percent of elderly patients, constraining addressable populations and preserving CT angiography's role in comprehensive stroke workups.
- Cerebral Blood Flow Monitoring:Intraoperative and neurocritical care applications rely on continuous Doppler monitoring where real-time velocity trends guide therapeutic intervention. India's tier-two and tier-three cities present whitespace for telemedicine-integrated portable deployments given certified neurosonographer shortages.
- Vascular Assessment:Stenosis screening and vasospasm detection in subarachnoid hemorrhage patients sustain demand for serial monitoring capabilities.
- Neurological Research:Cerebrovascular reactivity studies and cognitive activation paradigms employ Doppler as a non-invasive functional neuroimaging tool.
Stroke detection anchors the volume base while cerebral blood flow monitoring gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the dominant geography, with stroke surveillance programs and aging demographics driving procurement across multiple continents. National reimbursement frameworks and certified neurosonographer availability shape installation timelines in each market.
United States
Emergency department stroke triage protocols and Medicare reimbursement coding revisions are expanding eligible procedure volumes. FDA 510(k) premarket notification requirements and EPA disposal regulations for ultrasound gel add compliance layers to product lifecycle management. Stroke centers in Florida and Arizona are adopting subscription-based service models for outpatient neurology practices.
Germany
Tertiary hospital neurology departments and national stroke surveillance mandates sustain demand for portable and fixed installations. EU MDR Class IIa requirements and post-market surveillance obligations are accelerating replacement cycles for legacy equipment. The Rhine-Ruhr metropolitan region concentrates procurement authority through integrated hospital networks with long-term service contracts.
Japan
Aging demographics and MHLW reimbursement coding revisions for transcranial Doppler procedures are intensifying cerebrovascular monitoring in stroke prevention protocols. METI industrial standards and PMDA device regulations shape software validation requirements. The Kanto region around Tokyo anchors demand through university-affiliated stroke centers and localized technician training academies.
India
Tier-two and tier-three cities present whitespace for telemedicine-integrated portable deployments given certified neurosonographer shortages. CDSCO medical device regulations and BIS standards govern import and manufacturing compliance. Maharashtra and Karnataka are emerging as clinical trial hubs for ambulatory monitoring validation before broader national rollout.
United Kingdom
NHS England reimbursement coding changes and stroke pathway redesigns are shifting hospital procurement cycles toward integrated imaging ecosystems. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements creates transitional compliance complexity. The Greater Manchester and London stroke networks are piloting wearable continuous-monitoring protocols for post-discharge surveillance.
Transcranial Doppler Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the transcranial Doppler devices market. The upper tier comprises diversified imaging conglomerates with established service networks and EMR interoperability capabilities. The specialist tier includes focused neurology device manufacturers and regional portable system suppliers. Strategic moves concentrate on M&A for AI algorithm integration and capacity expansion for wearable form factor production.
Among diversified imaging conglomerates, GE Healthcare and Koninklijke Philips occupy positions exemplifying the integrated-leader archetype through bundled CT and MRI workflow offerings. Nihon Kohden Corporation represents the Asia-Pacific anchor within this tier, with its localized training infrastructure supporting regional penetration. These three entities collectively illustrate how service network density and regulatory documentation capabilities determine procurement committee prioritization across hospital networks.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips |
| Mindray Medical International |
| Nihon Kohden Corporation |
| Compumedics Limited |
| Natus Medical Incorporated |
| Atys Medical |
| Viasonix |
| Rimed |
| Others |
Value Network & Pricing Analysis
FDA 510(k) software validation and EU MDR Class IIa technical documentation requirements gate both supplier qualification and price differentiation in transcranial Doppler procurement. Manufacturers with established notified body relationships command premium positioning, while compliance gaps relegate competitors to standard-tier pricing in hospital network evaluations.
Pricing Analysis
Long-term service contracts with multi-year maintenance bundling dominate hospital procurement, displacing spot purchasing in United States and German stroke center networks. Price differentiation hinges on FDA 510(k) clearance tier and EMR interoperability certification, with premium systems capturing margin pools through 3D flow reconstruction capabilities. Cost compression in portable device tiers is intensifying because point-of-care ultrasound systems encroach on emergency department deployments. Independent diagnostic centers in Florida and Arizona exhibit highest price sensitivity, while tertiary neurology departments in Japan demonstrate lowest sensitivity due to bundled CT and MRI workflow integration requirements.
Supply Chain Analysis
Port congestion on East Asian trade lanes elevates inbound logistics costs for piezoelectric crystal shipments bound for device assembly facilities. Manufacturing concentrates in China, Japan, and Germany, with piezoelectric ceramics, ultrasound transducer assemblies, and signal processing chipsets as critical inputs. Single-source vulnerability in 2 MHz transducer supply creates exposure to raw material price swings and geopolitical disruption. Distribution runs through hospital GPO contracts in the United States, integrated service networks in Germany, and localized training academies in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transcranial Doppler incumbents face sustained substitution pressure from CT angiography and MR angiography systems capturing comprehensive anatomical imaging workflows. Defense requires recalibrating value propositions around velocity-based functional assessment irreplaceability.
For Market Incumbents: Shield installed base positions by deepening software companion development for automated emboli detection and securing long-term service contracts with European hospital networks. CT angiography substitution in comprehensive stroke workups demands reinforcement of real-time monitoring capabilities in intraoperative and neurocritical care settings where velocity trend guidance proves irreplaceable. Vertical integration into piezoelectric transducer manufacturing mitigates raw material volatility exposure.
For New Entrants and Emerging Players: Certified neurosonographer training infrastructure gaps in India's tier-two and tier-three cities present whitespace for telemedicine-integrated portable deployments with embedded AI interpretation. Wearable continuous-monitoring form factors for ambulatory stroke risk stratification offer the most penetrable segment given Japan's MHLW reimbursement expansion and United States Medicare coding revisions. Go-to-market execution should prioritize subscription-based service models bundling device access with technician certification programs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed portable device specialists holding FDA 510(k) clearances but lacking EMR interoperability scale. Five-to-ten year viability hinges on AI algorithm integration capabilities and wearable form factor manufacturing capacity. Monitor EU MDR post-market surveillance registry completion rates as inflection indicator for European procurement committee prioritization shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Integration | Automated emboli detection without specialist interpretation addresses neurosonographer scarcity in stroke centers. |
| Wearable Form Factor Development | Continuous monitoring capabilities extend cerebrovascular assessment beyond acute care into ambulatory prevention protocols. |
| EU MDR Technical Documentation Investment | Notified body relationships accelerate replacement cycle capture in European hospital network procurement. |
| Telemedicine Platform Partnership | Remote interpretation infrastructure unlocks tier-two and tier-three city penetration in neurosonographer-constrained markets. |
| Subscription Service Model Rollout | Per-procedure leasing with bundled training displaces capital expenditure purchasing in United States outpatient neurology. |
Research Methodology
A standing panel of stroke center directors, biomedical engineering managers, GPO contracts specialists, and neurosonography training program leads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, CMS Medicare procedure coding releases, and hospital procurement database extracts. Bottom-up installed base modeling and top-down reimbursement volume triangulation anchored market size estimation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling captured form factor tier, technology generation, end-user concentration, application workflow, and regional regulatory cluster dimensions. CAGRs derived from procedure volume elasticity to reimbursement coding changes and replacement cycle acceleration under tightened FDA and EU MDR pathways. Forecast inputs incorporated aging demographic stroke surveillance program expansion rates and certified neurosonographer training pipeline bottlenecks.
Underlying assumptions cover reimbursement stability, piezoelectric supply continuity, and substitution boundary containment between velocity-based and anatomical imaging modalities, with deviation risk concentrated in FDA software validation timeline extensions and CT angiography cost reduction curves. Practitioners should keep alternative scenarios live as MHLW and NHS England reimbursement coding revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Specimen Retrieval Market
Medical Devices
Enteral Stents Market
Medical Devices
Cough Assist Devices Market
Medical Devices
India Hemostats Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Global Keratometers Market
Medical Devices
Vaginal Pessary Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Global Angiographic Catheters Market
Medical Devices
Global IVF Devices Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Anti-Snore Device Market
Medical Devices
Global Capnography Market