
 Medical Device Regulatory Affairs Market | 2026-2036
Medical Device Regulatory Affairs Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Regulatory Affairs Market Intelligence
Regulatory consulting channels for mid-sized device manufacturers is fragmenting as boutique specialists and full-service conglomerates compete for overlapping client segments. IQVIA sustains geographic breadth through integrated clinical and regulatory platforms across multiple therapeutic areas. Emergo by UL leverages its Notified Body heritage to anchor European market access services. Freyr competes on cost-efficient submission management for emerging market authorizations.
Medical device regulatory affairs encompasses the scientific, legal, and administrative processes required to demonstrate safety, efficacy, and quality compliance for market authorization, including technical documentation preparation, clinical evidence evaluation, and post-market surveillance systems. The discipline serves manufacturers seeking lawful distribution across jurisdictions with divergent evidentiary standards. In vitro diagnostics commands specialized expertise due to evolving classification rules and companion diagnostic pathways. Software as a Medical Device represents the fastest-growing service category as algorithms attract novel scrutiny from FDA and EMA reviewers. Consulting services occupy mature margin pools while compliance auditing gains traction under intensified inspectorate activity.
FDA's Quality System Regulation and EU MDR technical documentation requirements shape service demand by mandating expanded clinical evidence and post-market clinical follow-up. ISO 13485 certification and MDSAP audit frameworks further structure vendor selection criteria for multinational manufacturers. Stakeholders must monitor convergence between FDA's pre-certification pilot and EU AI Act risk classifications for algorithm-based devices.
Market Dynamics
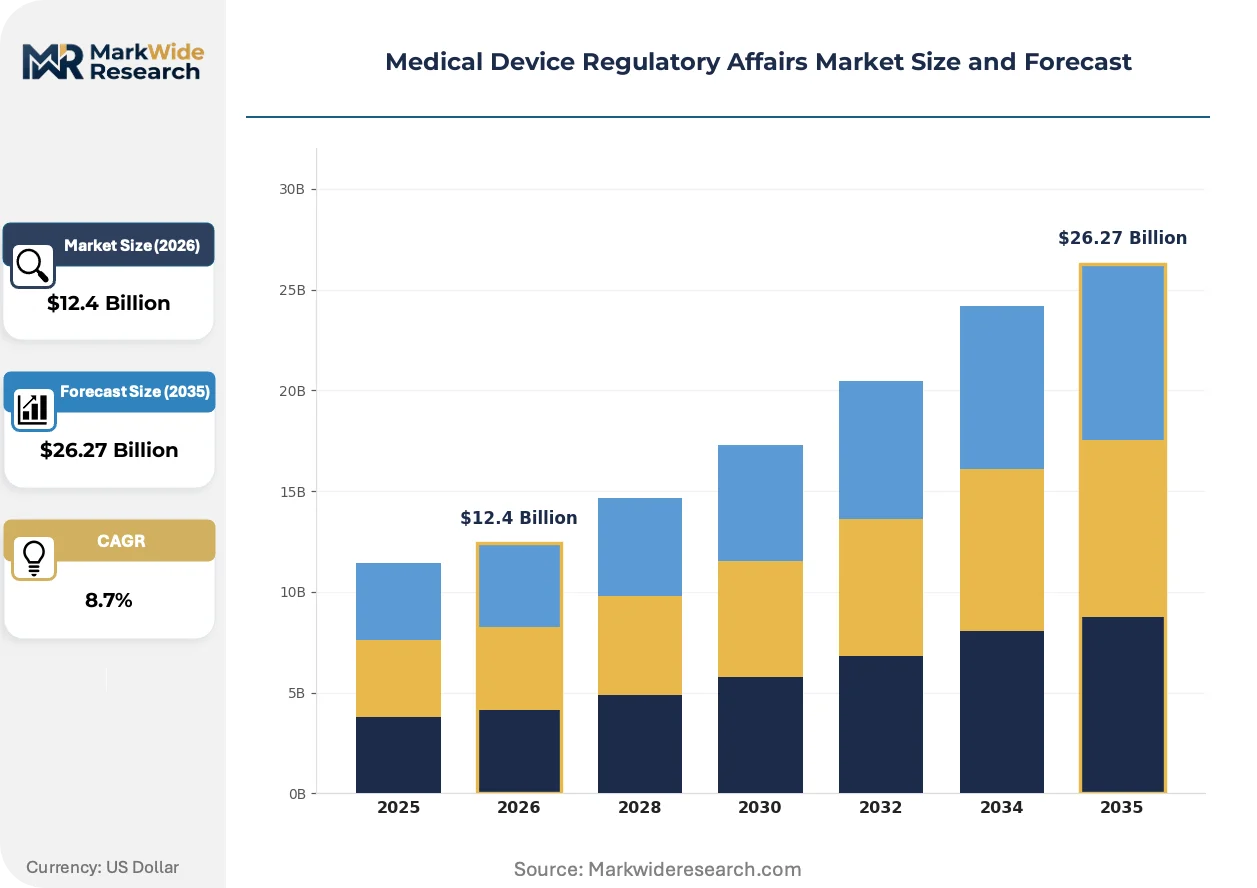
EU MDR technical documentation requirements and FDA pre-certification pilots are forcing manufacturers to rebuild quality management systems, creating sustained demand for specialized regulatory consulting as submission complexity outpaces in-house capability growth.
Growth Catalysts
- EU MDR Article 10 compliance deadlines:Legacy device manufacturers face mandatory technical documentation updates, driving outsourced clinical evaluation and post-market surveillance system builds.
- SaMD algorithm validation requirements:FDA's predetermined change control plans for machine learning-based diagnostics create novel submission pathways requiring specialized statistical and software engineering expertise.
- German medical technology cluster expansion:Concentrated device manufacturing in Baden-Württemberg and Bavaria generates localized demand for Notified Body liaison services and QMS implementation support.
Market Restraints
- Notified Body capacity constraints:EU MDR designation bottlenecks extend conformity assessment timelines, compressing service provider billing realization and client retention rates.
- Clinical investigator cost inflation:Principal investigator fees for PMCF studies have risen substantially across Western Europe, eroding project margins for fixed-price regulatory contracts.
- Substitute in-house regulatory buildouts:Large manufacturers including Medtronic and Johnson & Johnson have expanded captive regulatory affairs teams, reducing reliance on external consulting for routine submissions.
Strategic Opportunities
- Indian CDSCO manufacturing license facilitation:Medical device park investments in Andhra Pradesh and Gujarat create demand for import license and test license navigation services.
- Japan PMDA QMS ministerial ordinance convergence:Alignment between MHLW requirements and ISO 13485:2016 enables standardized service offerings across Asia-Pacific subsidiary networks.
- MDSAP single audit program expansion:Brazil ANVISA and South Korea MFDS recognition of MDSAP reports reduces redundant audit preparation, creating efficiency plays for multi-jurisdictional manufacturers.
Industry Challenges
- Competent authority reviewer turnover:FDA Center for Devices and Radiological Health and EMA device divisions face staffing attrition, extending query response cycles and submission unpredictability.
- Legacy QMS software integration:Manufacturers running on-premise quality systems require costly validation work to connect with cloud-based regulatory intelligence platforms.
- IVDR companion diagnostic pathway complexity:Co-development agreements between device and pharmaceutical sponsors demand novel project management capabilities spanning two distinct regulatory review frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Regulatory Affairs Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Devices, In vitro Diagnostics, Software as a Medical Device, Implants End User: Hospitals, Clinics, Laboratories, Research Institutions Service Type: Consulting, Submission Services, Compliance Auditing, Training Therapy Area: Cardiology, Orthopedics, Neurology, Urology |
| Companies Covered | MCRA, IQVIA, Emergo by UL, LabCorp, ICON, Arazy Group, Regulatory Compliance Associates, SGS, Freyr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Regulatory Affairs Market Strategic Shifts & Innovations
Regulatory intelligence platforms are compressing traditional consulting margins by automating submission tracking and predicate device research, forcing service providers to reposition toward higher-value clinical strategy and regulatory science advisory.
Artificial intelligence-enabled regulatory writing tools are collapsing document preparation timelines for 510(k) and technical file submissions. Mid-sized device manufacturers in Minnesota and Massachusetts are piloting these platforms for CER and risk management file generation. The technology is collapsing the economics of high-volume, template-driven regulatory writing services that previously sustained boutique consultancies.
FDA's proposed Quality System Regulation harmonization with ISO 13485:2016 will eliminate duplicative quality system requirements for US-market manufacturers. The agency's draft guidance on computerized systems validation signals reduced paper documentation burdens for software-based devices. Domestic manufacturers with existing ISO 13485 certification are preparing gap assessments to streamline dual compliance overhead.
Buyers are consolidating vendor relationships under enterprise regulatory outsourcing agreements that bundle consulting, auditing, and training across multiple affiliates. Large manufacturers are replacing project-based procurement with multi-year managed service contracts covering entire product portfolios. This consolidation is most visible among Fortune 500 device companies headquartered in California and Illinois, where procurement teams are reducing supplier counts from fifteen-plus to three to five strategic partners.
Medical Device Regulatory Affairs Market Segmentation
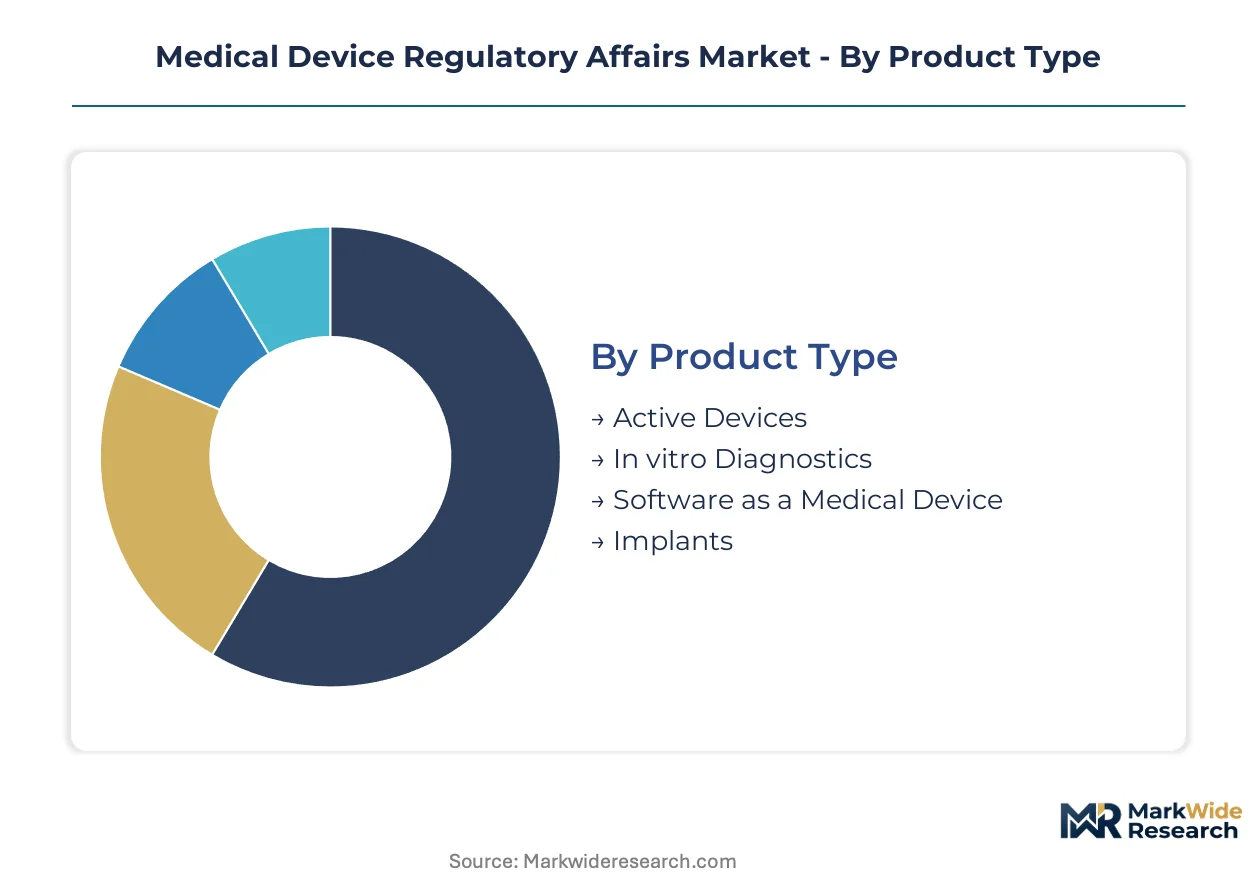
Regulatory affairs service providers structure their offerings around device classification complexity and client operational scale. Segment-specific expertise determines vendor selection as FDA and EU MDR submission pathways diverge across product categories.
Product Type:
Mature hardware categories coexist with emerging digital modalities, creating divergent service requirements across the compliance lifecycle.
- Active Devices:Electromechanical equipment with energy sources or sensors demands extensive electromagnetic compatibility documentation and electrical safety testing protocols. German manufacturers in Baden-Württemberg drive demand for Notified Body liaison services as EU MDR technical file requirements expand.
- In vitro Diagnostics:Reagents, instruments, and specimen collection systems face specialized classification rules under EU IVDR and FDA 510(k) pathways. Laboratory buyers in Massachusetts and California concentrate demand for companion diagnostic co-development regulatory strategy.
- Software as a Medical Device:Algorithm-based diagnostics and clinical decision support tools attract novel FDA pre-certification scrutiny.
- Implants:Long-term residence devices require biocompatibility testing dossiers and post-market clinical follow-up systems.
Active Devices handles the majority of throughput; Software as a Medical Device is the fastest mover on share.
End User:
Procurement sophistication varies sharply across institutional settings, shaping service bundling and pricing structures.
- Hospitals:Integrated delivery networks with captive compliance teams purchase targeted gap-filling for EU MDR transition and FDA warning letter remediation. Academic medical centers in Illinois and Texas generate demand for regulatory intelligence platform subscriptions.
- Clinics:Outpatient surgical centers and specialty practices rely on distributor-mediated regulatory support for device procurement authorization.
- Laboratories:Reference labs and hospital-based pathology units require IVDR technical documentation and quality management system implementation.
- Research Institutions:University technology transfer offices navigate investigational device exemption pathways for early-stage prototypes.
Hospitals command the largest contract values; Research Institutions are expanding most quickly as academic spinouts proliferate.
Service Type:
Margin compression in commoditized offerings pushes vendors toward higher-value advisory and technology-enabled delivery models.
- Consulting:Strategic advisory on regulatory pathway selection, predicate device identification, and clinical evidence planning commands premium pricing. FDA Q-Submission preparation and EU MDR gap assessments dominate project scopes for mid-sized manufacturers.
- Submission Services:Technical writing, dossier compilation, and authority correspondence management operate on fixed-fee or milestone-based pricing. Automation platforms are collapsing economics for template-driven 510(k) and technical file preparation.
- Compliance Auditing:ISO 13485 certification support and MDSAP audit preparation gain traction under intensified inspectorate activity.
- Training:Workforce education on FDA Quality System Regulation and EU MDR requirements addresses competency gaps in quality assurance departments.
Consulting captures the highest margins per engagement; Compliance Auditing is gaining share fastest as enforcement intensifies.
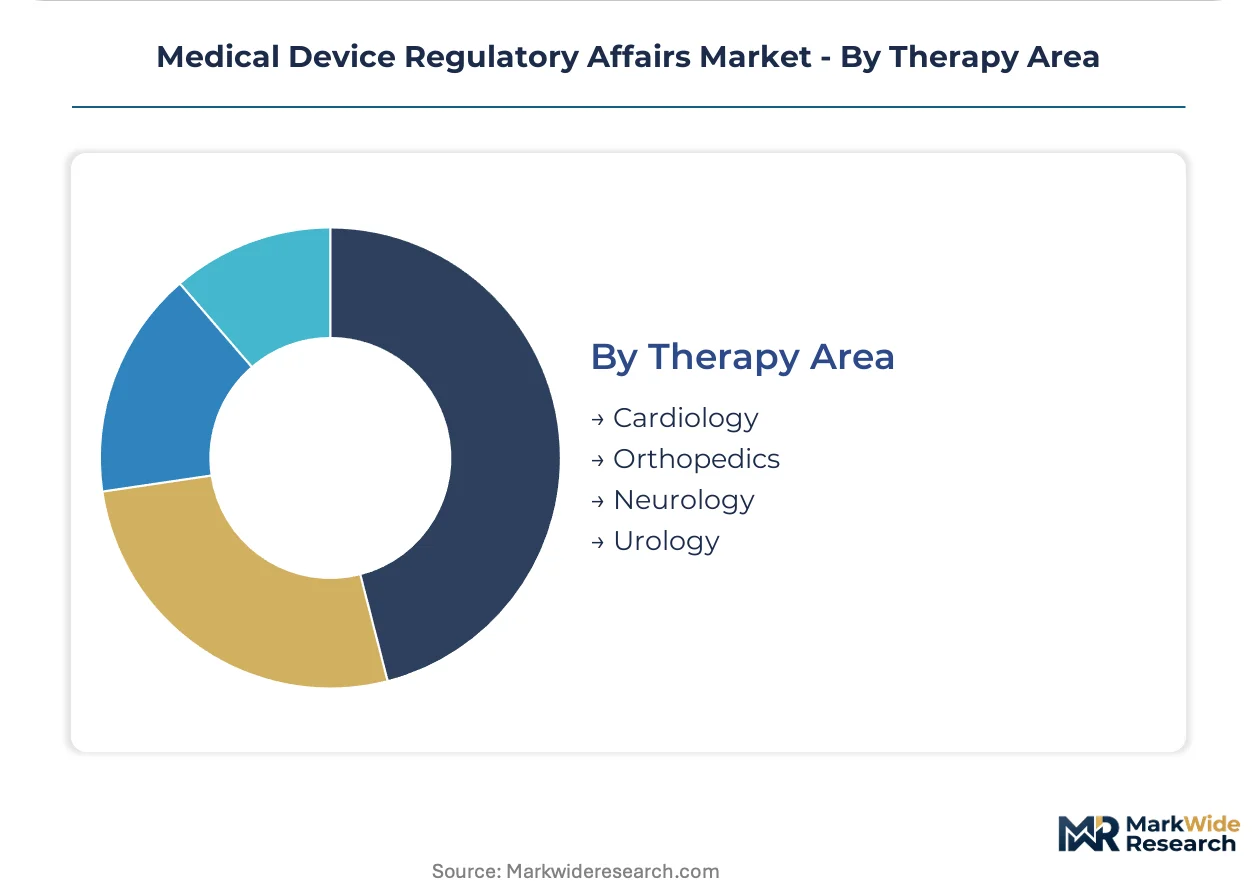
Therapy Area:
Clinical complexity and evidentiary standards create distinct regulatory specialization requirements across medical disciplines.
- Cardiology:Implantable pacemakers, defibrillators, and interventional devices face stringent FDA premarket approval and EU MDR Class III conformity assessment. Minnesota and Massachusetts device clusters generate concentrated demand for clinical evaluation report preparation.
- Orthopedics:Joint replacements and spinal implants require biocompatibility testing and mechanical performance documentation under ASTM and ISO standards. Warsaw, Indiana manufacturers seek MDSAP audit efficiency across US, Canadian, and Japanese markets.
- Neurology:Deep brain stimulators and diagnostic EEG systems navigate novel software validation requirements for algorithm-based interpretation.
- Urology:Endoscopic instruments and continence devices operate under moderate-risk classification with streamlined 510(k) clearance pathways.
Cardiology absorbs the most regulatory consulting hours; Neurology shows the steepest expansion trajectory as neurotechnology investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German regulatory consultants command premium pricing for EU MDR technical documentation services while Indian providers compete on cost-efficient emerging market authorizations. This pricing-power asymmetry reflects divergent regulatory complexity rather than capability gaps.
United States
FDA's pre-certification pilot for Software as a Medical Device and intensified Quality System Regulation enforcement drive demand for specialized submission support. The agency's Center for Devices and Radiological Health processes the majority of global 510(k) clearances. Minnesota's medical technology corridor around Minneapolis-St. Paul generates concentrated demand for clinical evaluation report preparation and predicate device identification services.
Germany
EU MDR Article 10 compliance deadlines and Notified Body capacity constraints create sustained demand for technical documentation remediation. The country's national regulator, BfArM, coordinates with designated Notified Bodies on conformity assessment timelines. Baden-Württemberg's device manufacturing cluster around Stuttgart and Tübingen anchors European demand for QMS implementation support and post-market surveillance system builds.
India
CDSCO manufacturing license facilitation and medical device park investments in Andhra Pradesh and Gujarat attract regulatory navigation services for import and test licenses. The national regulator's alignment with ISO 13485 standards streamlines quality system certification pathways. Hyderabad's life sciences corridor concentrates demand for emerging market authorization strategy as domestic manufacturers expand export capabilities.
Japan
PMDA QMS ministerial ordinance convergence with ISO 13485:2016 enables standardized service offerings across Asia-Pacific subsidiary networks. The Pharmaceuticals and Medical Devices Agency maintains stringent clinical evidence requirements for novel device categories. Tokyo-Osaka corridor medical device subsidiaries drive demand for bilingual regulatory submission management and local authorized representative services.
United Kingdom
MHRA post-Brexit regulatory divergence from EU MDR frameworks creates parallel compliance requirements for Great Britain market access. The national regulator's UKCA marking implementation demands novel technical documentation preparation. Cambridge-London medtech spinouts from university technology transfer offices generate demand for investigational device exemption pathway navigation.
Medical Device Regulatory Affairs Market Key Industry Players
Full-service conglomerates and boutique specialists split the market along client scale and therapeutic complexity vectors. The vendor base concentrates around three strategic archetypes: integrated clinical-regulatory platforms, Notified Body heritage consultancies, and cost-efficient emerging market specialists. Consolidation pressures intensify as large manufacturers reduce supplier counts from fifteen-plus to three to five strategic partners under multi-year managed service contracts.
Within the integrated platform tier, IQVIA exemplifies geographic breadth across multiple therapeutic areas while Emergo by UL anchors European market access services through its Notified Body heritage. Freyr occupies the cost-efficient submission management position for emerging market authorizations. These three represent the dominant competitive positioning archetypes: scale-driven integration, regulatory heritage leverage, and price-competitive specialization.
| Leading Market Players |
|---|
| MCRA |
| IQVIA |
| Emergo by UL |
| LabCorp |
| ICON |
| Arazy Group |
| Regulatory Compliance Associates |
| SGS |
| Freyr |
| Others |
Cost & Logistics Intelligence
German Notified Body heritage concentrates in Stuttgart and Tübingen, anchoring premium pricing for EU MDR technical documentation services while Indian CDSCO navigation providers compete on cost-efficient emerging market authorizations. This geographic bifurcation shapes where margin pools accumulate across the regulatory value chain.
Pricing Analysis
Configured-to-order pricing for bespoke clinical evaluation report preparation and Q-Submission strategy commands substantial premiums over standardized ISO 13485 gap assessment packages. Project-based fee structures dominate, with pricing differentiation driven by Notified Body certification tier and therapeutic area complexity. Cost compression in template-driven 510(k) preparation intensifies as AI-enabled regulatory writing platforms displace boutique consultancies. Mid-sized manufacturers in Minnesota and Massachusetts exhibit highest price sensitivity, while Fortune 500 device companies prioritize strategic partnership value over unit cost.
Supply Chain Analysis
Extended payment terms from large manufacturer procurement teams in California and Illinois strain cash conversion for boutique regulatory consultancies competing against integrated platform providers with supply-chain finance facilities. Service delivery draws from consultant talent pools in Germany, the United States, and India, with biocompatibility testing and predicate device research as critical input dependencies. Single-source vulnerability concentrates in specialized statistical expertise for SaMD algorithm validation. Distribution runs through direct enterprise sales to manufacturer regulatory affairs departments and channel partnerships with medical device trade associations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as regulatory intelligence platforms compress traditional consulting margins and enterprise outsourcing agreements consolidate vendor relationships under multi-year managed service contracts.
For Market Incumbents: Harden defensive positioning through deeper integration of clinical trial data platforms with regulatory submission workflows, creating switching costs for manufacturer clients. Invest in AI-enabled document generation capabilities to match automation-driven price erosion from emerging competitors. Priority levers include MDSAP audit standardization across Asia-Pacific networks and captive buildout of biostatistics expertise for SaMD predetermined change control plans.
For New Entrants and Emerging Players: Pursue white-space opportunities in IVDR companion diagnostic co-development project management, where pharmaceutical-device sponsor coordination demands remain underserved. Target CDSCO manufacturing license facilitation for Andhra Pradesh and Gujarat medical device parks, where import and test license navigation services face localized supply gaps. Go-to-market angle should emphasize bilingual Japanese-English regulatory submission management for Tokyo-Osaka corridor subsidiaries seeking PMDA QMS convergence efficiency.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regulatory consultancies possessing Notified Body heritage but lacking integrated clinical trial platforms. Long-term viability across the projection horizon hinges on successful transition from project-based revenue to recurring managed service contracts. Acquisition target archetype: mid-sized EU MDR specialists with established BfArM liaison relationships and scalable technical documentation remediation capabilities. Signal to watch: FDA pre-certification pilot expansion into algorithm-based diagnostic categories as volume inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Regulatory Writing Platform Deployment | Collapses 510(k) document preparation timelines for Minnesota and Massachusetts manufacturers. |
| MDSAP Single Audit Program Expansion | Reduces redundant audit preparation for Brazil ANVISA and South Korea MFDS recognition. |
| EU MDR Technical Documentation Remediation | Captures legacy device manufacturer demand ahead of Article 10 compliance deadlines. |
| SaMD Pre-Certification Pathway Navigation | Addresses FDA predetermined change control plan requirements for machine learning diagnostics. |
| Enterprise Regulatory Outsourcing Consolidation | Bundles consulting, auditing, and training across California and Illinois Fortune 500 portfolios. |
Research Approach
Cross-validation between primary interviews with regulatory affairs directors, quality assurance managers, Notified Body auditors, and GPO contracts managers and secondary sources including FDA 510(k) filings, EMA device division guidance documents, CDSCO manufacturing license records, and ISO 13485 certification databases anchors the qualitative findings. Bottom-up service provider revenue analysis triangulates against top-down manufacturer regulatory spending estimates across the analysis window.
Calibration against historical regulatory submission volumes and Notified Body capacity utilization informs the projection framework. Segmentation dimensions modeled include device classification tier, service type complexity, therapeutic area specialization, and geographic regulatory cluster. CAGRs derive from weighted average growth rates across segment-level demand drivers, incorporating EU MDR transition timelines, FDA pre-certification pilot expansion trajectories, and emerging market authorization filing patterns as industry-specific forecast inputs.
Sensitivities concentrate around Notified Body designation bottlenecks, FDA CDRH staffing attrition, and AI-enabled platform adoption curves. Forecasts reflect documented assumptions regarding regulatory convergence timelines and manufacturer outsourcing propensity. Macroeconomic contraction, regulatory framework divergence, or technological disruption in automated compliance tools would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Artificial Respirator Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Massage Equipment Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Brachytherapy Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Foot Suction Unit Market