
 Sinus Dilation Devices Market | 2026-2036
Sinus Dilation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sinus Dilation Devices Market Analysis
Leasing and pay-per-procedure financing is fragmenting capital deployment across the sinus dilation landscape. Stryker leverages its endoscopic instrument ecosystem to bundle navigation and dilation systems for integrated OR contracts. Medtronic anchors its position through sustained R&D intensity in powered instrumentation alongside balloon platforms. Smith & Nephew competes via geographic dominance in European ambulatory settings where outpatient sinus procedures have scaled fastest.
Sinus dilation devices are minimally invasive instruments designed to restore ostiomeatal complex patency through transnasal balloon inflation, typically employing catheter diameters of 3–7 mm and pressures up to 12 atmospheres for controlled microfracture of bony sinus outflow tracts. Their primary commercial purpose is to reduce reliance on functional endoscopic sinus surgery in chronic sinusitis cases while preserving mucosal integrity. Balloon-based systems lead procedural volumes due to established CPT reimbursement codes and lower complication profiles, while navigation systems capture disproportionate margin pools as hospitals prioritize image-guided safety protocols. Radiofrequency technology segments are expanding fastest in Asian markets where hybrid thermal-balloon platforms address polyp recurrence.
FDA 510(k) premarket notification requirements and ISO 13485 quality management standards govern device commercialization, with the former dictating clinical evidence thresholds and the latter shaping manufacturing audit protocols for outsourced component suppliers. The EU Medical Device Regulation intensifies notified body scrutiny for balloon materials and biocompatibility testing, extending certification timelines for manufacturers without legacy CE certificates. Stakeholders must monitor how CMS site-of-service differential payments reshape capital allocation between hospital outpatient departments and independent surgery centers.
Market Dynamics
Site-neutral reimbursement policies from CMS are redirecting procedural volumes from hospital outpatient departments toward ambulatory surgery centers, compressing capital equipment deployment cycles and forcing manufacturers to reconfigure their sales and service footprints around lower-acuity settings.
Growth Catalysts
- FDA 510(k) Pathway:Streamlined premarket notification for balloon sinus dilation systems accelerates commercial entry for device developers, reducing time-to-revenue for new catheter platforms.
- Chronic Rhinosinusitis Prevalence:Elevated disease burden in insured populations sustains procedural demand, particularly among adults aged 45-64 seeking alternatives to functional endoscopic sinus surgery.
- Hybrid Thermal-Balloon Convergence:Integration of radiofrequency energy with balloon dilation addresses polyp recurrence in revision cases, expanding addressable indications beyond primary ostiomeatal obstruction.
Market Restraints
- Nitinol Alloy Supply Concentration:Dependence on specialized shape-memory wire suppliers in East Asia creates input cost volatility and single-source vulnerability for catheter shaft manufacturing.
- EU MDR Certification Friction:Extended notified body scrutiny for balloon material biocompatibility testing delays CE marking timelines, particularly for manufacturers without legacy certificates.
- Functional Endoscopic Surgery Persistence:Established ENT surgeon training and reimbursement familiarity with traditional FESS techniques sustains competitive substitution pressure in complex anatomical cases.
Strategic Opportunities
- Japanese Ambulatory Expansion:METI-supported same-day surgery initiatives and aging sinusitis demographics create underpenetrated demand for outpatient-compatible balloon systems.
- Image-Guided Navigation Bundling:Convergence of electromagnetic tracking with dilation platforms enables premium pricing for integrated safety protocols in high-risk revision procedures.
- Leasing Model Penetration:Pay-per-procedure financing arrangements lower capital barriers for independent surgery centers, opening channel access beyond integrated health system purchasing.
Industry Challenges
- ISO 13485 Audit Complexity:Outsourced component manufacturing across multiple jurisdictions complicates quality management system compliance, particularly for balloon molding and catheter extrusion subcontractors.
- Navigation-Dilation Integration Talent:Scarce biomedical engineering expertise in electromagnetic tracking algorithm development constrains R&D velocity for next-generation image-guided platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sinus Dilation Devices Market |
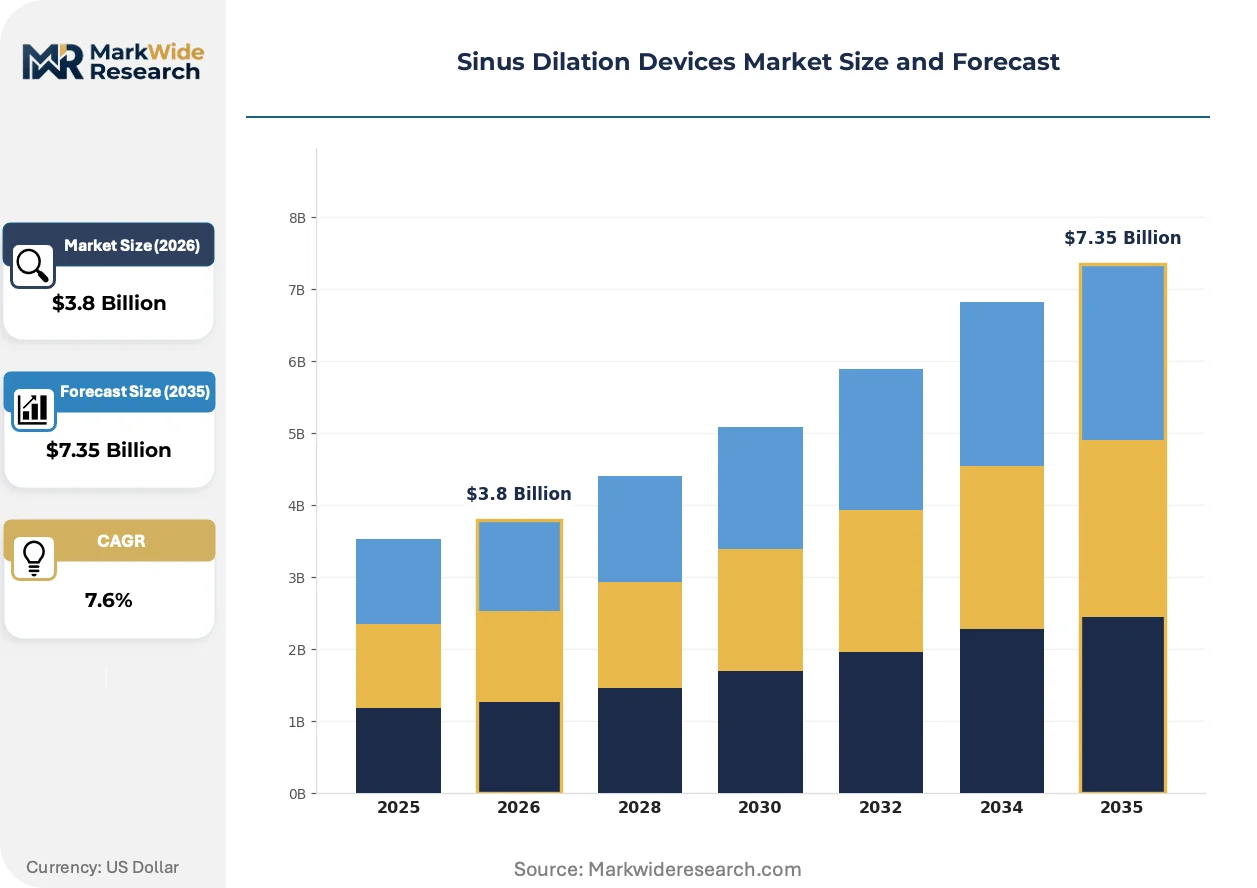
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloons, Stents, Dilation Instruments, Navigation Systems Technology: Hydrostatic, Ultrasonic, Mechanical, Radiofrequency End User: Hospitals, Surgery Centers, Clinics, Home Care Application: Chronic Sinusitis, Nasal Polyps, Sinus Surgery, Rhinoplasty |
| Companies Covered | Johnson & Johnson Services Inc., Stryker, Medtronic, Olympus Corporation, Smith & Nephew, Intersect ENT, Inc., Dalent Medical, Meril Life Sciences Pvt. Ltd., InnAccel Technologies Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sinus Dilation Devices Market Emerging Trajectories
Balloon catheter platforms are absorbing adjacent functionality from powered instrumentation and navigation systems, compressing the traditional separation between standalone device categories and enabling single-procedure solutions.
Single-use disposable balloon systems with integrated inflation pressure monitoring are collapsing the capital-replacement cycle for reusable instrumentation. Ambulatory surgery centers in the United States are adopting these platforms at accelerated rates, eliminating sterilization infrastructure requirements and reducing per-procedure overhead. The structural consequence is a shift from capital equipment sales toward recurring consumable revenue models that lock in procedural volume commitments.
The EU Medical Device Regulation intensifies post-market surveillance obligations for balloon material degradation and biocompatibility endpoints. Manufacturers must now maintain clinical follow-up registries that extend beyond initial certification, elevating compliance costs disproportionately for mid-tier device developers. European notified bodies are prioritizing audit resources toward legacy certificate renewals, creating queuing delays that favor established players with dedicated regulatory affairs infrastructure.
Hospital purchasing committees are unbundling after-sales service from device procurement, compressing vendor margin pools and forcing manufacturers to compete on transparent per-procedure economics. Independent surgery centers in Texas and Florida are leading this transition, negotiating direct access to balloon catheter inventory without mandatory navigation system attachments. The geographic concentration reflects state-level ambulatory surgery licensing permissiveness and payer preference for site-neutral episode reimbursement.
Sinus Dilation Devices Market Segmentation
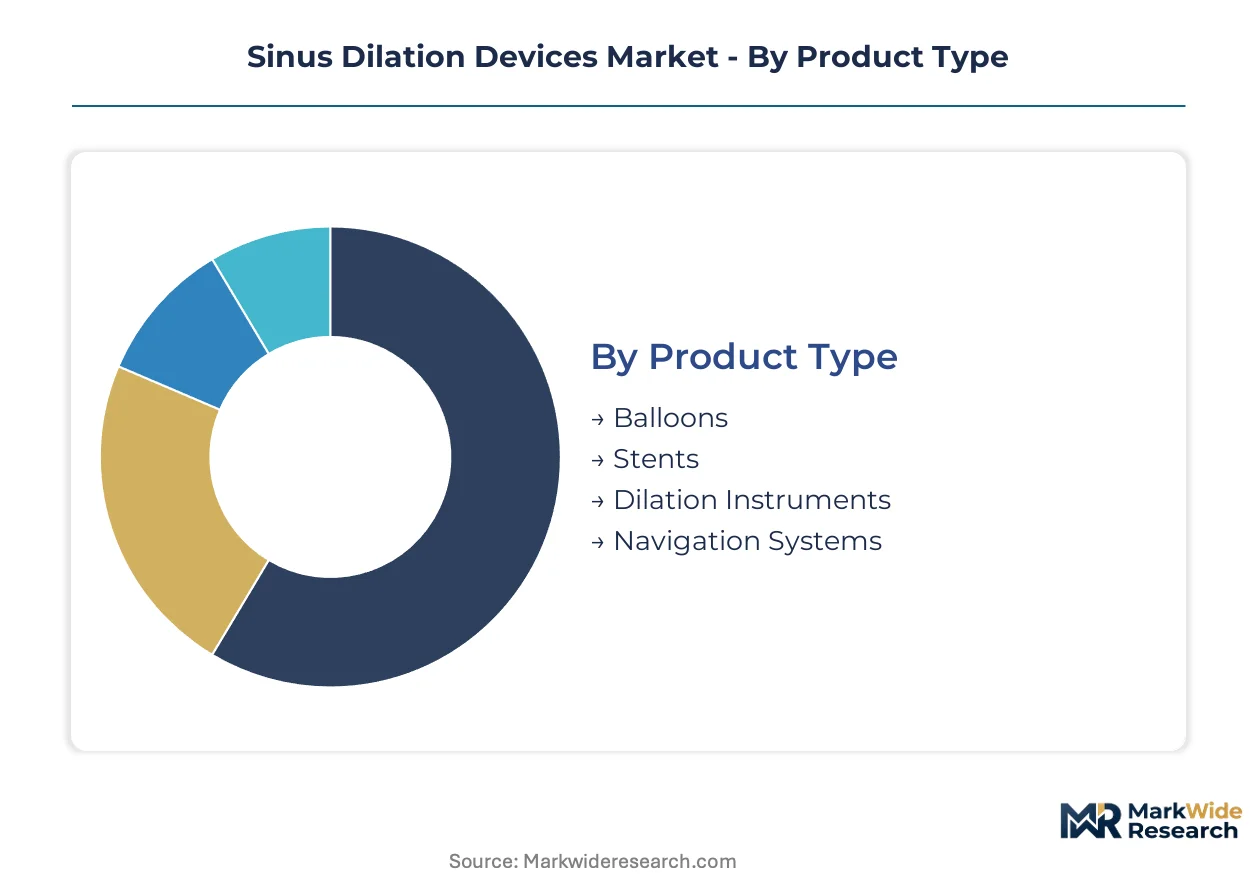
Sinus dilation device segmentation reveals divergent service intensity requirements across product categories. Balloon platforms demand minimal field engineering support while navigation systems require continuous calibration maintenance. These structural differences reshape how manufacturers allocate technical service resources across customer tiers.
Product Type:
After-sales-service intensity varies dramatically across product categories, with capital-intensive navigation platforms requiring dedicated field engineering teams while disposable balloon systems operate on replenishment logistics alone.
- Balloons:Catheter-based platforms employing 3–7 mm diameters and inflation pressures up to 12 atmospheres for controlled ostiomeatal microfracture. Demand concentrates in ambulatory surgery centers across Texas and Florida where site-neutral reimbursement accelerates outpatient procedural migration. CPT coding stability sustains predictable revenue cycles for manufacturers.
- Navigation Systems:Electromagnetic tracking platforms integrating with dilation instrumentation for image-guided safety protocols. Hospital purchasing committees in the United States prioritize these systems for revision cases and complex anatomical variants, commanding premium pricing through bundled OR contracts. Field service density requirements compress margins for mid-tier vendors.
- Stents:Biodegradable and drug-eluting implants maintaining post-dilation patency.
- Dilation Instruments:Powered and manual tools for traditional functional endoscopic approaches.
By volume, Balloons lead. By growth pace, Navigation Systems is ahead.
Technology:
Technology selection directly determines manufacturing complexity and regulatory pathway duration, with thermal platforms facing extended biocompatibility scrutiny under EU MDR frameworks.
- Hydrostatic:Pressure-mediated balloon inflation without thermal energy delivery, preserving mucosal integrity through controlled mechanical expansion. Hospital outpatient departments in the United States favor hydrostatic platforms for their established reimbursement profiles and lower complication documentation burdens. ISO 13485 audit protocols for balloon molding subcontractors remain straightforward.
- Radiofrequency:Thermal energy integration with balloon dilation addressing polyp recurrence in revision sinusitis cases. Asian markets, particularly Japan under METI-supported same-day surgery initiatives, show fastest uptake for hybrid thermal-balloon convergence. EU notified body scrutiny of thermal material degradation extends certification timelines.
- Ultrasonic:High-frequency mechanical vibration for tissue fragmentation.
- Mechanical:Direct instrumentation without energy delivery or fluid inflation.
By installed base, Hydrostatic dominates. By expansion trajectory, Radiofrequency climbs fastest.
End User:
End-user category shapes capital deployment cycles, with independent surgery centers demanding pay-per-procedure financing while hospital systems negotiate multi-year integrated contracts.
- Surgery Centers:Ambulatory facilities eliminating sterilization infrastructure through single-use disposable adoption. United States surgery centers in Texas and Florida lead unbundled procurement negotiations, separating balloon catheter access from mandatory navigation attachments. Leasing model penetration lowers capital barriers for independent operators.
- Hospitals:Integrated health systems prioritizing image-guided safety protocols and bundled service contracts. Academic medical centers sustain demand for navigation-dilation integration despite higher capital requirements. Purchasing committees compress vendor margin pools through transparent per-procedure economics.
- Clinics:Office-based settings with limited procedural capabilities.
- Home Care:Nasal irrigation and maintenance devices for post-procedural care.
By procedure volume, Surgery Centers lead. By revenue per procedure, Hospitals is ahead.
Application:
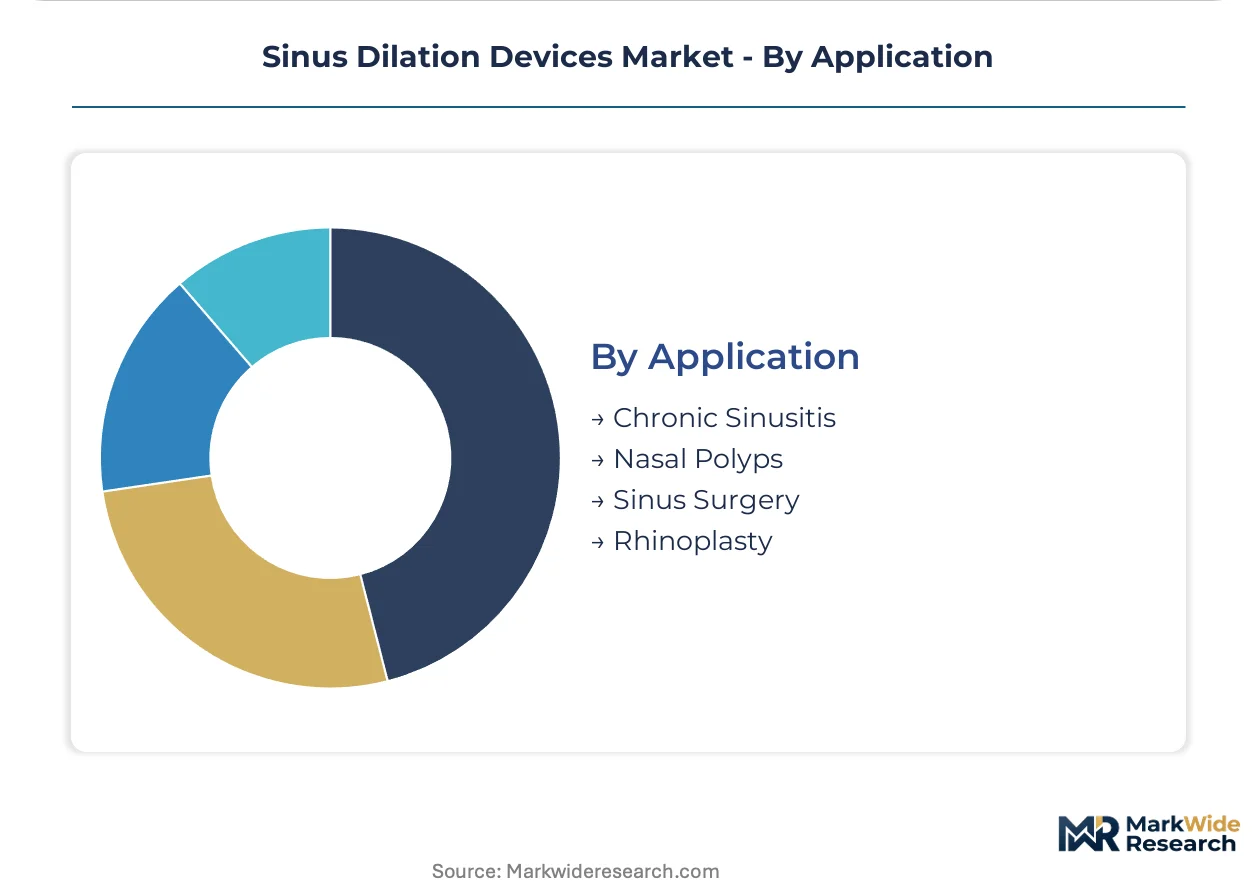
Application segmentation tracks disease severity gradients, with primary chronic sinusitis cases suitable for standalone dilation while polyp recurrence demands hybrid thermal approaches.
- Chronic Sinusitis:Persistent ostiomeatal obstruction in adults aged 45–64 seeking alternatives to functional endoscopic sinus surgery. United States insured populations sustain highest procedural volumes among developed markets. FDA 510(k) pathway streamlines commercial entry for new catheter platforms targeting this indication.
- Nasal Polyps:Recurrent inflammatory growths requiring revision procedures with elevated safety protocol demands. Hybrid thermal-balloon platforms address polyp recurrence, expanding addressable indications beyond primary obstruction. Asian markets show fastest adoption for integrated energy delivery systems.
- Sinus Surgery:Traditional operative approaches including functional endoscopic techniques.
- Rhinoplasty:Cosmetic and reconstructive nasal procedures with limited dilation device relevance.
By procedure count, Chronic Sinusitis leads. By technology upgrade intensity, Nasal Polyps is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in sinus dilation devices tilt toward net imports in emerging markets while established manufacturing clusters in the United States and Germany supply catheter platforms to Asia-Pacific ambulatory networks. Currency-adjusted procurement costs are widening price gaps between regional distribution channels.
United States
Site-neutral CMS reimbursement policies are accelerating procedural migration from hospital outpatient departments to independent surgery centers in Texas and Florida. FDA 510(k) clearance pathways streamline commercial entry for balloon catheter platforms targeting chronic rhinosinusitis cases. The Dallas-Fort Worth metroplex anchors domestic distribution networks serving ambulatory chains across the Southeast.
Germany
EU MDR compliance costs are compressing margins for mid-tier device developers while favoring established players with dedicated regulatory infrastructure. Notified body scrutiny of balloon material biocompatibility extends certification timelines for catheter shaft manufacturers. The Stuttgart industrial corridor concentrates precision molding subcontractors supplying nitinol-reinforced catheter platforms to European ENT specialists.
Japan
METI-supported same-day surgery initiatives are expanding addressable demand for outpatient-compatible balloon systems among aging sinusitis demographics. PMDA consultation pathways for hybrid thermal-balloon platforms address polyp recurrence indications beyond primary ostiomeatal obstruction. The Osaka-Kobe medical device cluster hosts catheter extrusion facilities serving domestic ambulatory networks.
India
CDSCO medical device rules are tightening import registration requirements for balloon dilation systems while domestic manufacturing incentives under the PLI scheme attract catheter assembly investments. Cost-sensitive procurement in tier-2 cities favors disposable balloon platforms over capital-intensive navigation systems. The Hyderabad medical technology corridor is emerging as a contract manufacturing hub for nitinol-reinforced catheter shafts.
Australia
TGA priority review pathways for minimally invasive ENT devices are compressing time-to-market for balloon catheter platforms with established European CE marking. Private health fund coverage policies favor same-day sinus procedures in independent day hospitals over overnight admissions. The Sydney-Melbourne corridor concentrates specialist ENT practice groups driving procedural volume concentration.
Sinus Dilation Devices Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform vendors capable of bundling navigation, dilation, and powered instrumentation within single-procedure contracts. Three strategic archetypes dominate: diversified medtech conglomerates with endoscopic ecosystems, standalone balloon catheter specialists with lean regulatory operations, and regional contract manufacturers serving private-label distributors. Competitive positioning hinges on M&A-driven technology integration and geographic expansion into ambulatory surgery center networks.
Within the diversified conglomerate tier, Johnson & Johnson Services Inc., Stryker, and Medtronic exemplify platform bundling strategies that combine navigation systems with disposable balloon catheters. These entities occupy positions shaped by integrated operating room contracts and sustained R&D intensity in powered instrumentation. Their geographic footprints span hospital purchasing committees and independent surgery center networks through differentiated service intensity models.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Stryker |
| Medtronic |
| Olympus Corporation |
| Smith & Nephew |
| Intersect ENT, Inc. |
| Dalent Medical |
| Meril Life Sciences Pvt. Ltd. |
| InnAccel Technologies Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in East Asian nitinol wire production is tightening input cost discipline for catheter shaft manufacturers while simultaneously elevating pricing leverage for shape-memory alloy suppliers serving balloon dilation device assemblers in the United States and Germany.
Pricing Analysis
Hospital purchasing committees anchor pricing negotiations for navigation-dilation bundles through transparent per-procedure economics that separate disposable catheter access from capital equipment attachments. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and electromagnetic tracking integration depth. Cost compression in standard-tier balloon platforms is intensifying because independent surgery centers in Texas and Florida negotiate unbundled procurement. Independent ambulatory operators demonstrate highest price sensitivity; academic medical centers with integrated OR contracts show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for nitinol-reinforced catheter platforms. Manufacturing concentrates in the United States, Germany, and Japan for precision molding and electromagnetic tracking assembly. Raw material dependencies center on nickel-titanium shape-memory wire, medical-grade silicone balloon membranes, and biocompatible catheter extrusion polymers. Single-source vulnerability in East Asian nitinol supply creates input volatility. Distribution runs through GPO contracts for hospital systems and direct inventory replenishment for independent surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional endoscopic sinus surgery techniques pose persistent substitution pressure that balloon dilation incumbents must neutralize through procedural efficacy demonstration and surgeon training capture.
For Market Incumbents: Entrench navigation-dilation bundling through electromagnetic tracking algorithm R&D investments that raise switching costs for hospital purchasing committees. Deepen backward integration into nitinol wire supply through captive sourcing agreements with East Asian metallurgical specialists. Neutralize FESS substitution threat by embedding balloon platforms into ENT residency curricula. For New Entrants and Emerging Players: Pursue Japanese ambulatory surgery center networks where METI-supported same-day procedure expansion outpaces established vendor service footprints. Target hybrid thermal-balloon white space in revision sinusitis cases where polyp recurrence demands integrated energy delivery. Deploy pay-per-procedure financing to circumvent capital barriers at independent Texas and Florida surgery centers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among standalone balloon catheter specialists with lean regulatory operations and established CPT reimbursement pathways. Long-term viability hinges on FDA 510(k) clearance velocity and ambulatory surgery center channel density. Monitor PMDA consultation pathway acceleration for hybrid thermal-balloon platforms as inflection signal for Asian market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Navigation-Dilation Integration | Electromagnetic tracking convergence enables premium pricing for revision procedure safety protocols. |
| Pay-per-Procedure Financing | Leasing model penetration unlocks independent surgery center access beyond integrated health system purchasing. |
| EU MDR Certification Investment | Notified body resource prioritization favors established players with dedicated regulatory affairs infrastructure. |
| Japanese Ambulatory Expansion | METI-supported same-day surgery initiatives create underpenetrated demand for outpatient-compatible platforms. |
| Nitinol Supply Backward Integration | Upstream control over shape-memory wire mitigates East Asian single-source vulnerability and input cost volatility. |
Methodological Framework
A standing panel of ENT surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, CMS Medicare procedure databases, hospital procurement registries, and ISO 13485 audit records. Bottom-up catheter platform volume estimates triangulated with top-down ambulatory surgery center capacity assessments.
Scenario-bracketing around site-neutral reimbursement acceleration and EU MDR certification friction anchored projection ranges across the analysis window. Segmentation dimensions modeled include product type, technology platform, end-user facility category, and application indication. CAGRs derived from procedural volume trajectory analysis incorporating chronic rhinosinusitis prevalence trends and insured population demographics.
Sensitivities concentrate around CMS site-of-service payment differential adjustments and nitinol alloy supply disruption. Forecasts reflect documented assumptions regarding ambulatory surgery center licensing permissiveness and CPT coding stability. Macroeconomic contraction, regulatory timeline extension, or hybrid thermal-balloon platform efficacy deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bunion Correction Systems Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Pipette Controllers Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Power Smart Bed Market
Medical Devices
Snare Devices Market
Medical Devices
Global Pupillometer Market
Medical Devices
Education Microscope Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
North America Wearable Medical Devices Market