
 Stent Delivery Systems Market | 2026-2036
Stent Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Stent Delivery Systems Market Outlook
Ambulatory surgical centers is restructuring the end-use mix for stent delivery systems as outpatient settings capture a rising share of percutaneous coronary interventions. Boston Scientific Corporation leverages its broad interventional cardiology portfolio to sustain catheter lab loyalty across integrated delivery networks. Medtronic Plc anchors its position through structural heart and coronary synergies that extend its device ecosystem into hybrid operating rooms. Abbott Laboratories differentiates via proprietary balloon and self-expanding platforms that occupy premium tiers in hospital purchasing matrices.
Stent delivery systems are catheter-based devices engineered to transport and deploy vascular or non-vascular stents through guidewire lumens with balloon inflation or self-expanding mechanisms, typically constructed from polymer shafts, radiopaque markers, and hydrophilic coatings to achieve trackability through tortuous anatomy. Drug-eluting platforms command concentrated R&D investment as polymer coating chemistries and antiproliferative agent release kinetics define clinical differentiation. Balloon-expandable configurations dominate coronary applications where precise diameter control matters, while self-expanding systems lead in peripheral and carotid territories where vessel conformability shapes outcomes. Percutaneous deployment mode generates the highest procedure volume across hospitals and ambulatory surgical centers, though hybrid approaches are gaining traction in complex structural heart interventions.
FDA premarket notification and EU MDR conformity assessment processes govern market access timelines and clinical evidence requirements for stent delivery systems, with FDA's breakthrough device designation pathway accelerating review for innovations addressing unmet coronary needs. Japan's PMDA and China's NMPA impose supplementary local testing protocols that fragment registration strategies for multinational manufacturers. Stakeholders must monitor evolving reimbursement thresholds for same-day discharge procedures and the pace of bioabsorbable scaffold platform maturation.
Market Dynamics
Outpatient reimbursement frameworks are accelerating the migration of percutaneous coronary interventions from hospital catheterization laboratories to ambulatory surgical centers, compressing capital equipment cycles and forcing manufacturers to reconfigure device portfolios for same-day discharge protocols.
Growth Catalysts
- Same-day discharge reimbursement:CMS outpatient prospective payment system expansions in the United States are channeling PCI volume toward ambulatory surgical centers, creating dedicated device procurement streams.
- Polymer coating chemistries:Advanced drug-eluting platforms with tunable antiproliferative release kinetics are extending lesion-free survival metrics and commanding premium placement in integrated delivery network purchasing matrices.
- Japan's PMDA accelerated review pathways:Conditional early approval frameworks for breakthrough coronary devices are truncating market access timelines and incentivizing Japanese clinical trial investment.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply concentrates among a limited set of specialty metallurgical processors, exposing self-expanding stent delivery system manufacturers to input volatility and qualification bottlenecks.
- EU MDR clinical evidence requirements:Conformity assessment timelines for legacy coronary devices have extended substantially, freezing product line extensions and consuming notified body capacity.
- Bioabsorbable scaffold performance limitations:Scaffold thrombosis and mechanical integrity failures in coronary applications have chilled physician enthusiasm and redirected R&D investment toward metallic platforms.
Strategic Opportunities
- Peripheral artery disease expansion:Below-the-knee and femoropopliteal interventions remain underpenetrated relative to coronary procedures, offering volume growth for trackable, low-profile delivery systems.
- Hybrid operating room convergence:Structural heart programs combining surgical and interventional capabilities are creating demand for stent delivery systems compatible with fluoroscopy-C-arm integration and robotic navigation platforms.
- China NMPA innovation fast-track:Priority review pathways for domestically manufactured Class III cardiovascular devices are incentivizing local production partnerships and abbreviated registration strategies.
Industry Challenges
- Interventional cardiologist training pipelines:Fellowship program output is not keeping pace with PCI volume expansion, stretching operator availability and compressing proctoring capacity for complex lesion subsets.
- Cross-border sterilization validation:Ethylene oxide and radiation sterilization protocol harmonization across FDA, EU MDR, and NMPA jurisdictions is extending supply chain qualification timelines and inflating validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stent Delivery Systems Market |
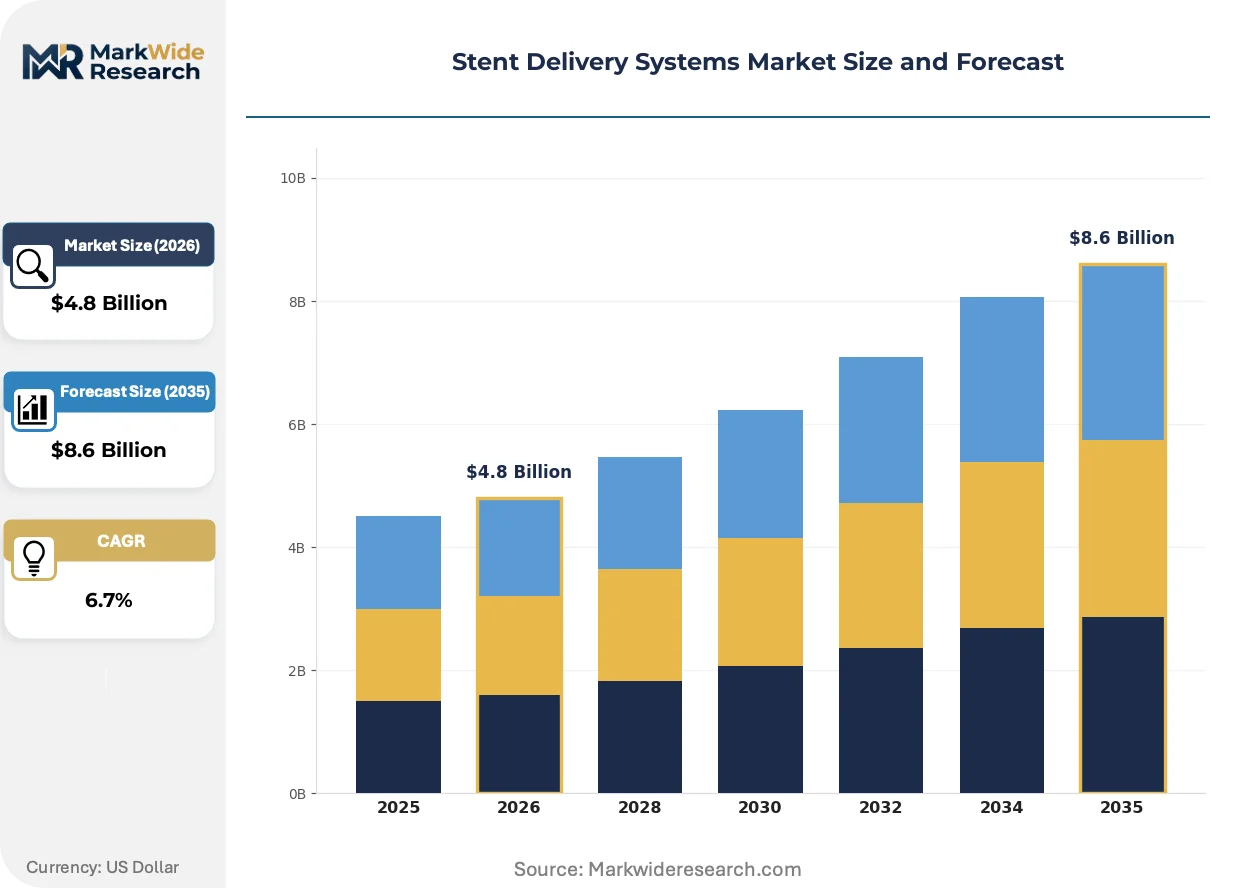
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon-Expandable, Self-Expanding, Bioabsorbable, Drug-Eluting End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Deployment Mode: Percutaneous, Surgical, Hybrid, Transcatheter Material: Polymer, Metal, Composite, Coated |
| Companies Covered | Boston Scientific Corporation, Medtronic Plc, Abbott Laboratories, B. Braun Melsungen AG, Terumo Corporation, Stryker Corporation, Becton, Dickinson and Company, Svelte Medical, ELLA - CS, s.r.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stent Delivery Systems Market Strategic Shifts
Device miniaturization and intelligent delivery mechanisms are converging to reshape competitive positioning, with manufacturers racing to integrate sensing capabilities and automated deployment features into next-generation catheter platforms.
Robotic-assisted PCI navigation systems are expanding into high-volume catheterization laboratories as integrated health networks seek to standardize procedural outcomes and reduce operator radiation exposure. Hospital systems in the United States are piloting these platforms for chronic total occlusion and bifurcation lesions where manual wire manipulation demands exceptional skill. The structural consequence is compressing the addressable market for conventional over-the-wire delivery systems in complex lesion subsets.
EU MDR Article 10 post-market surveillance requirements are mandating systematic implant registry participation and periodic safety update reporting for all coronary stent delivery systems. Manufacturers must now maintain dedicated vigilance systems and contract with notified bodies for ongoing conformity audits. High-risk device categories face the steepest compliance burden, with several firms withdrawing legacy product lines rather than absorbing clinical evidence generation costs.
Integrated delivery networks are consolidating stent procurement under centralized value analysis committees that unbundle device selection from physician preference items. Hospital supply chain directors now negotiate multi-year sole-source agreements with tiered performance guarantees. This concentration is most visible across United States metropolitan markets where three-system networks control the majority of PCI volume and standardize on limited device form factors.
Stent Delivery Systems Market Segmentation
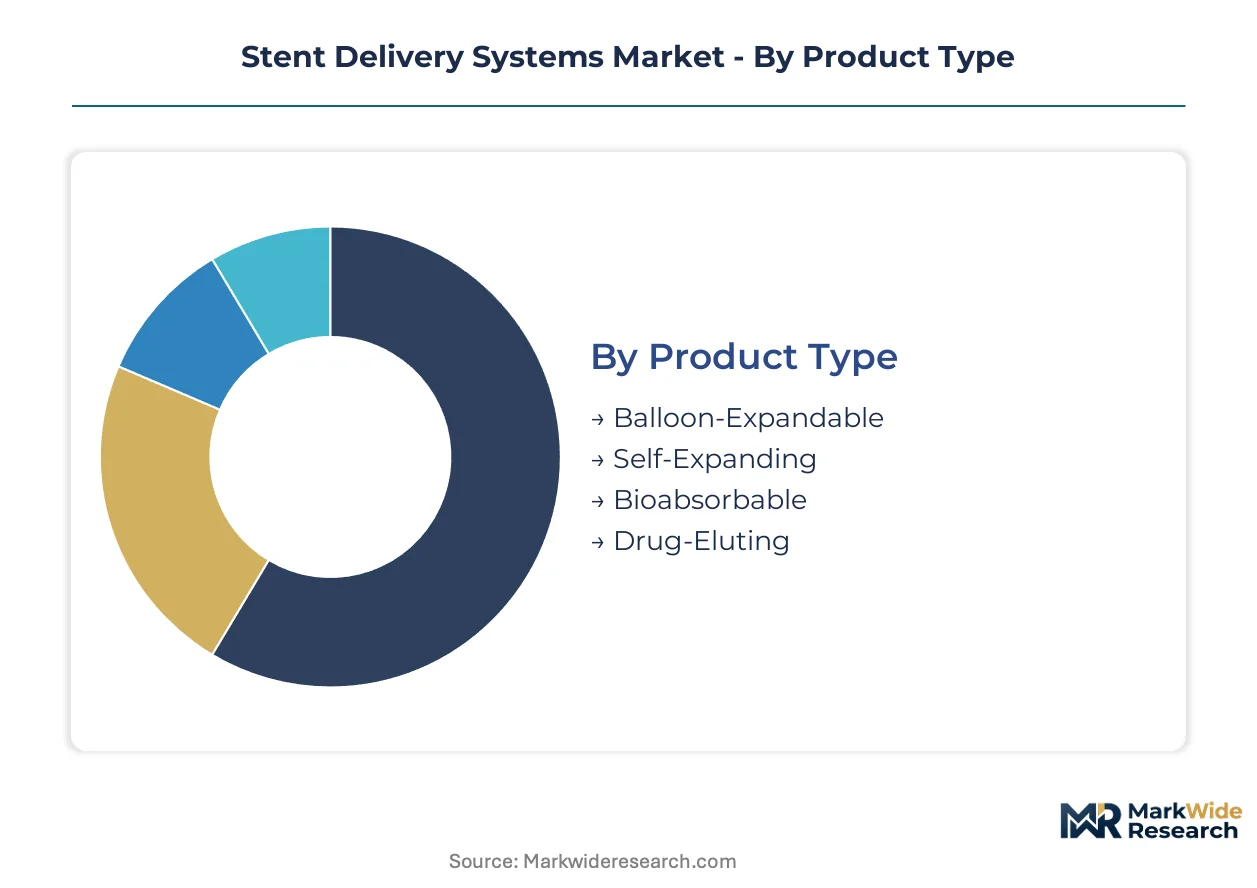
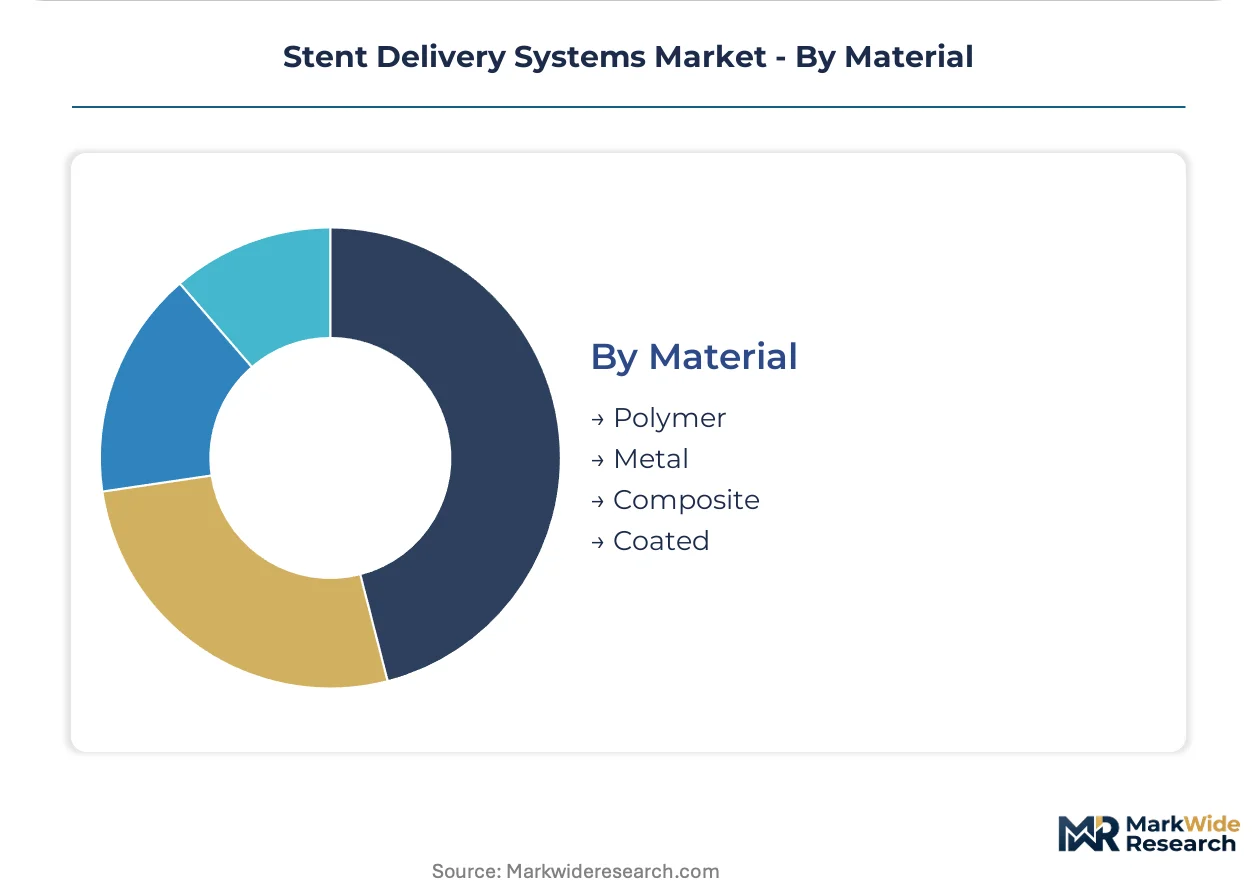
Stent delivery system segmentation reveals how regulatory pathways, reimbursement structures, and procedural settings fragment procurement strategies across device categories. Manufacturers must align product development with distinct clinical evidence requirements and capital equipment cycles governing each segment.
Product Type:
FDA premarket notification and EU MDR conformity assessment timelines vary sharply across these platforms, with drug-eluting configurations demanding the most extensive clinical dossiers and bioabsorbable scaffolds facing heightened scrutiny.
- Balloon-Expandable:Polymer balloon catheters with stainless steel or cobalt-chromium stent crimping deliver precise diameter control through hydraulic inflation. Demand concentrates in United States hospital catheterization laboratories where PCI volume justifies dedicated inventory systems and same-day discharge protocols.
- Self-Expanding:Nitinol superelastic alloys enable radial force deployment without balloon inflation, optimizing conformability in tortuous peripheral and carotid anatomy. European vascular surgery programs and Japanese neurointerventional suites drive procurement as below-the-knee intervention volumes expand.
- Bioabsorbable:Poly-L-lactic acid and magnesium alloy scaffolds face stalled commercial traction after scaffold thrombosis events chilled physician adoption.
- Drug-Eluting:Polymer coating chemistries with sirolimus analog release kinetics command premium tier placement in integrated delivery network purchasing matrices.
Leading the category by volume: Balloon-Expandable. Growing fastest: Self-Expanding.
End User:
Capital equipment intensity and reimbursement frameworks create distinct procurement rhythms across settings, with ambulatory surgical centers compressing device selection cycles as outpatient PCI migrates from hospital campuses.
- Hospitals:Integrated catheterization laboratories with hybrid operating room capabilities maintain the broadest device form factor inventories. United States metropolitan health systems anchor volume through high-complexity chronic total occlusion and bifurcation lesion programs.
- Ambulatory Surgical Centers:Streamlined same-day discharge protocols favor low-profile, rapid-exchange delivery systems with minimal sterilization infrastructure. CMS outpatient prospective payment system expansions are accelerating dedicated procurement streams.
- Specialty Clinics:Peripheral vascular and structural heart focused facilities concentrate demand for trackable, hydrophilic-coated platforms.
- Research Institutions:Academic medical centers with investigational device exemption pathways pilot next-generation robotic navigation and sensing-integrated delivery mechanisms.
Hospitals retain the dominant volume position. Ambulatory Surgical Centers are climbing the fastest as reimbursement shifts.
Deployment Mode:
Procedural complexity and operator training requirements stratify addressable markets, with percutaneous approaches generating scale economics that hybrid and transcatheter modes cannot yet match.
- Percutaneous:Guidewire-based femoral or radial access generates the highest procedure volume across all geographies. United States interventional cardiology fellowship programs standardize on this modality, entrenching device familiarity and inventory commitments.
- Surgical:Open vessel exposure for direct stent deployment persists in emergent trauma and failed endovascular salvage scenarios.
- Hybrid:Combined surgical cutdown with fluoroscopic guidance demands C-arm integration and specialized operating room infrastructure.
- Transcatheter:Structural heart applications including transcatheter aortic valve replacement utilize adapted delivery platforms with larger French sizes.
Percutaneous deployment commands the volume lead. Hybrid approaches are gaining share fastest in structural heart convergence.
Material:
Raw material qualification and sterilization validation costs concentrate competitive advantage among manufacturers with captive metallurgical processing or polymer synthesis capabilities.
- Polymer:PEBAX and nylon shaft materials with hydrophilic coatings optimize trackability through calcified lesions. Japanese PMDA and China NMPA impose distinct biocompatibility testing protocols that fragment registration strategies.
- Metal:Stainless steel, cobalt-chromium, and platinum-iridium radiopaque markers dominate balloon-expandable coronary platforms. Nitinol supply concentrates among limited specialty processors, exposing self-expanding manufacturers to input volatility.
- Composite:Braided wire-reinforced polymer shafts balance pushability and flexibility for complex chronic total occlusion cases.
- Coated:Drug-polymer matrix surfaces with tunable release kinetics define clinical differentiation in premium tier placements.
Metal platforms lead by procedure volume. Composite materials are expanding most quickly as lesion complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Malaysia are concentrating catheter manufacturing capacity as multinationals seek FDA-aligned regulatory environments with labor cost advantages.
United States
Integrated health networks in metropolitan markets centralize high-volume catheterization laboratory procurement under value analysis committees. FDA breakthrough device designation pathways accelerate review timelines for innovations addressing unmet coronary needs. The Minneapolis-St. Paul corridor anchors nitinol processing and polymer shaft fabrication for self-expanding platforms.
Germany
EU MDR conformity assessment timelines have extended substantially for legacy coronary devices, freezing product line extensions. The country's notified bodies consume capacity processing post-market surveillance requirements under Article 10. Baden-Württemberg's precision engineering clusters supply braided wire-reinforced catheter shafts to hybrid operating room programs.
Japan
PMDA conditional early approval frameworks for breakthrough coronary devices truncate market access timelines. Local testing protocols for polymer biocompatibility fragment registration strategies for multinational manufacturers. Tokyo and Osaka metropolitan areas concentrate fellowship-trained interventional cardiologists driving percutaneous procedure volume.
China
NMPA priority review pathways for domestically manufactured Class III cardiovascular devices incentivize local production partnerships. Dual carbon goals and environmental compliance are reshaping sterilization facility siting decisions. The Yangtze River Delta medical device zones host contract manufacturers serving multinational catheter assembly programs.
India
CDSCO medical device rules are converging toward risk-based classification harmonized with IMDRF principles. PLI scheme incentives for domestic manufacturing of high-value medical devices are attracting catheter assembly investments. Hyderabad and Bengaluru clusters concentrate contract research organizations supporting multinational clinical trial programs for coronary interventions.
Stent Delivery Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated delivery network procurement concentration favoring full-portfolio suppliers over niche component vendors. The vendor base organizes into three tiers: multinational device ecosystems with catheter lab loyalty programs, regional specialists with regulatory speed advantages, and contract manufacturers supplying private-label platforms. Dominant competitive moves include strategic partnerships with ambulatory surgical center chains and backward integration into nitinol metallurgical processing to secure raw material qualification.
Within the multinational ecosystem tier, Boston Scientific Corporation, Medtronic Plc, and Abbott Laboratories occupy positions defined by catheter laboratory relationship depth and interventional cardiology portfolio breadth. These entities exemplify the integrated device ecosystem archetype where structural heart and coronary synergies extend platform reach into hybrid operating rooms. Their positioning reflects the premium-tier procurement dynamics of United States metropolitan health systems where sole-source agreements with performance guarantees standardize device form factors across network facilities.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic Plc |
| Abbott Laboratories |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Stryker Corporation |
| Becton, Dickinson and Company |
| Svelte Medical |
| ELLA - CS, s.r.o. |
| Others |
Value Chain & Pricing Dynamics
Fellowship-trained interventional cardiologist concentration in United States metropolitan corridors and Costa Rican catheter assembly labor pools creates cost-of-production differentials that stratify pricing tiers across balloon-expandable and self-expanding platforms.
Pricing Analysis
Short lead-time premiums for nitinol self-expanding systems and spot-inventory discounts for legacy balloon-expandable configurations dominate transaction structures. Three-tier pricing structure across premium drug-eluting, standard bare-metal, and economy private-label tiers separates procurement matrices by clinical evidence depth and coating sophistication. Cost compression in economy tiers is intensifying because ambulatory surgical center chains negotiate multi-year volume commitments. Integrated delivery networks show lowest price sensitivity for robotic-compatible delivery systems, while independent specialty clinics drive hardest bargain on rapid-exchange platforms.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital value analysis committees and European notified body qualification requirements force manufacturers to maintain redundant nitinol processors and polymer shaft fabricators. Supply concentrates in Costa Rica, Malaysia, and the Minneapolis-St. Paul corridor for catheter assembly and metallurgical processing. Nitinol superelastic alloy, PEBAX shaft polymers, and platinum-iridium radiopaque markers anchor bill-of-materials exposure. Single-source vulnerability in specialty nitinol qualification creates supply chain risk. Distribution runs through GPO contracts managers and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 10 post-market surveillance mandates and FDA breakthrough device evidentiary thresholds erect compliance cost barriers that favor incumbents with dedicated regulatory affairs infrastructure and freeze out undercapitalized entrants.
For Market Incumbents: Anticipate robotic-assisted PCI platform displacement of conventional over-the-wire systems in chronic total occlusion segments by deepening backward integration into nitinol metallurgical processing and securing captive polymer synthesis capacity. Hospital system sole-source agreement consolidation threatens component vendor margins; defend via catheter lab loyalty programs bundling structural heart and coronary portfolios. For New Entrants and Emerging Players: Launch via private-label contract manufacturing partnerships serving United States ambulatory surgical center chains with streamlined same-day discharge protocols. Below-the-knee peripheral artery disease interventions and China NMPA fast-track domestic manufacturing partnerships represent the most penetrable white-space targets. Reimbursement strategy development for outpatient PCI migration offers differentiated go-to-market positioning. For Investors and Strategic Acquirers: Re-rating potential sits with nitinol-integrated mid-cap specialists given EU MDR notified body capacity constraints and legacy product line withdrawal waves. Long-term viability hinges on sterilization protocol harmonization capabilities and robotic navigation platform compatibility. Watch interventional cardiologist fellowship program output as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 10 Compliance Investment | Notified body audit capacity scarcity freezes competitor product line extensions. |
| Robotic Navigation Platform Partnership | Fluoroscopy-C-arm integration demands reshape catheter lab equipment procurement. |
| Nitinol Metallurgical Backward Integration | Captive superelastic alloy processing insulates against specialty processor bottlenecks. |
| Ambulatory Surgical Center Chain Alliance | CMS outpatient reimbursement expansion channels PCI volume to dedicated procurement streams. |
| China NMPA Domestic Manufacturing Joint Venture | Priority review pathways for Class III cardiovascular devices accelerate market access timelines. |
Study Parameters
FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, and CMS outpatient prospective payment system documentation formed the secondary backbone. Primary interviews with interventional cardiologists, hospital value analysis committee directors, GPO contracts managers, and biomedical engineering procurement leads combined with secondary validation. Bottom-up and top-down triangulation anchored volume estimates.
Bottom-up procedure volume modeling by deployment mode, product type, and end-use setting combined with top-down integrated delivery network purchasing matrix analysis across the projection horizon. Segmentation dimensions included balloon-expandable versus self-expanding platforms, hospital versus ambulatory surgical center settings, and percutaneous versus hybrid deployment approaches. CAGRs derived from procedure volume trajectories and device ASP erosion patterns. Forecast inputs incorporated PMDA accelerated review pathway utilization rates and NMPA domestic manufacturing incentive uptake.
EU MDR notified body capacity constraints, bioabsorbable scaffold clinical trial failure rates, and ambulatory surgical center reimbursement threshold adjustments are the dominant revision risks. Deviation in EU MDR Article 10 post-market surveillance audit timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Global Refractive Surgery Devices Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Prescription Lens Market
Medical Devices
Gamma Knife Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Spine Surgery Robots Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
Implantable Port Market