
 Global Regulatory Affairs Market | 2026-2036
Global Regulatory Affairs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Regulatory Affairs Market Foresight
A shortage of specialized regulatory scientists is reorganizing how sponsors access submission expertise. IQVIA leverages its global consultant network to anchor large-scale pharmaceutical engagements across multiple jurisdictions. ICON plc competes through integrated clinical and regulatory service bundles that sustain client retention. PAREXEL International Corporation specializes in rare disease regulatory pathways where expertise scarcity commands premium positioning.
Regulatory affairs encompasses the strategic management of product compliance with health authority requirements, spanning chemistry, manufacturing, and controls documentation through post-market surveillance protocols. The discipline ensures market authorization, risk mitigation, and ongoing adherence to evolving safety standards for commercialized therapeutics and devices. Pharmaceuticals dominates sector demand due to pipeline complexity and the volume of investigational new drug applications requiring structured guidance. Medical Devices is expanding fastest as software-as-a-medical-device classifications and EU MDR transition create urgent compliance backlogs. Regulatory Consulting captures the largest margin pool within service types, particularly for first-time filers navigating novel therapeutic categories.
FDA, EMA, and WHO frameworks collectively shape submission standards, inspection protocols, and pharmacovigilance reporting requirements that determine market access timelines. The EU AI Act and FDA's emerging guidance on machine learning-enabled devices are introducing new validation layers that expand scope for regulatory technology integration. Stakeholders must decide whether to build captive regulatory capabilities or deepen outsourcing partnerships as submission complexity outpaces internal talent development.
Market Dynamics
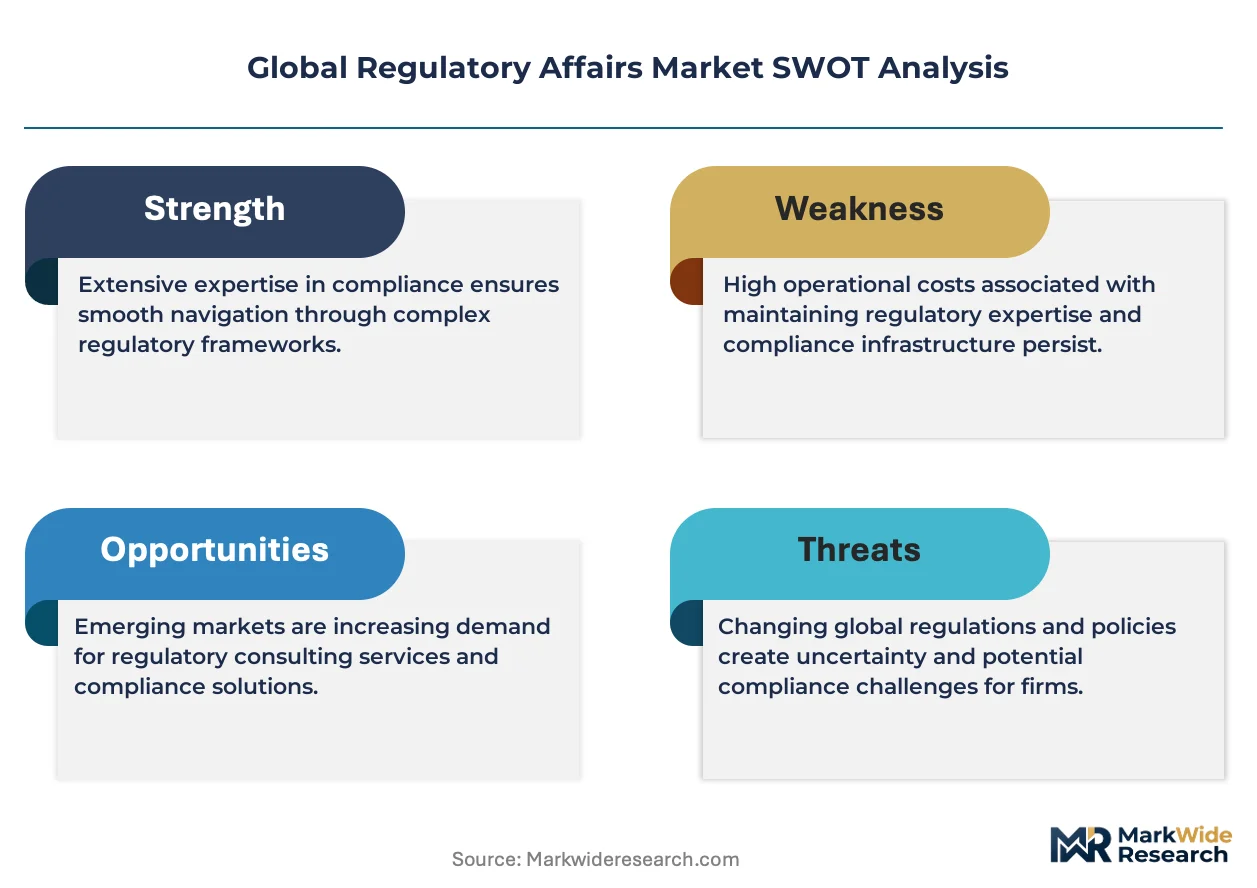
The EU MDR transition deadline and FDA's digital health guidance expansion are compressing submission timelines while fragmenting expertise availability across sponsor organizations.
Growth Catalysts
- EU MDR Compliance Deadlines:Medical device manufacturers face mandatory recertification requirements that expand demand for clinical evaluation report specialists and notified body liaison services.
- Software-as-a-Medical-Device Classifications:FDA's evolving framework for machine learning-enabled diagnostics creates new submission pathways requiring algorithm validation documentation and real-world performance monitoring protocols.
- Biopharmaceutical Pipeline Complexity:Cell and gene therapy submissions to FDA and EMA demand novel chemistry, manufacturing, and controls strategies that outpace internal regulatory capacity at emerging sponsors.
Market Restraints
- Specialized Talent Scarcity:Experienced regulatory scientists with FDA advisory committee presentation experience command compensation premiums that strain mid-tier service provider margins.
- Notified Body Capacity Bottlenecks:European Union medical device recertification queues extend 12-18 months as designated organizations struggle to expand technical reviewer headcount.
- Submission Fee Escalation:FDA prescription drug user fee act reauthorization raises program application costs for small and mid-size sponsors seeking initial market authorization.
Strategic Opportunities
- India CDSCO Harmonization:India's adoption of ICH E6 guidelines for clinical trial conduct creates demand for regulatory consulting services bridging US FDA and local submission requirements.
- Real-World Evidence Integration:Convergence of electronic health record analytics and regulatory submission protocols enables post-market surveillance automation for medical device manufacturers.
- EU AI Act Validation Services:High-risk healthcare algorithm deployments require conformity assessments that expand scope for regulatory technology platforms integrating technical documentation workflows.
Industry Challenges
- Cross-Functional Coordination Gaps:Clinical operations and regulatory affairs teams operate on misaligned timelines that compress quality control review windows before submission deadlines.
- Legacy System Interoperability:Sponsor document management platforms lack API connectivity with health authority electronic submission gateways, requiring manual metadata reconciliation.
- Pharmacovigilance Signal Detection:Adverse event reporting volume growth outpaces case processing automation, creating compliance exposure during FDA inspection cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Regulatory Affairs Market |
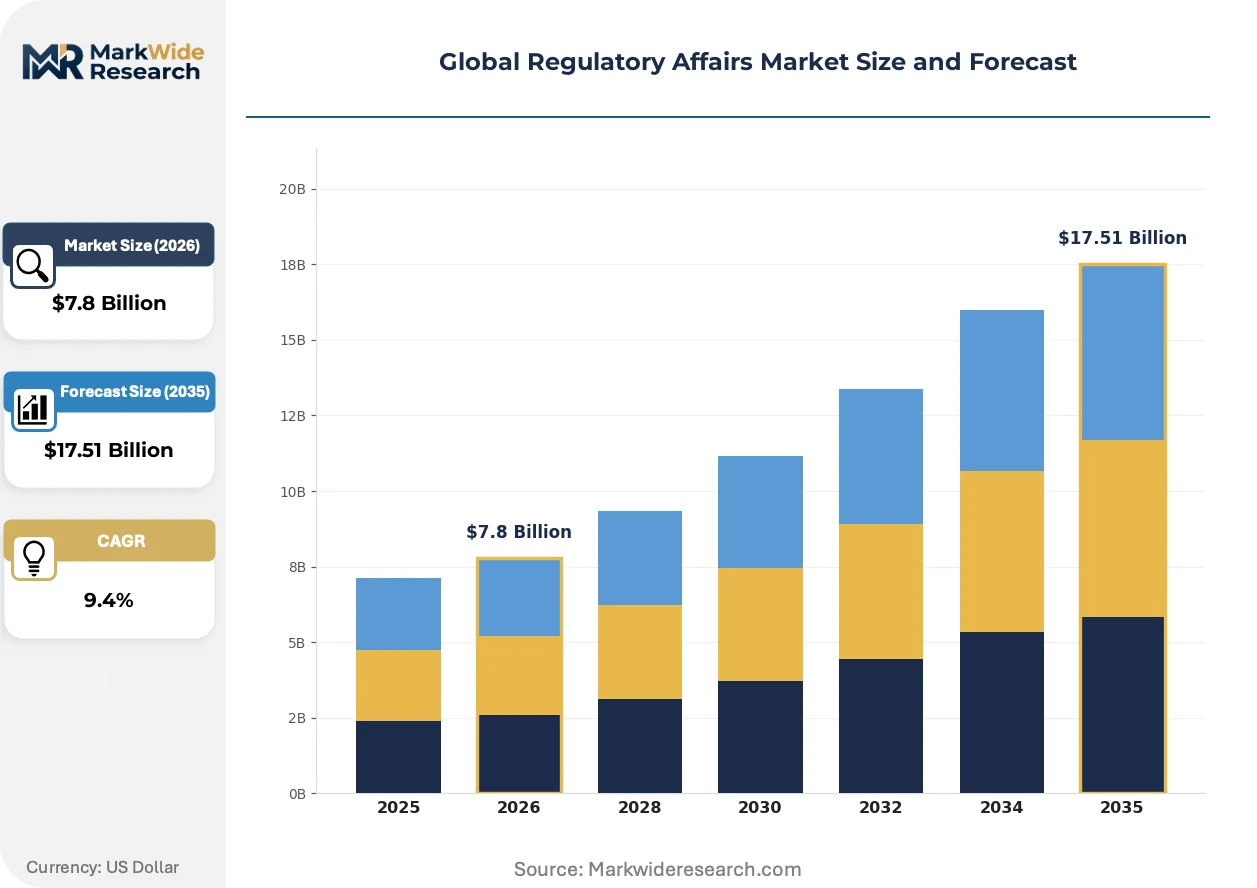
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sector: Pharmaceuticals, Biotechnology, Medical Devices, Cosmetics, Chemicals Service Type: Regulatory Consulting, Compliance Management, Submissions & Filings, Auditing & Inspection Support, Labeling & Documentation Client Type: Startups, Contract Research Organizations, Manufacturers, Distributors, Government Agencies Technology Adoption: Cloud-based Solutions, Electronic Document Management, Artificial Intelligence, Blockchain, Data Analytics |
| Companies Covered | IQVIA, ICON plc, PAREXEL International Corporation, WuXi AppTec, Medpace, Charles River Laboratories, Labcorp, Freyr, Genpact, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Regulatory Affairs Market Shifts & Advancements
Regulatory technology platforms are displacing document-centric workflows with structured data architectures that compress submission preparation cycles and enable real-time health authority collaboration.
Artificial intelligence document generation is fragmenting traditional medical writing service models. Natural language processing tools extract clinical study report components from structured datasets, reducing narrative drafting cycles for FDA 505(b)(2) submissions. Large pharmaceutical sponsors deploy these capabilities in-house while mid-tier sponsors access them through specialized regulatory consulting partnerships.
EMA's extended mandate for pediatric investigation plans and FDA's project optima dose optimization requirements are reshaping early-phase clinical development strategies. Sponsors now embed regulatory scientists into protocol design teams before first-in-human studies to anticipate health authority feedback on trial endpoints and comparator selections. Oncology and rare disease programs face the steepest documentation burden under these expanded requirements.
Biopharmaceutical procurement patterns favor outcome-linked regulatory service contracts that tie vendor compensation to submission acceptance milestones rather than time-and-materials billing. Sponsor finance teams pressure regulatory affairs leadership to convert fixed consulting costs to variable structures aligned with pipeline progression. This shift concentrates contract awards among service providers with demonstrated FDA breakthrough therapy designation and EMA PRIME eligibility track records.
Global Regulatory Affairs Market Segmentation

Regulatory affairs services fragment across specialized domains where substitution pressures vary sharply. Sponsors select engagement models based on internal capability gaps, submission complexity, and health authority jurisdiction requirements.
Sector:
Pharmaceuticals faces the strongest substitution threat as sponsors build captive regulatory teams for repeat FDA and EMA submissions.
- Pharmaceuticals:Small-molecule and biologic submissions dominate service demand. Chemistry, manufacturing, and controls documentation for FDA 505(b)(1) and 505(b)(2) pathways absorbs the largest consulting hours. United States sponsors concentrate spending here due to prescription drug user fee act timelines.
- Medical Devices:EU MDR recertification and software-as-a-medical-device classifications create urgent compliance backlogs. Germany and France manufacturers drive demand for notified body liaison services as technical reviewer queues extend.
- Biotechnology:Cell and gene therapy sponsors require novel regulatory strategies for breakthrough therapy designation pathways.
- Cosmetics:EU Cosmetics Regulation compliance and emerging MoCRA requirements in the United States shape formulation documentation needs.
- Chemicals:REACH registration dossiers and ECHA substance evaluation responses command specialized toxicology expertise.
Pharmaceuticals retains volume leadership; Medical Devices holds the steepest expansion curve.
Service Type:
Cost tier stratification separates premium advisory from commoditized compliance monitoring.
- Regulatory Consulting:Strategic advisory for novel therapeutic categories and first-time filers commands the highest margins. FDA advisory committee preparation and EMA scientific advice meeting support concentrate among elite practitioners. Sponsors in the United States pay premiums for breakthrough therapy designation navigation.
- Submissions & Filings:Structured authoring of investigational new drug applications, marketing authorization applications, and 510(k) premarket notifications forms the core revenue base. Japan PMDA and China NMPA submissions require local regulatory intelligence partnerships.
- Compliance Management:Ongoing pharmacovigilance and post-market surveillance outsourcing.
- Auditing & Inspection Support:Mock FDA inspections and EMA good manufacturing practice readiness assessments.
- Labeling & Documentation:Package insert drafting and multi-jurisdictional label harmonization.
Submissions & Filings generates the highest absolute revenue; Regulatory Consulting delivers the widest margin differential.
Client Type:
Application maturity determines whether clients seek transactional support or embedded partnerships.
- Manufacturers:Large pharmaceutical and device companies maintain hybrid models blending internal staff with outsourced surge capacity for major submissions. Their procurement teams pressure vendors toward outcome-linked contracts tied to FDA acceptance milestones.
- Startups:Emerging sponsors lack regulatory infrastructure entirely. First-in-human study applications and initial IND filings absorb their limited consulting budgets. United States biotech clusters in Boston and San Francisco concentrate this demand.
- Contract Research Organizations:CROs bundle regulatory services with clinical trial execution.
- Distributors:Import license maintenance and local authorized representative obligations.
- Government Agencies:Capacity-building support for national regulators adopting ICH guidelines.
Manufacturers account for the largest contract value; Startups provide the fastest client acquisition velocity.
Technology Adoption:
Supply concentration among platform vendors shapes deployment patterns across sponsor tiers.
- Electronic Document Management:Structured data architectures for eCTD submissions displace legacy document-centric workflows. FDA electronic submission gateway integration and EMA common technical document compliance drive replacement cycles. Mid-tier sponsors in Germany and Switzerland lag in adoption.
- Artificial Intelligence:Natural language processing tools extract clinical study report components and automate narrative drafting for 505(b)(2) submissions. Large United States sponsors deploy in-house; others access through consulting partnerships.
- Cloud-based Solutions:Multi-site collaboration platforms for distributed regulatory teams.
- Blockchain:Immutable audit trails for clinical trial documentation integrity.
- Data Analytics:Real-world evidence integration for post-market surveillance automation.
Electronic Document Management holds installed base dominance; Artificial Intelligence is climbing the fastest adoption trajectory.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory affairs consumption patterns diverge sharply by jurisdiction complexity. The United States concentrates spending on FDA advisory committee preparation and breakthrough therapy designation navigation. Germany and Switzerland anchor European demand around EMA centralized procedures and notified body liaison services. India and China represent the fastest expansion vectors as local sponsors adopt ICH guidelines and multinational sponsors require bridge submission strategies.
United States
FDA prescription drug user fee act timelines and breakthrough therapy designation pathways absorb the largest consulting budgets. Cell and gene therapy sponsors in Greater Boston and San Francisco drive demand for novel chemistry, manufacturing, and controls strategies. The FDA's evolving digital health guidance for machine learning-enabled devices creates algorithm validation documentation requirements that outpace internal regulatory capacity.
Germany
EU MDR recertification queues and notified body capacity bottlenecks concentrate demand for technical file preparation and clinical evaluation report specialists. Munich and Berlin host the densest clusters of medical device manufacturers facing mandatory recertification deadlines. EMA scientific advice meeting support and pediatric investigation plan navigation command premium positioning among local regulatory consultancies.
Switzerland
Swissmedic alignment with EU regulatory frameworks and third-country manufacturer obligations sustain cross-border submission activity. Basel and Zurich anchor biopharmaceutical regulatory operations for sponsors seeking EMA parallel consultation pathways. The country's dual EU-EFTA positioning creates specialized demand for marketing authorization application strategies spanning both jurisdictions.
India
CDSCO adoption of ICH E6 guidelines and local clinical trial conduct rules expand demand for regulatory consulting bridging US FDA and Indian submission requirements. Hyderabad and Mumbai biotech clusters drive first-in-human study application preparation for emerging sponsors. The country's pharmaceutical export orientation sustains long-term demand for US FDA and EMA dossier development capabilities.
China
NMPA marketing authorization reforms and international multi-center clinical trial acceptance reshape submission strategies for multinational sponsors. Shanghai and Beijing regulatory operations centers manage chemistry, manufacturing, and controls documentation for global development programs. The country's innovation-focused drug review pathways create demand for local regulatory intelligence partnerships.
Global Regulatory Affairs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in regulatory affairs services. Large contract research organizations leverage clinical trial execution relationships to bundle regulatory consulting and capture multi-year pharmaceutical engagements. Boutique regulatory consultancies compete through FDA advisory committee presentation expertise and rare disease pathway specialization. Strategic moves concentrate on outcome-linked contract structures and regulatory technology platform integration.
Within the integrated service provider tier, IQVIA, ICON plc, and PAREXEL International Corporation occupy anchor positions. IQVIA exemplifies the global network model, deploying consultant resources across FDA, EMA, and emerging market jurisdictions. ICON plc represents the clinical-regulatory bundle archetype, sustaining client retention through seamless trial execution and submission preparation. PAREXEL International Corporation anchors the specialized pathway segment, commanding premium positioning in breakthrough therapy designation and rare disease regulatory navigation where expertise scarcity limits competition.
| Leading Market Players |
|---|
| IQVIA |
| ICON plc |
| PAREXEL International Corporation |
| WuXi AppTec |
| Medpace |
| Charles River Laboratories |
| Labcorp |
| Freyr |
| Genpact |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance tiers and EU MDR conformity assessment routes gate both supplier qualification and price differentiation simultaneously. Sponsors seeking breakthrough therapy designation navigation pay premiums for advisory scientists with FDA advisory committee experience, while notified body liaison services for EU MDR recertification command surcharges as technical reviewer queues extend.
Pricing Analysis
Project-based contracts dominate regulatory affairs engagements, with outcome-linked structures tying vendor compensation to FDA acceptance milestones gaining share from time-and-materials billing. Price differentiation rests on certification depth — FDA breakthrough therapy designation expertise and EMA PRIME eligibility navigation command tier-one premiums, while standardized IND filing support competes on volume scale. Pricing pressure stems from sponsor procurement teams converting fixed consulting costs to variable structures aligned with pipeline progression. Startups exhibit the highest price sensitivity due to limited first-in-human study budgets, whereas large pharmaceutical manufacturers prioritize demonstrated track records over unit cost.
Supply Chain Analysis
Inventory cycles for regulatory talent extend 12-18 months as experienced scientists with FDA advisory committee presentation experience command compensation premiums that strain mid-tier service provider margins. Supply concentrates in the United States, Germany, and Switzerland, where dense clusters of pharmaceutical and device manufacturers sustain consulting demand. Raw material inputs draw from specialized toxicology expertise, clinical evaluation report specialists, and algorithm validation documentation capabilities for machine learning-enabled devices. Single-source vulnerability runs through notified body capacity bottlenecks as designated organizations struggle to expand technical reviewer headcount. Distribution runs through direct enterprise sales relationships and CRO bundled offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory affairs services are entering a cyclical recovery phase as EU MDR recertification deadlines and FDA digital health guidance expansion compress submission timelines and expand outsourcing demand.
For Market Incumbents: Fortify regulatory technology platform integration to automate document-centric workflows and compress submission preparation cycles. Deepen captive consulting networks across FDA, EMA, and emerging market jurisdictions to anchor multi-year pharmaceutical engagements. Vertical integration into AI-powered medical writing tools defends margin position against specialized regulatory technology entrants. For New Entrants and Emerging Players: Lead with EU AI Act validation services for high-risk healthcare algorithm deployments, where conformity assessment demand outpaces established provider capacity. Target India CDSCO harmonization consulting as local sponsors adopt ICH E6 guidelines and require bridge strategies spanning US FDA and Indian submission requirements. A software-as-a-medical-device specialization offers the most penetrable entry vector given FDA's evolving framework for machine learning-enabled diagnostics. For Investors and Strategic Acquirers: FDA's emerging guidance on machine learning-enabled devices reshapes the acquisition landscape toward regulatory technology platforms with algorithm validation documentation capabilities. Five-to-ten year viability favors vertically integrated service providers combining clinical trial execution with submission preparation. Boutique consultancies with rare disease regulatory pathway expertise and demonstrated breakthrough therapy designation track records represent priority acquisition archetypes. The signal to monitor is FDA inspection backlog clearance rates as an indicator of sponsor outsourcing urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Platform Integration | Structured data architectures displace document-centric workflows and compress FDA submission preparation cycles. |
| Outcome-Linked Contract Structuring | Tying vendor compensation to FDA acceptance milestones aligns consulting costs with pipeline progression. |
| EU MDR Recertification Service Expansion | Notified body liaison services command premiums as technical reviewer queues extend across Germany and France. |
| AI Document Generation Capability | Natural language processing tools extract clinical study report components and automate 505(b)(2) narrative drafting. |
| Emerging Market Regulatory Bridge Services | India CDSCO and China NMPA harmonization consulting captures demand from sponsors requiring multi-jurisdictional strategies. |
Research Methodology
Operator-level perspectives from regulatory affairs directors, drug development executives, notified body technical reviewers, and sponsor procurement managers anchored the qualitative base. Primary interviews combined with secondary validation across FDA 510(k) filings, EMA centralized procedure submissions, ClinicalTrials.gov records, and notified body designation databases. Bottom-up service provider revenue triangulation against top-down sponsor spending estimates established market sizing boundaries.
Sensitivity analysis tested forecast robustness across regulatory timeline scenarios and talent availability assumptions. Segmentation dimensions modeled span sector, service type, client maturity tier, and technology adoption intensity. CAGRs derived from regression analysis of historical sponsor outsourcing ratios projected against pipeline complexity indices. Forecast inputs incorporated EU MDR transition deadlines, FDA digital health guidance evolution, and ICH guideline adoption trajectories.
Forecasts assume regulatory continuity in FDA, EMA, and WHO frameworks; material policy shifts would require re-modeling. Specific risks include notified body capacity expansion failure, FDA user fee reauthorization disruption, and sponsor vertical integration into captive regulatory capabilities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Italy Operations Service Consulting Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
UK Healthcare Consulting Market