
 Massage Equipment Market | 2026-2036
Massage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Massage Equipment Market Intelligence
Subscription-based leasing and asset-light clinic partnerships are tilting competitive access toward mid-tier brands that lack capital for outright equipment purchases. Panasonic Holdings Corp. leverages its vertical manufacturing depth to control component costs across electric massage systems. Family Inada Co. Ltd. anchors premium positioning through handcrafted chair assembly in Japan. HoMedics USA competes aggressively in the foot massager segment via big-box retail channel control.
Massage equipment comprises electromechanical and manually operated devices engineered to apply pressure, vibration, or heat to soft tissue, typically operating at frequencies between 20–60 Hz for percussive modalities and temperatures up to 45°C for thermal applications. These systems serve therapeutic muscle recovery, stress reduction, and circulation improvement across commercial and residential settings. Massage chairs command the largest value pool due to high unit prices and embedded software complexity, while massage guns represent the fastest-expanding category as sports recovery protocols migrate from professional athletic facilities into household settings. Electric massage technology captures widening share as lithium-ion power density improvements enable cordless operation at sustained torque outputs.
The FDA regulates medical claims on percussive and heated massage devices in the United States, compelling manufacturers to distinguish wellness positioning from therapeutic indications. CE marking under the EU MDR and RoHS substance restrictions shape European market access and material selection for electronic massage systems. Stakeholders must monitor evolving battery safety standards and medical device classification thresholds as regulatory bodies reassess where wellness equipment crosses into therapeutic territory.
Market Dynamics
The migration of sports recovery protocols from professional athletic facilities into household settings is compressing distribution layers and forcing manufacturers to recalibrate channel economics around direct-to-consumer fulfillment.
Growth Catalysts
- FDA Class II Medical Device Oversight:Regulatory clarity around therapeutic claims in the United States creates definitional boundaries that premium brands exploit to differentiate wellness positioning from medical-grade positioning.
- Lithium-ion Power Density Gains:Cordless percussive devices now sustain torque outputs previously requiring tethered power, unlocking portability for commercial fitness centers and mobile physical therapy practices.
- China Domestic Manufacturing Scale:Concentrated production of heated massage and electric massage technologies in Guangdong and Zhejiang provinces drives component cost curves down for both household and clinic end users.
Market Restraints
- Raw Material Input Volatility:Neodymium magnet prices and lithium carbonate contract terms create margin pressure for percussive motor assemblies and battery pack suppliers.
- Supply Concentration in East Asian Component Ecosystems:Single-source dependencies for precision vibration motors and heated element controllers expose brands to geopolitical friction and logistics disruption.
- Technical Ceiling on Percussive Frequency:Soft tissue damage thresholds above 60 Hz limit amplitude expansion for massage guns, capping performance differentiation in the category.
Strategic Opportunities
- Subscription-based Leasing Models:Asset-light clinic partnerships in Germany and France allow mid-tier brands to bypass capital-intensive outright purchase barriers.
- EU Medical Device Regulation Tailwinds:CE marking under MDR creates compliance moats that filter out low-cost competitors while opening reimbursement pathways for certified therapeutic chairs.
- Aging Population Cohorts in Japan:METI-backed senior care infrastructure investments expand addressable demand for circulation-focused thermal massage systems in institutional settings.
Industry Challenges
- Embedded Software Talent Scarcity:Firmware engineering for adaptive pressure algorithms and biometric feedback loops outpaces vocational training pipeline output in key manufacturing regions.
- Prolonged FDA 510(k) Timelines:Therapeutic indication submissions for heated massage chairs face review backlogs that delay market entry by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Massage Equipment Market |
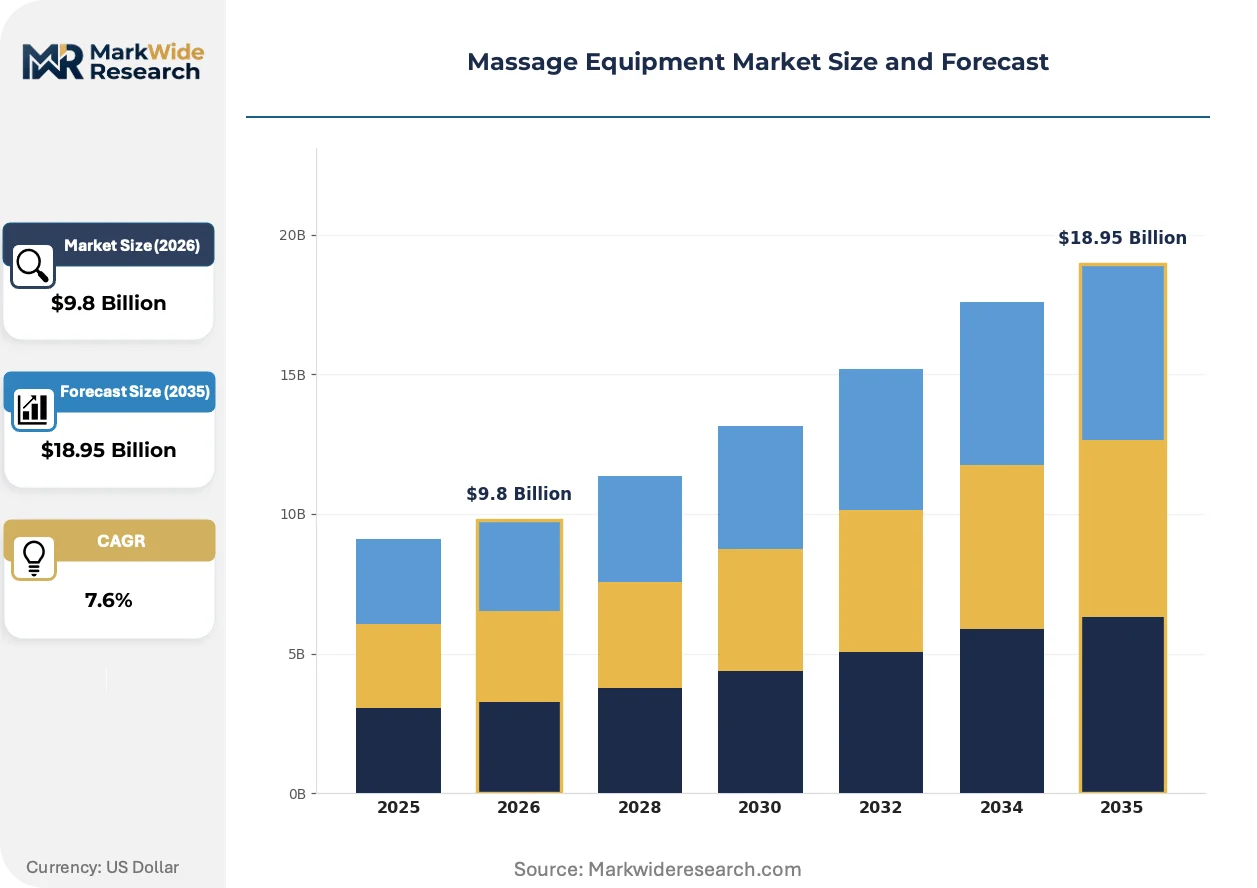
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Massage Chairs, Massage Guns, Massage Tables, Foot Massagers Application: Therapeutic Use, Health & Wellness, Sports Recovery, Spa Treatments End User: Households, Fitness Centers, Spas, Clinics Technology: Manual Massage, Electric Massage, Heated Massage, Vibration Therapy |
| Companies Covered | Human Touch LLC, OMRON Corp., Panasonic Holdings Corp., HoMedics USA, Family Inada Co. Ltd., OSIM International Pte. Ltd., Luraco Technologies, Casada International GmbH, Beurer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Massage Equipment Market Strategic Shifts & Innovations
Convergence between biometric sensing and adaptive pressure modulation is redefining product architecture, with software complexity now determining margin capture more than mechanical refinement.
Percussive massage technology is hybridizing with real-time muscle tension detection via integrated EMG sensors. Commercial fitness chains in Australia and Canada are piloting these systems for personalized recovery programming. The technology is compressing differentiation timelines as hardware commoditizes faster than firmware can be replicated.
REACH substance restrictions under EU chemical policy are forcing material substitutions in heated element housings and vibration-dampening elastomers. Manufacturers serving European markets must reformulate supply chains around SVHC-free alternatives. Massage chair producers with German and French distribution footprints face the steepest compliance cost curves.
Corporate wellness procurement is consolidating vendor relationships around integrated platform contracts rather than discrete equipment purchases. Facility managers at Fortune 500 headquarters in the United States now bundle massage equipment with ergonomic furniture and mental health app subscriptions. This behavior concentrates contract value with full-solution providers and marginalizes standalone equipment specialists.
Massage Equipment Market Segmentation
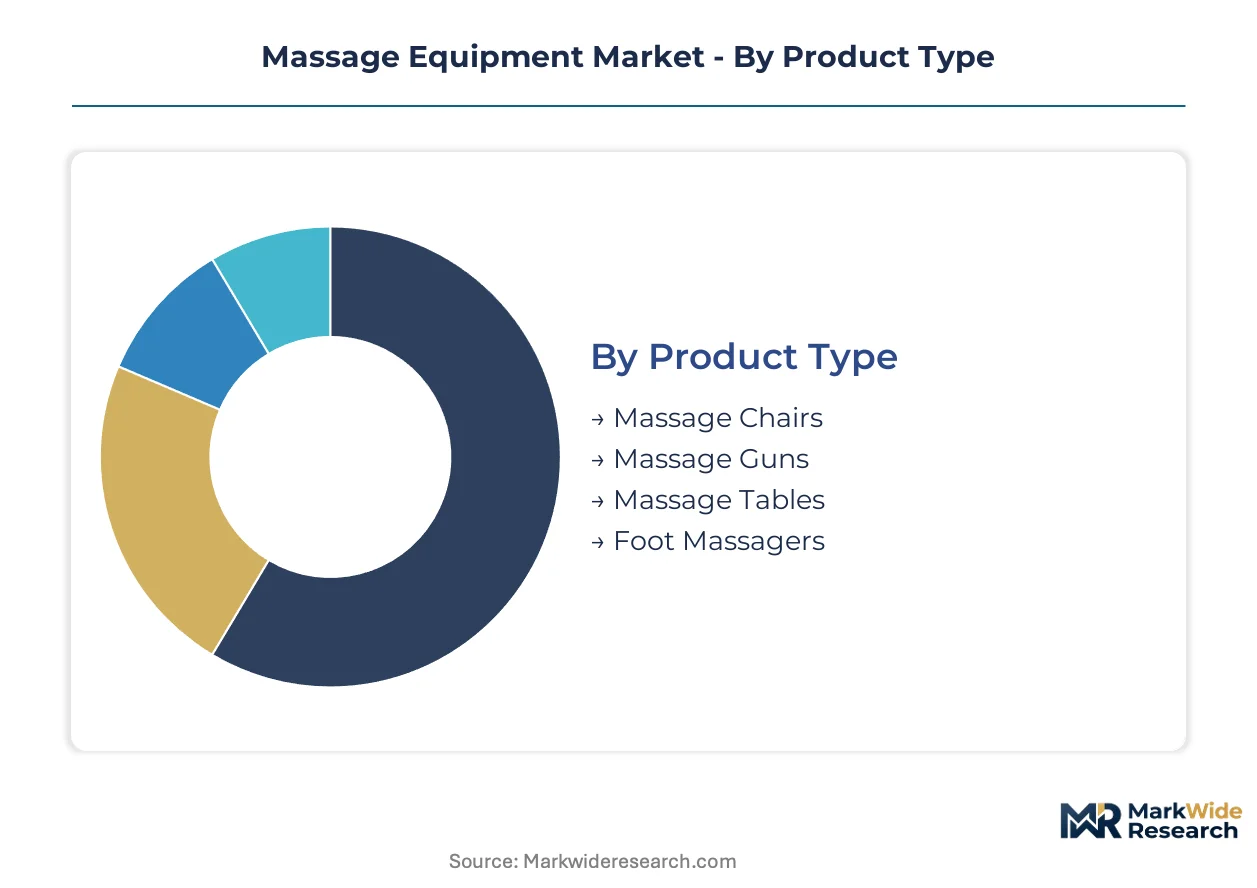
Segmentation in massage equipment reveals divergent service economics and margin architectures across product categories. After-sales intensity varies dramatically—chairs demand field technician networks while guns operate on replacement-head models. Understanding these structural differences guides capital allocation and channel strategy.
Product Type:
After-sales-service intensity escalates with unit complexity and embedded software density, reshaping profitability profiles across the four product categories.
- Massage Chairs:Electromechanical systems integrate heated rollers, airbag arrays, and adaptive pressure firmware requiring specialized installation and preventive maintenance contracts. Demand concentrates in Japanese and German household segments where METI-backed senior care infrastructure and statutory health reimbursement pathways offset premium price points. Service revenue often exceeds hardware margin over the product lifecycle.
- Massage Guns:Lithium-ion powered percussive devices operating at 20–60 Hz frequencies have migrated from professional athletic facilities into residential settings across Australia and Canada. Cordless torque improvements and direct-to-consumer fulfillment compression are displacing traditional retail layers.
- Massage Tables:Portable aluminum-frame and stationary wooden models serve mobile physical therapy practices and institutional spa chains with minimal embedded technology and correspondingly thin service attach rates.
- Foot Massagers:Shiatsu roller and compression boot configurations dominate big-box retail channels in the United States, with HoMedics USA maintaining category leadership through shelf-space control and seasonal promotional cadence.
By volume, foot massagers lead. By growth pace, massage guns are expanding most quickly.
Application:
Cost tier stratification separates premium therapeutic positioning from mass-market wellness claims, with regulatory classification determining reimbursement eligibility and pricing power.
- Therapeutic Use:FDA Class II medical device submissions for heated massage chairs face prolonged 510(k) review timelines, creating compliance moats that filter low-cost competitors while delaying market entry for innovative entrants. Certified indications open institutional procurement channels in German rehabilitation clinics.
- Health & Wellness:General wellness positioning avoids therapeutic claim scrutiny, enabling faster SKU turnover in United States big-box retail and Chinese e-commerce platforms where domestic manufacturers scale electric massage technologies.
- Sports Recovery:Percussive protocols originally developed for professional athletic facilities in Australia now penetrate household settings through subscription-based leasing models in France and Germany.
- Spa Treatments:Commercial-grade tables and thermal systems serve hospitality and wellness resort chains with vendor consolidation around integrated platform contracts rather than discrete equipment purchases.
Therapeutic use commands the highest unit margins. Sports recovery applications are gaining share fastest among residential purchasers.
End User:
Customer type determines procurement modality—outright purchase versus subscription leasing—and correspondingly shapes manufacturer working capital requirements.
- Households:Direct-to-consumer fulfillment dominates for massage guns and compact foot massagers, with biometric-enabled adaptive pressure systems commanding price premiums in Japanese and Canadian markets.
- Fitness Centers:Commercial chains in Australia pilot EMG-integrated percussive systems for personalized recovery programming, compressing hardware differentiation timelines as firmware commoditizes.
- Spas:Hospitality procurement consolidation around full-solution providers marginalizes standalone equipment specialists in United States Fortune 500 corporate wellness contracts.
- Clinics:Asset-light leasing partnerships in Germany and France allow mid-tier brands to bypass capital-intensive outright purchase barriers for therapeutic-grade chairs.
Households represent the largest addressable base. Clinics are climbing the fastest as reimbursement pathways mature.
Technology:
Supply concentration in Guangdong and Zhejiang provinces for electric and heated massage components creates geographic dependencies that shape margin volatility and logistics risk.
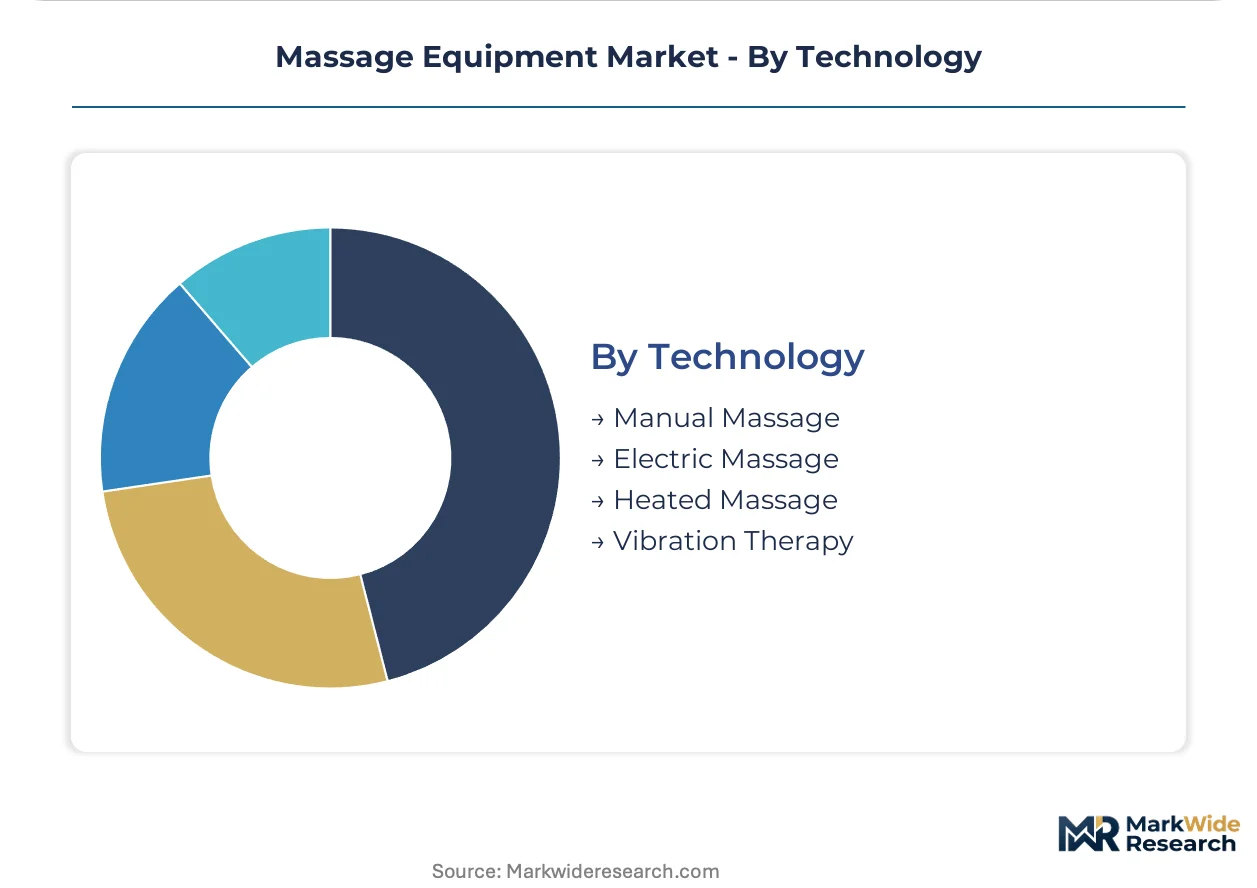
- Manual Massage:Non-powered tables and basic rollers serve price-sensitive segments with minimal regulatory exposure and thin but stable margins.
- Electric Massage:Lithium-ion power density improvements enable sustained cordless torque outputs, unlocking portability for mobile physical therapy practices and commercial fitness centers.
- Heated Massage:Thermal systems up to 45°C face REACH substance restrictions under EU chemical policy, forcing SVHC-free material substitutions in element housings for German and French distribution footprints.
- Vibration Therapy:Percussive frequencies above 60 Hz encounter soft tissue damage thresholds that cap performance differentiation and limit amplitude expansion in massage gun engineering.
Electric massage holds the widest installed base. Heated massage is gaining traction fastest in institutional senior care deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household buyers in Japan and Germany drive premium therapeutic demand, while fitness chains in Australia and Canada accelerate sports-recovery adoption. Chinese domestic manufacturers capture volume through scaled electric and heated massage production. Regulatory divergence across FDA, MDR, and METI frameworks fragments compliance pathways.
United States
Corporate wellness procurement at Fortune 500 headquarters bundles massage equipment with ergonomic furniture and mental health subscriptions. FDA Class II medical device oversight of therapeutic claims creates definitional boundaries that premium brands exploit for differentiation. Manufacturing for domestic brands concentrates in supply partnerships with Guangdong and Zhejiang component ecosystems.
China
Domestic manufacturers scale heated massage and electric massage technologies for both household and clinic end users, driving component cost curves downward. The country's national standards regulator enforces GB standards for electronic massage systems and battery safety. Production gravity concentrates in Guangdong and Zhejiang provinces where precision vibration motor and heated element controller supply chains cluster.
Germany
Asset-light leasing partnerships allow mid-tier brands to bypass capital-intensive outright purchase barriers in rehabilitation clinics. CE marking under EU MDR and REACH substance restrictions shape market access and material selection for electronic massage systems. Industrial concentration in Baden-Württemberg and Bavaria hosts distribution headquarters serving EU therapeutic-grade procurement channels.
Japan
METI-backed senior care infrastructure investments expand addressable demand for circulation-focused thermal massage systems in institutional settings. Family Inada Co. Ltd. anchors premium positioning through handcrafted chair assembly. The Kanto region around Tokyo maintains design and firmware engineering capabilities for adaptive pressure algorithms.
Australia
Commercial fitness chains pilot EMG-integrated percussive systems for personalized recovery programming. The country's national therapeutic goods regulator classifies medical device claims for massage equipment entering clinical channels. Sydney and Melbourne serve as test markets for biometric-enabled adaptive pressure systems before broader Asia-Pacific rollout.
Massage Equipment Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent margin architectures. Panasonic Holdings Corp. leverages backward integration into component manufacturing to control electric massage system costs. Three archetypes dominate: vertically integrated electronics conglomerates, handcrafted premium assemblers, and retail-channel specialists. Competitive moves center on subscription-based leasing partnerships and firmware differentiation as hardware commoditizes.
Among Japan-based manufacturers, Family Inada Co. Ltd. and OMRON Corp. occupy positions at opposite ends of the craftsmanship-scale spectrum. Panasonic Holdings Corp. represents the electronics-integrated archetype with captive supply chain control. HoMedics USA exemplifies retail-channel dominance through big-box shelf-space command. These three anchors illustrate how geographic origin and corporate structure map to divergent competitive strategies.
| Leading Market Players |
|---|
| Human Touch LLC |
| OMRON Corp. |
| Panasonic Holdings Corp. |
| HoMedics USA |
| Family Inada Co. Ltd. |
| OSIM International Pte. Ltd. |
| Luraco Technologies |
| Casada International GmbH |
| Beurer GmbH |
| Others |
Cost & Logistics Intelligence
The Shenzhen-Long Beach maritime corridor carries heated massage component shipments at rates that fluctuate with lithium carbonate contract terms, compressing margins for percussive motor assemblers while amplifying price differentiation between FDA-cleared therapeutic chairs and wellness-positioned alternatives.
Pricing Analysis
Cost-plus contracts with neodymium magnet indexation dominate procurement between Guangdong vibration motor suppliers and massage gun OEMs. Three-tier pricing structure across premium, standard, and economy levels separates METI-backed institutional chairs from direct-to-consumer cordless devices and entry-level foot massagers. Pricing pressure stems from raw material volatility in rare-earth magnet markets. Household buyers in Australia and Canada exhibit highest price sensitivity, while German rehabilitation clinics accept premium positioning for CE-marked therapeutic systems.
Supply Chain Analysis
Upstream feedstock for precision vibration motors draws from rare-earth processing facilities in China, lithium carbonate refineries in Chile and Australia, and copper winding suppliers in South Korea. Heated element controllers and neodymium magnet assemblies create single-source dependencies for percussive device manufacturers. Tariff exposure on Chinese electronic components threatens margin stability for brands without captive component production. Distribution runs through direct-to-consumer fulfillment for massage guns and field technician networks for chair installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from low-cost Chinese electric massage manufacturers scaling through domestic e-commerce platforms, requiring defensive repositioning around certification moats and firmware differentiation.
For Market Incumbents: Harden regulatory compliance boundaries by accelerating FDA 510(k) submissions for heated massage chairs before review backlogs lengthen. Deepen backward integration into lithium-ion battery pack assembly to offset raw material volatility. Channel control through clinic leasing partnerships in France and Germany defends against direct-to-consumer price erosion. For New Entrants and Emerging Players: Underpenetrated asset-light leasing markets in German rehabilitation clinics offer white-space access without capital-intensive inventory build. Target biometric-enabled adaptive pressure systems for Australian fitness chains piloting personalized recovery programming. Pursue white-label manufacturing partnerships with Zhejiang component suppliers to compress time-to-market. For Investors and Strategic Acquirers: Firmware-specialist mid-caps with embedded software engineering capabilities in Kanto region represent acquisition targets as hardware commoditization accelerates. Long-term viability hinges on adaptive pressure algorithm differentiation and regulatory certification breadth. Watch FDA 510(k) approval velocity as inflection signal for therapeutic-grade market access.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Therapeutic claim clearance opens institutional procurement channels in US rehabilitation networks. |
| Backward Integration into Battery Assembly | Captive lithium-ion pack production insulates margins from carbonate contract volatility. |
| Biometric Sensor Platform Integration | EMG-adaptive pressure systems command premium positioning in Australian fitness pilot programs. |
| Asset-Light Leasing Partnership | Clinic subscription models bypass capital barriers for mid-tier brands entering German markets. |
| CE Marking Pathway Investment | MDR compliance filters low-cost competitors while enabling reimbursement in EU therapeutic channels. |
Research Approach
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and fitness center operations directors provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA 510(k) filings, CE marking databases under EU MDR, METI senior care infrastructure disclosures, and customs records for Guangdong and Zhejiang export flows. Bottom-up unit economics triangulated against top-down category spending estimates.
Scenario-bracketing around lithium carbonate price bands and neodymium magnet contract terms bounded projection uncertainty across the analysis window. Segmentation modeling incorporated product type, application, end user, and technology dimensions with regional regulatory cluster overlays. CAGR derivation weighted historical adoption curves for massage guns against saturation dynamics in Japanese massage chair markets. Firmware development timelines and FDA review backlogs served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in freight rates through Shenzhen-Long Beach corridors and rare-earth export quotas would shift the trajectory. Forecasts reflect documented assumptions about battery power density improvement curves and regulatory classification stability. Cross-checking against hospital procurement database trends and fitness chain capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Global Refractive Surgery Devices Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Cardiac Implants Market
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
Anesthesia Resuscitators Masks Market