
 Global Hydrocephalus Shunts Market | 2026-2036
Global Hydrocephalus Shunts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrocephalus Shunts Market Foresight
Neurosurgeon training bottlenecks is unwinding market expansion as specialized fellowship programs fail to keep pace with procedure volumes. Medtronic leverages its programmable valve portfolio to sustain leadership across North American teaching hospitals. Integra LifeSciences anchors its position through vertical control of silicone biomaterial supply chains. Christoph Miethke GmbH & Co. KG specializes in gravitational valve technology that differentiates its offering in European neurosurgery centers.
Hydrocephalus shunts are cerebrospinal fluid diversion systems comprising proximal catheters, pressure-regulating valves, and distal tubing, typically manufactured from medical-grade silicone elastomer with radiopaque barium sulfate for fluoroscopic visualization. These devices maintain intracranial pressure equilibrium by routing excess fluid to peritoneal, pleural, or atrial cavities. Programmable valve shunts command premium positioning due to post-implant pressure adjustability that reduces revision surgeries. Pediatric hydrocephalus applications represent the largest volume pool, while normal pressure hydrocephalus segments exhibit faster procedural growth tied to geriatric diagnostic expansion.
FDA premarket notification pathways and EMA Medical Device Regulation conformity assessments shape product development timelines and biocompatibility documentation burdens. Japan's PMDA enforces stringent JIS standards for long-term implantable silicone devices that filter market entrants. WHO surgical device guidelines influence procurement standards across emerging hospital systems. Stakeholders must monitor reimbursement parity between programmable and fixed-pressure valves as health technology assessment bodies recalibrate cost-effectiveness thresholds.
Market Dynamics
Programmable valve pressure adjustability is compressing revision surgery volumes while concentrating procurement decisions among neurosurgeons with specialized training access. This capability shift is redistributing value capture toward device manufacturers with post-implant service infrastructure.
Growth Catalysts
- Pediatric neurosurgery expansion:Tertiary hospital departments in the United States, Germany, and Japan are elevating valve implant volumes through dedicated fellowship programs.
- EMA MDR biocompatibility pathways:Tightened silicone testing requirements are filtering substandard suppliers and elevating documentation standards across European manufacturing.
- Normal pressure hydrocephalus diagnostics:Geriatric screening protocols in Japanese university hospitals are accelerating procedural identification rates.
Market Restraints
- Medical-grade silicone supply concentration:Three specialty chemical manufacturers control radiopaque elastomer formulations, creating input vulnerability.
- FDA premarket notification timelines:510(k) pathway documentation burdens for programmable valves extend commercialization cycles by eight to fourteen months.
- Neurosurgeon training bottlenecks:Fellowship program graduation rates lag procedure volume growth across North American teaching hospitals.
Strategic Opportunities
- Brazil ANVISA fast-track pathways:Emerging market regulators are streamlining import registration for CE-marked devices.
- Telemedicine valve pressure adjustment:Remote programming protocols are converging with wearable intracranial pressure monitors.
- Pleural and atrial diversion segments:Alternative cavity routing applications remain underdeveloped relative to peritoneal standards.
Industry Challenges
- ISO 10993 biocompatibility certification:Extended cytotoxicity and sensitization testing timelines compress product launch windows.
- Legacy fixed-pressure valve inventory:Hospital purchasing committees face write-down pressure amid programmable substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrocephalus Shunts Market |
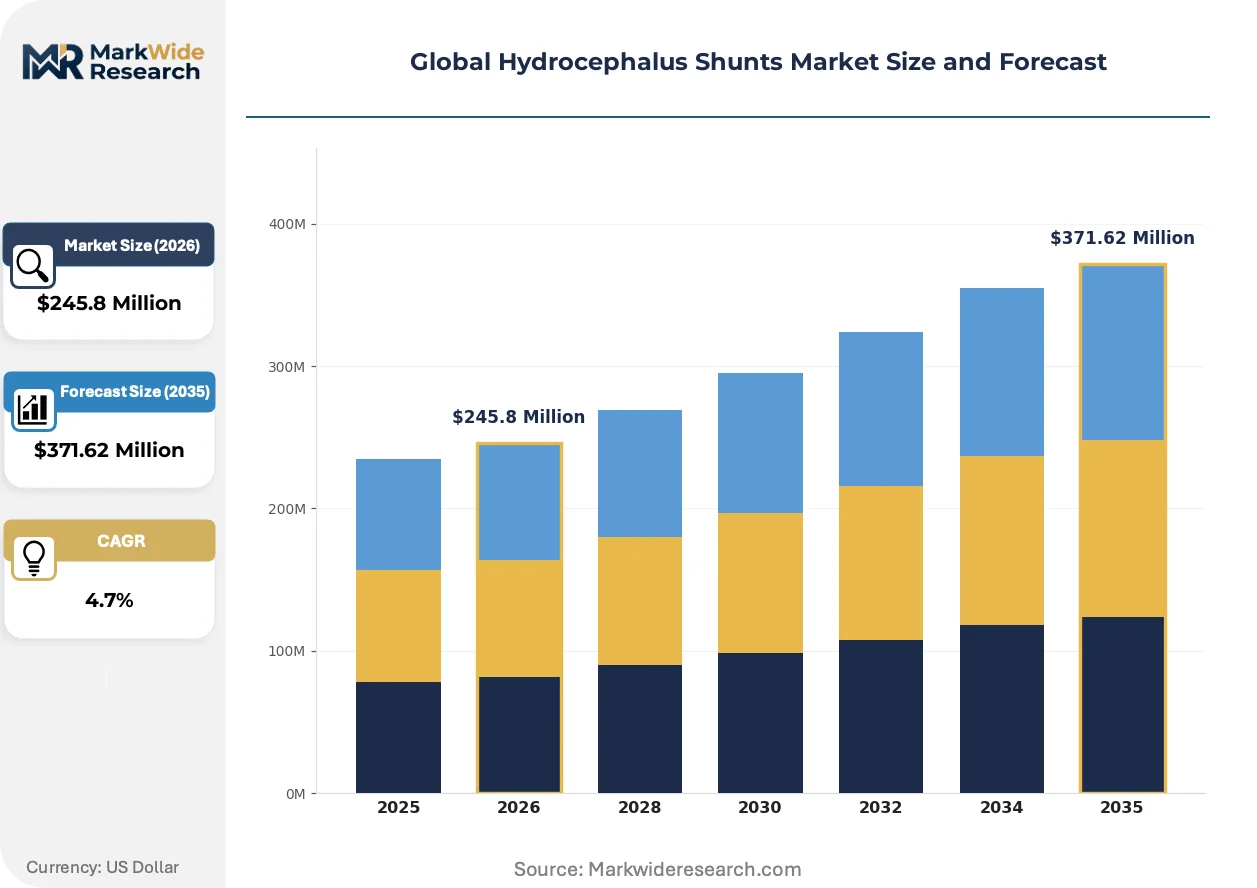
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $371.62 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Valve Shunts, Fixed Pressure Valve Shunts, Flow-Regulated Shunts, Anti-Siphon Valve Shunts Application: Pediatric Hydrocephalus, Adult Hydrocephalus, Post-Traumatic Hydrocephalus, Normal Pressure Hydrocephalus End User: Neurosurgery Centers, Specialized Clinics, Rehabilitation Facilities, Private Practice Physicians Distribution Channel: Direct Sales, Medical Distributors, E-commerce Platforms, Hospital Procurement |
| Companies Covered | Medtronic, Integra LifeSciences, Sophysa, Spiegelberg GmbH & Co. KG, Aesculap, Inc., Christoph Miethke GmbH & Co. KG, B. Braun SE, Kaneka Medix Corp., Natus Medical Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrocephalus Shunts Market Shifts & Advancements
Smart valve connectivity is penetrating neurosurgical practice, embedding sensors that transmit intracranial pressure data to remote monitoring platforms. This instrumentation layer is redefing post-operative care protocols and device service relationships.
Gravitational valve technology is fragmenting competitive positioning across European neurosurgery centers. Christoph Miethke GmbH & Co. KG's differential pressure designs enable posture-responsive flow regulation that fixed-pressure mechanisms cannot replicate. German and Austrian university hospitals are adopting these systems for complex hydrocephalus cases, compressing market share concentration among programmable incumbents.
Japan's PMDA enforcement of JIS T 0313 long-term implantable silicone standards is extending conformity assessment durations. Device manufacturers must submit accelerated aging data and extractable profiles that exceed European MDR requirements. Pediatric valve suppliers targeting Japanese distribution are restructuring quality management systems to accommodate these documentation burdens.
Health technology assessment bodies in Germany and England are recalibrating reimbursement parity between programmable and fixed-pressure valves. Hospital procurement committees face compressed decision cycles as cost-effectiveness thresholds tighten, forcing manufacturers to unbundle post-implant adjustment services from device pricing. This behavioral shift is most visible within NHS England's specialized commissioning frameworks.
Global Hydrocephalus Shunts Market Segmentation
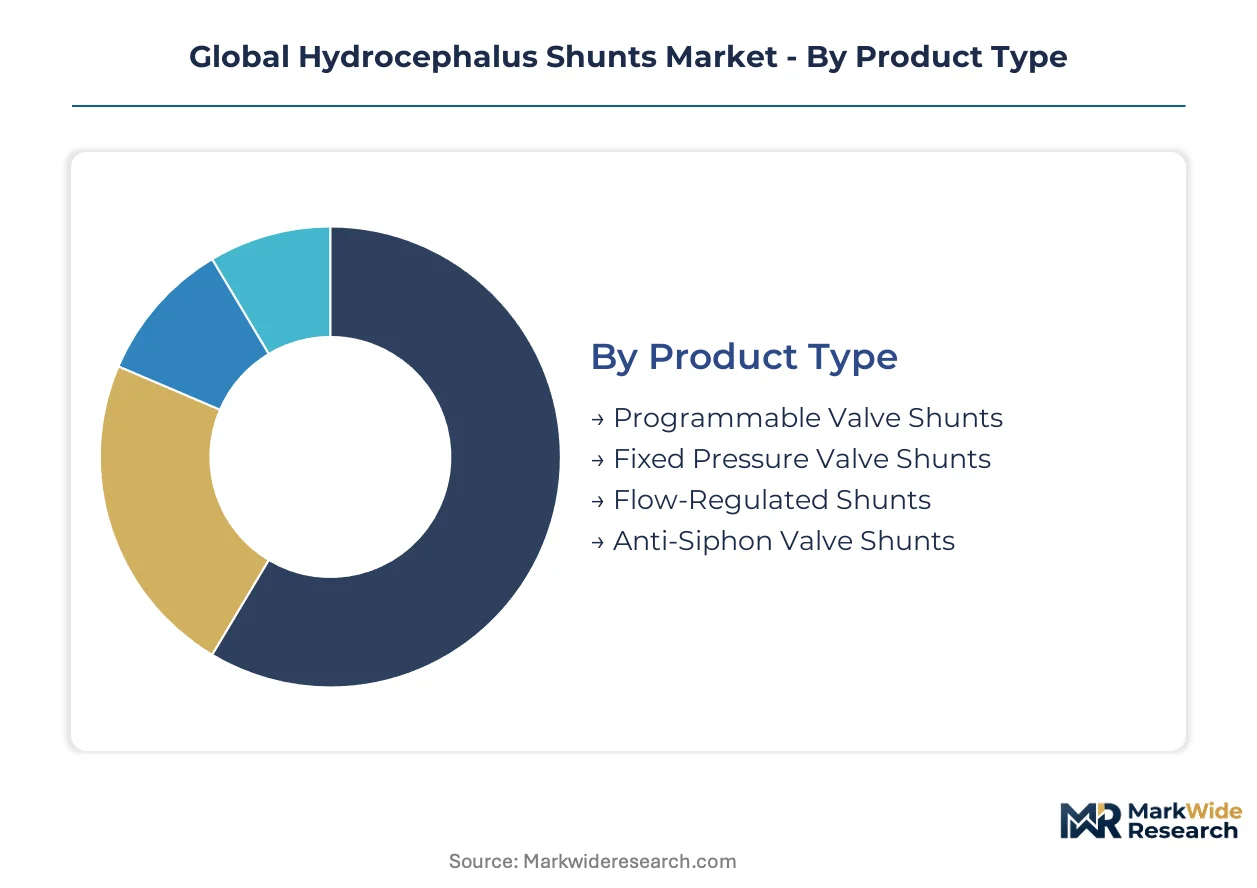
Segmentation in hydrocephalus shunts reveals distinct procurement pathways and clinical decision hierarchies. Valve programmability and patient age demographics create divergent channel strategies across tertiary hospitals and specialized neurosurgery centers.
Product Type:
Channel-mix varies sharply by valve sophistication, with programmable systems flowing through direct manufacturer relationships while fixed-pressure alternatives move through distributor networks.
- Programmable Valve Shunts:These devices incorporate magnetic or electromagnetic pressure adjustment mechanisms enabling non-invasive post-implant calibration. Demand concentrates in United States teaching hospitals and German university medical centers where neurosurgeons with specialized training access drive procurement decisions for complex pediatric and normal pressure hydrocephalus cases.
- Fixed Pressure Valve Shunts:Pre-set pressure mechanisms manufactured from medical-grade silicone elastomer with radiopaque barium sulfate. Volume flows through medical distributors to community hospitals and emerging market facilities where cost constraints and simpler clinical protocols dominate selection criteria.
- Flow-Regulated Shunts:Differential pressure designs that respond to patient posture and activity levels, manufactured primarily by European specialists.
- Anti-Siphon Valve Shunts:Gravitational mechanisms preventing overdrainage during upright positioning, adopted in Austrian and Swiss neurosurgery departments for complex cases.
By volume, Fixed Pressure Valve Shunts leads. By growth pace, Programmable Valve Shunts is ahead.
Application:
Cost tier stratification separates emergency congenital interventions from elective geriatric procedures, with reimbursement parity varying across national health technology assessment frameworks.
- Pediatric Hydrocephalus:Congenital and early-onset cerebrospinal fluid diversion procedures representing the largest implant volume pool globally. Tertiary pediatric neurosurgery departments in Japan and the United States sustain procedure growth through dedicated fellowship programs and expanded NICU capabilities.
- Normal Pressure Hydrocephalus:Geriatric diagnostic expansion in Japanese university hospitals and German specialized clinics is accelerating procedural identification rates for this reversible dementia mimic.
- Adult Hydrocephalus:Acquired cases from tumor, hemorrhage, or infection requiring shunt placement across general hospital neurosurgery services.
- Post-Traumatic Hydrocephalus:Secondary hydrocephalus following traumatic brain injury, treated in trauma centers and rehabilitation facilities with delayed intervention timelines.
Pediatric Hydrocephalus captures the highest procedure count. Normal Pressure Hydrocephalus exhibits the steepest expansion trajectory.
End User:
Customer type determines service intensity, with neurosurgery centers demanding post-implant pressure adjustment services while private practice physicians prioritize device simplicity.
- Neurosurgery Centers:Tertiary academic medical centers with specialized pediatric and adult neurosurgery fellowship programs. These facilities concentrate programmable valve procurement and maintain direct manufacturer relationships for technical support and remote pressure adjustment protocols.
- Specialized Clinics:Dedicated hydrocephalus and CSF disorder centers in Germany, Japan, and the United States managing complex revision surgeries and gravitational valve placements.
- Rehabilitation Facilities:Post-acute care settings managing shunt-dependent patients with traumatic brain injury histories.
- Private Practice Physicians:Individual neurosurgeons in community settings relying on distributor networks for fixed-pressure valve procurement with limited post-implant service requirements.
Neurosurgery Centers dominate programmable valve procurement. Specialized Clinics are expanding gravitational valve adoption most rapidly.
Distribution Channel:
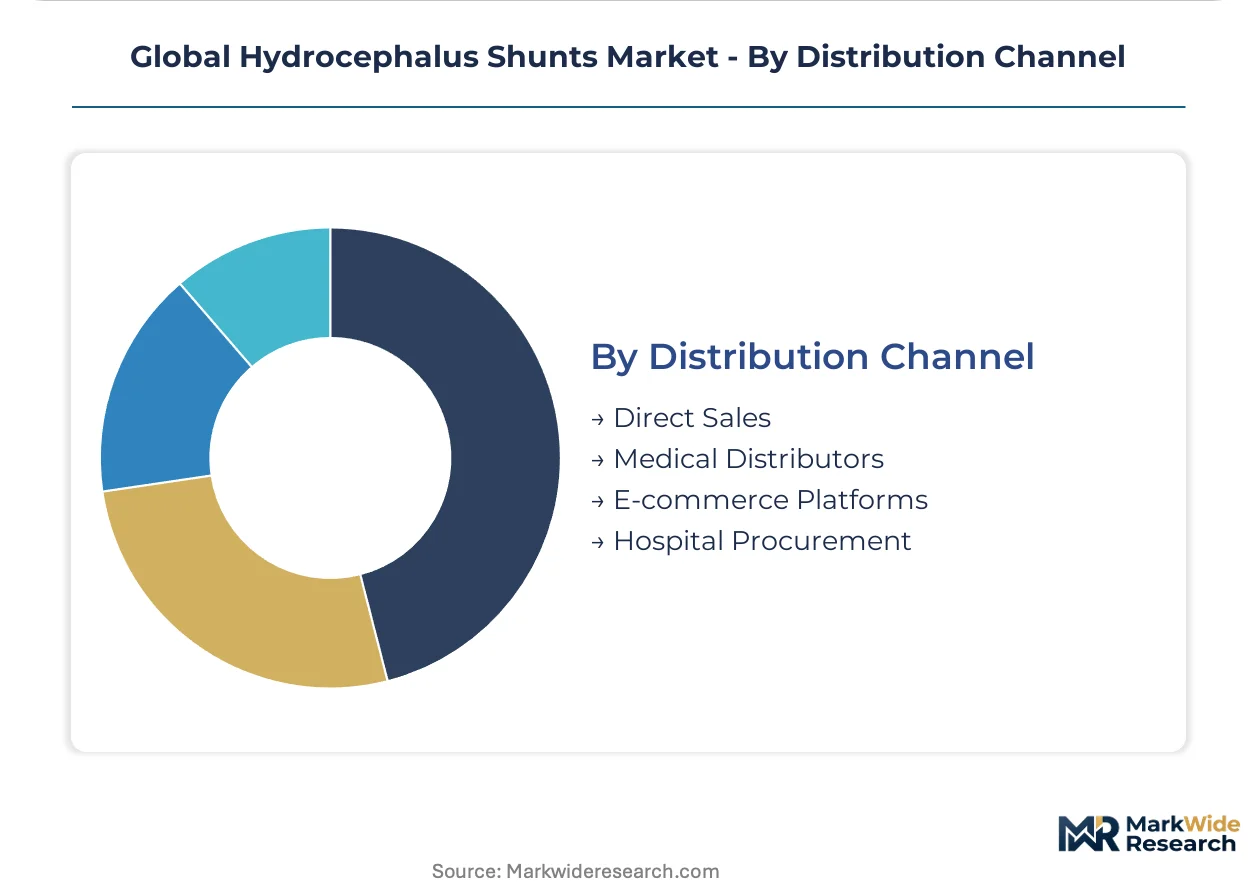
Supply concentration in medical-grade silicone manufacturing shapes channel economics, with direct sales capturing premium programmable systems and distributors handling volume fixed-pressure transactions.
- Direct Sales:Manufacturer-to-hospital relationships for programmable valve systems requiring technical training, post-implant adjustment services, and warranty management. Dominant in United States academic medical centers and Japanese university hospitals with specialized neurosurgery departments.
- Medical Distributors:Regional and national distributors handling fixed-pressure valve inventory, emergency replacement stock, and community hospital procurement across Germany and emerging markets.
- E-commerce Platforms:Emerging channel for consumable shunt components and replacement parts in select European markets with streamlined CE-marking recognition.
- Hospital Procurement:Centralized purchasing committees within NHS England and German hospital networks negotiating device contracts and bundled service agreements.
Direct Sales commands the highest value per transaction. Hospital Procurement is consolidating purchasing volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German benchmarks by roughly one-third for programmable valve systems, while Japanese procurement committees extract steep discounts through volume bundling. This asymmetry reflects divergent reimbursement architectures and neurosurgeon training densities.
United States
Pediatric neurosurgery fellowship expansion at Johns Hopkins, Boston Children's, and Cincinnati Children's drives implant volume concentration. FDA 510(k) pathway documentation for programmable valves extends commercialization timelines, filtering smaller entrants. The Midwest corridor—Cleveland Clinic, Mayo Clinic, and Ann Arbor—anchors normal pressure hydrocephalus diagnostic protocol development.
Germany
University medical centers in Heidelberg, Tübingen, and Berlin elevate gravitational valve adoption for complex hydrocephalus cases. EMA MDR biocompatibility requirements for silicone components tighten conformity assessment burdens, elevating documentation standards. The Baden-Württemberg cluster—Aesculap's headquarters region—concentrates European manufacturing expertise.
Japan
Geriatric screening protocols at Tokyo University Hospital and Osaka University accelerate normal pressure hydrocephalus identification rates. PMDA enforcement of JIS T 0313 long-term implantable silicone standards extends device approval cycles beyond European timelines. The Kanto region—Tokyo, Yokohama, and Chiba—concentrates pediatric neurosurgery capacity and valve procurement volume.
United Kingdom
NHS England specialized commissioning frameworks compress reimbursement parity between programmable and fixed-pressure valves, forcing unbundling of post-implant services. MHRA post-Brexit regulatory divergence from EMA MDR creates parallel conformity assessment pathways. The Oxford-Cambridge-London triangle concentrates academic neurosurgery research and complex case referrals.
Brazil
ANVISA fast-track registration pathways for CE-marked devices accelerate import access for European and North American manufacturers. São Paulo's Hospital das Clínicas and Rio de Janeiro's Instituto Estadual do Cérebro anchor pediatric neurosurgery training expansion. The Southeast region—São Paulo, Minas Gerais, and Rio de Janeiro—generates two-thirds of national procedure volume.
Global Hydrocephalus Shunts Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with programmable valve innovators commanding premium positioning while fixed-pressure manufacturers compete on scale and distributor reach. The market structure concentrates around three to five integrated manufacturers with captive silicone supply arrangements, surrounded by specialized gravitational valve designers and regional distributors. Dominant competitive moves include backward integration into medical-grade silicone formulation and strategic partnerships with tertiary neurosurgery centers for post-implant service infrastructure.
Among diversified medical technology conglomerates, Medtronic and Integra LifeSciences occupy positions defined by programmable valve portfolios and vertical control over biomaterial supply chains. Christoph Miethke GmbH & Co. KG exemplifies the European specialist archetype, with gravitational valve differentiation concentrated in German and Austrian academic centers. These three represent distinct strategic postures: scale-driven service infrastructure, upstream supply security, and posture-responsive flow technology.
| Leading Market Players |
|---|
| Medtronic |
| Integra LifeSciences |
| Sophysa |
| Spiegelberg GmbH & Co. KG |
| Aesculap, Inc. |
| Christoph Miethke GmbH & Co. KG |
| B. Braun SE |
| Kaneka Medix Corp. |
| Natus Medical Incorporated |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for medical-grade silicone elastomer lock in supply access and price visibility for programmable valve manufacturers serving United States teaching hospitals and German university centers. These arrangements insulate tier-one device makers from radiopaque formulation spot-market volatility while anchoring procurement committee negotiations.
Pricing Analysis
Configured-to-order pricing for programmable valve systems commands substantial premiums over standard fixed-pressure alternatives across Japanese university hospitals and NHS England procurement frameworks. Three-tier pricing structure across premium, standard, and economy levels stratifies by valve programmability, biocompatibility certification tier, and bundled post-implant adjustment services. Cost compression in fixed-pressure tiers intensifies because Brazilian and Indian distributors compete on distributor margin sacrifice. Community hospitals and emerging market facilities exhibit highest price sensitivity; tertiary neurosurgery centers with dedicated fellowship programs show lowest.
Supply Chain Analysis
Germany, the United States, and Japan anchor medical-grade silicone formulation and precision valve machining for hydrocephalus shunt manufacturing. Radiopaque barium sulfate compounding, platinum-cured elastomer extrusion, and magnetic pressure adjustment mechanism assembly feed from this tripartite base. Single-source vulnerability concentrates in specialty chemical manufacturers controlling JIS T 0313-compliant long-term implantable silicone grades. Distribution runs through direct manufacturer relationships for programmable systems and regional medical distributors for fixed-pressure inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as deferred pediatric neurosurgery procedures from pandemic-era backlogs convert to implant volumes across tertiary hospital systems.
For Market Incumbents: Compound defensive positioning through backward integration into medical-grade silicone compounding and captive supply of radiopaque elastomer formulations. Expand post-implant remote pressure adjustment service infrastructure to lock in United States academic medical center procurement. Counter gravitational valve specialists by embedding posture-responsive flow algorithms into next-generation programmable platforms. For New Entrants and Emerging Players: Brazil ANVISA fast-track pathways for CE-marked devices offer lowest regulatory friction entry into Latin American neurosurgery markets. Target pleural and atrial diversion segments where peritoneal shunt standards have not yet consolidated procurement specifications. Lead with telemedicine-integrated valve pressure monitoring to differentiate from incumbent hardware-centric service models. For Investors and Strategic Acquirers: European gravitational valve designers with differentiated posture-responsive technology represent compelling acquisition targets as programmable incumbents seek flow-regulation capability gaps. Long-term viability hinges on reimbursement parity maintenance between valve tiers across German and English health technology assessment frameworks. Watch for NHS England specialized commissioning framework revisions as inflection signal for post-implant service unbundling acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR biocompatibility documentation requirements filter substandard European suppliers. |
| Hospital System Partnership | Direct relationships with Johns Hopkins and Boston Children's anchor programmable valve procurement. |
| Software Companion Development | Remote pressure adjustment platforms redefine post-operative care protocols and service relationships. |
| Reimbursement Strategy | German IQWiG and NICE cost-effectiveness thresholds force post-implant service unbundling. |
| FDA Submission | 510(k) pathway timelines for programmable valves extend commercialization cycles by eight to fourteen months. |
Research Methodology
The analysis maps programmable valve systems, fixed-pressure alternatives, gravitational flow-regulated designs, and anti-siphon mechanisms, each validated through pediatric neurosurgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Primary interviews with device manufacturers and tertiary hospital procurement leads combined with secondary validation against FDA 510(k) filings, EMA MDR conformity assessments, PMDA approval databases, and hospital procurement contract repositories. Bottom-up implant volume modeling and top-down market sizing triangulated across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across valve programmability tiers, patient age demographics, end-user facility types, and regional regulatory clusters. CAGRs derived from procedure volume elasticity to neurosurgeon fellowship graduation rates, aging demographic trajectories, and normal pressure hydrocephalus diagnostic protocol penetration. Forecast inputs incorporated silicone biomaterial supply constraints, reimbursement parity shifts, and telemedicine integration adoption curves throughout the projection horizon.
Decision-makers should treat outputs as directional under assumptions of stable FDA and EMA regulatory timelines, silicone supply concentration persistence, and neurosurgeon training bottleneck gradual resolution; material deviation would warrant model refresh. Specific risk factors include accelerated EMA MDR enforcement, Japanese PMDA JIS T 0313 standard revisions, and health technology assessment body reimbursement recalibration. Recalibration cycles align with material shifts in regulatory approval durations, supply chain concentration events, and reimbursement framework revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Global Breast Pumps Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Skull Clamp Market
Medical Devices
Rib Fracture Repair Systems Market