
 Endoscopic Tattooing Market | 2026-2036
Endoscopic Tattooing Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Tattooing Market Foresight
Subscription-based maintenance contracts for endoscopic visualization systems is expanding the recurring revenue base beyond capital equipment sales. Boston Scientific Corporation leverages its interventional endoscopy portfolio to anchor tattooing adjuncts within broader therapeutic procedure bundles. Cook Medical specializes in single-use delivery devices that integrate with third-party dye formulations. Olympus Corporation dominates the installed base of endoscopy platforms, controlling accessory compatibility standards that shape tattooing product interoperability.
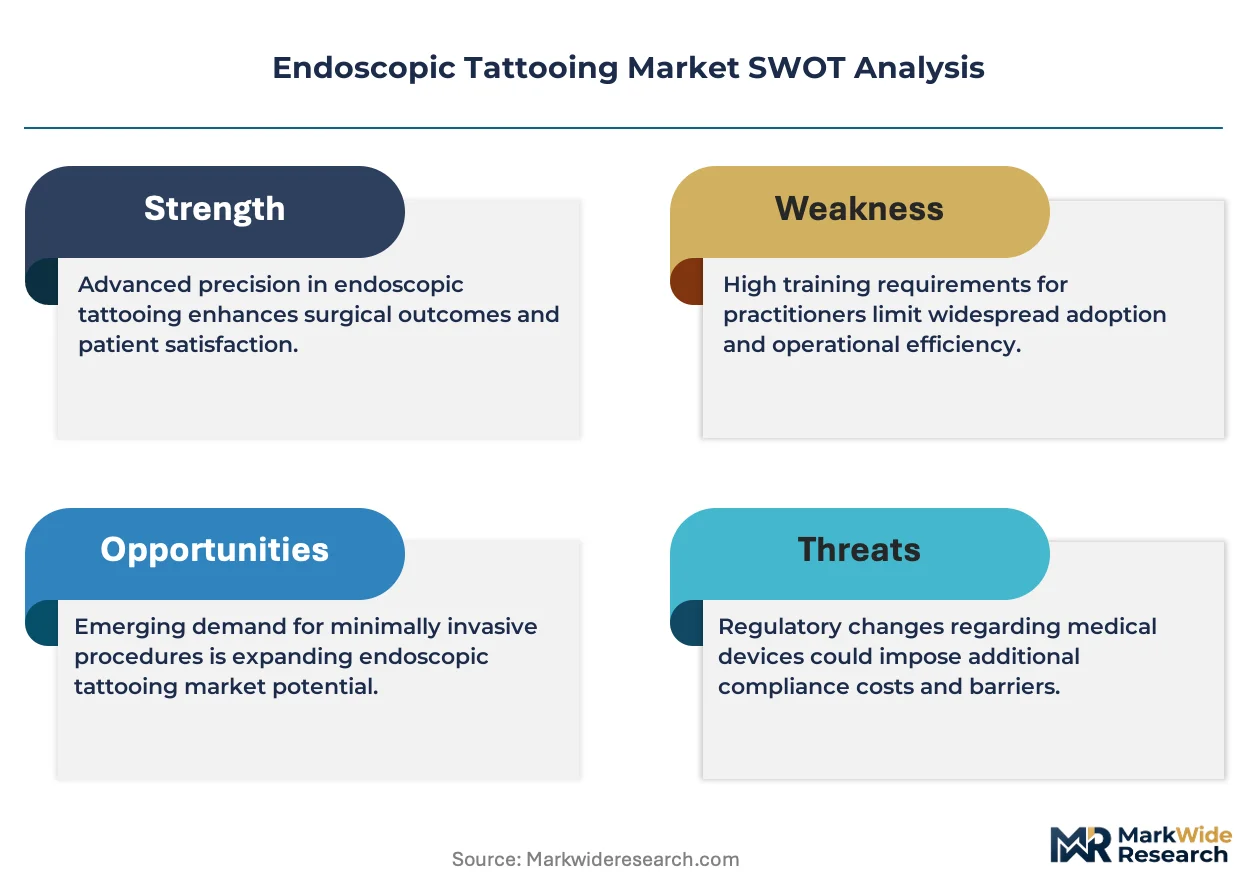
Endoscopic tattooing refers to the intramural or submucosal deposition of colored marking agents via flexible endoscopes to permanently identify lesions, polyps, or tumor margins for subsequent surgical localization; carbon particle suspensions and sterile ink formulations constitute the primary agent classes, with particle size and tissue retention time serving as critical performance parameters. Gastrointestinal procedures occupy the largest application segment due to the volume of colorectal cancer screening and polypectomy follow-up cases requiring tattoo placement. Dye-based products lead the product type category, though marker pens are gaining traction in ambulatory surgery centers seeking simplified workflow integration. Manual techniques retain substantial share in cost-sensitive settings, while laser-based approaches remain confined to specialized academic medical centers.
The FDA's 510(k) clearance pathway governs endoscopic tattooing agents marketed in the United States, with biocompatibility testing and sterility validation representing core submission requirements; ISO 10993 standards for biological evaluation of medical devices provide the underlying technical framework referenced in premarket submissions. The EU Medical Device Regulation's classification rules for invasive surgical products determine conformity assessment procedures for tattooing agents distributed in European member states. Stakeholders must monitor evolving reimbursement coding for tattooing procedures, as coverage determinations by Medicare administrative contractors directly influence hospital purchasing decisions and product commercialization strategies.
Market Dynamics
Integrated delivery networks in the United States are consolidating procurement authority across multi-site endoscopy programs, compressing vendor selection cycles and elevating compatibility requirements with dominant endoscopy platform ecosystems. This buyer concentration is reshaping competitive positioning for tattooing agent suppliers.
Growth Catalysts
- FDA 510(k) pathway standardization:Clearer biocompatibility testing requirements under ISO 10993 are reducing premarket submission variability, accelerating product entry timelines for sterile ink formulations.
- Carbon particle suspension improvements:Optimized particle size distributions are extending tissue retention times, reducing repeat tattooing procedures in colorectal surgery departments.
- Ambulatory surgery center expansion:Freestanding GI facilities in the United States are installing dedicated endoscopy suites, creating dedicated demand channels for simplified workflow tattooing systems.
Market Restraints
- Single-source dye dependency:Three suppliers control pharmaceutical-grade carbon black supply for suspension formulations, creating input concentration risk.
- EU MDR conformity costs:Reclassification of tattooing agents under invasive surgical product rules is expanding notified body assessment requirements for European market access.
- Laser-based system substitution:Electrocautery marking devices in academic medical centers compete for lesion localization budgets in high-complexity cases.
Strategic Opportunities
- Japan's aging screening population:METI-supported cancer early detection programs are expanding colonoscopy volumes, creating unmet demand for permanent marking agents.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting tattooing delivery device assembly operations for cost-sensitive Asian markets.
- Fluorescence-ink convergence:Near-infrared dye integration with standard visualization systems is enabling real-time margin confirmation during laparoscopic resections.
Industry Challenges
- GI endoscopy technician certification gaps:Submucosal injection technique proficiency varies across ambulatory settings, affecting tattoo placement consistency and reintervention rates.
- Legacy platform interoperability:Proprietary delivery channel designs from dominant endoscope manufacturers require custom adapter development for third-party tattooing agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopic Tattooing Market |
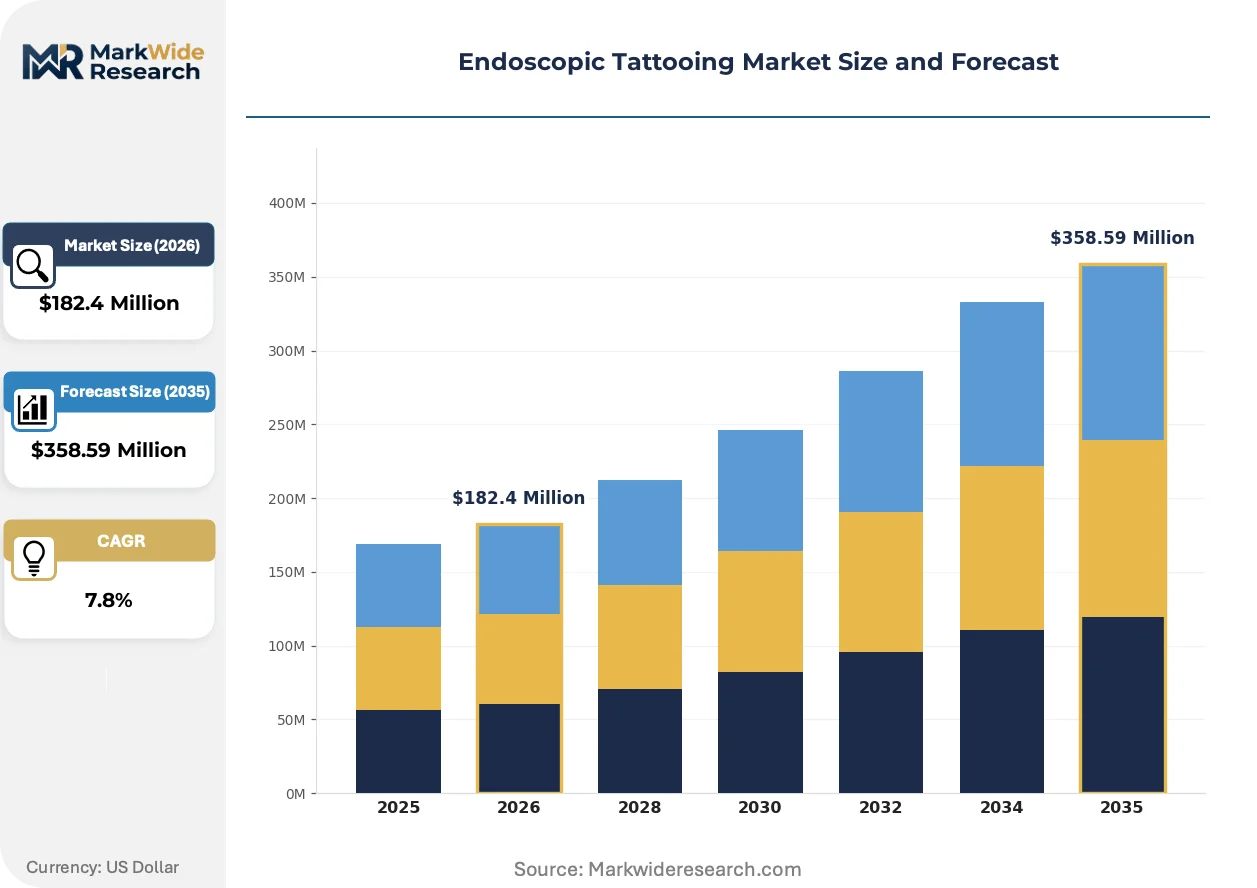
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $358.59 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Marker Pens, Dyes, Adhesive Markers, Pencils End User: Hospitals, Clinics, Research Facilities, Surgery Centers Application: Gastrointestinal Procedures, Urological Procedures, Gynecological Procedures, Other Medical Procedures Technology: Electrocoagulation, Laser-Based, Manual Techniques, Others |
| Companies Covered | ConMed Corporation, KARL STORZ SE & Co. KG, Boston Scientific Corporation, Fujifilm Holdings Corporation, Stryker Corporation, Cook Medical, Medtronic, Johnson & Johnson, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Tattooing Market Shifts & Advancements
Digital pathology integration and precision surgery workflows are demanding more sophisticated lesion marking capabilities than traditional carbon suspensions provide. Suppliers are responding with agent formulations engineered for multimodal detectability.
Fluorescent hybrid inks combining visible color with near-infrared signatures are rewriting surgical localization protocols. Academic medical centers in Germany and the United States are piloting these agents for robot-assisted colorectal resections. The technology is compressing operative time by enabling transmural visualization without intraoperative endoscopy.
The EU Medical Device Regulation's 2021 implementation timeline is forcing tattooing agent suppliers to rebuild technical documentation around biological safety evaluation. Sterility validation protocols now require endotoxin testing at batch-release levels previously reserved for implantable devices. European distributors are consolidating supplier relationships to manage heightened quality system audit burdens.
Subscription-based maintenance contracts for endoscopic visualization systems are unbundling accessory procurement from capital equipment cycles. Hospital systems in the United States are negotiating multi-year supply agreements that lock in tattooing agent volumes alongside platform service commitments. This bundling is visible most acutely in integrated delivery networks standardizing across twelve or more endoscopy sites.
Endoscopic Tattooing Market Segmentation
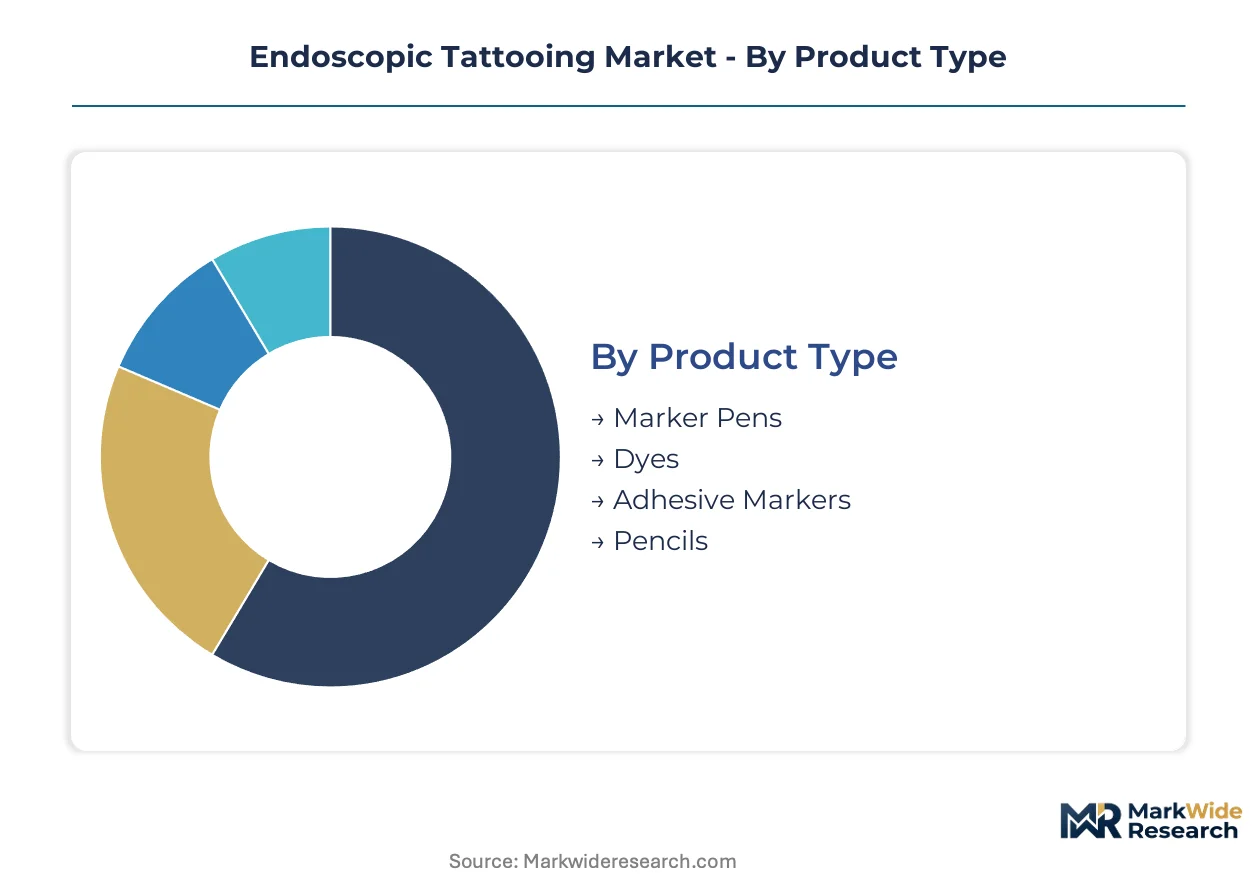
Segmentation in endoscopic tattooing reveals how procurement authority concentrates around platform compatibility and procedure volume economics. Hospital systems negotiate supply agreements that bundle agent formulations with visualization system maintenance, reshaping competitive dynamics across product categories.
Product Type:
Supply concentration in sterile ink manufacturing favors suppliers with integrated dye synthesis capabilities and pharmaceutical-grade carbon black sourcing relationships.
- Dyes:Carbon particle suspensions and sterile ink formulations dominate procurement volumes, with particle size distribution determining tissue retention performance. Demand concentrates in United States integrated delivery networks standardizing across multi-site colorectal surgery programs. FDA 510(k) pathway standardization under ISO 10993 biocompatibility frameworks accelerates sterile ink formulation entry timelines.
- Marker Pens:Single-use delivery devices with pre-filled ink reservoirs simplify workflow integration in ambulatory settings. United States ambulatory surgery centers expanding dedicated endoscopy suites drive procurement volume for disposable pen systems. Pre-filled designs reduce technician training burden and placement variability compared to manual injection techniques.
- Adhesive Markers:External surface markers applied during endoscopy for temporary lesion localization in low-complexity cases.
- Pencils:Reusable marking instruments requiring manual ink loading, retained in cost-sensitive regional hospital systems.
Today's leader: Dyes. Tomorrow's challenger: Marker Pens.
End User:
Procurement authority is shifting toward centralized supply chain functions as hospital systems consolidate endoscopy program management.
- Hospitals:Academic medical centers and community hospital systems perform the majority of complex colorectal resections requiring permanent tattoo placement. United States hospital systems negotiate multi-year supply agreements locking in tattooing agent volumes alongside endoscopy platform service commitments. Centralized procurement functions standardize product selection across twelve or more endoscopy sites.
- Surgery Centers:Freestanding gastrointestinal facilities in the United States install dedicated endoscopy suites with simplified workflow requirements. Ambulatory settings prioritize single-use delivery devices and pre-configured agent systems to minimize technician training investment. Medicare reimbursement coding for tattooing procedures directly influences purchasing decisions in these cost-constrained environments.
- Clinics:Office-based endoscopy practices performing screening colonoscopies with lower lesion localization complexity.
- Research Facilities:Academic centers piloting fluorescent hybrid ink formulations and near-infrared visualization protocols.
Procurement gravity: Hospitals. Volume expansion: Surgery Centers.
Application:
Procedure volume economics concentrate investment in screening program infrastructure and polypectomy follow-up workflows.
- Gastrointestinal Procedures:Colorectal cancer screening and polypectomy follow-up cases generate permanent marking demand across screening-age populations. Japan's METI-supported cancer early detection programs expand colonoscopy volumes, creating unmet demand for reliable tissue retention agents. Carbon suspension improvements extending retention times reduce repeat tattooing procedures and operative delays.
- Urological Procedures:Bladder and upper tract lesion marking for subsequent transurethral or laparoscopic resection.
- Gynecological Procedures:Cervical and endometrial lesion localization in gynecologic oncology workflows.
- Other Medical Procedures:Thoracic and general surgery applications with specialized marking requirements.
Volume anchor: Gastrointestinal Procedures. Emerging use case: Urological Procedures.
Technology:
Platform ecosystem control by dominant endoscope manufacturers shapes interoperability requirements for third-party delivery systems.
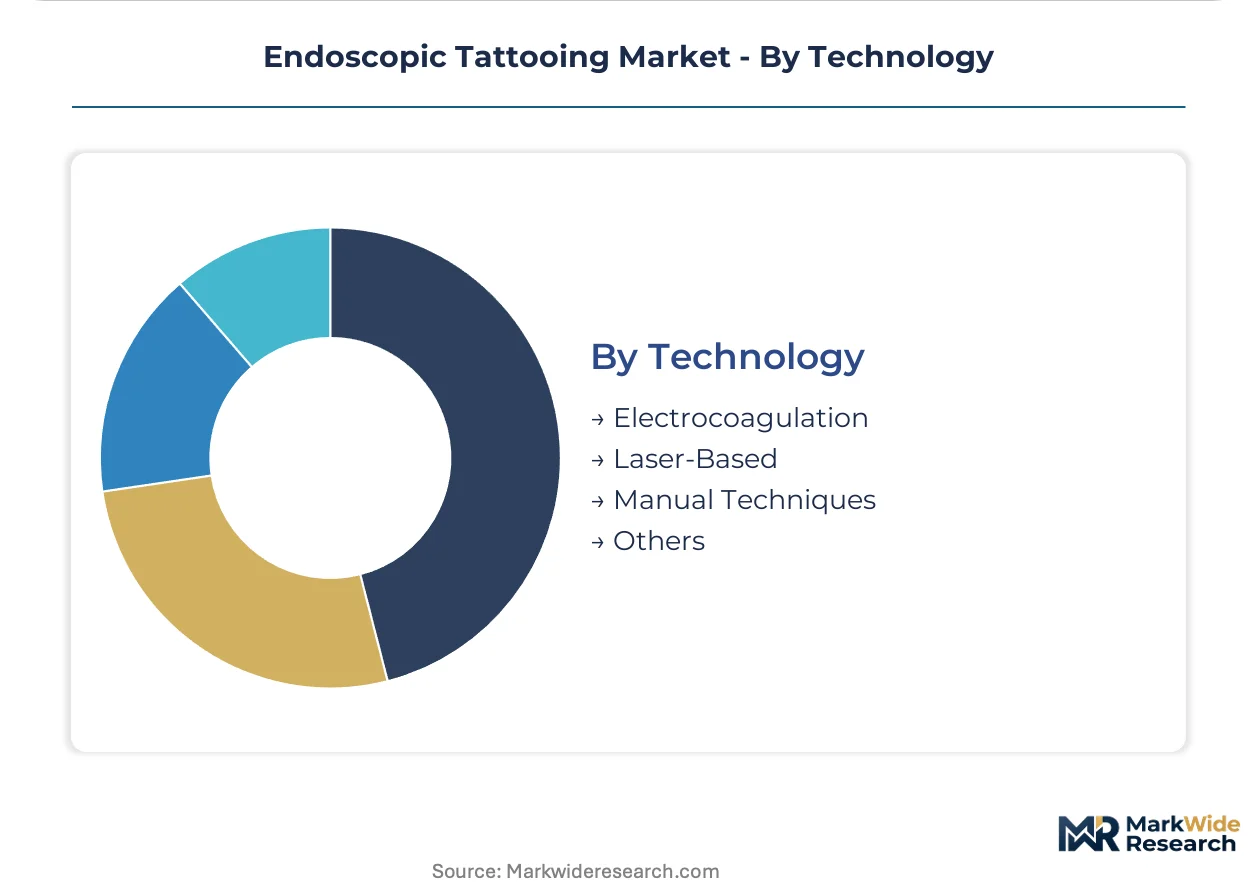
- Manual Techniques:Submucosal injection via standard endoscopic needles retains substantial share in cost-sensitive settings and legacy platform installations. Technique proficiency varies across ambulatory settings, affecting placement consistency and reintervention rates. GI endoscopy technician certification gaps create quality variation that suppliers address with simplified delivery device designs.
- Laser-Based:Electrocautery marking systems compete for lesion localization budgets in academic medical centers performing high-complexity cases. Near-infrared dye integration with standard visualization systems enables real-time margin confirmation during robot-assisted colorectal resections. Transmural visualization without intraoperative endoscopy compresses operative time in specialized centers.
- Electrocoagulation:Thermal marking devices for superficial lesion localization with limited tissue penetration.
- Others:Experimental fluorescence and hybrid detection modalities in development pipelines.
Installed base dominance: Manual Techniques. Technology frontier: Laser-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined medical device approval pathways. The EU MDR's expanded conformity assessment requirements are elevating compliance costs for tattooing agent suppliers, while the FDA's 510(k) framework offers clearer premarket entry timelines for sterile ink formulations.
United States
Integrated delivery networks in Texas and California are consolidating procurement across twelve or more endoscopy sites, compressing vendor selection cycles. The FDA's ISO 10993 biocompatibility framework governs sterile ink submissions, with 510(k) clearance timelines averaging shorter than EU MDR notified body assessments. Boston Scientific Corporation anchors its interventional endoscopy portfolio in the Greater Boston cluster, bundling tattooing adjuncts within therapeutic procedure packages.
Germany
Academic medical centers in Bavaria and Baden-Württemberg are piloting fluorescent hybrid inks for robot-assisted colorectal resections. The EU MDR's invasive surgical product classification rules expand notified body assessment requirements for tattooing agents distributed in European member states. Heidelberg and Munich host specialized endoscopy research clusters where near-infrared visualization protocols are undergoing clinical validation.
Japan
METI-supported cancer early detection programs are expanding colonoscopy volumes among the aging screening population in the Kanto and Kansai regions. The PMDA's pharmaceutical affairs law governs medical device registration, with streamlined pathways for products with prior FDA or CE marking. Tokyo and Osaka medical centers generate unmet demand for permanent marking agents with extended tissue retention performance.
India
The PLI scheme for medical devices is attracting tattooing delivery device assembly operations to Gujarat and Maharashtra for cost-sensitive Asian market supply. CDSCO's medical device rules require registration for Class B and C devices, though domestic manufacturing incentives reduce import dependency. Hyderabad and Bengaluru clusters are developing third-party dye formulation capabilities to serve regional endoscopy programs.
United Kingdom
NHS England's specialized commissioning frameworks are standardizing procurement of endoscopic accessories across integrated care systems in London and the Midlands. The MHRA's post-Brexit regulatory framework maintains alignment with EU MDR technical standards while offering independent approval pathways. Cambridge and Oxford academic medical centers participate in multicenter trials evaluating laser-based marking systems against carbon suspension techniques.
Endoscopic Tattooing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform ecosystem control by dominant endoscope manufacturers shaping accessory interoperability requirements. The supplier base concentrates around three strategic tiers: integrated medtech conglomerates with visualization system installed bases, interventional endoscopy specialists bundling tattooing adjuncts within therapeutic portfolios, and single-use delivery device manufacturers serving cost-sensitive ambulatory settings. Competitive moves center on multi-year supply agreement negotiations with integrated delivery networks and fluorescence-ink convergence R&D partnerships with academic medical centers.
Among integrated medtech conglomerates, Olympus Corporation and Fujifilm Holdings Corporation occupy positions defined by endoscopy platform ecosystem control, with proprietary delivery channel designs requiring custom adapter development for third-party tattooing agents. Boston Scientific Corporation exemplifies the interventional endoscopy specialist archetype, leveraging therapeutic procedure bundles to anchor tattooing adjuncts within broader product portfolios. These three companies represent the dominant competitive anchors shaping market access and procurement dynamics.
| Leading Market Players |
|---|
| ConMed Corporation |
| KARL STORZ SE & Co. KG |
| Boston Scientific Corporation |
| Fujifilm Holdings Corporation |
| Stryker Corporation |
| Cook Medical |
| Medtronic |
| Johnson & Johnson |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Integrated delivery network consolidation across United States hospital systems is compressing vendor selection cycles and forcing tattooing agent suppliers to absorb certification costs while maintaining sterile ink formulation quality. This buyer concentration elevates platform compatibility premiums and squeezes margins for third-party delivery device manufacturers lacking direct endoscopy system integration.
Pricing Analysis
Distributor margins of 15-25% separate sterile ink manufacturers from hospital procurement committees, with three-tier pricing structure across premium, standard, and economy levels differentiated by ISO 10993 certification tier and particle size distribution precision. Academic medical centers show lowest price sensitivity due to reimbursement pass-through mechanisms, while ambulatory surgery centers in cost-constrained environments drive volume toward pre-filled marker pen formats. Cost compression in economy-tier carbon suspensions is intensifying because single-source pharmaceutical-grade carbon black suppliers command input pricing power.
Supply Chain Analysis
Pharmaceutical-grade carbon black supply rests on three specialty chemical producers in the United States, Germany, and Japan, with sterile ink formulation capacity concentrated in FDA-registered and EU MDR-notified facilities across these same markets. Raw material dependencies include carbon particle feedstock, medical-grade ink vehicles, and single-use polymer delivery components. Single-source vulnerability in carbon black supply creates concentration risk for suspension-based products. Distribution runs through medtech distributors with GPO contracts and direct hospital system agreements for integrated delivery network procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where permanent marking agent specifications are tightening as robot-assisted colorectal resections demand fluorescent hybrid ink capabilities with near-infrared detectability.
For Market Incumbents: Deepen backward integration into pharmaceutical-grade carbon black sourcing to defend against input concentration risk from the three dominant suppliers. Lock in multi-year supply agreements with United States integrated delivery networks standardizing across twelve or more endoscopy sites, anchoring tattooing adjuncts within visualization system maintenance bundles to forestall third-party marker pen displacement.
For New Entrants and Emerging Players: The gap between premium fluorescent hybrid inks and economy carbon suspensions opens white-space targeting for mid-tier sterile ink formulations with extended tissue retention. India's PLI scheme for medical devices offers the most penetrable geography for delivery device assembly serving cost-sensitive Asian markets. A GPO contract pathway with ambulatory surgery center networks provides the cleanest go-to-market angle bypassing dominant platform ecosystem control.
For Investors and Strategic Acquirers: Asymmetric upside sits with single-use delivery device specialists possessing FDA 510(k) clearance and EU MDR technical documentation for pre-filled marker systems. Long-term viability over the next decade hinges on fluorescence-ink convergence R&D partnerships with academic medical centers piloting near-infrared visualization protocols. The signal to watch as inflection indicator is Medicare reimbursement coding expansion for tattooing procedures in ambulatory settings.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorescent Hybrid Ink Development | Near-infrared dye integration enables real-time margin confirmation during robot-assisted colorectal resections. |
| EU MDR Technical Documentation Rebuild | Biological safety evaluation expansion opens European market access for sterile ink formulations. |
| Integrated Delivery Network Supply Agreement | Multi-year contracts with United States hospital systems lock in volumes across twelve or more endoscopy sites. |
| India PLI Manufacturing Footprint | Domestic assembly operations in Gujarat and Maharashtra reduce cost structures for Asian market supply. |
| Platform Compatibility Adapter Development | Custom delivery channel designs overcome proprietary interoperability barriers from dominant endoscope manufacturers. |
Research Methodology
Direct dialogue with hospital procurement managers, GPO contracts specialists, biomedical engineers, and interventional gastroenterologists grounded the qualitative assessment, cross-referenced against FDA 510(k) filings, EU MDR notified body assessments, hospital procurement databases, and CMS Medicare reimbursement coding records. Secondary validation drew from ISO 10993 biocompatibility testing protocols and carbon black supplier technical specifications. Bottom-up and top-down triangulation reconciled procedure volume estimates with supply-side manufacturing capacity.
Bottom-up modeling built from country-level colonoscopy screening program volumes, polypectomy follow-up rates, and tattoo placement protocol penetration by procedure type. Top-down analysis cross-checked against endoscopy platform installed bases and visualization system maintenance contract coverage. Segmentation across product type, end user, application, and technology dimensions shaped the projection framework. CAGRs derived from fitted growth curves incorporating Japan's METI-supported screening expansion and United States ambulatory surgery center buildout trajectories.
Caveats apply where EU MDR notified body assessment delays or carbon black supply disruptions could materially shift the outlook for sterile ink formulation entry timelines. Forecasts reflect assumptions around reimbursement coding stability and platform ecosystem interoperability standards. A small set of named triggers—Medicare contractor coverage determinations, fluorescent hybrid ink clinical validation results, and integrated delivery network procurement centralization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Automated Endoscopy Reprocessor Market
Endoscopy
Duodenoscope Market
Endoscopy
US Colonic Stents Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
United Kingdom Endoscopy Devices Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
Sigmoidoscope Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Global Endoscope Leak Detection Device Market