
 Brachytherapy Market | 2026-2036
Brachytherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Brachytherapy Market Intelligence
Multi-source component sourcing is recalibrating how brachytherapy device manufacturers secure iridium-192 and iodine-125 isotopes. Varian Medical Systems leverages captive supply agreements with domestic reactor operators to reduce import dependency for high dose rate sources. Elekta AB anchors its European installed base through long-term service contracts that bundle afterloader hardware with proprietary treatment planning software. Eckert & Ziegler BEBIG competes on geographic reach, maintaining production facilities across Germany and the United States to shorten lead times for custom source configurations.
Brachytherapy delivers targeted radiation through temporarily or permanently implanted radioactive sources placed in direct contact with tumor tissue, typically using sealed capsules containing isotopes such as cesium-137 or palladium-103 with dose rates measured in Grays per hour. The technique enables conformal dose distribution that spares adjacent healthy organs, making it standard of care for localized prostate malignancies and select gynecological cancers. High dose rate afterloading systems dominate current revenue pools due to shorter treatment times and outpatient compatibility, while electronic brachytherapy represents the fastest-expanding segment as water-cooled X-ray sources eliminate radioactive material handling burdens. Prostate cancer applications sustain the largest therapy area volume, though breast cancer intraoperative procedures are gaining protocol adoption in specialized cancer clinics seeking intraoperative radiation alternatives.
FDA 510(k) clearance and EU MDR conformity assessment shape product development timelines, with the FDA requiring biocompatibility and dosimetric validation for all new source designs while EU MDR demands updated clinical evidence for legacy devices previously approved under the Medical Device Directive. The EPA and NRC jointly regulate sealed source possession, transportation, and disposal in the United States, creating compliance barriers that favor established vendors with dedicated radiation safety infrastructure. Stakeholders must monitor reimbursement code valuations for electronic brachytherapy procedures, as coverage determinations by Medicare and major European payors will decide whether capital investment in X-ray source platforms displaces traditional isotope-dependent systems.
Market Dynamics
Electronic brachytherapy systems are compressing treatment timelines while eliminating radioactive isotope dependencies, forcing established vendors to reconfigure hardware portfolios and service architectures around water-cooled X-ray platforms.
Growth Catalysts
- Prostate cancer protocols:Outpatient high dose rate procedures reduce hospital bed utilization while maintaining biochemical recurrence rates comparable to radical prostatectomy, driving urology clinic investment in afterloader systems.
- EU MDR clinical evidence requirements:Updated conformity assessment pathways for legacy sealed-source devices create competitive moats for manufacturers with established quality management systems and clinical data repositories.
- Cesium-137 substitution:Reactor production constraints and transportation security burdens are accelerating iodine-125 adoption for low dose rate permanent implants in localized malignancies.
Market Restraints
- Iridium-192 supply concentration:Production depends on aging research reactors in Canada and South Africa, with scheduled maintenance creating predictable shortage windows that disrupt treatment scheduling.
- Capital intensity of electronic platforms:Water-cooled X-ray source systems require specialized electrical infrastructure and shielding retrofits that exceed typical linear accelerator installation costs.
- Reimbursement code valuation compression:Medicare physician fee schedule adjustments for brachytherapy procedures lag equipment depreciation cycles, squeezing free-standing oncology center margins.
Strategic Opportunities
- Breast intraoperative radiation:Intraoperative electronic brachytherapy during lumpectomy procedures addresses unmet demand for single-session adjuvant therapy in community hospital settings.
- Japan's aging reactor infrastructure:Domestic isotope production shortfalls create import substitution openings for sealed-source vendors with established PMDA quality system certifications.
- AI-enabled treatment planning:Machine learning algorithms for dwell time optimization converge with cloud-based dose calculation platforms to reduce physicist staffing requirements per procedure.
Industry Challenges
- Medical physicist scarcity:Specialized training requirements for brachytherapy dosimetry and source commissioning exceed pipeline output from accredited residency programs.
- Legacy afterloader integration:New electronic source platforms must interface with decade-old treatment planning software architectures, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brachytherapy Market |
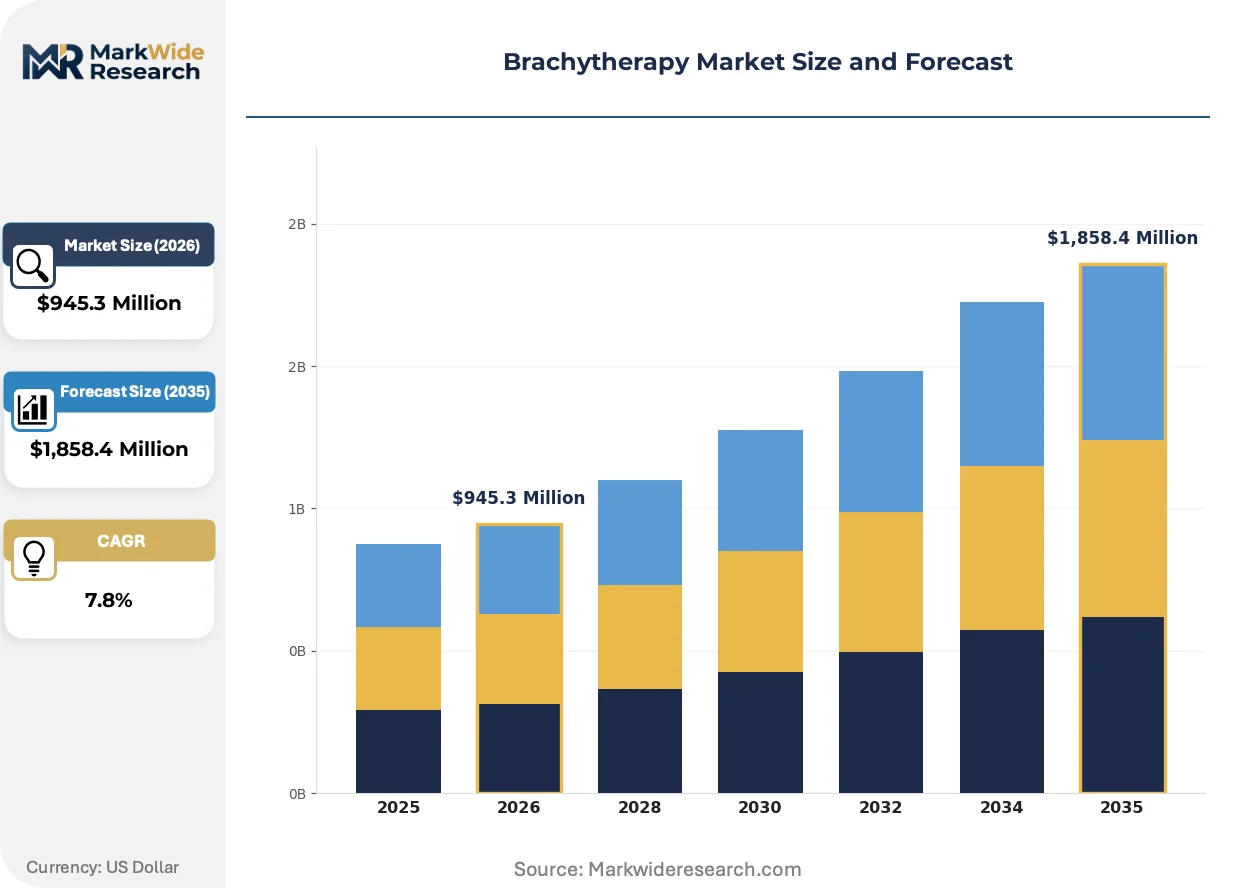
| Market Size in 2026 | $945.3 Million |
| Market Size in 2035 | $1,858.4 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Dose Rate, Low Dose Rate, Pulsed Dose Rate, Electronic Brachytherapy Therapy Area: Prostate Cancer, Cervical Cancer, Breast Cancer, Eye Cancer, Esophageal Cancer End User: Radiation Oncology Centers, Specialized Cancer Clinics, Research Institutes, Ambulatory Surgical Centers Delivery Mode: Afterloading Devices, Manual Loading, Remote Control Systems, Robotic Assistance |
| Companies Covered | Varian Medical Systems, Elekta AB, Becton Dickinson and Company, Eckert & Ziegler BEBIG, IsoRay, Theragenics Corporation, iCAD, CIVCO Medical Solutions, Carl Zeiss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brachytherapy Market Strategic Shifts & Innovations
Hardware commoditization is compressing margins across afterloader systems while software-defined treatment workflows and isotope-free platforms emerge as primary value differentiation vectors.
Electronic brachytherapy is consolidating technical validation around water-cooled X-ray sources that eliminate NRC possession license requirements. Freestanding radiation oncology centers in the United States are adopting these systems at replacement cycle points to reduce regulatory overhead. This technology is consolidating market structure by collapsing the traditional distinction between brachytherapy and external beam modalities.
EU MDR conformity assessment timelines are extending market access for legacy sealed-source devices previously approved under the Medical Device Directive. Manufacturers must generate updated clinical evidence or execute equivalence justifications for established iridium-192 source designs. High dose rate afterloader systems with extensive installed bases face the most significant documentation burdens.
Service unbundling is fragmenting traditional hardware-software-research reactor bundle structures. Oncology centers increasingly procure treatment planning software subscriptions independent of afterloader hardware, then source isotopes through third-party radiopharmaceutical distributors. Germany exhibits the most advanced disaggregation, with university hospitals leading procurement model experimentation.
Brachytherapy Market Segmentation
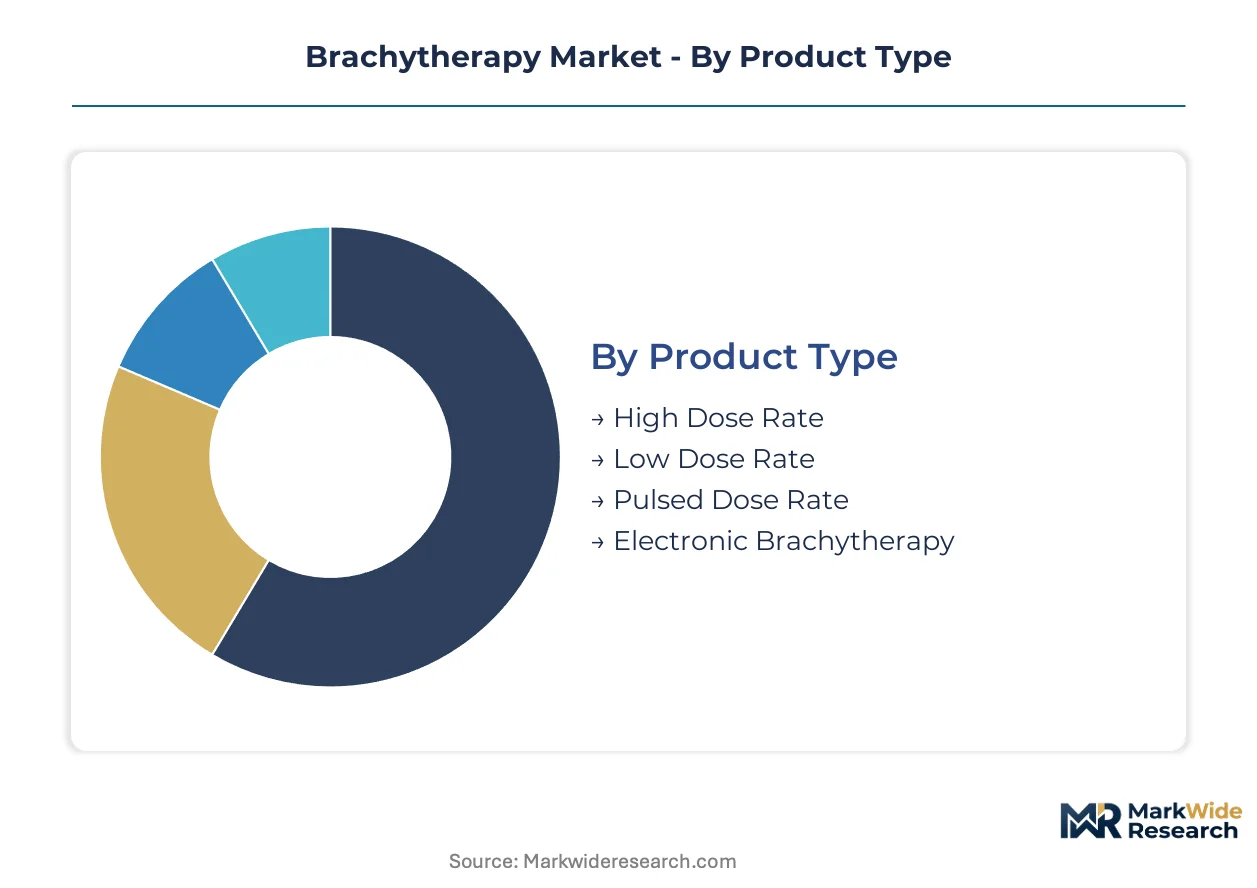
Segmentation in brachytherapy reveals how clinical workflows, regulatory constraints, and capital availability fragment purchasing decisions across institutions. Understanding these divisions exposes where hardware commoditization pressures software-defined differentiation and where isotope dependencies create vendor lock-in effects.
Product Type:
Procurement committees weight upfront capital against recurring isotope costs and regulatory burden when selecting dose delivery platforms.
- High Dose Rate:Afterloader systems using iridium-192 sources deliver concentrated radiation in minutes through remote-controlled catheters. United States radiation oncology centers favor HDR for prostate protocols due to outpatient reimbursement alignment and NRC possession license efficiencies.
- Electronic Brachytherapy:Water-cooled X-ray sources eliminate sealed-source handling entirely, collapsing brachytherapy into external beam regulatory categories. Freestanding clinics in Germany and Japan adopt these systems at replacement cycles to bypass reactor supply volatility.
- Low Dose Rate:Permanent iodine-125 or palladium-103 implants deliver continuous radiation over months for localized prostate malignancies.
- Pulsed Dose Rate:Hybrid systems combine HDR dose intensity with LDR biological effectiveness through programmable pulse intervals.
Volume sits with High Dose Rate; growth tilts toward Electronic Brachytherapy.
Therapy Area:
Tumor site determines reimbursement code valuation, procedure complexity, and competitive modality threat from external beam alternatives.
- Prostate Cancer:Transperineal needle placement of permanent or temporary sources dominates localized malignancy protocols. United States urology clinics drive installed base expansion where biochemical recurrence rates match radical prostatectomy with lower incontinence profiles.
- Breast Cancer:Intraoperative radiation during lumpectomy addresses adjuvant therapy demand in community hospital settings. Specialized cancer clinics in Germany and Japan pilot electronic brachytherapy for single-session treatment completion.
- Cervical Cancer:Intracavitary tandem and ovoid applications remain standard for locally advanced gynecological malignancies.
- Eye Cancer:Plaque brachytherapy for uveal melanoma requires custom source configurations and specialized ophthalmic surgical coordination.
- Esophageal Cancer:Intraluminal applications for obstructive tumors face competition from chemoradiation and stenting alternatives.
Prostate Cancer commands the largest procedure volume; Breast Cancer applications are climbing the fastest.
End User:
Institutional scale dictates whether procurement favors bundled service contracts or unbundled component sourcing.
- Radiation Oncology Centers:High-volume institutions with dedicated physicist staffing prioritize HDR afterloader throughput and treatment planning software integration. United States hospital networks negotiate multi-system enterprise agreements with established vendors.
- Ambulatory Surgical Centers:Limited-space facilities seek electronic brachytherapy platforms that eliminate shielding retrofits and NRC licensing overhead. German outpatient clinics lead adoption where CE marking streamlines installation timelines.
- Specialized Cancer Clinics:Focused institutions balance procedure mix against modality diversification requirements.
- Research Institutes:Academic medical centers demand investigational device access and clinical trial participation rights.
Radiation Oncology Centers anchor current revenue; Ambulatory Surgical Centers represent the steepest expansion trajectory.
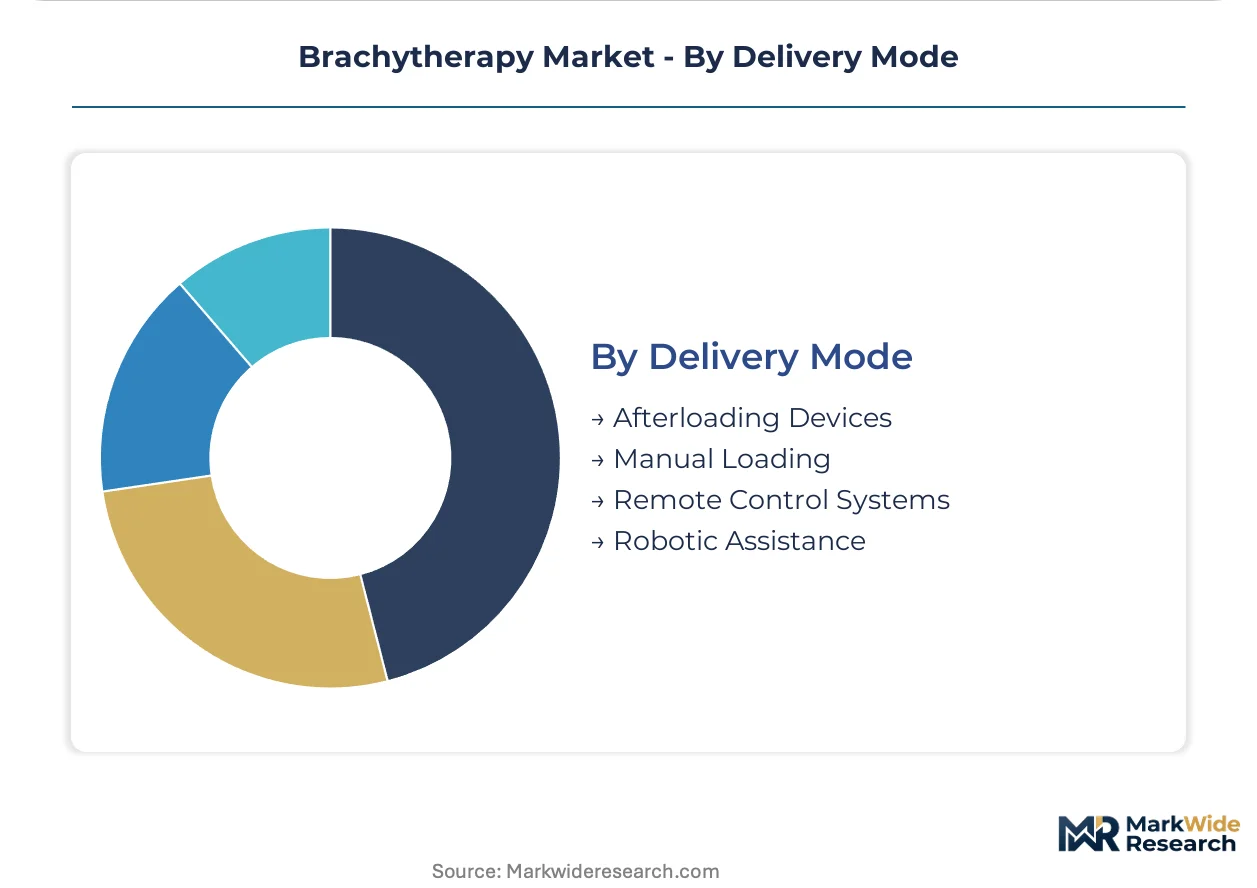
Delivery Mode:
Automation level determines staffing ratios, source security protocols, and integration complexity with legacy treatment planning architectures.
- Afterloading Devices:Remote source positioning systems dominate HDR procedures through computer-controlled dwell time optimization. United States and Japanese installations favor these systems for physicist productivity and radiation safety compliance.
- Robotic Assistance:Needle guidance and source placement automation address medical physicist scarcity and procedure standardization demands. German university hospitals evaluate robotic platforms for prostate and gynecological applications.
- Manual Loading:Direct source handling persists in low-resource settings and specific plaque configurations.
- Remote Control Systems:Networked afterloader operation enables centralized physicist coverage across distributed clinic networks.
Afterloading Devices hold the dominant installed base; Robotic Assistance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iridium-192 reactor production concentrates in Canada and South Africa, creating geographic dependencies that shape procurement patterns across treatment centers worldwide. Reimbursement frameworks and regulatory pathways in specific national markets determine whether clinics invest in isotope-dependent systems or pivot toward electronic alternatives.
United States
Outpatient prostate cancer protocols drive HDR afterloader demand where Medicare reimbursement codes favor shorter treatment courses. FDA 510(k) clearance pathways and NRC possession licensing create compliance moats favoring established vendors with dedicated radiation safety infrastructure. Major cancer centers in Houston and Boston anchor enterprise procurement negotiations for multi-system hospital network agreements.
Germany
University hospitals in Munich and Heidelberg lead service unbundling experiments, procuring treatment planning software independent of afterloader hardware. EU MDR conformity assessment requirements under the Medical Device Regulation extend timelines for legacy sealed-source device recertification. The country's national pharmaceutical regulator demands updated clinical evidence for iridium-192 source designs previously approved under the Medical Device Directive.
Japan
Aging domestic reactor infrastructure creates isotope production shortfalls that open import substitution opportunities for sealed-source vendors. PMDA quality system certifications serve as gatekeeping requirements for market entry. Oncology centers in Tokyo and Osaka prioritize electronic brachytherapy platforms to bypass supply volatility and streamline installation timelines.
India
Government hospitals in Delhi and Mumbai expand radiotherapy capacity under national cancer control programs with budget constraints favoring manual loading configurations. CDSCO medical device regulations tighten import requirements for sealed-source devices while domestic manufacturing incentives remain limited. Private hospital chains in Bangalore and Hyderabad pilot robotic assistance platforms to address medical physicist scarcity.
United Kingdom
NHS procurement frameworks consolidate purchasing power across regional cancer networks, favoring vendors with comprehensive service contracts. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining conformity assessment for innovative electronic platforms. London and Manchester academic medical centers drive clinical trial participation for next-generation afterloader systems.
Brachytherapy Market Key Industry Players
Global majors compete with regional champions across reactor supply agreements and software integration capabilities. The vendor base clusters around three strategic tiers: diversified radiation therapy conglomerates with captive isotope sourcing, specialized afterloader manufacturers with hardware-software bundles, and emerging electronic platform developers eliminating radioactive material dependencies entirely. Dominant competitive moves include backward integration into reactor supply chains and geographic expansion through localized service infrastructure.
Within the diversified conglomerate tier, Varian Medical Systems and Elekta AB occupy positions anchored by installed base scale and long-term service contract penetration. Eckert & Ziegler BEBIG exemplifies the specialized manufacturer archetype with production facilities spanning multiple continents to shorten lead times for custom source configurations. These three entities represent distinct strategic postures: captive supply security, software-defined workflow integration, and geographic proximity manufacturing respectively.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Becton Dickinson and Company |
| Eckert & Ziegler BEBIG |
| IsoRay |
| Theragenics Corporation |
| iCAD |
| CIVCO Medical Solutions |
| Carl Zeiss |
| Others |
Cost & Logistics Intelligence
Iridium-192 spot pricing volatility cascades through brachytherapy device tiers, compressing margins for isotope-dependent afterloader systems while elevating electronic platform competitiveness in procurement committees weighing total cost of ownership against upfront capital outlay.
Pricing Analysis
Extended warranty and source-replacement bundling separates premium HDR system contracts from unbundled procurement models gaining traction in German university hospitals. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and physicist training inclusion. Cost compression in the mid-tier is intensifying because electronic platforms eliminate recurring isotope expenditures. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while major hospital networks prioritize throughput optimization over unit economics.
Supply Chain Analysis
Specialized freight forwarding for sealed radioactive sources adds cost layers that electronic platform distributors bypass entirely. Production of iridium-192 and iodine-125 isotopes centers on Canada, South Africa, and Belgium reactor facilities. Manufacturing of afterloader hardware draws from German precision engineering and Japanese mechatronics suppliers. Single-source vulnerability in aging research reactor infrastructure creates predictable shortage windows. Distribution runs through authorized radiopharmaceutical distributors with NRC or national nuclear regulator licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over reactor supply agreements or isotope-eliminating electronic platforms determines sustainable margin structures.
For Market Incumbents: Hedge reactor dependency exposure through dual-source isotope contracting and accelerated electronic platform R&D to counter water-cooled X-ray entrants. Secure backward integration into domestic reactor partnerships where geographic proximity shortens lead times. Fortify installed base retention with treatment planning software subscriptions that raise switching costs for oncology centers evaluating unbundled procurement.
For New Entrants and Emerging Players: Begin with ambulatory surgical center targeting in Germany and Japan where CE marking and PMDA pathways favor electronic platforms eliminating shielding retrofits. Address medical physicist scarcity through AI-enabled dwell time optimization as differentiated value proposition. Pursue hospital system partnership models that bundle staff training with hardware deployment to accelerate reference site establishment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor electronic platform developers with FDA 510(k) clearance and established reimbursement code valuations in the United States. Long-term viability hinges on displacement trajectory of isotope-dependent systems over the next decade. Monitor Medicare physician fee schedule adjustments for electronic brachytherapy procedures as inflection indicator for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Supply Agreement | Captive isotope sourcing insulates Varian and Elekta from Canadian reactor maintenance disruptions. |
| CE Marking Pathway | EU MDR conformity assessment timelines favor electronic platforms with simpler clinical evidence requirements. |
| Hospital System Partnership | Enterprise agreements with Houston and Boston cancer centers anchor multi-system procurement decisions. |
| Software Companion Development | Cloud-based dose calculation platforms reduce physicist staffing requirements per procedure. |
| Reimbursement Strategy | Medicare coverage determinations for electronic brachytherapy will decide X-ray source platform viability. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with radiation oncologists, medical physicists, hospital purchasing committee members, and GPO contracts managers. FDA 510(k) databases, NRC sealed source possession reports, EU MDR conformity assessment documentation, and hospital procurement databases provided structural validation. Bottom-up procedure volume estimates triangulated against top-down equipment installation data.
Shipment data reconciliation with reimbursement code utilization statistics informed volume projections across the analysis window. Segmentation modeling incorporated product type, therapy area, end user scale, and delivery mode automation level. CAGRs derived from installed base replacement cycles, protocol adoption curves, and payer coverage expansion trajectories. Forecast inputs included reactor production schedules, physicist residency graduation rates, and electronic platform technical validation timelines.
Underlying measurement precision varies by segment; electronic brachytherapy growth estimates carry tighter precision than isotope supply forecasts given reactor infrastructure uncertainty. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Bioresorbable Coronary Scaffolds Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Sphincterotomes Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
GCC Implantable Medical Devices Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Global Self-Injection Device Market