
 Bowel Stimulators Market | 2026-2036
Bowel Stimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Bowel Stimulators Market Outlook
Recurring revenue from remote programming and cloud-based therapy optimization is shifting how manufacturers capture lifetime value from each implant. Medtronic plc leverages its proprietary CareLink network to sustain long-term patient engagement beyond the initial procedure. Axonics, Inc. differentiates through rechargeable systems that reduce replacement frequency and anchor higher-margin service contracts.
Bowel stimulators are implantable or external neuromodulation devices that deliver targeted electrical impulses to sacral nerves or colonic tissue to restore defecation rhythm, typically operating at frequencies between 10-40 Hz with pulse widths calibrated to afferent fiber recruitment. These systems serve patients with refractory lower gastrointestinal motility disorders where pharmaceutical and behavioral interventions have failed. Implantable systems command premium pricing due to surgical placement requirements and extended battery longevity, while external transcutaneous platforms expand addressable populations through non-invasive access. Neurogenic bowel dysfunction applications represent the fastest-growing clinical segment as spinal cord injury and multiple sclerosis populations age, whereas chronic constipation remains the largest volume category with established reimbursement codes.
The FDA's breakthrough device program and the EU Medical Device Regulation reshape clinical evidence requirements, with FDA demanding prospective bowel movement diary endpoints and EMA's notified bodies enforcing stricter biocompatibility testing for implantable pulse generators. Japan's PMDA has tightened electrical safety standards for neuromodulation hardware, extending review timelines for foreign manufacturers. Stakeholders must monitor how CMS national coverage determinations for sacral nerve stimulation evolve relative to emerging closed-loop adaptive algorithms.
Market Dynamics
Neuromodulation hardware miniaturization is compressing surgical footprints and accelerating same-day discharge protocols, fundamentally altering how providers deploy sacral nerve stimulation systems across outpatient settings.
Growth Catalysts
- Breakthrough Device Pathway:FDA's accelerated review mechanism shortens commercialization timelines for novel closed-loop algorithms, enabling faster patient access to adaptive stimulation protocols.
- Reimbursement Expansion:CMS national coverage determinations for sacral nerve stimulation now extend to neurogenic bowel dysfunction, broadening addressable populations beyond chronic constipation.
- Cloud-Based Therapy Optimization:Remote programming platforms sustain long-term patient engagement through subscription revenue models that decouple manufacturer value from hardware replacement cycles.
Market Restraints
- Biocompatibility Testing Burden:EMA's notified bodies enforce stricter implantable pulse generator requirements under MDR, extending European regulatory timelines and inflating pre-market costs.
- Lithium-Ion Supply Concentration:Rechargeable system manufacturers face input vulnerability from concentrated Asian battery cell production, creating procurement risk for extended-life neuromodulation platforms.
- Transcutaneous Substitution:External stimulation devices capture price-sensitive segments with non-invasive access, pressuring premium pricing for implantable surgical systems.
Strategic Opportunities
- Home Care Penetration:Outpatient bowel management protocols in Germany and France expand addressable demand beyond hospital-based implantation centers.
- Closed-Loop Convergence:Adaptive algorithms integrating real-time physiological feedback represent unclaimed white space distinct from open-loop stimulation paradigms.
- Japan's Aging Demographics:PMDA regulatory alignment with international standards creates pathway for foreign manufacturers targeting spinal cord injury populations.
Industry Challenges
- Electrical Safety Certification:PMDA's tightened neuromodulation hardware standards demand extended electromagnetic compatibility testing, compressing development timelines.
- Interdisciplinary Surgical Training:Sacral nerve implantation requires urogynecology-colorectal coordination that outpaces current fellowship pipeline capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bowel Stimulators Market |
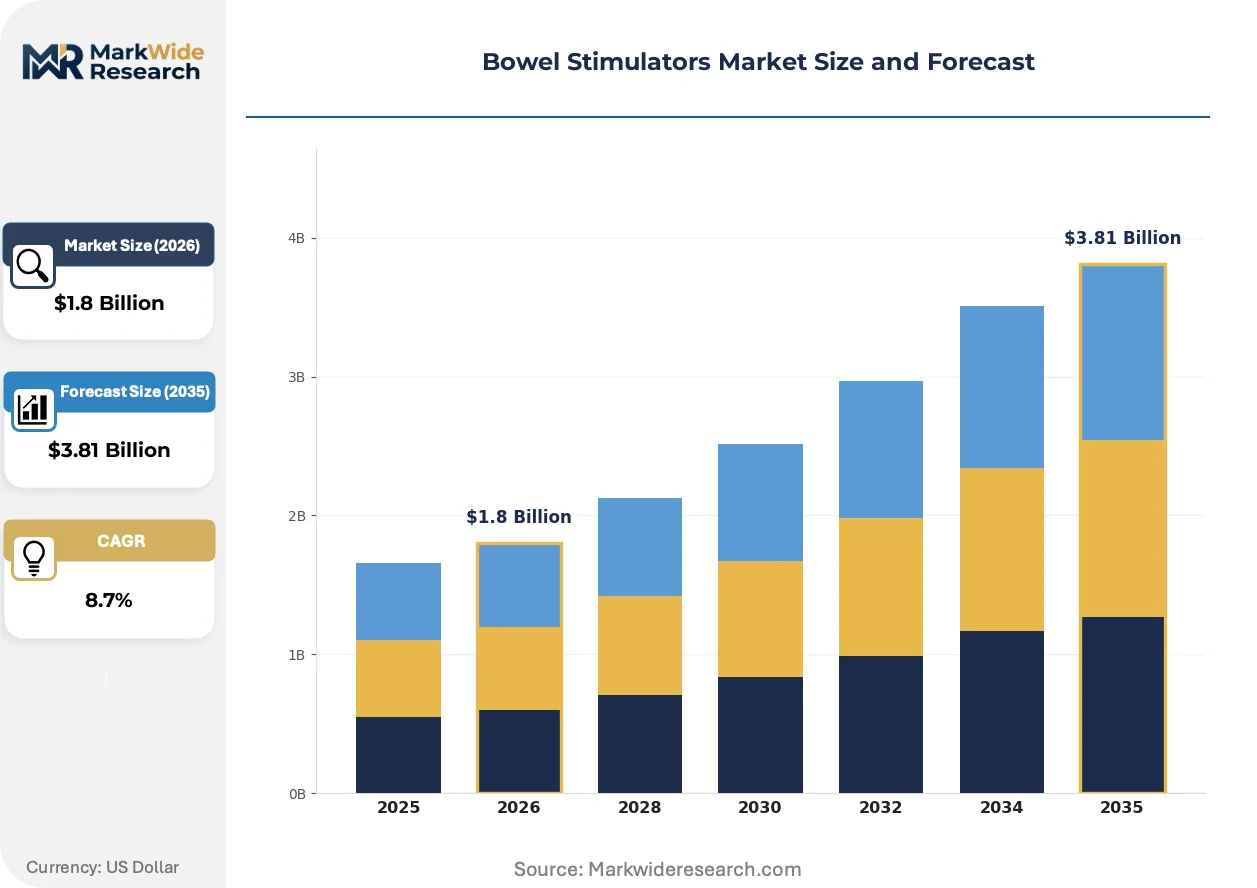
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Stimulators, Non-Electrical Devices, Implantable Systems, External Systems End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Application: Chronic Constipation, Neurogenic Bowel Dysfunction, Fecal Incontinence, Colonic Motility Disorders Technology: Transcutaneous Electrical Nerve Stimulation, Sacral Nerve Stimulation, Intravenous Techniques, Novel Therapeutic Approaches |
| Companies Covered | Medtronic plc, Axonics, Inc., Laborie Medical Technologies, B. Braun SE, Boston Scientific Corporation, Abbott Laboratories, LivaNova PLC, Nevro Corp., Coloplast A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bowel Stimulators Market Strategic Shifts
Digital health integration is redefining how bowel stimulator manufacturers capture lifetime value, shifting competitive advantage from hardware specifications to continuous therapy optimization capabilities.
Closed-loop adaptive algorithms are converging with cloud-based patient monitoring platforms to enable real-time parameter adjustment based on defecation pattern recognition. Academic medical centers in the United States and Netherlands are piloting these systems for spinal cord injury populations. This convergence is compressing the traditional distinction between implantable hardware and digital therapeutic services.
EU Medical Device Regulation enforcement is intensifying clinical evidence requirements for implantable pulse generators, mandating prospective bowel movement diary endpoints that exceed historical 510(k) standards. Notified bodies in Germany and Ireland are rejecting legacy biocompatibility data, forcing manufacturers to regenerate preclinical packages. Small-cap developers without European regulatory infrastructure are retreating to US-only commercialization strategies.
After-sales service unbundling is fragmenting traditional device-procurement relationships as hospital systems negotiate remote programming and cloud access separately from implant hardware. Integrated delivery networks in California and Texas are leading this disaggregation, pressuring manufacturers to disclose algorithm update pricing. This behavioral shift compresses upfront capital commitments while elongating vendor accountability windows.
Bowel Stimulators Market Segmentation
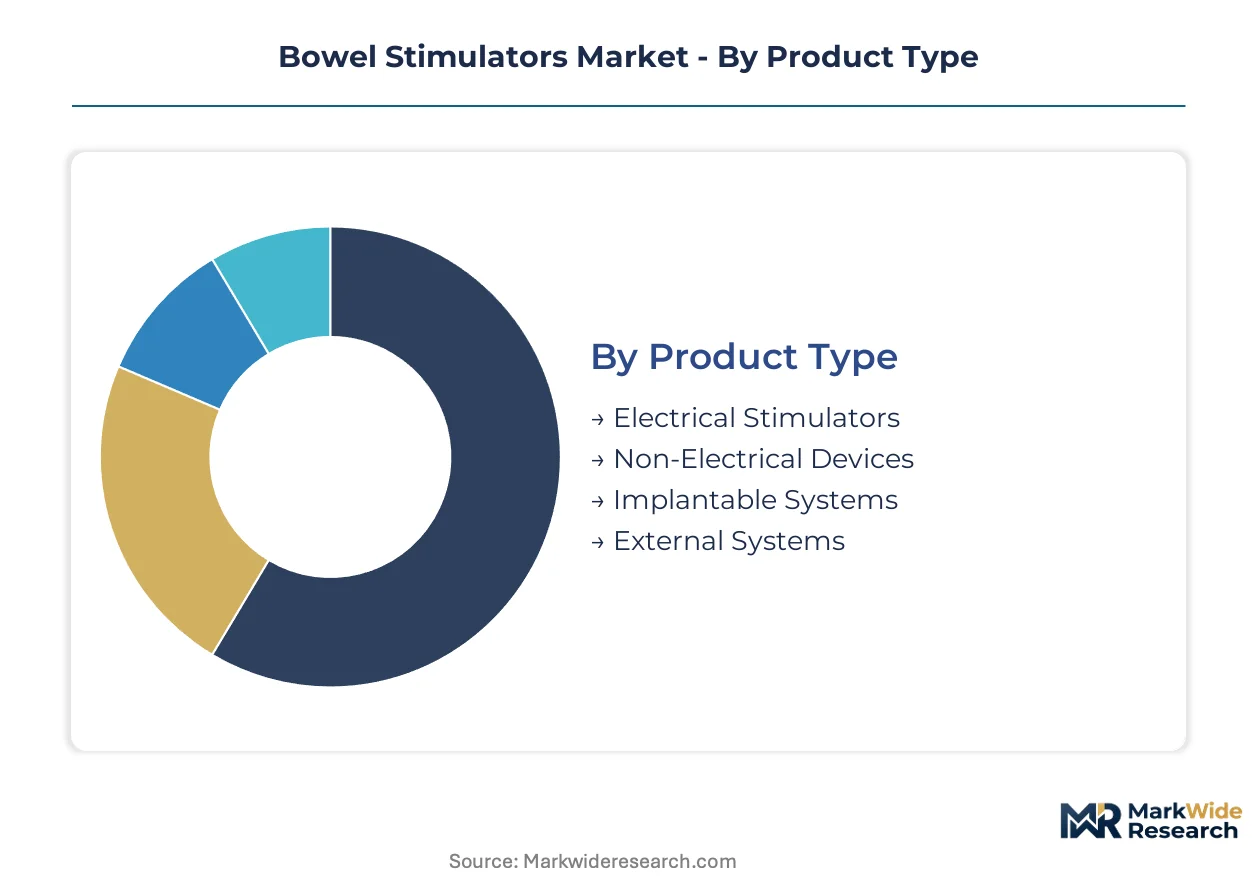
Segmentation in bowel stimulators reveals how capital deployment, reimbursement pathways, and clinical settings fragment commercial opportunity. Manufacturers must align product architecture with specific procurement channels and patient acuity levels to capture margin.
Product Type:
Implantable systems demand substantial upfront surgical infrastructure and long-term battery engineering investment, while external platforms require lower capital commitment but sacrifice pricing power.
- Implantable Systems:These devices integrate pulse generators with lead assemblies for direct sacral nerve interfacing, requiring operating room deployment and specialized implantation training. United States hospital systems concentrate procurement through integrated delivery networks that negotiate multi-year service bundles, with CMS reimbursement codes anchoring pricing stability.
- External Systems:Transcutaneous platforms deliver neuromodulation through skin-surface electrodes, eliminating surgical risk and expanding addressable populations to outpatient and home settings. German home care providers are expanding adoption as patients seek bowel management solutions outside institutional environments, though price sensitivity compresses margins relative to implantable alternatives.
- Electrical Stimulators:Devices delivering targeted impulse patterns at calibrated frequencies for nerve fiber recruitment, dominating clinical protocols for neurogenic dysfunction.
- Non-Electrical Devices:Mechanical or pharmacological bowel management systems serving price-sensitive segments and contraindicated electrical stimulation populations.
Implantable systems absorb the bulk of installed capacity; external systems are expanding most quickly.
End User:
Procurement authority concentrates differently across settings, with hospitals maintaining capital equipment budgets while home care channels favor disposable or rental models.
- Hospitals:Academic medical centers and tertiary facilities perform complex implantations for spinal cord injury and multiple sclerosis populations, requiring interdisciplinary surgical teams and dedicated neuromodulation service lines.
- Home Care:Outpatient bowel management protocols in France and Germany drive external device adoption as patients transition from institutional to residential settings, with remote programming platforms sustaining manufacturer engagement beyond initial dispensing.
- Clinics:Ambulatory surgical centers in the United States are capturing same-day implantation volumes as miniaturized hardware compresses procedural footprints.
- Rehabilitation Centers:Spinal cord injury specialty facilities integrate bowel stimulators into comprehensive neurogenic dysfunction protocols.
Hospitals retain the deepest installed base; home care channels are climbing the fastest.
Application:
Clinical indication shapes evidence requirements and regulatory pathway complexity, with neurogenic applications demanding more extensive safety documentation than functional disorders.
- Neurogenic Bowel Dysfunction:Spinal cord injury and multiple sclerosis populations drive demand for closed-loop adaptive algorithms that respond to physiological feedback. Academic medical centers in the Netherlands and United States pilot these systems, with aging patient demographics expanding addressable volume.
- Chronic Constipation:The largest procedural category benefits from established reimbursement codes and broad physician familiarity with sacral nerve stimulation protocols, though competitive pressure from pharmaceutical alternatives constrains pricing.
- Fecal Incontinence:Overlapping neuromodulation indications with urinary dysfunction enable cross-selling to urogynecology practices.
- Colonic Motility Disorders:Refractory cases where pharmaceutical and behavioral interventions have failed, representing niche but high-acuity demand.
Chronic constipation commands the greatest procedure volume; neurogenic bowel dysfunction is gaining share fastest.
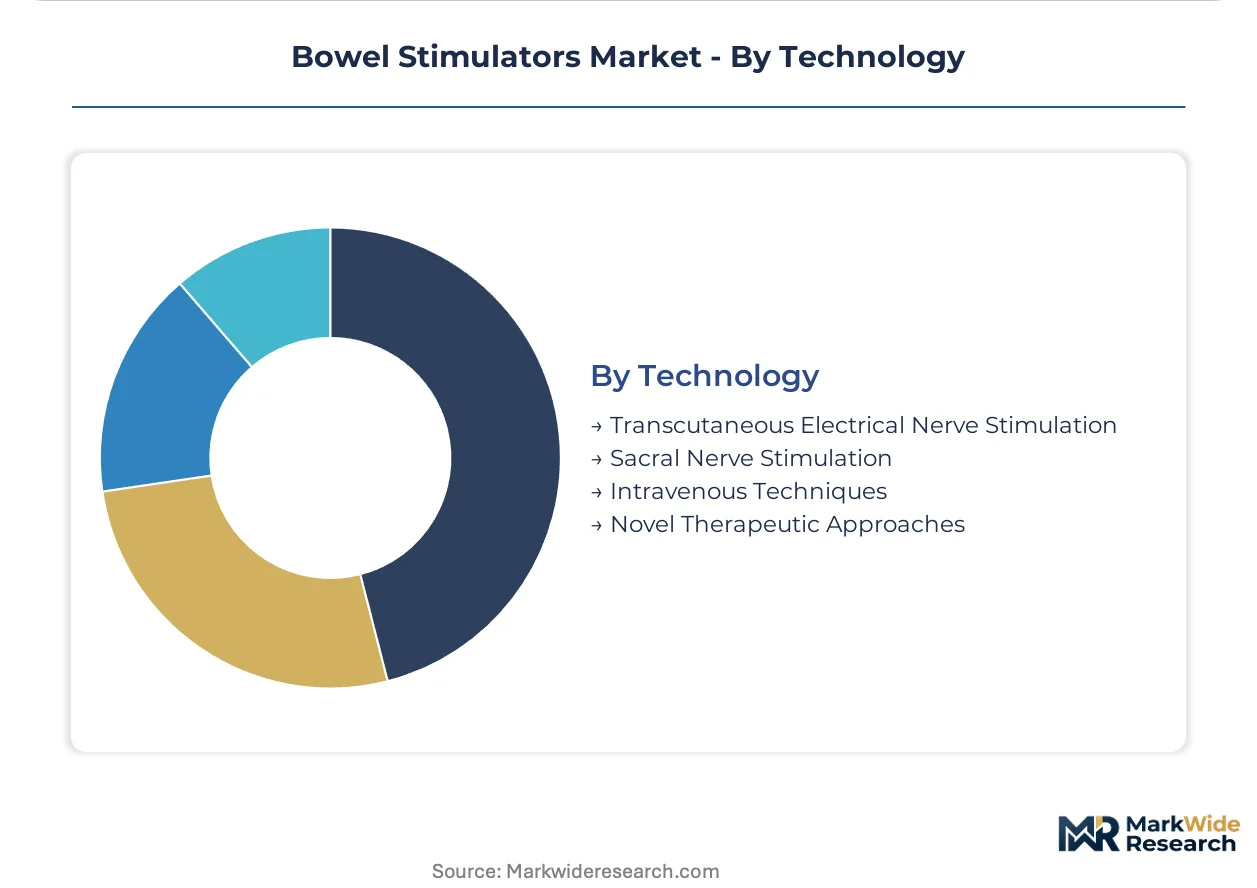
Technology:
Intellectual property concentration and regulatory novelty vary sharply across stimulation modalities, with sacral nerve platforms representing mature standards and closed-loop algorithms occupying unclaimed competitive space.
- Sacral Nerve Stimulation:Established implantable platforms with extensive clinical evidence bases and broad CMS coverage, though hardware miniaturization is compressing surgical footprints and accelerating same-day discharge protocols.
- Novel Therapeutic Approaches:Closed-loop adaptive systems integrating real-time physiological feedback represent white space distinct from open-loop paradigms, with FDA breakthrough device designation accelerating commercialization timelines.
- Transcutaneous Electrical Nerve Stimulation:Non-invasive surface delivery expanding access for contraindicated or price-sensitive populations.
- Intravenous Techniques:Pharmaceutical-neuromodulation hybrid approaches with limited current clinical traction.
Sacral nerve stimulation anchors current revenue; novel therapeutic approaches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American neuromodulation manufacturing, with its medical device corridor concentrating sacral nerve stimulation engineering talent and FDA premarket submission expertise.
United States
Academic medical centers in Boston and Houston pilot closed-loop adaptive algorithms for spinal cord injury populations. FDA breakthrough device designation accelerates commercialization timelines for novel neuromodulation platforms. The Twin Cities corridor concentrates implantable pulse generator manufacturing and remote programming infrastructure development.
Germany
Home care providers in Bavaria and North Rhine-Westphalia expand external device adoption as patients seek outpatient bowel management solutions. EMA notified bodies enforce stricter biocompatibility testing under MDR, extending regulatory timelines. The MedTech cluster around Tübingen advances miniaturized hardware for same-day discharge protocols.
Japan
Aging demographics and spinal cord injury rehabilitation demand drive PMDA regulatory alignment with international standards. METI coordinates electrical safety certification harmonization for foreign manufacturers. The Kansai region around Osaka concentrates neuromodulation hardware testing and electromagnetic compatibility facilities.
Netherlands
Academic medical centers in Utrecht and Rotterdam lead European pilot programs for real-time physiological feedback systems. EMA clinical evidence requirements mandate prospective bowel movement diary endpoints exceeding historical standards. The Eindhoven health technology corridor integrates digital therapeutic platforms with implantable device development.
France
Outpatient bowel management protocols in Île-de-France and Auvergne-Rhône-Alpes drive external system adoption outside institutional settings. ANSM enforces post-market surveillance requirements for implantable pulse generators. The Paris-Saclay medical technology cluster advances cloud-based therapy optimization platforms for remote patient monitoring.
Bowel Stimulators Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the neuromodulation value chain. The market consolidates around integrated device manufacturers with captive surgical training infrastructure and proprietary remote programming networks. Three archetypes dominate: diversified medtech conglomerates with neuromodulation divisions, pure-play sacral nerve stimulation specialists, and urogynecology-colorectal crossover platforms. Strategic moves concentrate on cloud-based service unbundling and rechargeable battery technology licensing.
Among diversified medtech conglomerates, Medtronic plc and Boston Scientific Corporation exemplify the integrated service-network archetype, anchoring competitive positioning through proprietary remote monitoring infrastructure. Axonics, Inc. occupies the rechargeable system specialist tier. Laborie Medical Technologies and B. Braun SE represent the urology-colorectal crossover fabricators with distributed European manufacturing footprints.
| Leading Market Players |
|---|
| Medtronic plc |
| Axonics, Inc. |
| Laborie Medical Technologies |
| B. Braun SE |
| Boston Scientific Corporation |
| Abbott Laboratories |
| LivaNova PLC |
| Nevro Corp. |
| Coloplast A/S |
| Others |
Value Chain & Pricing Dynamics
Closed-loop adaptive algorithm miniaturization simultaneously compresses implantable pulse generator production costs and concentrates manufacturing expertise in the Twin Cities corridor, creating asymmetric pricing power for integrated device manufacturers with captive rechargeable battery engineering capabilities.
Pricing Analysis
Outcome-based reimbursement anchoring through CMS national coverage determinations structures pricing around defecation frequency endpoints rather than hardware procurement alone. Three-tier pricing structure across premium implantable systems, standard external platforms, and economy transcutaneous devices differentiates by surgical invasiveness and battery longevity. Cost compression in external system tiers is intensifying because German home care providers negotiate disposable electrode contracts separately from hardware. Price-sensitive home care channels in France and Germany resist premium implantable pricing, while academic medical centers in Boston and Houston absorb higher capital commitments for adaptive algorithm access.
Supply Chain Analysis
Direct-to-hospital integrated delivery network channels handle complex implantable procurement, while distributor-mediated routes serve ambulatory surgical centers and home care providers. Manufacturing concentrates in the United States, Germany, and Japan, with lithium-ion cell supply drawing from concentrated South Korean and Japanese production. Implantable pulse generators rest on titanium biocompatibility certification, platinum-iridium electrode materials, and specialized hermetic sealing components. Single-source vulnerability in rechargeable battery cell supply creates procurement risk for extended-life neuromodulation platforms. Distribution runs through GPO contracts and direct manufacturer agreements with hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Medical Device Regulation enforcement is compressing weaker developers into US-only commercialization strategies, accelerating consolidation around manufacturers with European regulatory infrastructure and notified body relationships.
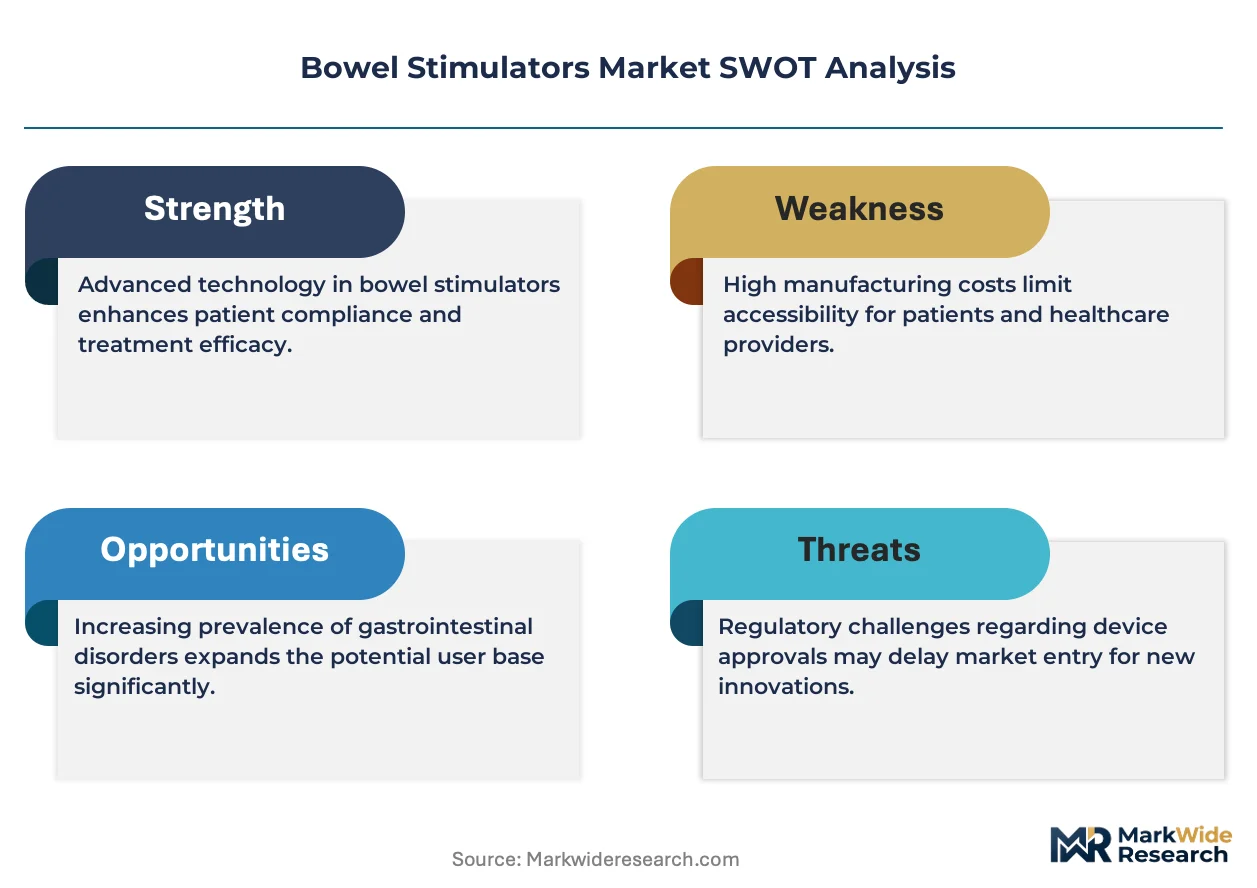
For Market Incumbents: To counter transcutaneous substitution pressure from external device manufacturers, deepen backward integration into rechargeable battery cell supply and expand proprietary remote programming network lock-in through CareLink-style cloud platforms. Anchor hospital system relationships by underwriting interdisciplinary surgical training fellowships that outpace current urogynecology-colorectal coordination pipeline capacity. For New Entrants and Emerging Players: Closed-loop adaptive algorithms integrating real-time physiological feedback offer technology-first entry into neurogenic bowel dysfunction applications where established sacral nerve stimulation protocols lack competitive response. Target spinal cord injury rehabilitation centers in Japan and the Netherlands as the most penetrable clinical settings. Pursue FDA breakthrough device designation to compress commercialization timelines relative to legacy 510(k) pathways. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medtech conglomerates seeking neuromodulation service-network expansion, with rechargeable system specialists and digital therapeutic platform developers commanding strategic premiums. Long-term viability hinges on recurring revenue capture through subscription-based remote programming rather than hardware replacement cycles. Watch CMS national coverage determination evolution for closed-loop adaptive algorithms as the critical reimbursement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway Pursuit | Accelerates commercialization timelines for novel closed-loop adaptive algorithms beyond standard 510(k) review. |
| Rechargeable Battery Technology Licensing | Reduces replacement frequency and anchors higher-margin service contracts for extended-life implantable systems. |
| Hospital System Partnership Development | Secures integrated delivery network procurement concentration through multi-year service bundle negotiations. |
| Software Companion Platform Integration | Enables cloud-based therapy optimization and remote patient monitoring beyond initial implant procedure. |
| Reimbursement Strategy Alignment | Positions adaptive algorithms for CMS national coverage determination expansion beyond chronic constipation codes. |
Study Parameters
Document review covered FDA premarket submission databases, EMA notified body guidance documents, and CMS national coverage determination records, complemented by interviews with implantable device engineers, hospital purchasing committee administrators, GPO contracts managers, and reimbursement strategy consultants. Secondary validation drew from hospital procurement databases, Medicare claims data, and neuromodulation society clinical registry publications. Bottom-up implant volume estimates and top-down market sizing triangulated across analysis approaches.
Segment-level outputs across product type, end user, application, and technology dimensions were generated through the projection horizon, with CAGRs derived from procedure volume trajectories and pricing evolution assumptions. Modeling incorporated rechargeable battery replacement cycle compression, remote programming subscription attach rates, and regulatory pathway timeline differentials as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced FDA guidance shifts, PMDA electrical safety standard revisions, and lithium-ion supply chain disruption events beyond baseline assumptions. Forecasts reflect documented assumptions about reimbursement stability and competitive response timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Endoscope Flushing Pumps Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Global Extremities Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Corneal Implants Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Bilirubin Meters Market