
 Global Strategic Consulting Services Market | 2026-2036
Global Strategic Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Strategic Consulting Services Market Foresight
Enterprise-grade strategic advisory is bifurcating the competitive landscape between premium boutique partnerships and technology-augmented scale players. McKinsey & Company leverages its proprietary knowledge management systems to sustain premium pricing for C-suite transformation mandates. Boston Consulting Group anchors its position through deep specialization in climate and energy transition advisory. Deloitte Consulting competes by integrating its consulting practice with audit and tax compliance capabilities across multiple jurisdictions.
Strategic consulting services encompass structured problem-solving engagements delivered to organizational leadership, combining primary research, quantitative modeling, and implementation planning to improve decision quality and execution outcomes. These engagements typically deploy cross-functional teams averaging four to twelve consultants per assignment, with project durations spanning eight weeks to twenty-four months depending on scope complexity. Management consulting and IT consulting represent the largest revenue pools within service type segmentation, though operations consulting demonstrates the fastest expansion as supply chain resilience becomes a board-level priority. Healthcare and technology verticals command premium engagement rates due to specialized regulatory knowledge requirements, while outcome-based pricing models are gaining traction as corporate procurement teams demand measurable return on consulting expenditure.
The Securities and Exchange Commission shapes disclosure requirements that drive demand for financial advisory and risk consulting across publicly traded clients. The European Union's Corporate Sustainability Reporting Directive mandates granular ESG data collection, expanding the addressable market for sustainability strategy practices. China's Ministry of Industry and Information Technology imposes data localization standards that require foreign-market entrants to retain domestic advisory support. Stakeholders must evaluate whether their service portfolios align with emerging AI governance frameworks before competitive positioning hardens around algorithmic transparency credentials.
Market Dynamics
Artificial intelligence integration into consulting workflows is compressing project delivery timelines and forcing incumbents to restructure talent deployment models or surrender margin to technology-augmented competitors.
Growth Catalysts
- Basel III capital requirements:Financial services firms in the United States and European Union are expanding advisory budgets to navigate complex compliance mandates, creating sustained demand for risk and regulatory consulting.
- Generative AI deployment:Large language models are automating research synthesis and quantitative modeling tasks, enabling consultancies to scale output without proportional headcount expansion.
- Supply chain resilience prioritization:Board-level mandates across manufacturing and healthcare verticals are accelerating operations consulting engagements focused on geographic diversification and inventory optimization.
Market Restraints
- Talent cost inflation:Specialized practitioners with dual expertise in sector knowledge and data science command compensation premiums that compress project margins, particularly in climate transition and healthcare advisory.
- Client insourcing:Fortune 500 companies are building internal strategy functions staffed by former consultants, reducing reliance on external advisory for recurring operational improvement work.
- Data localization requirements:China's MIIT and comparable frameworks in other jurisdictions fragment knowledge management systems, increasing compliance overhead for cross-border engagements.
Strategic Opportunities
- EU Corporate Sustainability Reporting Directive:Granular ESG data collection mandates are expanding the addressable market for sustainability strategy practices across European-listed enterprises.
- AI governance advisory:The EU AI Act and emerging algorithmic transparency frameworks in multiple jurisdictions create white space for consultancies to develop certification and risk assessment services.
- Outcome-based contracting:Corporate procurement teams in the United States are piloting engagement structures tying fees to measurable operational improvements, opening differentiation paths for analytically sophisticated players.
Industry Challenges
- Knowledge codification:Senior partners must translate tacit expertise into scalable digital assets without commoditizing the insights that sustain premium pricing.
- Legacy system integration:Advisory recommendations often face implementation friction where client IT infrastructure cannot support proposed analytics or automation architectures.
- Retention of specialized talent:Practitioners with climate science, biomedical, or semiconductor expertise rotate to industry roles, eroding practice depth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Strategic Consulting Services Market |
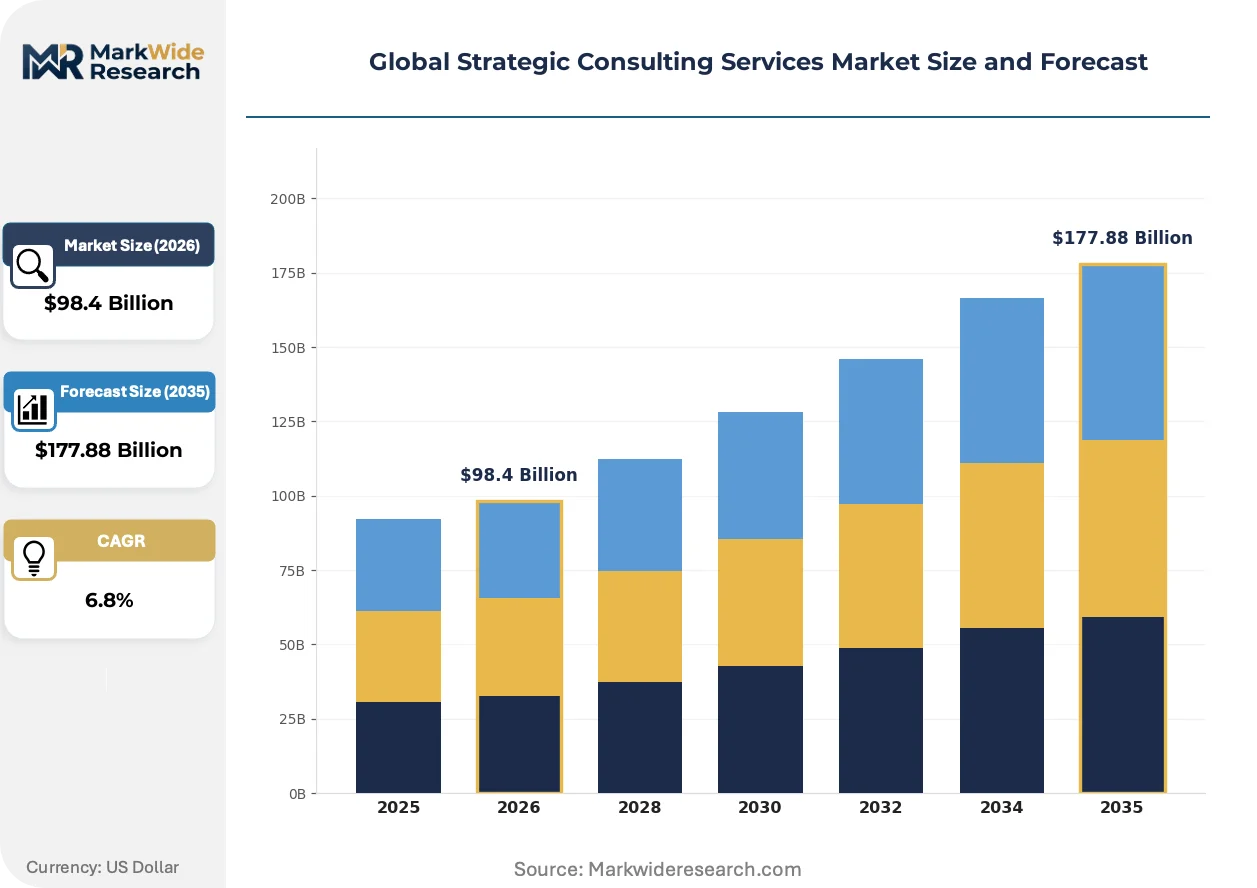
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $177.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Management Consulting, IT Consulting, Financial Advisory, Operations Consulting Industry Vertical: Healthcare, Technology, Energy, Manufacturing Client Type: Corporate Enterprises, Startups, Government Agencies, Non-Profits Engagement Model: Fixed Price, Time & Materials, Retainer, Outcome-Based |
| Companies Covered | McKinsey & Company, Boston Consulting Group, Bain & Company, Accenture, Deloitte Consulting, Ernst & Young Global Limited, PricewaterhouseCoopers Advisory Services, KPMG International Limited, Oliver Wyman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Strategic Consulting Services Market Shifts & Advancements
Workflow automation and regulatory complexity are reshaping how strategic advisory is delivered and consumed, with technology-augmented delivery models gaining ground against traditional time-based billing structures.
Generative AI is bifurcating the consulting value chain. Large language models handle document synthesis, pattern recognition in unstructured data, and initial scenario modeling. Tier-one firms deploy these tools to compress junior-staff hours on due diligence and market research, while mid-tier competitors use them to punch above weight class on analytical sophistication. The structural consequence is a widening gap between consultancies with proprietary training data and workflow integration versus those dependent on off-the-shelf platforms.
The EU AI Act establishes risk-tiered compliance obligations for algorithmic decision systems deployed in high-stakes domains including credit scoring, healthcare diagnostics, and employment screening. Industrial consequence includes mandatory conformity assessments and documentation burdens for advisory firms building AI-enabled tools for clients. Financial services and healthcare verticals across Germany, France, and the Netherlands are most affected, with early movers establishing dedicated AI risk practices to capture implementation advisory revenue.
Corporate procurement functions are unbundling strategy advisory from implementation support. Large enterprises in the United States now separate diagnostic and design phases from execution, awarding latter-stage contracts to specialized implementation firms or building captive capabilities. This pattern is most visible in technology and telecommunications verticals, where digital transformation roadmaps require sustained engineering capacity that pure-play consultancies cannot economically provide.
Global Strategic Consulting Services Market Segmentation
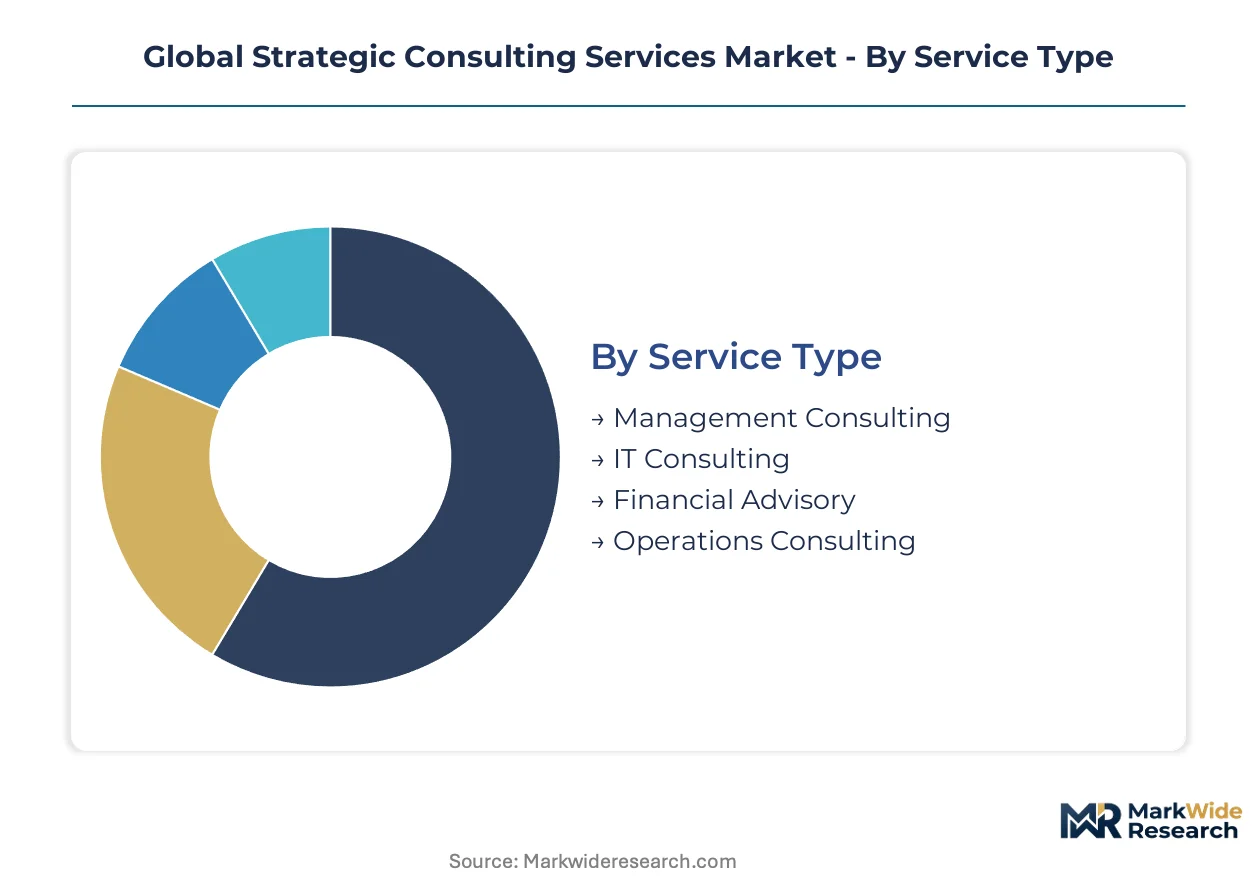
Strategic consulting services fragment across four distinct dimensions that shape competitive positioning and margin structures. Service type and industry vertical determine pricing power, while engagement model selection increasingly separates premium advisory from commoditized implementation work.
Service Type:
Management consulting engagements concentrate in domestic Fortune 500 headquarters, while IT consulting crosses borders through remote delivery infrastructure.
- Management Consulting:C-suite transformation mandates deploy cross-functional teams averaging eight consultants per assignment. Demand clusters in the United States as corporate headquarters prioritize organizational redesign and digital roadmaps.
- IT Consulting:Technology architecture advisory spans cloud migration, cybersecurity frameworks, and legacy system modernization. European banking regulators mandate specific infrastructure standards, expanding implementation advisory across Germany, France, and the Netherlands.
- Financial Advisory:Capital structure optimization and M&A due diligence for mid-market transactions.
- Operations Consulting:Supply chain resilience and geographic diversification planning for manufacturing clients.
Management consulting holds the largest share; momentum sits with operations consulting as board-level supply chain mandates accelerate.
Industry Vertical:
Healthcare and technology verticals command premium rates due to specialized regulatory knowledge, while energy and manufacturing segments compete on implementation scale.
- Healthcare:Advisory encompasses FDA pathway navigation, clinical trial design, and reimbursement strategy for pharmaceutical and medical device clients. The vertical demands dual expertise in biomedical science and regulatory compliance, tightening talent pools.
- Technology:Digital transformation roadmaps, platform economics, and AI governance frameworks dominate engagement scopes. China's MIIT data localization requirements force foreign entrants to retain domestic advisory support, fragmenting service delivery.
- Energy:Climate transition strategy and renewable project finance for utilities and oil majors.
- Manufacturing:Operational excellence and inventory optimization across automotive and industrial equipment.
Healthcare commands the highest fee rates; energy is climbing fastest on EU Green Deal implementation deadlines.
Client Type:
Corporate enterprises anchor revenue stability, while government procurement cycles introduce volatility that specialized practices must absorb.
- Corporate Enterprises:Multi-year transformation programs with dedicated partner relationships and proprietary knowledge management access. Procurement functions increasingly unbundle strategy from implementation, pressuring pure-play advisory margins.
- Startups:Venture-backed growth strategy and market entry advisory with equity-linked compensation structures. Engagement concentration tracks venture deployment cycles in the United States and United Kingdom.
- Government Agencies:Policy implementation and public sector efficiency mandates with extended procurement timelines.
- Non-Profits:Mission alignment and donor strategy advisory at discounted fee structures.
Corporate enterprises dominate absolute revenue; startups deliver the steepest expansion trajectory as venture deployment accelerates.
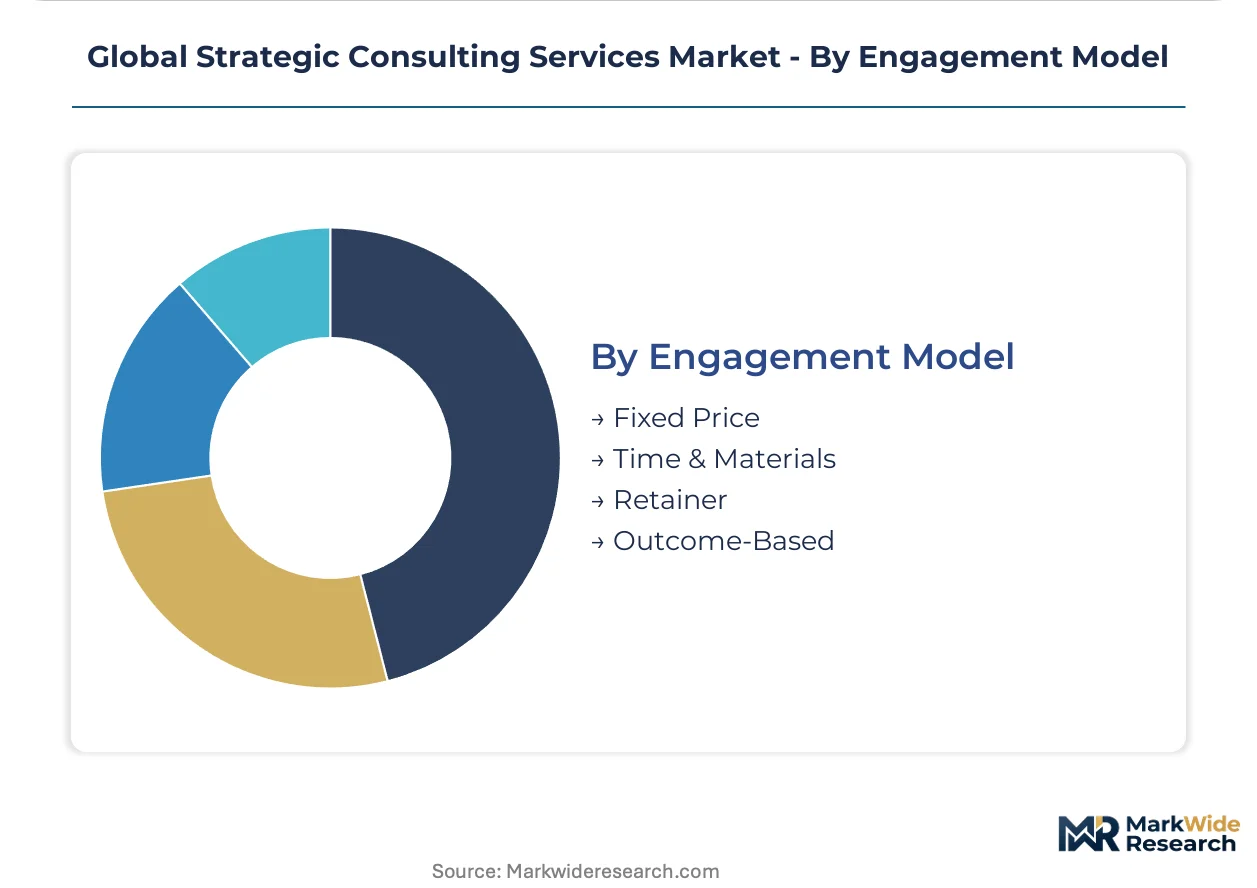
Engagement Model:
Pricing structure separates premium advisory from implementation work, with outcome-based models gaining traction in analytically mature client segments.
- Fixed Price:Scope-defined deliverables with risk transfer to the consultancy. Standard for diagnostic and design-phase work where boundaries are definable upfront.
- Time & Materials:Hourly billing with tiered rate cards by staff seniority. Dominant for open-ended advisory relationships and regulatory compliance support.
- Retainer:Annual advisory access with priority staffing guarantees. Preferred by financial services clients navigating continuous regulatory evolution.
- Outcome-Based:Fee linkage to measurable operational improvements or financial targets. Procurement pilots in the United States favor this structure for digital transformation and cost reduction mandates.
Time and materials retains the largest share; outcome-based contracting is gaining share fastest as corporate procurement demands accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based consultancies export transformation advisory to European headquarters clusters, while United Kingdom firms serve Commonwealth financial centers. Cross-border project delivery concentrates in English-speaking corridors and EU regulatory zones.
United States
Fortune 500 headquarters in New York and Chicago drive demand for C-suite organizational redesign and digital roadmaps. SEC disclosure requirements expand advisory budgets for financial services compliance. The Boston-to-Washington corridor anchors premium strategy practices serving technology and healthcare verticals.
Germany
Industrial Mittelstand firms seek operations consulting for supply chain geographic diversification. EU Green Deal implementation deadlines accelerate energy transition advisory across utilities and automotive suppliers. The Rhine-Ruhr and Stuttgart regions concentrate climate strategy practices.
United Kingdom
London's financial services cluster sustains demand for risk and regulatory consulting amid Basel III implementation. The Financial Conduct Authority shapes capital adequacy advisory mandates. Canary Wharf and the City of London house dense concentrations of M&A and restructuring specialists.
China
MIIT data localization requirements force foreign-market entrants to retain domestic advisory support. State-owned enterprises in Beijing and Shanghai procure transformation consulting for dual carbon goal alignment. The Yangtze River Delta fragments knowledge management systems for cross-border engagements.
France
EU AI Act risk-tiered compliance obligations drive implementation advisory for algorithmic decision systems. ANSM and CNIL frameworks shape healthcare and data governance consulting demand. Paris anchors sustainability strategy practices serving European-listed enterprises.
Global Strategic Consulting Services Market Competitive Landscape
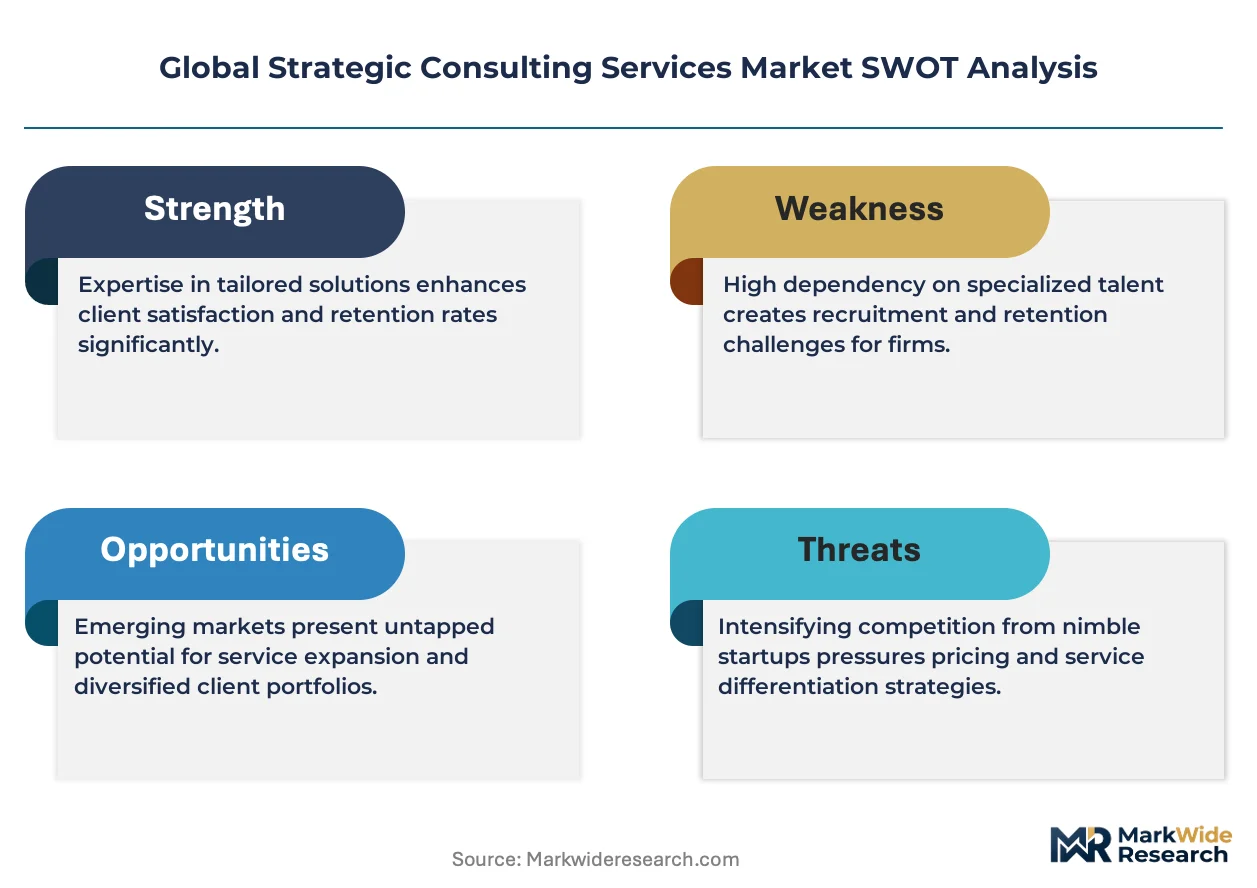
Listed leaders compete with private specialists across partnership structures and pricing models. The market structures around three tiers: premium boutiques commanding C-suite transformation mandates, technology-augmented scale players integrating AI workflows, and Big Four advisory networks bundling consulting with compliance capabilities. Strategic moves concentrate on proprietary knowledge codification and outcome-based contracting pilots.
Within the premium boutique tier, McKinsey & Company and Boston Consulting Group exemplify archetypes built on partner-led expertise and sector specialization. Among Big Four-integrated networks, Deloitte Consulting occupies a position combining audit relationships with advisory scale. These anchors represent competitive positioning around either tacit knowledge premiums or compliance-adjacent service bundling.
| Leading Market Players |
|---|
| McKinsey & Company |
| Boston Consulting Group |
| Bain & Company |
| Accenture |
| Deloitte Consulting |
| Ernst & Young Global Limited |
| PricewaterhouseCoopers Advisory Services |
| KPMG International Limited |
| Oliver Wyman |
| Others |
Supply & Pricing Matrix
Partner-level capacity utilization at tier-one consultancies creates scale economies that compress delivery costs while elevating price floors for boutique competitors. McKinsey and BCG leverage proprietary knowledge assets to sustain premium positioning against technology-augmented challengers from Accenture and Deloitte.
Pricing Analysis
Next-generation AI-augmented delivery models command fee premiums over traditional time-and-materials structures, while legacy project-based pricing faces compression from client procurement functions. Pricing stratifies across premium C-suite transformation mandates, standard implementation advisory, and economy-tier research support. Cost compression in the standard tier intensifies as generative AI tools automate junior-staff hours on due diligence and market research. Corporate enterprises exhibit the highest price sensitivity due to unbundling of strategy from implementation, while healthcare clients show least sensitivity given specialized regulatory knowledge requirements.
Supply Chain Analysis
Port congestion on trans-Pacific trade lanes elevates inbound logistics costs for consultancies deploying talent from United States headquarters to Asia-Pacific client sites. Knowledge production concentrates in the United States, United Kingdom, and Germany, with delivery infrastructure drawing from India and Poland for analytics support. Talent pipelines hinge on elite business school recruitment and lateral hiring from industry practitioners. Single-source vulnerability sits with partner-level expertise in climate transition and healthcare advisory. Distribution runs through direct partner relationships, with increasing channel diversification into alliance partnerships with technology vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The strategic consulting market is entering a cyclical recovery phase as deferred transformation budgets reactivate following Basel III implementation deadlines. Advisory spend typically lags regulatory enforcement by twelve to eighteen months, positioning the current window for demand inflection.
For Market Incumbents: Secure proprietary AI training data assets to differentiate algorithmic delivery capabilities from off-the-shelf platform competitors. Consolidate partner expertise in EU AI Act compliance advisory before certification requirements harden competitive positioning. Talent retention programs must address rotation risk to industry roles among climate science and biomedical specialists.
For New Entrants and Emerging Players: Certification fast-tracks for EU Corporate Sustainability Reporting Directive advisory create white-space entry paths without incumbent relationship encumbrance. Target mid-market manufacturing clients in Germany's Rhine-Ruhr corridor where supply chain resilience mandates outpace internal strategy capacity. Go-to-market positioning should emphasize outcome-based contracting pilots that align fees with measurable operational improvements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among consultancies with retainer-based financial services relationships and proprietary knowledge management subscriptions. Long-term viability favors boutiques with defensible sector specialization over generalist scale players facing margin compression. Watch for inflection signals in venture deployment cycles that drive startup advisory demand in the United States and United Kingdom.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary AI Knowledge Codification | Translates partner expertise into scalable digital assets that sustain premium pricing against technology-augmented competitors. |
| EU AI Act Compliance Practice Buildout | Captures implementation advisory revenue from German, French, and Dutch financial services and healthcare verticals. |
| Outcome-Based Contracting Pilots | Aligns fee structures with measurable operational improvements demanded by United States corporate procurement functions. |
| Climate Transition Specialization Deepening | Addresses talent scarcity in renewable project finance and carbon accounting advisory across EU Green Deal implementation. |
| Alliance Partnership Expansion | Extends delivery capacity for digital transformation roadmaps through technology vendor relationships beyond captive engineering. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with strategy partners, managing directors, corporate procurement officers, and technology implementation leads. Secondary validation drew from SEC disclosure filings, EU regulatory directive texts, management consulting firm partnership admissions data, and venture capital deployment databases. Bottom-up engagement value estimates triangulated against top-down market sizing from service type and vertical segmentation.
Across the analysis window, the forecasting framework modeled revenue trajectories by service type, industry vertical, client archetype, and engagement model dimensions. CAGRs were derived from historical growth rate analysis adjusted for regulatory mandate timing and technology adoption curves. Forecast inputs incorporated AI deployment penetration rates, Basel III compliance spend patterns, and supply chain resilience advisory demand indicators.
Decision-makers should treat outputs as directional under assumptions of continued regulatory enforcement and stable venture deployment cycles; material deviation would warrant model refresh. Specific risk factors include accelerated client insourcing of strategy functions and geopolitical fragmentation of cross-border knowledge management systems. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Healthcare Contract Sales Organizations Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Italy Operations Service Consulting Market
Healthcare Consulting
UK Healthcare Consulting Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market