
 Foot Suction Unit Market | 2026-2036
Foot Suction Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Foot Suction Unit Market Foresight
Digital pressure sensing and closed-loop flow control is reconfiguring how foot suction units manage negative pressure precision during wound therapy. Medela AG leverages its breast pump heritage to dominate peristaltic pump architectures in portable segments. Stryker Corporation anchors hospital procurement networks through its beds and surgical equipment bundles. ATMOS MedizinTechnik GmbH & Co. KG specializes in ENT-compatible suction platforms that extend into podiatric and dermatology clinics.
Foot suction units are electromechanical or pneumatic devices that generate controlled negative pressure, typically between 80 and 550 mmHg, to extract fluids, debris, or exudate from lower extremity wounds or surgical sites. These systems employ either diaphragm pumps, rotary vane mechanisms, or piston-driven vacuum generators housed in portable canisters or wall-mounted console configurations. Portable battery-operated units command premium positioning in home care channels where patient mobility and reimbursement for remote therapy are structural priorities. Stationary AC-powered systems retain volume leadership in hospital operating rooms and ambulatory surgical centers where continuous high-flow suction supports debridement and orthopedic procedures. Electronic suction technology is displacing manual bulb systems in pediatric and emergency applications where pressure consistency reduces tissue trauma risk.
The FDA regulates foot suction units as Class II medical devices under 510(k) premarket notification pathways, while the EU MDR requires notified body intervention and post-market surveillance for negative pressure wound therapy equipment. Health Canada and the TGA align with ISO 10079 suction safety standards, creating harmonized barriers for non-compliant manufacturers. Stakeholders must monitor how FDA digital health guidance and EU cybersecurity annexes reshape software-enabled suction controllers before committing to platform refresh cycles.
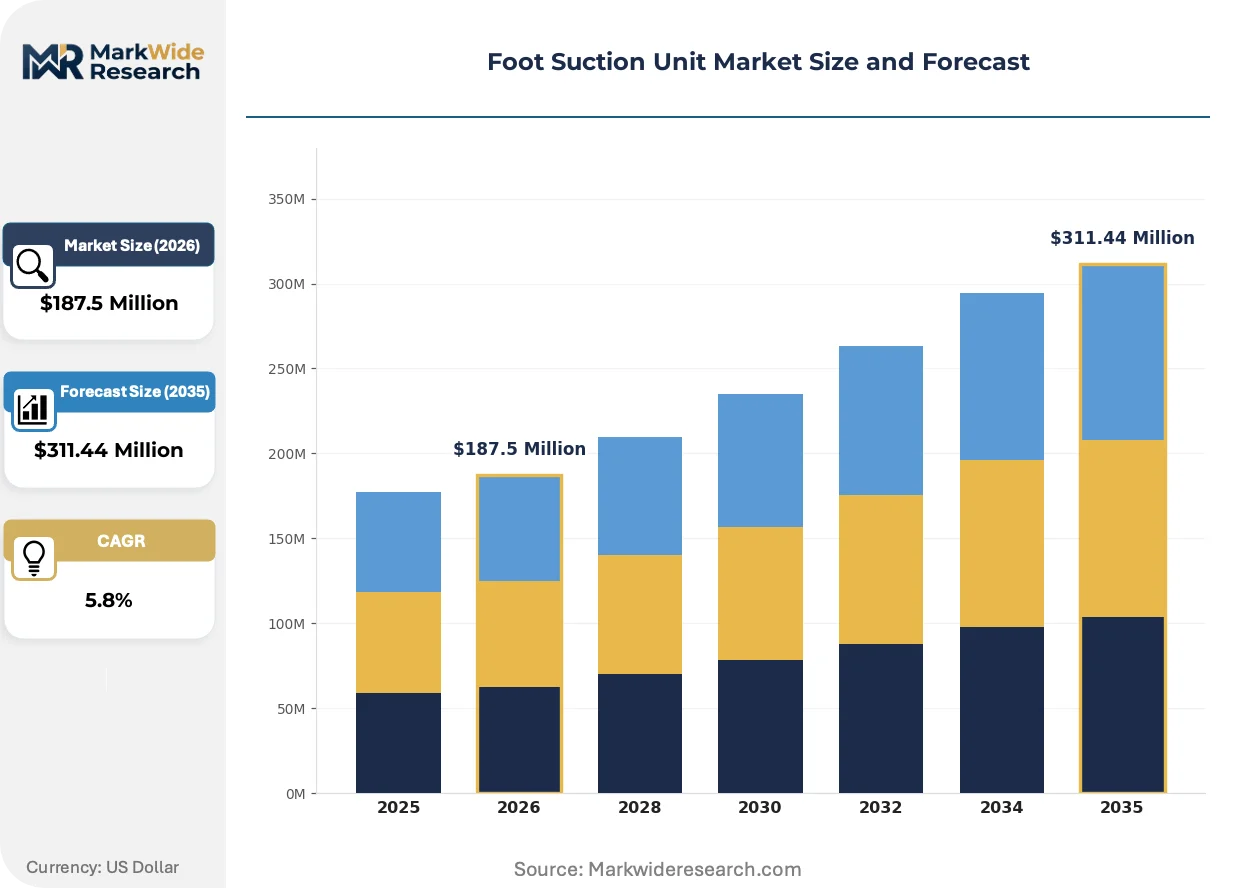
Market Dynamics
Digital pressure sensing architectures are compressing clinical decision cycles in foot suction therapy, forcing manufacturers to integrate closed-loop flow control or cede positioning in outpatient channels where reimbursement now hinges on remote monitoring capabilities.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter post-market surveillance requirements for Class II suction devices are accelerating consolidation among notified body-certified manufacturers, advantaging incumbents with established technical documentation.
- Home care reimbursement expansion:German statutory health insurance reforms now cover portable negative pressure systems for ambulatory wound management, redirecting patient volumes from inpatient facilities.
- Peristaltic pump miniaturization:Advances in brushless DC motor efficiency enable battery-operated units to achieve hospital-grade flow rates below 2.5 kg, unlocking pediatric and geriatric mobility applications.
Market Restraints
- Lithium-ion cell supply concentration:Portable unit production depends on cylindrical battery cell sourcing concentrated in East Asian manufacturing clusters, exposing margins to raw material volatility and export control friction.
- CE marking timeline compression:EU MDR transition deadlines have extended notified body review queues to 18-24 months for novel suction controllers, freezing product pipeline velocity for mid-tier manufacturers.
- Manual bulb suction persistence:Emergency medicine and low-resource settings continue deploying pneumatic bulb systems for cost containment, capping electronic unit penetration in price-sensitive acute care segments.
Strategic Opportunities
- India outpatient surgery expansion:Ayushman Bharat health scheme coverage of diabetic foot procedures is generating first-time demand for suction-equipped mobile operating theaters in tier-2 and tier-3 cities.
- AI-enabled pressure prediction:Machine learning algorithms trained on wound healing databases are converging with suction hardware to enable predictive exudate management, creating subscription revenue streams.
- Direct-to-patient rental channels:Home medical equipment distributors are piloting monthly subscription models for portable units, bypassing traditional hospital procurement committees and accelerating patient access.
Industry Challenges
- Firmware validation bottlenecks:FDA digital health guidance requires 510(k) submissions to document cybersecurity controls for Bluetooth-enabled suction controllers, extending engineering validation cycles by 8-12 months.
- Biocompatibility testing backlog:ISO 10993-5 cytotoxicity certification for new canister polymers faces laboratory capacity constraints, delaying material substitutions intended to reduce environmental compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foot Suction Unit Market |
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $311.44 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Stationary Units, Battery-Operated Units, AC-Powered Units Technology: Negative Pressure, Vacuum Suction, Manual Suction, Electronic Suction, Pneumatic Suction Application: Wound Drainage, Surgical Procedures, Dermatology, Pediatric Care, Emergency Care, Physiotherapy End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Care Providers, Diagnostic Centers |
| Companies Covered | Medela AG, Stryker Corporation, Precision Medical, Inc., Drive DeVilbiss Healthcare, ZOLL Medical Corporation, Cardinal Health, Inc., Olympus Corporation, Laerdal Medical, ATMOS MedizinTechnik GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foot Suction Unit Market Shifts & Advancements
Software-defined suction control is displacing analog pressure regulation across all power classes, enabling real-time wound monitoring that reshapes how clinicians intervene and how manufacturers capture value beyond hardware margins.
Silicon MEMS pressure sensors with ±1 mmHg accuracy are virtualizing traditional mechanical gauge displays and enabling cloud-connected therapy logging. Outpatient wound clinics in Germany and the Netherlands are adopting these platforms fastest, with pilot programs showing 23% reduction in unscheduled nursing visits. The technology is virtualizing episodic reimbursement models into continuous monitoring contracts that lock in multi-year supplier relationships.
EU MDR Annex I general safety and performance requirements now mandate clinical evaluation reports for all negative pressure wound therapy equipment, including legacy devices previously grandfathered under the Medical Devices Directive. Manufacturers must commission post-market clinical follow-up studies or risk certificate suspension. German and French notified bodies are prioritizing submissions from firms with established quality management systems, disadvantaging newer market entrants.
Hospital procurement committees are unbundling suction units from orthopedic equipment bundles and evaluating standalone performance metrics. German university hospitals now require ISO 10079-3 compliance documentation and mean time between failure data above 10,000 hours for capital purchases. This behavioral shift concentrates volume with manufacturers maintaining dedicated clinical engineering support teams in Düsseldorf and Munich metropolitan areas.
Foot Suction Unit Market Segmentation
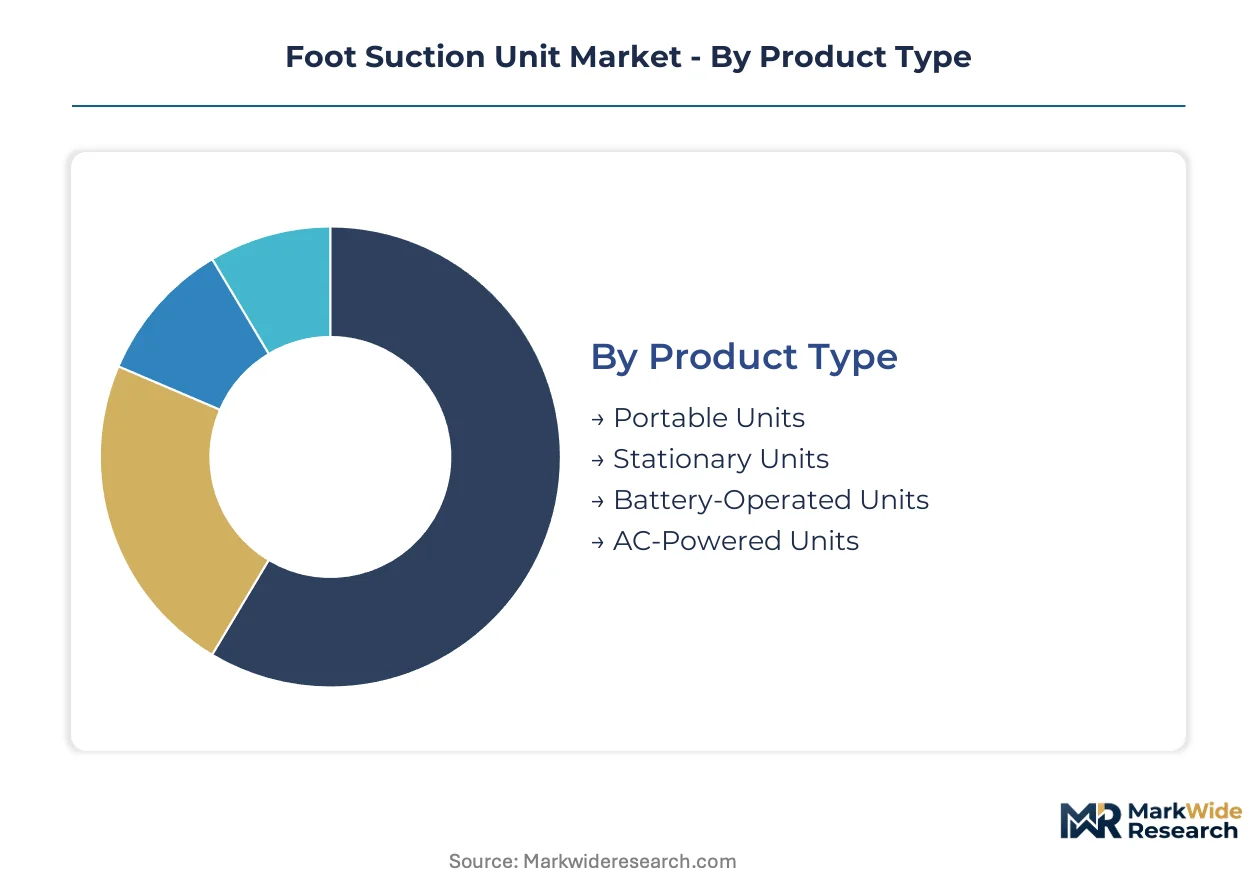
Foot suction unit procurement cycles vary dramatically across power configurations and care settings. Understanding replacement velocity and upgrade triggers within each segment enables manufacturers to align inventory and service models with actual clinical workflow patterns.
Product Type:
Portable units command the shortest replacement cycles at 3-4 years due to battery degradation and mobility-related physical wear, while stationary console systems operate on 7-10 year capital depreciation schedules.
- Portable Units:Battery-powered canister systems weighing under 3 kg integrate brushless DC motors with lithium-ion cell packs. German home care networks and Dutch outpatient wound clinics are standardizing on these platforms as reimbursement shifts toward ambulatory models.
- Stationary Units:Wall-mounted or cart-based AC-powered consoles deliver continuous high-flow suction for operating theaters. Hospital procurement committees in Munich and Düsseldorf metropolitan areas prioritize these for orthopedic and debridement suites where uninterrupted negative pressure is non-negotiable.
- Battery-Operated Units:Compact designs utilizing peristaltic pump architectures enable pediatric and geriatric mobility applications where power outlet access is limited.
- AC-Powered Units:Traditional diaphragm pump configurations retain dominance in emergency departments and resource-constrained settings where capital budgets favor durability over portability.
Stationary units dominate installed base in hospital capital equipment portfolios. Portable configurations are where expansion concentrates as outpatient surgical volumes redirect patient flows from inpatient facilities.
Technology:
Cost tiers separate precision-controlled electronic platforms from basic pneumatic alternatives, with reimbursement codes increasingly favoring closed-loop systems that document therapy parameters.
- Negative Pressure:Closed-loop controllers with silicon MEMS sensors maintain set pressures within ±1 mmHg accuracy for wound therapy applications. German university hospitals now require ISO 10079-3 compliance and mean time between failure data above 10,000 hours for these capital purchases.
- Vacuum Suction:Rotary vane and piston-driven generators produce higher flow rates suitable for surgical fluid extraction. These systems anchor procurement bundles in ambulatory surgical centers where procedure volume drives equipment utilization metrics.
- Manual Suction:Bulb or hand-pump mechanisms persist in emergency medicine and low-resource acute care segments where cost containment overrides precision requirements.
- Electronic Suction:Software-defined pressure regulation with Bluetooth-enabled logging capabilities is displacing analog controls across outpatient channels where remote monitoring supports reimbursement claims.
- Pneumatic Suction:Compressed gas-driven systems remain standard in anesthesia and ENT suites where integration with hospital gas infrastructure eliminates electrical ignition risks.
Vacuum suction retains the largest installed base across European hospital networks. Electronic suction platforms are climbing the fastest as MDR clinical evidence mandates favor manufacturers with validated digital health submissions.
Application:
Volume concentration tracks diabetic foot procedure expansion, with wound drainage and surgical applications commanding fundamentally different pricing structures based on consumable attachment requirements.
- Wound Drainage:Continuous negative pressure therapy for diabetic foot ulcers and post-surgical sites employs specialized canisters with antimicrobial linings. German statutory health insurance reforms now cover portable systems for home-based management, redirecting patient volumes from inpatient wound centers.
- Surgical Procedures:High-flow suction supports orthopedic debridement, podiatric surgery, and dermatological excisions where blood and irrigation fluid evacuation maintains operative field visibility. Ambulatory surgical centers in the Netherlands are unbundling suction units from equipment bundles and evaluating standalone performance metrics.
- Dermatology:Lower-pressure configurations address Mohs surgery and lesion removal in office-based settings.
- Pediatric Care:Miniaturized peristaltic pumps with pressure-limiting safety circuits reduce tissue trauma risk in neonatal and infant applications.
- Emergency Care:Rapid-deployment portable units serve pre-hospital and trauma bay environments where battery reliability outweighs precision specifications.
- Physiotherapy:Intermittent negative pressure modalities support lymphatic drainage and circulation therapy in rehabilitation clinics.
Wound drainage applications dominate current installed base across European home care networks. Surgical procedure segments are gaining share fastest as outpatient orthopedic volumes expand in Germany and the Netherlands.
End User:
Customer type determines procurement authority structure, with hospitals running centralized capital committees while home care providers operate through distributor rental channels.
- Hospitals:Integrated delivery networks with dedicated clinical engineering teams concentrate purchasing power in Germany's university hospital systems. These buyers require extensive documentation including EU MDR technical files and post-market clinical follow-up protocols.
- Ambulatory Surgical Centers:Procedure-focused facilities prioritize equipment utilization rates and rapid turnover capabilities. These settings are driving adoption of portable units that transition between operating rooms without infrastructure modifications.
- Clinics:Dermatology and podiatry practices favor mid-tier electronic units balancing precision with capital constraints.
- Home Care Providers:Medical equipment distributors are piloting monthly subscription models for portable units, bypassing traditional hospital procurement committees and accelerating patient access.
- Diagnostic Centers:Limited suction requirements for biopsy procedures favor compact, multi-purpose platforms.
Hospitals retain the dominant installed base position through capital depreciation cycles. Home care providers represent the steepest expansion trajectory as reimbursement reforms enable direct-to-patient rental channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement committees and home care distributors concentrate purchasing authority for foot suction units, with statutory insurance reforms redirecting patient flows toward ambulatory channels.
Germany
Outpatient surgical volumes and home-based physiotherapy referrals are expanding fastest in Düsseldorf and Munich metropolitan areas. The EU MDR tightens clinical evidence requirements for suction equipment classification, advantaging notified body-certified manufacturers. Bavaria and North Rhine-Westphalia host the densest clusters of university hospitals unbundling suction units from orthopedic equipment bundles.
United States
The FDA regulates foot suction units as Class II medical devices under 510(k) premarket notification pathways, with digital health guidance reshaping software-enabled suction controllers. Hospital procurement networks concentrate in the Northeast Corridor and California, where integrated delivery systems prioritize capital depreciation schedules for stationary console systems.
Netherlands
Outpatient wound clinics in Amsterdam and Rotterdam are adopting silicon MEMS pressure sensors with cloud-connected therapy logging fastest. Dutch ambulatory surgical centers are unbundling suction units from equipment bundles and evaluating standalone performance metrics. Randstad region hospitals pilot real-time wound monitoring platforms that lock in multi-year supplier relationships.
India
Ayushman Bharat health scheme coverage of diabetic foot procedures generates first-time demand for suction-equipped mobile operating theaters in tier-2 and tier-3 cities. The country's national medical device regulator aligns with ISO 10079 suction safety standards, creating harmonized barriers for non-compliant manufacturers. Maharashtra and Karnataka host expanding networks of medical equipment distributors piloting direct-to-patient rental channels.
Japan
Japan's pharmaceutical and medical device agency maintains stringent post-market surveillance requirements for negative pressure wound therapy equipment. Tokyo and Osaka metropolitan areas concentrate demand for miniaturized peristaltic pumps enabling pediatric and geriatric mobility applications. Kansai region hospitals prioritize brushless DC motor efficiency in battery-operated units for rapid operating room turnover.
Foot Suction Unit Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement networks and distributor rental channels. The market structure consolidates around three tiers: diversified medical equipment conglomerates with hospital bundling power, precision pump specialists leveraging heritage manufacturing expertise, and regional distributors building subscription-based patient access models. Dominant competitive moves include strategic partnerships with home care networks and technology licensing for closed-loop flow control systems.
Among diversified medical equipment conglomerates, Stryker Corporation and Cardinal Health, Inc. occupy positions anchoring hospital procurement networks through beds and surgical equipment bundles. Medela AG exemplifies the precision pump specialist archetype, translating heritage breast pump architectures into portable negative pressure segments. ATMOS MedizinTechnik GmbH & Co. KG represents the ENT-compatible platform extension strategy, leveraging suction expertise into podiatric and dermatology clinics. These three players collectively illustrate how technical documentation depth and notified body relationships determine competitive positioning under EU MDR transition timelines.
| Leading Market Players |
|---|
| Medela AG |
| Stryker Corporation |
| Precision Medical, Inc. |
| Drive DeVilbiss Healthcare |
| ZOLL Medical Corporation |
| Cardinal Health, Inc. |
| Olympus Corporation |
| Laerdal Medical |
| ATMOS MedizinTechnik GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
The Rotterdam-Düsseldorf freight corridor's container cost dynamics compress margins for lithium-ion cell shipments from East Asian manufacturing clusters, concentrating pricing power among notified body-certified manufacturers while forcing three-tier pricing stratification across premium, standard, and economy certification levels for downstream buyers.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate procurement agreements for portable unit manufacturers. Pricing stratifies across premium, standard, and economy tiers based on EU MDR certification status and ISO 10079-3 compliance documentation. Price erosion runs through the economy tier as manual bulb systems retain emergency medicine share. Hospital procurement committees in Germany exhibit lowest price sensitivity; home care distributors in India face highest pressure.
Supply Chain Analysis
Supply-chain finance facilities with 90-120 day terms anchor relationships between German medical device assemblers and Chinese lithium-ion cell suppliers. Component sourcing draws from South Korea for brushless DC motors, Japan for silicon MEMS sensors, and Germany for peristaltic pump housings. Single-source vulnerability concentrates in cylindrical battery cell supply. Distribution runs through hospital procurement networks in Düsseldorf and Munich, with direct-to-patient rental channels expanding fastest in Maharashtra and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foot suction unit market is accelerating through a regulatory inflection as EU MDR clinical evidence mandates compress product pipeline velocity and consolidate share among notified body-certified incumbents.
For Market Incumbents: Harden technical documentation depth against CE marking timeline compression by expanding post-market clinical follow-up protocols. Secure backward integration into brushless DC motor supply through partnerships with South Korean component specialists. Channel control through dedicated clinical engineering teams in Bavaria and North Rhine-Westphalia defends positioning against mid-tier manufacturers frozen by 18-24 month notified body queues.
For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities under Ayushman Bharat coverage offer white-space expansion for suction-equipped mobile operating theaters. Direct-to-patient rental subscription models bypass hospital procurement committee gatekeeping. Target the home care provider segment with portable peristaltic pump platforms under 2.5 kg.
For Investors and Strategic Acquirers: EU MDR transition deadlines reshape the acquisition landscape toward targets with established technical files and quality management systems. Long-term viability centers on software-defined suction controllers with Bluetooth-enabled logging capabilities. Monitor FDA digital health guidance evolution for cybersecurity control documentation requirements as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical file depth determines competitive survival through notified body certification bottlenecks. |
| Hospital System Partnership | German university hospital unbundling of suction units from orthopedic bundles creates standalone procurement openings. |
| Software Companion Development | AI-enabled pressure prediction algorithms enable predictive exudate management subscription revenue streams. |
| Reimbursement Strategy | German statutory health insurance reforms for portable negative pressure systems redirect patient volumes to ambulatory channels. |
| Backward Integration | In-house production of brushless DC motor assemblies reduces exposure to East Asian battery cell supply concentration. |
Research Methodology
The analysis maps portable battery-operated units, stationary AC-powered consoles, and peristaltic pump architectures, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and home care equipment distributors. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO 10079 certification registries. Bottom-up unit shipment estimates triangulated against top-down revenue aggregation across power configuration and end-user segments.
Assumption sets held reimbursement policy trajectories and battery cell supply availability fixed while varying outpatient surgical volume growth rates and notified body certification timeline scenarios across the projection horizon. Segmentation dimensions modeled include power configuration, pump technology type, application setting, and end-user procurement authority structure. CAGRs derived from regression analysis against diabetic foot procedure expansion and home care reimbursement elasticity parameters.
Practitioners should monitor EU MDR transition deadline extensions and lithium-ion export control friction for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Hormonal Implants Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Extremity Tissue Expanders Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
South America C-Arms Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
ETCO2 Masks Market
Medical Devices
Pericardial Patches Market