
 Adjustable Speed Vortex Mixer Market | 2026-2036
Adjustable Speed Vortex Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Adjustable Speed Vortex Mixer Market Insights
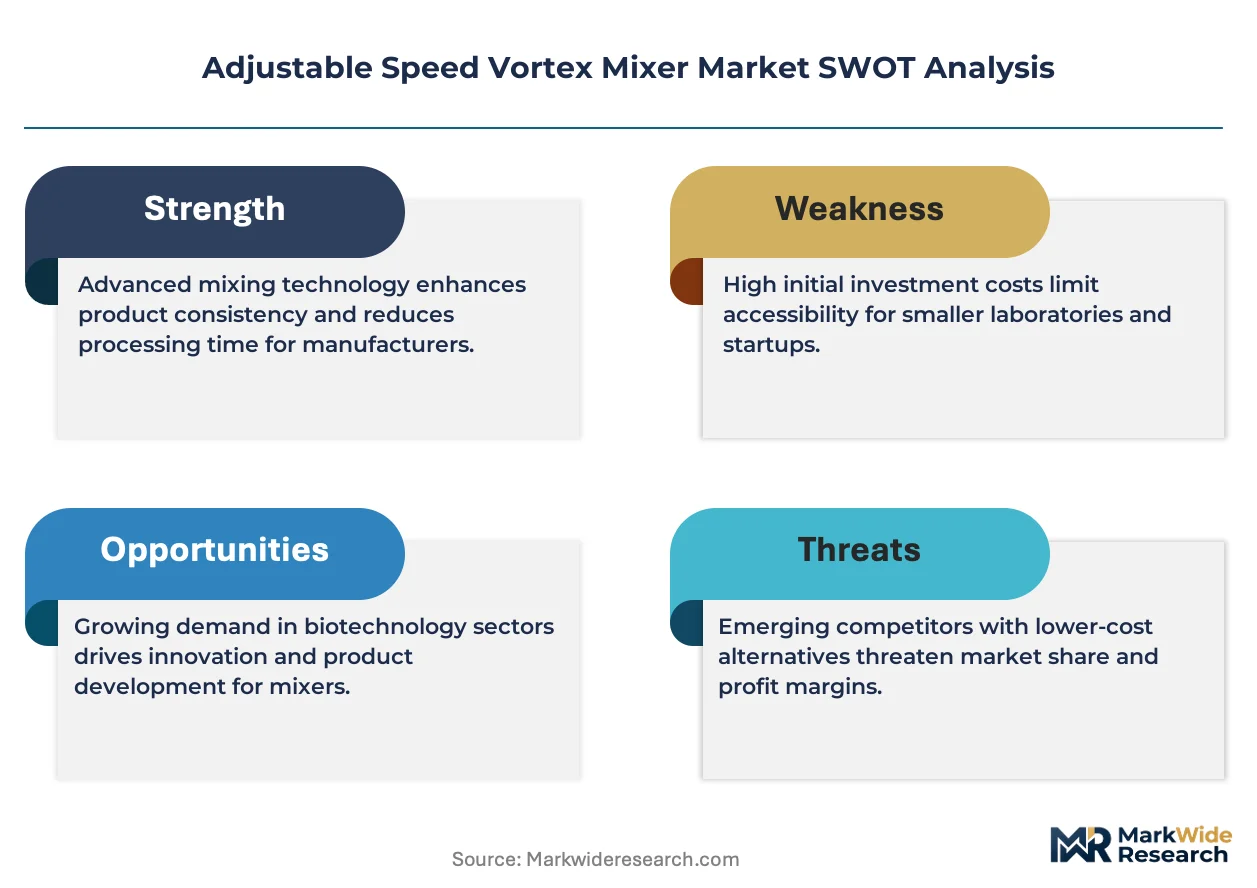
Benchtop-grade precision calibration is bifurcating the competitive landscape into specification-differentiated tiers. Thermo Fisher Scientific leverages its integrated life sciences platform to bundle vortex mixers with broader workflow solutions. Eppendorf anchors its position through deep specialization in liquid-handling-adjacent sample preparation equipment. IKA competes on German-engineered reliability standards that sustain premium positioning across European academic procurement channels.
An adjustable speed vortex mixer employs orbital shaking at variable rotational frequencies, typically spanning 200 to 3,000 rpm, to suspend, homogenize, or disrupt liquid samples in microtube, plate, or flask formats. Brushless motor technology now dominates mid-to-premium product tiers due to reduced heat generation and extended duty-cycle tolerance for continuous pharmaceutical screening operations. Tabletop mixer configurations command the largest installed base in academic settings, while portable mixer demand accelerates fastest among decentralized clinical diagnostics networks. Laboratory mixer sales concentrate margin pools in heavy-duty mixer variants engineered for high-throughput cell disruption protocols.
The FDA enforces quality system regulation for laboratory equipment used in diagnostic applications, compelling manufacturers to maintain design control documentation and risk management files. ISO 13485 certification shapes competitive access for mixers deployed in pharmaceutical quality-control environments, while CE marking under the EU MDR framework governs European commercialization pathways. Stakeholders must monitor evolving electrification efficiency standards from the DOE and comparable bodies, as motor technology selections carry growing compliance implications for cross-border instrument shipments.
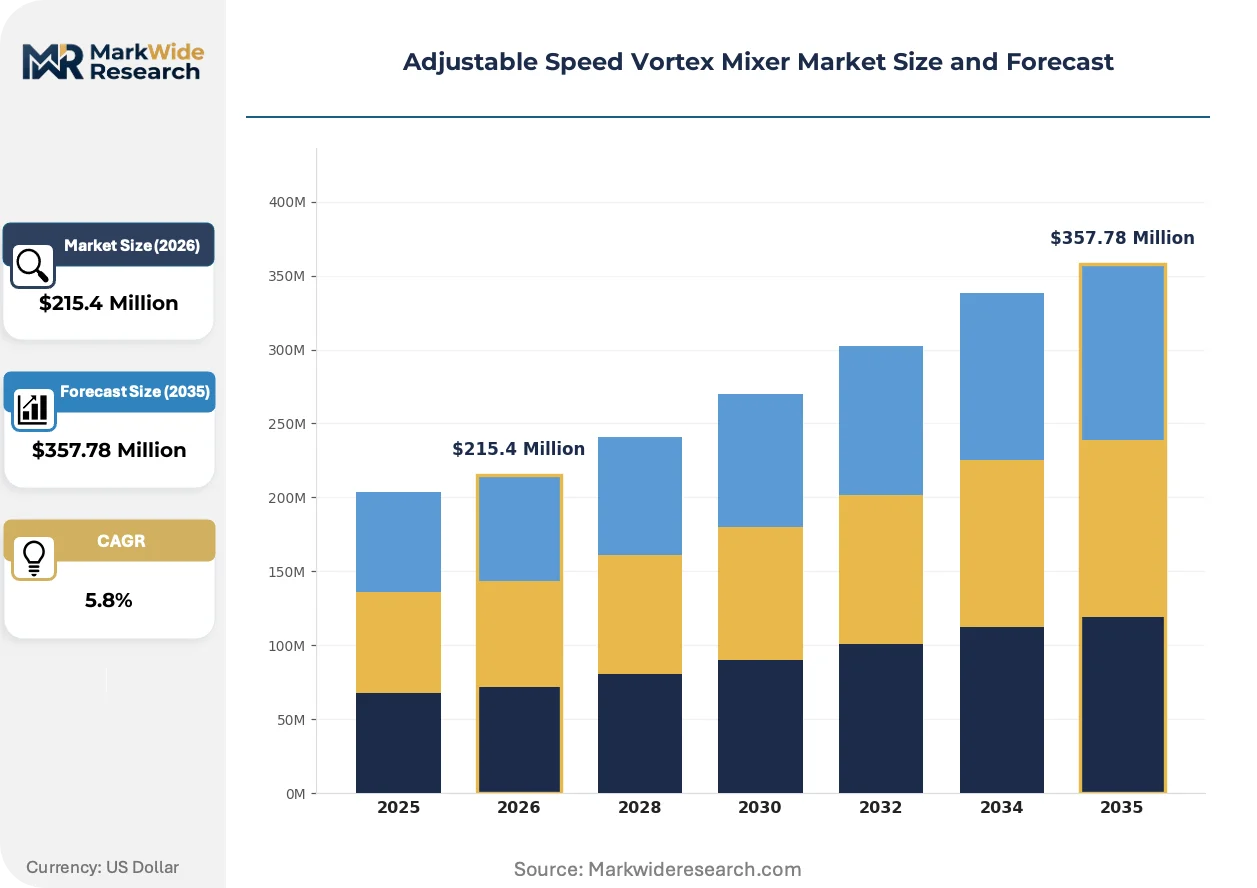
Market Dynamics
Brushless motor architecture is compressing replacement cycles while FDA quality system documentation requirements are elevating compliance costs for market entry, creating a bifurcation between specification-differentiated tiers and commodity-grade alternatives.
Growth Catalysts
- High-throughput genomics workflows:Academic institutions in the United States are expanding procurement of brushless motor units to support continuous sample processing demands in CRISPR screening and next-generation sequencing protocols.
- EU MDR framework:CE marking under the EU MDR is accelerating equipment refresh cycles as laboratories replace legacy mixers lacking updated technical documentation and risk management files.
- Pharmaceutical quality-control environments:ISO 13485 certification requirements are creating specification premiums for mixers deployed in sterile fill-finish and stability testing operations.
Market Restraints
- Neodymium magnet supply concentration:Rare earth magnet sourcing dependence on Chinese processing infrastructure creates input cost volatility and geopolitical exposure for brushless motor manufacturers.
- Calibration documentation burden:FDA design control requirements impose fixed compliance costs that disproportionately burden low-volume producers and regional specialists.
- Magnetic bead homogenizers:Bead-based disruption systems are capturing share in cell lysis applications where vortex mixing previously dominated sample preparation workflows.
Strategic Opportunities
- Decentralized clinical diagnostics networks:Portable mixer demand is accelerating among point-of-care testing facilities in India and Southeast Asia where cold-chain logistics and field deployment require battery-operated units.
- DOE electrification efficiency standards:Evolving motor efficiency mandates are creating first-mover advantages for manufacturers with optimized brushless designs and regenerative power architectures.
- Digital torque sensing integration:Convergence of precision motor control with IoT-enabled condition monitoring is enabling predictive maintenance contracts and usage-based service models.
Industry Challenges
- Metrology technician scarcity:Precision calibration and orbital frequency verification require specialized skills that contract in regional markets lacking accredited laboratory infrastructure.
- Legacy LIMS integration friction:New mixer installations face protocol adaptation costs when interfacing with established laboratory information management systems in pharmaceutical quality-control settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adjustable Speed Vortex Mixer Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $357.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Mixer, Laboratory Mixer, Portable Mixer, Heavy-Duty Mixer Technology: Magnetic Drive, Direct Drive, Brushless Motor, Piezoelectric Drive End User: Academic Institutions, Research Laboratories, Pharmaceutical Companies, Clinical Labs Application: Sample Preparation, Homogenization, Cell Disruption, Chemical Mixing |
| Companies Covered | Thermo Fisher Scientific, Eppendorf, IKA, Scientific Industries, VWR International, Heidolph Instruments, Benchmark Scientific, Bio-Rad Laboratories, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adjustable Speed Vortex Mixer Market Trends and Innovations
Orbital shaking platforms are incorporating sensor fusion and adaptive control algorithms that transform static equipment into data-generating nodes within connected laboratory ecosystems.
Direct-drive brushless motors with integrated Hall-effect position sensing are displacing belt-driven brushed architectures in mid-to-premium product tiers. Pharmaceutical contract research organizations are specifying these units for 24-hour continuous screening operations. The technology is displacing legacy motor suppliers from specification-intensive procurement channels where duty-cycle tolerance determines vendor qualification.
REACH restrictions on perfluorinated compounds are forcing gasket and seal material substitutions in mixer housings exposed to aggressive solvents. European manufacturers are accelerating fluoropolymer-free validation programs to maintain market access. The F-Gas Regulation is additionally shaping refrigerant choices in cooled mixer variants used for temperature-sensitive enzymatic reactions.
Academic procurement offices are consolidating vendor relationships through framework agreements that bundle vortex mixers with centrifuge and pipetting platforms. Distributor margins compress as manufacturers establish direct institutional sales channels. Germany exhibits the most advanced concentration, where IKA and Eppendorf anchor dense clusters of precision instrument engineering that bypass traditional laboratory supply intermediaries.
Adjustable Speed Vortex Mixer Market Segmentation
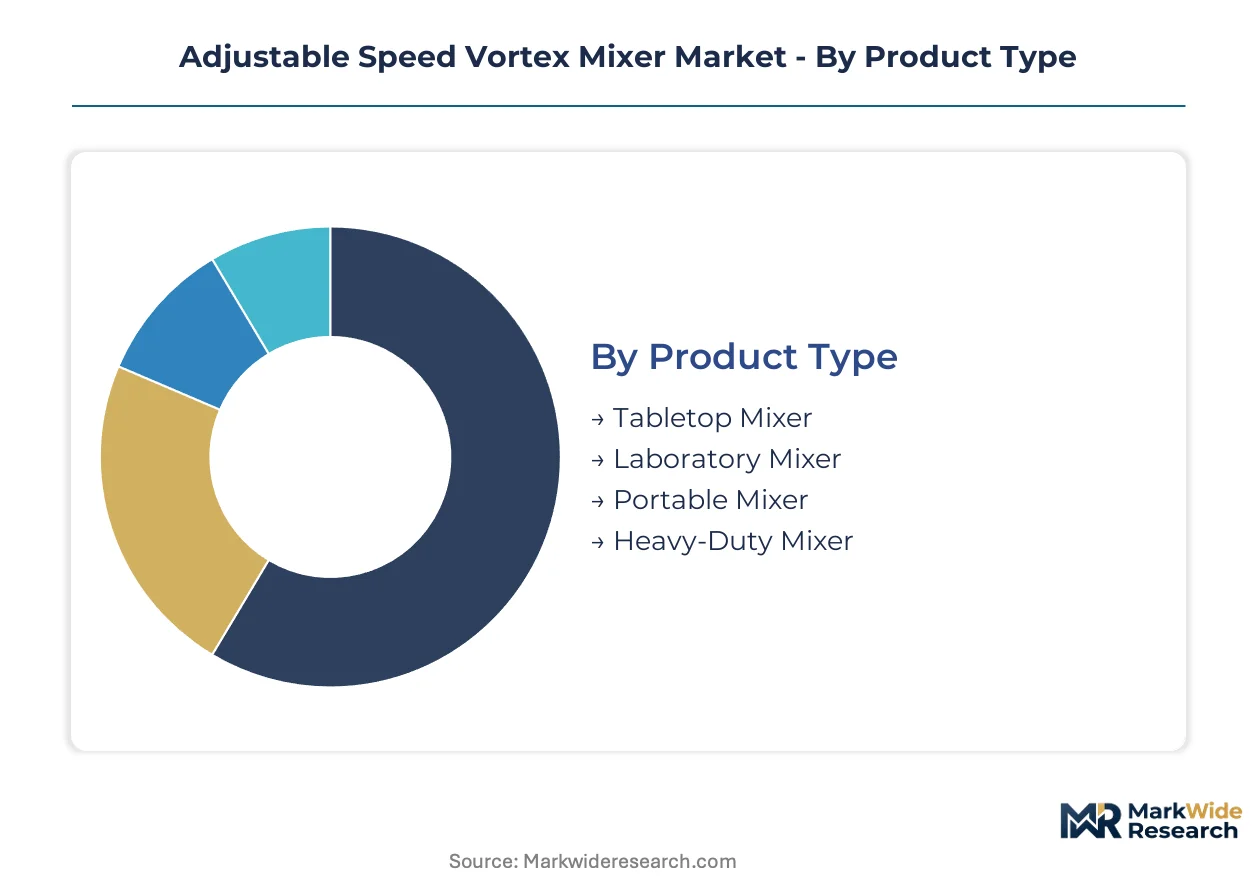
Adjustable speed vortex mixer procurement patterns diverge sharply across institutional settings, with academic buyers prioritizing capital efficiency while pharmaceutical quality-control operations demand validated calibration documentation. Technology selection and product format decisions cascade through compliance requirements, duty-cycle specifications, and integration complexity with existing laboratory infrastructure.
Product Type:
Domestic procurement concentrates in tabletop and laboratory configurations, while portable and heavy-duty variants track export-led demand from decentralized diagnostics networks and contract manufacturing clusters.
- Tabletop Mixer:Orbital shaking platforms in 200-3,000 rpm ranges dominate academic installations where space constraints and multi-user access predetermine format selection. United States research universities are consolidating framework agreements that bundle these units with centrifuge platforms, compressing distributor margins while expanding direct manufacturer relationships.
- Portable Mixer:Battery-operated units with brushless motor architectures are climbing the fastest among point-of-care testing facilities in India and Southeast Asia where cold-chain logistics and field deployment require mobile sample preparation. Procurement runs through regional distributors with established clinical diagnostics relationships rather than traditional laboratory supply channels.
- Laboratory Mixer:Mid-duty units with ISO 13485 certification documentation serve pharmaceutical quality-control environments requiring validated calibration traceability.
- Heavy-Duty Mixer:Continuous-duty architectures with extended orbital throw specifications support high-throughput cell disruption protocols in contract research organizations.
Tabletop mixer holds the largest share; momentum sits with portable mixer.
Technology:
Cost tier stratification separates premium brushless and piezoelectric architectures from standard magnetic and direct-drive alternatives, with certification-grade applications commanding specification premiums.
- Brushless Motor:Direct-drive architectures with integrated Hall-effect position sensing displace belt-driven alternatives in mid-to-premium tiers, reducing heat generation for 24-hour continuous pharmaceutical screening operations. FDA design control documentation requirements elevate procurement thresholds, disqualifying legacy motor suppliers from specification-intensive channels.
- Magnetic Drive:Simpler induction mechanisms without permanent magnet rotors occupy economy tiers where calibration documentation requirements remain minimal and replacement cycles are shorter.
- Direct Drive:Mechanical coupling architectures persist in legacy installations where orbital frequency verification protocols are already established.
- Piezoelectric Drive:Ultrasonic vibration mechanisms enable precise amplitude control for temperature-sensitive enzymatic reactions in specialized pharmaceutical stability testing.
Brushless motor commands specification-intensive procurement; piezoelectric drive is expanding most quickly in precision applications.
End User:
Volume concentration patterns separate high-unit academic procurement from low-volume, high-margin pharmaceutical and clinical segments where compliance documentation drives pricing power.
- Academic Institutions:Framework agreement consolidation across United States research universities is compressing vendor margins while expanding installed base for integrated life sciences platforms. Procurement offices prioritize capital efficiency and multi-instrument bundling over standalone specification optimization.
- Pharmaceutical Companies:Sterile fill-finish and stability testing operations require ISO 13485 certification and validated calibration documentation, creating specification premiums that sustain manufacturer margin pools.
- Research Laboratories:CRISPR screening and next-generation sequencing protocols are driving brushless motor specification in high-throughput genomics workflows.
- Clinical Labs:Point-of-care networks in decentralized settings are accelerating demand for portable, battery-operated configurations with simplified maintenance protocols.
Academic institutions hold the largest installed base; pharmaceutical companies sustain the steepest expansion trajectory.
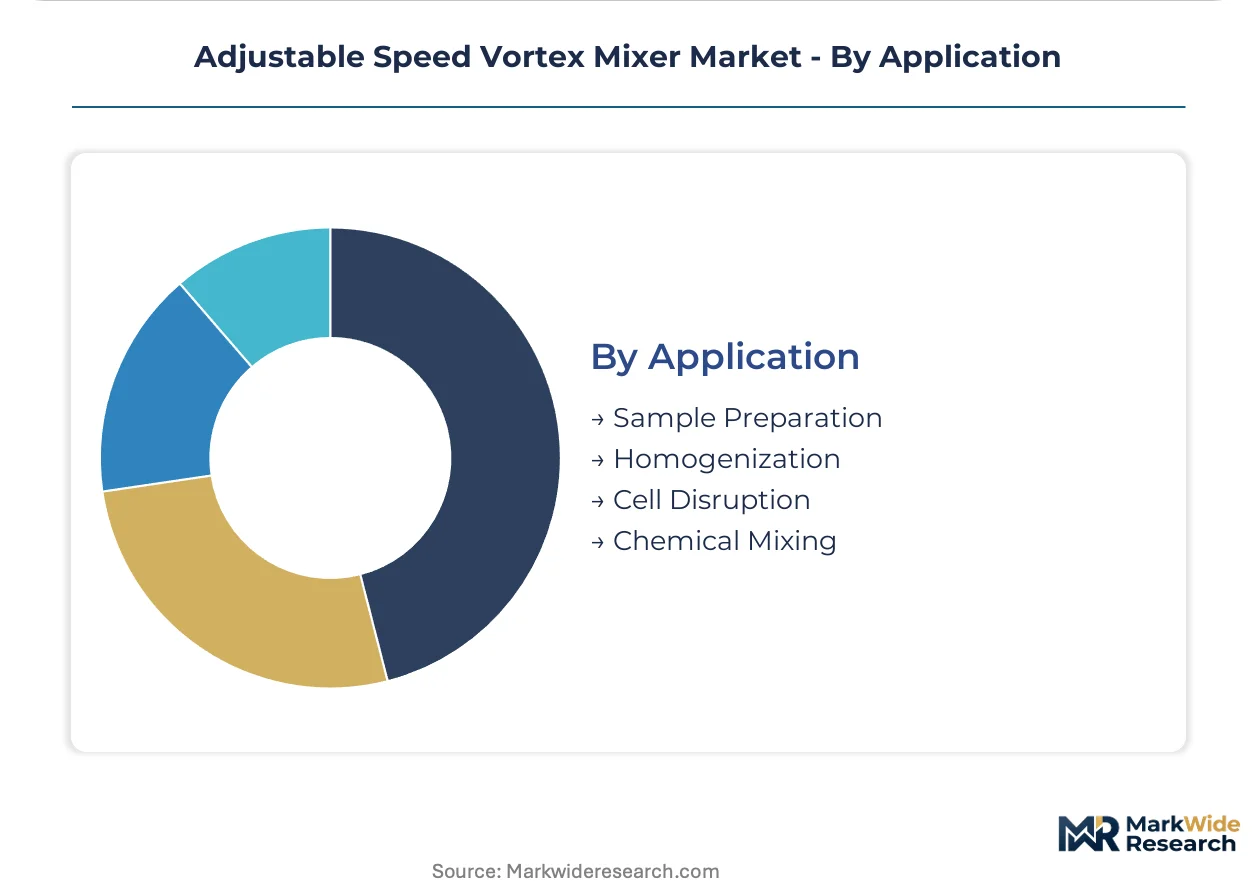
Application:
Maturity differentiation separates established sample preparation and homogenization workflows from emerging cell disruption and chemical mixing protocols where technology substitution risk is elevated.
- Sample Preparation:Standard microtube and plate-format suspension protocols represent the most mature application segment, with procurement decisions driven by capital cost minimization rather than performance differentiation.
- Cell Disruption:Bead-based homogenization systems are capturing share from traditional vortex mixing in lysis applications, forcing equipment manufacturers to integrate multi-modal disruption capabilities or retreat to lower-specification market tiers.
- Homogenization:Liquid-liquid and solid-liquid mixing protocols in environmental and food safety testing sustain steady replacement demand across regulatory inspection cycles.
- Chemical Mixing:Aggressive solvent exposure is forcing gasket and seal material substitutions under REACH restrictions, with fluoropolymer-free validation programs becoming prerequisites for European market access.
Sample preparation holds the largest share; cell disruption is gaining share fastest amid technology substitution dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of precision laboratory equipment track toward markets with dense pharmaceutical manufacturing and expanding academic research infrastructure. Import dependence for rare earth magnet components concentrates supply risk in brushless motor supply chains.
United States
Academic institutions are consolidating framework agreements for high-throughput genomics workflows. The FDA's updated quality system regulations for laboratory equipment mandate enhanced calibration documentation. Research universities in Massachusetts and California anchor procurement clusters where direct manufacturer relationships are displacing traditional distributor channels.
Germany
Precision instrument engineering clusters sustain premium positioning for laboratory equipment manufacturers. The EU MDR framework accelerates equipment refresh cycles as laboratories replace legacy mixers lacking updated technical documentation. IKA and Eppendorf anchor dense industrial concentrations in Hamburg and North Rhine-Westphalia that bypass traditional supply intermediaries.
China
Domestic pharmaceutical quality-control operations are expanding ISO 13485-certified equipment procurement. NMPA regulations align with international standards for in-vitro diagnostic device manufacturing. Contract manufacturing clusters in Jiangsu and Zhejiang provinces drive demand for continuous-duty mixer architectures in sterile fill-finish operations.
India
Point-of-care testing networks in decentralized clinical diagnostics are accelerating demand for portable battery-operated configurations. CDSCO regulations for medical device quality systems shape procurement specifications for diagnostic applications. Clinical diagnostics distributors in Maharashtra and Karnataka are building regional supply relationships outside traditional laboratory channels.
Japan
Pharmaceutical stability testing operations require validated calibration traceability for precision sample preparation equipment. METI electrification efficiency standards influence motor technology selections for cross-border instrument shipments. Precision manufacturing clusters in Osaka and Nagoya sustain demand for piezoelectric drive systems in temperature-sensitive enzymatic applications.
Adjustable Speed Vortex Mixer Market Competitive Landscape
Concentration sits with integrated life sciences platforms and specialized precision instrument engineers. The market structure bifurcates between specification-intensive procurement channels and capital-efficient academic segments. Three archetypes dominate: diversified platform bundlers, deep specialization players, and regional precision fabricators. Competitive moves center on direct institutional sales channel expansion and fluoropolymer-free material validation for European market access.
Among integrated platform providers, Thermo Fisher Scientific exemplifies the bundling archetype that combines vortex mixers with broader workflow solutions. Eppendorf occupies a position within the liquid-handling specialization tier. IKA represents German-engineered reliability standards that sustain premium positioning across European academic procurement channels. These three anchors illustrate how competitive differentiation flows from either breadth of integration or depth of technical specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eppendorf |
| IKA |
| Scientific Industries |
| VWR International |
| Heidolph Instruments |
| Benchmark Scientific |
| Bio-Rad Laboratories |
| Corning Incorporated |
| Others |
Pricing and Supply Chain Analysis
ISO 13485 certification gates both supplier qualification and price stratification in pharmaceutical procurement channels, compressing margin pools for uncertified manufacturers while elevating specification premiums for documented calibration traceability. Academic framework agreements and decentralized clinical networks operate on divergent cost structures that reshape upstream sourcing priorities.
Pricing Analysis
Pharmaceutical quality-control buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ISO 13485 documentation and FDA design control files driving tier placement. Brand premiums concentrate in German-engineered reliability standards from Hamburg and North Rhine-Westphalia manufacturing clusters, while volume-scale discounts dominate United States research university procurement. Pricing pressure stems from rare earth magnet cost volatility in brushless motor architectures, with academic institutions exhibiting highest price sensitivity and pharmaceutical sterile fill-finish operations least.
Supply Chain Analysis
Inventory buffers for Hall-effect position sensors and neodymium magnet rotors extend lead times for brushless motor assemblies, compressing responsiveness in specification-intensive procurement windows. Manufacturing concentrates in Germany, China, and the United States, with rare earth processing dependence tethered to Chinese infrastructure creating single-source vulnerability. Brushless motor components, fluoropolymer-free gasket materials, and precision orbital bearings constitute critical input dependencies. Distribution runs through direct institutional sales channels in academic markets and regional clinical diagnostics distributors in decentralized testing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision calibration capabilities and metrology technician scarcity are concentrating competitive advantage among manufacturers with captive validation infrastructure, widening the gap between specification-intensive and commodity-grade market tiers.
For Market Incumbents: Secure backward integration into brushless motor component supply to mitigate neodymium magnet sourcing exposure from Chinese processing infrastructure. Deepen ISO 13485 certification documentation capabilities to defend against magnetic bead homogenizer substitution in cell disruption applications. Channel control through direct institutional sales relationships in Germany and the United States anchors pricing power against distributor margin compression. For New Entrants and Emerging Players: Anchor in portable battery-operated configurations for point-of-care testing networks in Maharashtra and Karnataka, India, where CDSCO regulations are still formalizing and incumbent presence remains thin. Target clinical diagnostics distributors with established cold-chain logistics relationships rather than traditional laboratory supply channels. A service-first go-to-market model emphasizing simplified maintenance protocols addresses technician scarcity barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across piezoelectric drive system manufacturing due to precision ceramic fabrication requirements and METI efficiency compliance investments. Acquisition targets should display integrated Hall-effect sensing capabilities and existing FDA design control file infrastructure. The signal to watch is NMPA alignment progress among Chinese contract manufacturing clusters, indicating export-ready quality system maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer-Free Material Validation | REACH restrictions on perfluorinated compounds mandate gasket substitutions for European market access under ECHA enforcement. |
| Brushless Motor Backward Integration | Captive Hall-effect sensor production reduces neodymium magnet supply exposure from Chinese rare earth processing. |
| Direct Institutional Sales Channel Expansion | Framework agreements with Massachusetts and California research universities bypass distributor margin compression. |
| Digital Torque Sensing Integration | IoT-enabled condition monitoring enables predictive maintenance contracts in 24-hour pharmaceutical screening operations. |
| Portable Configuration Development | Battery-operated units address CDSCO-regulated point-of-care demand in decentralized Indian clinical diagnostics networks. |
Research Methodology
Initial hypotheses were tested against primary input from laboratory equipment procurement managers, pharmaceutical quality-control directors, biomedical engineers at contract research organizations, and aftermarket service heads at precision instrument distributors, then refined through secondary validation. FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and customs trade data for laboratory equipment imports provided triangulation anchors. Bottom-up installed base estimates and top-down pharmaceutical capital expenditure patterns were reconciled across analysis approaches.
Variance decomposition across product type, technology tier, end-user segment, and application maturity shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Brushless motor adoption curves in genomics workflows, EU MDR-driven equipment refresh timing, and DOE electrification efficiency standard implementation trajectories constituted industry-specific forecast inputs.
Material uncertainties — neodymium supply disruption, REACH restriction expansion, FDA quality system enforcement intensity — sit outside the modeled envelope and could revise trajectory assumptions. Forecasts reflect documented assumptions about regulatory alignment and technology substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Asia-Pacific Biosurgery Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
US Clear Aligners Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Ehealth Devices Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Video-Guided Pericardial Access Device Market