
 Public Access Automated External Defibrillators (Aeds) Market | 2026-2036
Public Access Automated External Defibrillators (Aeds) Market Size, Share, and Industry Trends Forecast 2026-2036
Public Access Automated External Defibrillators (Aeds) Market Insights
Lithium manganese dioxide chemistry is consolidating as the dominant power source for public access AEDs, displacing older sealed lead-acid battery packs across new installations. Stryker Corporation leverages its emergency care portfolio to sustain hospital-to-public channel continuity. ZOLL Medical Corporation anchors its position through proprietary Real CPR Help feedback technology. Koninklijke Philips N.V. differentiates via global service infrastructure that supports device readiness compliance.
Public access automated external defibrillators are portable electronic devices that analyze cardiac rhythm and deliver biphasic shock therapy to victims of sudden cardiac arrest, typically operating with energy outputs between 150 and 360 joules depending on patient impedance and waveform design. The semi-automatic product category dominates installed volume due to lower unit cost and broader operator training compatibility, while fully automatic configurations are capturing faster growth in unsupervised environments where bystander hesitation limits intervention rates. The public spaces application segment commands the largest share of replacement demand as municipal procurement cycles mature, though educational institutions represent an emerging margin pool driven by state-level mandates for campus cardiac emergency preparedness.
The FDA governs device safety and efficacy through 510(k) premarket clearance requirements, while the EU MDR imposes stricter clinical evidence standards for AEDs marketed across European member states. Japan's PMDA maintains distinct approval pathways that prioritize bilingual voice prompt validation and specific waveform documentation. Stakeholders must monitor evolving battery chemistry regulations and connectivity standards as remote device monitoring becomes integral to fleet management.
Market Dynamics
Cardiac emergency preparedness mandates are tightening installation requirements across transit hubs and educational campuses, compressing replacement cycles and elevating fleet management complexity for procurement officers.
Growth Catalysts
- Metropolitan transit density targets:Japan's PMDA-aligned deployment standards now exceed Western benchmarks, accelerating unit demand across Tokyo, Osaka, and Nagoya rail networks.
- Biphasic waveform standardization:Improved patient impedance matching is expanding operator confidence among untrained bystanders in unsupervised environments.
- Campus cardiac safety legislation:State-level mandates in the United States require AED accessibility within three minutes of any point on public university grounds.
Market Restraints
- Lithium manganese dioxide supply concentration:Battery cell production clusters in East Asia create single-source vulnerability for device manufacturers.
- EU MDR clinical evidence requirements:Stricter documentation standards for waveform efficacy are extending approval timelines by twelve to eighteen months.
- Sealed lead-acid residual installed base:Legacy chemistry in older units creates interoperability gaps with remote monitoring infrastructure.
Strategic Opportunities
- Remote readiness compliance platforms:Cloud-connected fleet management systems enable predictive maintenance contracts with municipal health departments.
- Voice prompt localization gaps:Bilingual validation requirements in Japan and Canada favor manufacturers with in-country acoustic engineering capabilities.
- Airport terminal retrofit waves:Federal Aviation Administration guidance on cardiac emergency response is triggering replacement demand at hub facilities.
Industry Challenges
- Biomedical technician certification scarcity:Qualified personnel for electrode pad replacement and battery testing are concentrated in urban hospital systems.
- Legacy device data migration:Older units lack standardized connectivity protocols, complicating unified fleet dashboards for multi-site operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Access Automated External Defibrillators (Aeds) Market |
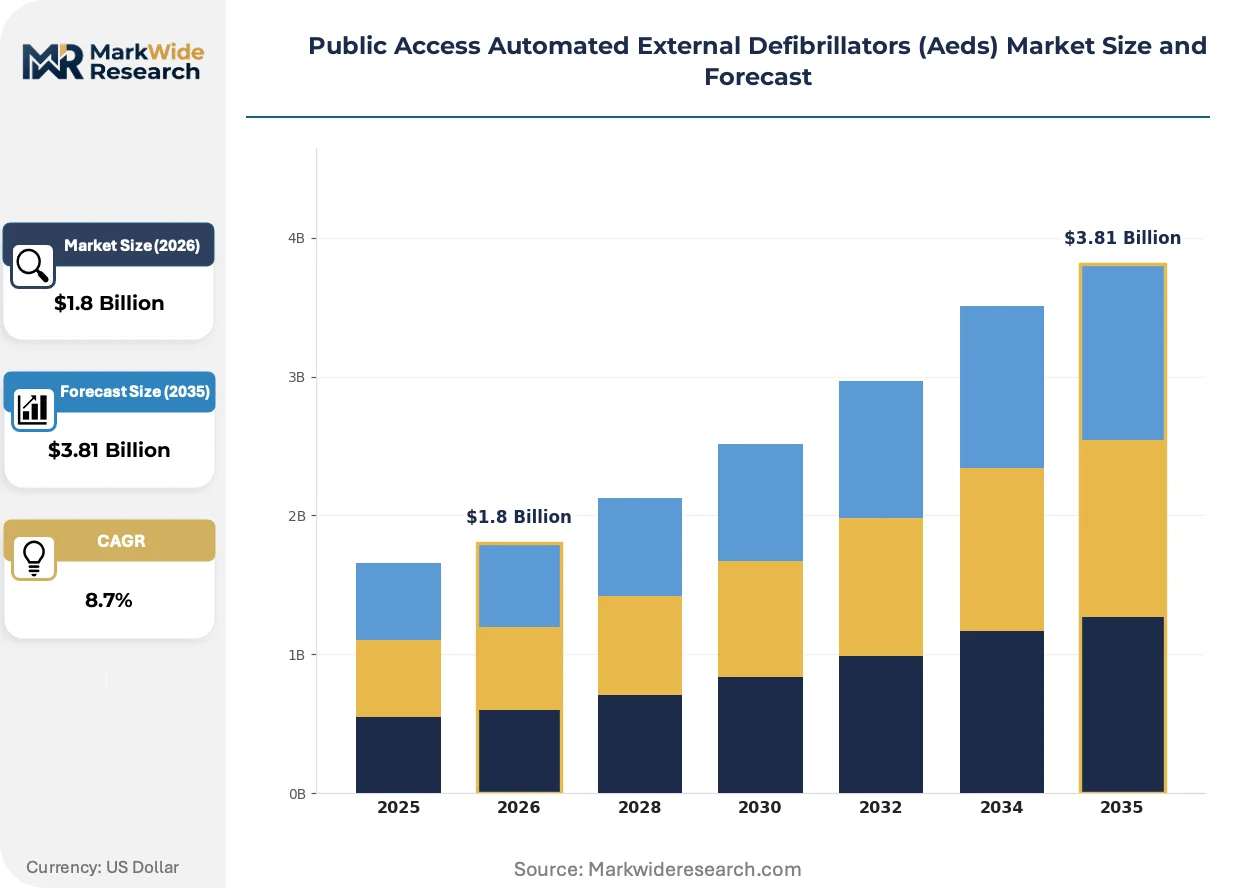
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Public Spaces, Sports Venues, Office Buildings, Educational Institutions Product Type: Semi-Automatic, Fully Automatic, Wearable AEDs, Training Devices End User: Healthcare Providers, Corporations, Non-Profits, Government Agencies Sales Channel: Direct Sales, Online Retail, Distributors, Medical Supply Stores |
| Companies Covered | Stryker Corporation, ZOLL Medical Corporation, Koninklijke Philips N.V., Nihon Kohden Corporation, Defibtech, Cardiac Science, HeartSine Technologies, Schiller AG, CU Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Access Automated External Defibrillators (Aeds) Market Trends and Innovations
Device intelligence and connectivity standards are redefining competitive advantage, shifting procurement criteria from unit cost toward total lifecycle readiness assurance and integration with emergency response ecosystems.
Connectivity modules with cellular and Wi-Fi capability are consolidating as default features in new installations, enabling real-time electrode pad expiration alerts and shock delivery transmission to emergency medical services. Airport authorities and university systems are specifying these capabilities in tender documents. The technology is consolidating vendor selection around platforms with proven interoperability with existing dispatch software.
The FDA's 510(k) premarket notification pathway continues shaping technical documentation requirements, particularly for waveform algorithm modifications that claim improved conversion rates. Manufacturers are responding by front-loading clinical evidence collection before submission. Hospital procurement committees now require FDA clearance documentation even for public access units.
Service contract unbundling is fragmenting traditional device-plus-maintenance bundles, with third-party biomedical service firms capturing electrode replacement and battery logistics. Municipal buyers are separating capital equipment acquisition from ongoing readiness assurance. This pattern is most pronounced in United States school district procurement, where facilities management departments negotiate maintenance separately from initial purchase.
Public Access Automated External Defibrillators (Aeds) Market Segmentation
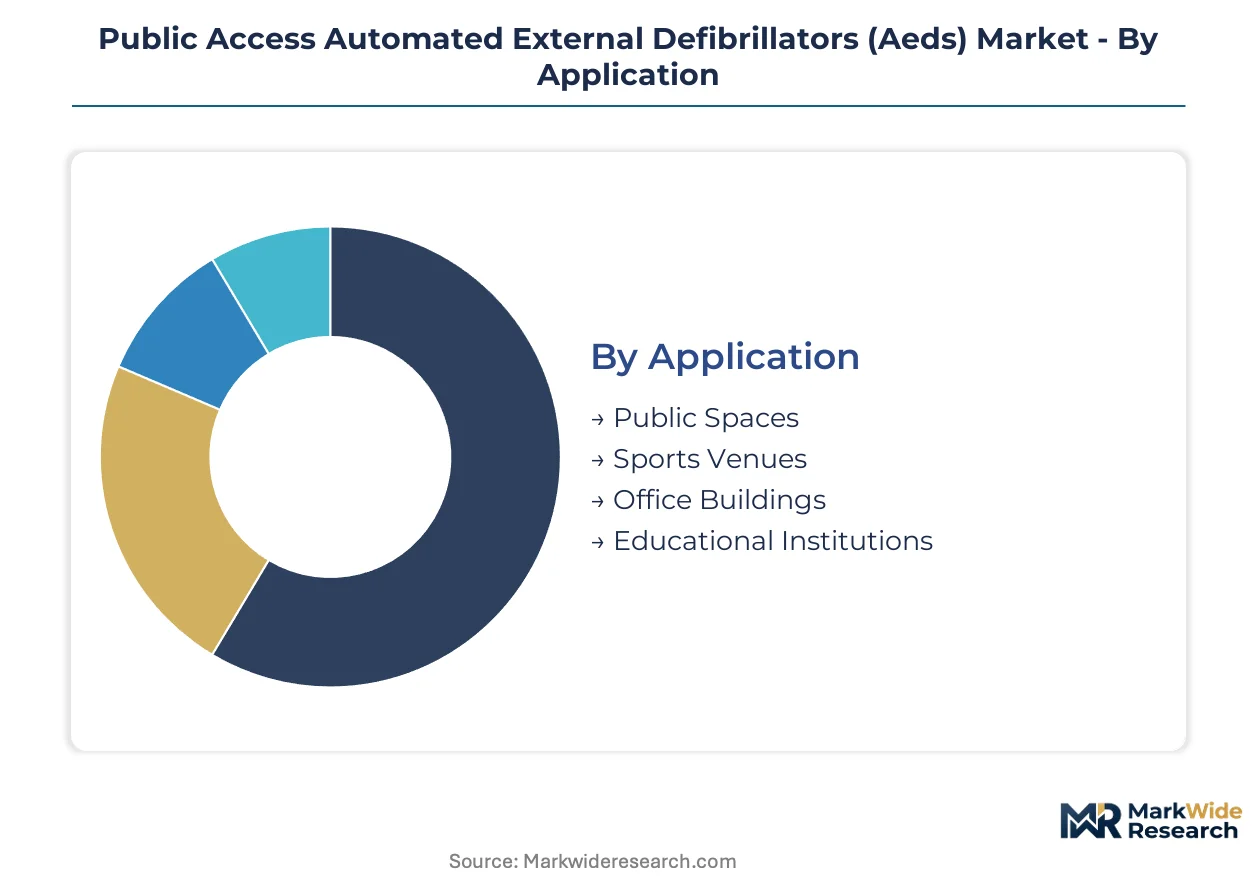
Procurement patterns for public access AEDs diverge sharply across installation environments, with regulatory mandates and operator training requirements dictating product specifications. Device manufacturers configure warranty terms, connectivity features, and service contracts differently for each segment.
Application:
Supply concentration in lithium manganese dioxide cell production favors high-volume municipal tenders over fragmented private installations.
- Public Spaces:Airport terminals, rail stations, and municipal buildings deploy units with bilingual voice prompts and cellular connectivity for fleet monitoring. Transit authorities in Japan and the United States specify these features in procurement documents.
- Sports Venues:Stadium operators prioritize rapid deployment cases with integrated CPR feedback and extreme temperature tolerance for outdoor seating sections. Professional league mandates in North America are compressing replacement cycles.
- Office Buildings:Corporate facilities managers favor compact wall-mounted units with minimal maintenance requirements and discrete aesthetic profiles for lobby installations.
- Educational Institutions:Campus safety officers specify pediatric-capable electrode pads and training-compatible devices to satisfy state-level cardiac emergency preparedness legislation.
Public Spaces absorbs the bulk of installed capacity; Educational Institutions is expanding most quickly.
Product Type:
Cost tier differentiation separates premium connected devices from basic units, with waveform algorithm sophistication driving price bands.
- Semi-Automatic:Operators must press a shock button after rhythm analysis, reducing liability exposure for untrained bystanders. These units dominate school district and municipal procurement due to broader training compatibility.
- Fully Automatic:Devices deliver shocks without operator intervention, eliminating hesitation delays in unsupervised environments. Airport authorities and remote industrial sites specify these configurations.
- Wearable AEDs:Vest-mounted systems with continuous ECG monitoring serve high-risk patient populations and occupational settings with cardiac event history.
- Training Devices:Non-shocking simulators with reusable electrode pads support CPR certification programs and facility staff preparedness drills.
Semi-Automatic retains the largest installed base; Fully Automatic is climbing the fastest as unsupervised deployment expands.
End User:
Customer type determines service contract structure, with healthcare providers demanding integrated fleet dashboards and non-profits prioritizing acquisition cost.
- Healthcare Providers:Hospital systems specify units compatible with existing emergency response infrastructure and require FDA 510(k) documentation for all purchases.
- Corporations:Risk management departments negotiate predictive maintenance contracts tied to electrode expiration alerts and remote readiness verification.
- Non-Profits:Community organizations and faith-based groups favor refurbished units and grant-funded installations with simplified maintenance protocols.
- Government Agencies:Federal, state, and municipal procurement officers mandate compliance with specific connectivity standards and bilingual voice prompt requirements.
Government Agencies deploy the greatest unit volume; Corporations are adopting connected fleet management fastest.
Sales Channel:
Volume concentration in distributor networks shapes manufacturer incentive structures and technical support allocation.
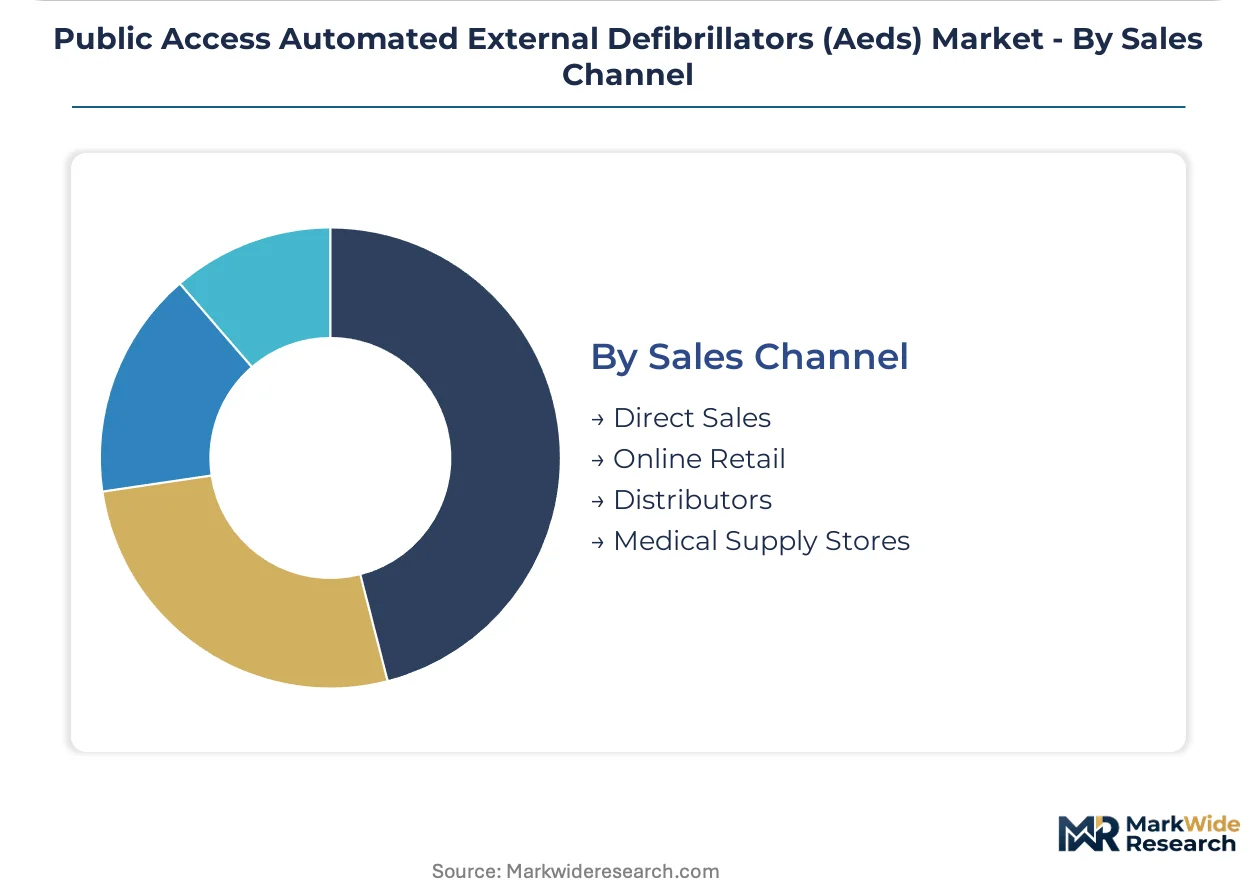
- Direct Sales:Manufacturers engage large healthcare systems and airport authorities directly for multi-site fleet deployments with customized service terms.
- Online Retail:E-commerce platforms serve small businesses and residential buyers with standard configurations and limited technical support.
- Distributors:Regional medical supply distributors dominate educational institution and municipal procurement through established relationships with facilities managers.
- Medical Supply Stores:Brick-and-mortar outlets support urgent replacement needs and provide hands-on product comparison for smaller commercial buyers.
Distributors channel the majority of institutional volume; Direct Sales is gaining share fastest among large healthcare networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's metropolitan transit networks and airport terminals in the United States and Germany concentrate the heaviest deployment density for public access AEDs, with regulatory mandates now exceeding Western preparedness benchmarks.
United States
Airport terminals and university campuses drive replacement demand as the FAA tightens cardiac emergency guidance and state-level campus safety legislation mandates three-minute accessibility standards. The FDA's 510(k) premarket notification pathway shapes technical documentation requirements for waveform algorithm modifications. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor hub facility retrofit waves.
Japan
Tokyo, Osaka, and Nagoya rail networks exceed Western public defibrillator density targets under PMDA-aligned deployment standards. The PMDA maintains distinct approval pathways prioritizing bilingual voice prompt validation and specific waveform documentation. Kanto region transit authorities specify cellular connectivity and fleet monitoring capabilities in procurement documents.
Germany
Municipal buildings and sports venues compress replacement cycles as the EU MDR imposes stricter clinical evidence standards for waveform efficacy. The EU MDR extends approval timelines by twelve to eighteen months for devices seeking European market access. Bavaria and North Rhine-Westphalia concentrate biomedical technician certification programs for electrode pad logistics.
United Kingdom
Educational institutions and corporate facilities expand installations under campus cardiac safety mandates and corporate risk management protocols. The Medicines and Healthcare products Regulatory Agency enforces CE marking transitions under EU MDR alignment. Greater London and Southeast England dominate distributor network concentration for institutional procurement.
Canada
Airport authorities and government facilities specify bilingual voice prompt requirements in tender documents, favoring manufacturers with in-country acoustic engineering capabilities. Health Canada regulates device safety through premarket licensing requirements aligned with FDA technical standards. Toronto Pearson and Vancouver International trigger hub facility replacement demand.
Public Access Automated External Defibrillators (Aeds) Market Competitive Landscape
Technology licensing and service contract unbundling dominate the current landscape, fragmenting traditional device-plus-maintenance bundles across institutional procurement. The vendor base separates into three tiers: diversified medical technology conglomerates with emergency care portfolios, specialized cardiac device manufacturers with proprietary feedback systems, and regional distributors capturing maintenance logistics. Strategic archetypes include waveform algorithm specialists, connectivity platform integrators, and third-party biomedical service firms. M&A activity concentrates among hospital-to-public channel continuity plays, while geographic expansion targets Japanese transit density premiums.
Among diversified medical technology conglomerates, Stryker Corporation and Koninklijke Philips N.V. exemplify portfolio breadth across hospital and public access channels. ZOLL Medical Corporation occupies a position within the specialized cardiac device tier, representing proprietary real-time CPR feedback technology. These three companies anchor competitive positioning around service infrastructure scale, algorithm sophistication, and fleet management platform integration.
| Leading Market Players |
|---|
| Stryker Corporation |
| ZOLL Medical Corporation |
| Koninklijke Philips N.V. |
| Nihon Kohden Corporation |
| Defibtech |
| Cardiac Science |
| HeartSine Technologies |
| Schiller AG |
| CU Medical Systems |
| Others |
Pricing and Supply Chain Analysis
Municipal procurement officers in Japan and the United States increasingly specify cellular connectivity and bilingual voice prompts as mandatory tender requirements, forcing manufacturers to absorb higher BOM costs or cede volume to competitors with established acoustic engineering capabilities in-country. This specification creep compresses margins on standard units while creating pricing power for vendors with vertically integrated firmware and localization teams.
Pricing Analysis
Volume concentrates in semi-automatic units sold through distributor networks to educational institutions and municipal buyers, while margins accrue to fully automatic configurations with integrated fleet management platforms sold direct to airport authorities. Price differentiation rests on FDA 510(k) clearance tier and cellular connectivity module inclusion. Pricing pressure stems from lithium manganese dioxide cell cost volatility as East Asian production clusters face export logistics constraints. School districts exhibit highest price sensitivity, deferring replacement cycles until electrode pad expiration triggers mandatory refresh.
Supply Chain Analysis
Direct-to-municipality channels handle hyperscale transit authority deployments in Tokyo and Osaka, while regional medical supply distributors manage fragmented educational institution procurement across North American school districts. Cell production concentrates in Japan, South Korea, and China, with electrode pad fabrication anchored in Malaysia and Costa Rica. Battery chemistry supply rests on cobalt and manganese ore flows from the Democratic Republic of Congo and Australia. Single-source vulnerability in East Asian lithium cell output creates exposure to maritime logistics chokepoints. Distribution runs through three-tier structures: manufacturer to national distributor to local biomedical service firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The public access AED market functions as a cost-of-compliance arena where the FDA's 510(k) premarket notification pathway and Japan's PMDA bilingual validation requirements erect substantial regulatory moats that filter out undercapitalized entrants and sustain pricing power for cleared incumbents.
For Market Incumbents: Anchor service infrastructure scale as the primary defensive lever by expanding predictive maintenance contracts with municipal health departments, countering third-party biomedical firms that unbundle electrode replacement logistics. Deepen backward integration into lithium manganese dioxide cell sourcing through offtake agreements with Korean and Japanese suppliers, mitigating single-source exposure as transit density targets accelerate in Tokyo and Nagoya. Prioritize in-country acoustic engineering investments to capture Canadian and Japanese bilingual tender premiums. For New Entrants and Emerging Players: Begin with refurbished device refurbishment and grant-funded community organization installations, exploiting price sensitivity among non-profit faith-based groups underserved by premium connected platforms. Target corporate facilities management departments in North American office buildings with simplified wall-mounted units lacking cellular modules, avoiding direct competition with Stryker and Philips in connected fleet segments. Pursue white-label partnerships with regional distributors lacking proprietary device portfolios. For Investors and Strategic Acquirers: Re-rating potential sits with specialized cardiac device manufacturers possessing proprietary CPR feedback algorithms given hospital procurement committees increasingly requiring FDA clearance documentation for public access units. Long-term viability favors vendors with demonstrated 510(k) submission success and integrated service platforms spanning hospital-to-public channel continuity. Monitor EU MDR approval timeline extensions as an inflection signal for European market access consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Clearance documentation now required by hospital procurement committees for public access units. |
| CE Marking Pathway under EU MDR | Stricter clinical evidence standards extend approval timelines and favor incumbent evidence libraries. |
| Hospital System Partnership | Emergency care portfolio continuity strengthens channel position for public access fleet expansion. |
| Software Companion Development | Remote readiness dashboards enable predictive maintenance contracts with municipal health departments. |
| Reimbursement Strategy | State-level campus safety legislation creates procurement budget certainty for educational institution sales. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, municipal procurement officer discussions, and biomedical technician field assessments underwrites the qualitative findings in this study. Primary research incorporated structured conversations with emergency care portfolio managers at diversified medical technology conglomerates, regulatory affairs specialists navigating FDA 510(k) and PMDA pathways, and facilities management directors at major U.S. airport authorities. Secondary validation drew from FDA 510(k) clearance databases, PMDA approval documentation, Japanese transit authority procurement records, and EU MDR technical documentation requirements. Bottom-up unit demand estimates from installation environment segmentation were triangulated against top-down market value reconstructions.
Comparable historical periods anchored the forecast window to mature replacement cycles in public spaces and emerging legislative mandates in educational institutions. The analytical framework modeled demand across product type, application environment, end-user category, and sales channel dimensions throughout the forecast period. CAGRs were derived from segment-specific growth trajectory assessments. Forecast inputs included lithium manganese dioxide cell supply constraints, EU MDR approval timeline extensions, and Japan's metropolitan transit density targets exceeding Western benchmarks.
Underlying measurement precision varies by segment; public spaces and airport terminal installations carry tighter precision due to documented procurement cycles, while wearable AEDs and training devices exhibit wider confidence intervals given fragmented demand. Forecasts reflect assumptions regarding regulatory pathway stability and battery chemistry supply continuity. Periodic stress-testing of base assumptions is recommended given single-source vulnerability in East Asian cell production and evolving connectivity standard requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Tricorder Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Disposable Lancets Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Global Hi-Tech Medical Devices Market
Medical Devices
Supraglottic Device Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Venous Device Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Endoprosthesis Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Low Vision Aids Market
Medical Devices
PPG Biosensors Market
Medical Devices
Global Medical Cannula Market