
 Global Laparoscopic and Open Hernia Mesh Repair Surgery Market | 2026-2036
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market Intelligence
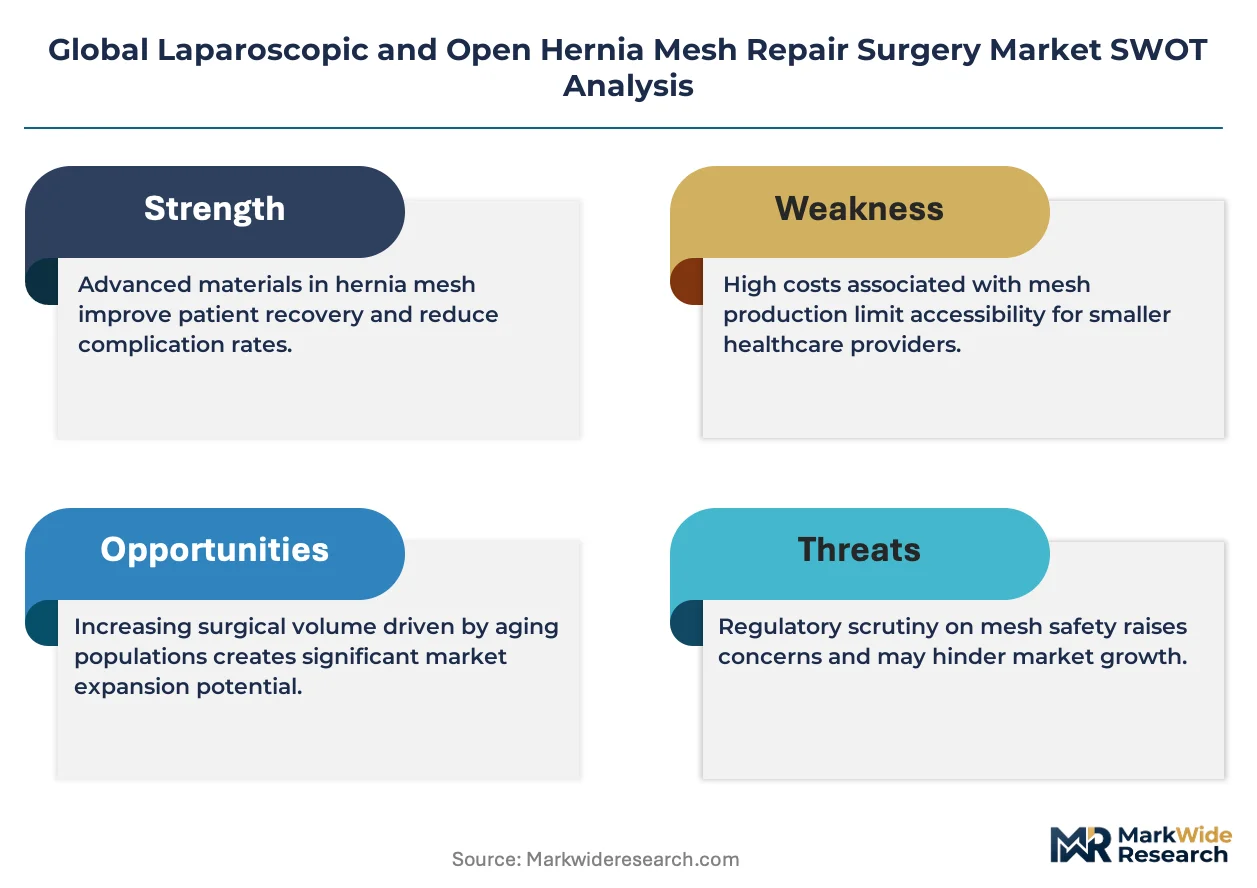
The European Union's Medical Device Regulation (MDR) is restructuring the cost-of-entry calculus for new hernia mesh products by mandating extensive clinical data. Medtronic plc leverages its extensive distribution network to maintain a significant presence in both laparoscopic and open surgery segments. Johnson & Johnson (Ethicon) differentiates through its focus on biologic and composite mesh innovations. B. Braun Melsungen AG competes on the basis of its comprehensive portfolio covering both mesh and fixation devices.
Laparoscopic and open hernia mesh repair surgery involves the surgical implantation of a prosthetic material to reinforce weakened tissue at a hernia site. These meshes are typically woven or non-woven sheets made from materials like polypropylene, designed to promote tissue ingrowth and provide durable abdominal wall support. While inguinal hernia repair remains the dominant application, biologic mesh products are gaining traction for complex incisional hernia cases despite higher costs. Robotic-assisted surgery represents the fastest-growing technology segment, offering enhanced precision for surgeons in specialized surgical centers.
Device approval and post-market surveillance are governed by agencies like the US Food and Drug Administration (FDA) and China's National Medical Products Administration (NMPA). Compliance with ISO 10993 for biocompatibility is a fundamental requirement for market access across major geographies. Stakeholders must now decide how to balance investment in next-generation absorbable materials against the established efficacy of permanent synthetic meshes.
Market Dynamics
The market's primary tension stems from the conflict between healthcare system cost-containment pressures and the heightened clinical evidence demands from regulations like the EU's MDR. This dynamic dictates R&D investment and market access strategies for all device manufacturers.
Growth Catalysts
- Aging Demographics:
Rising procedural volumes in developed nations like Germany and the United States are directly linked to an expanding elderly population, which has a higher incidence of hernias requiring surgical intervention.
- Robotic Surgery Adoption:
The expansion of robotic-assisted procedures in specialized surgical centers enhances operative precision and attracts patients, driving demand for compatible mesh and fixation devices designed for these advanced systems.
- Shift to Ambulatory Centers:
A procedural migration towards ambulatory surgical centers, particularly in the US, favors efficient, minimally invasive techniques with faster patient recovery, supporting the use of laparoscopic mesh products.
Market Restraints
- Post-Surgical Complications:
The risk of chronic pain and mesh-related complications creates patient reluctance and fuels litigation, particularly in the United States, leading to cautious adoption and higher professional liability insurance costs for surgeons.
- Stringent Regulatory Hurdles:
The EU's MDR and similar initiatives by China's NMPA require extensive and costly clinical trials for new device approval, raising significant barriers to entry for smaller innovators and slowing the pace of new product introductions.
- High Cost of Biologic Mesh:
The substantial price of biologic meshes restricts their application primarily to complex, recurrent, or contaminated hernia repairs, preventing broader market penetration despite their clinical advantages in tissue regeneration.
Strategic Opportunities
- Absorbable and Composite Materials:
Development of next-generation fully absorbable or hybrid meshes that combine synthetic strength with biologic integration capabilities presents a significant pathway for product differentiation and value creation.
- Emerging Economies:
Underpenetrated markets in countries such as Brazil and India offer substantial volume growth potential as healthcare infrastructure, surgeon training, and patient access to advanced surgical care expand.
- Personalized Mesh Solutions:
The application of 3D printing and advanced imaging to create patient-specific mesh implants for complex abdominal wall reconstruction represents a nascent but high-value opportunity for specialized manufacturers.
Industry Challenges
- Surgeon Training and Skill Gaps:
The steep learning curve for advanced laparoscopic and robotic-assisted hernia repair techniques creates a training bottleneck, limiting the pace of technology adoption outside of major academic medical centers.
- Reimbursement Complexity:
Securing favorable reimbursement codes and adequate payment levels for innovative but more expensive mesh technologies across different national healthcare systems remains a constant operational hurdle for market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laparoscopic and Open Hernia Mesh Repair Surgery Market |
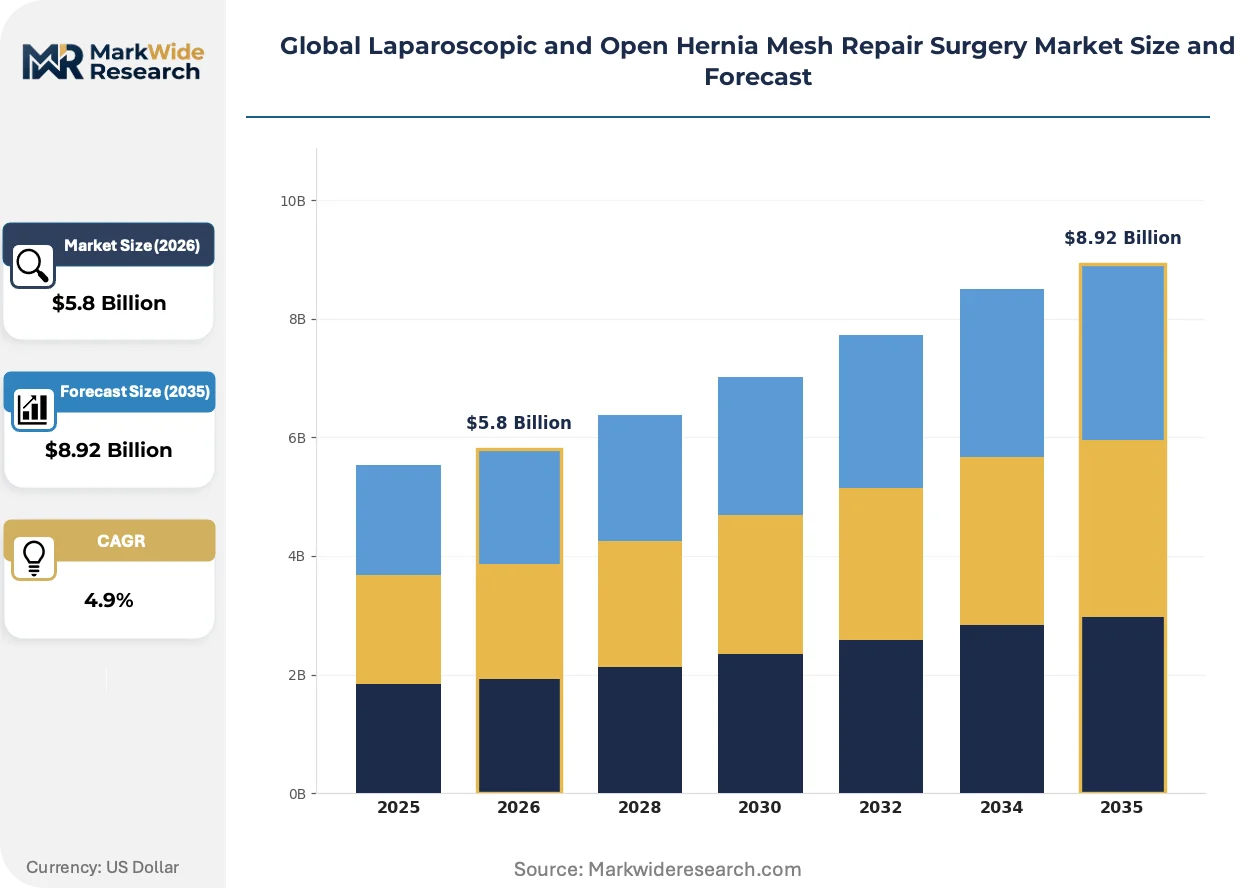
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.92 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene Mesh, Polyester Mesh, Expanded Polytetrafluoroethylene, Composite Mesh, Biologic Mesh Technology: Laparoscopic Technique, Open Surgery, Robotic-Assisted Surgery, Hybrid Procedure Application: Inguinal Hernia Repair, Incisional Hernia Repair, Umbilical Hernia Repair, Femoral Hernia Repair, Hiatal Hernia Repair End User: Specialized Surgical Centers, General Hospitals, Ambulatory Surgical Facilities, Outpatient Clinics |
| Companies Covered | Medtronic plc, Johnson & Johnson (Ethicon), B. Braun Melsungen AG, Becton Dickinson and Company, W. L. Gore & Associates, Cook Group Inc, Baxter International Inc., AbbVie Inc., Integra Lifesciences Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market Strategic Shifts & Innovations
The convergence of material science and digital surgery is reshaping the hernia mesh market. This evolution prioritizes long-term biocompatibility and improved surgical precision, shifting focus beyond basic mechanical reinforcement toward more integrated and data-supported patient outcomes.
Robotic-assisted surgery provides surgeons with enhanced 3D visualization and wristed instrumentation for intricate mesh placement and fixation. Specialized surgical centers and academic hospitals are rapidly adopting these systems for complex ventral and inguinal hernia repairs. This technological advancement is electrifying the surgical workflow, enabling more precise and minimally invasive procedures that were previously challenging with standard laparoscopy.
Implementation of the European Union's Medical Device Regulation (MDR) now mandates more rigorous pre-market clinical evidence and continuous post-market surveillance for all hernia meshes. This regulation significantly increases the time and cost associated with bringing new mesh products to the European market. Manufacturers of permanent synthetic meshes are most affected, now needing to generate long-term clinical data comparable to that required for implantable pharmaceuticals.
A clear preference shift is occurring within hospital purchasing committees toward devices supported by extensive, long-term clinical outcome data. This trend favors established manufacturers with the resources to fund large-scale trials, displacing smaller market participants who compete primarily on price. This data-driven purchasing behavior is most prominent in large hospital networks in the United States and Germany, where value-based care initiatives are influential.
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market Segmentation
Market segmentation provides a granular view of the diverse product offerings, technological advancements, and end-user preferences shaping the hernia mesh repair surgery landscape. This detailed analysis helps stakeholders understand specific demand patterns and strategic investment areas within the global market.
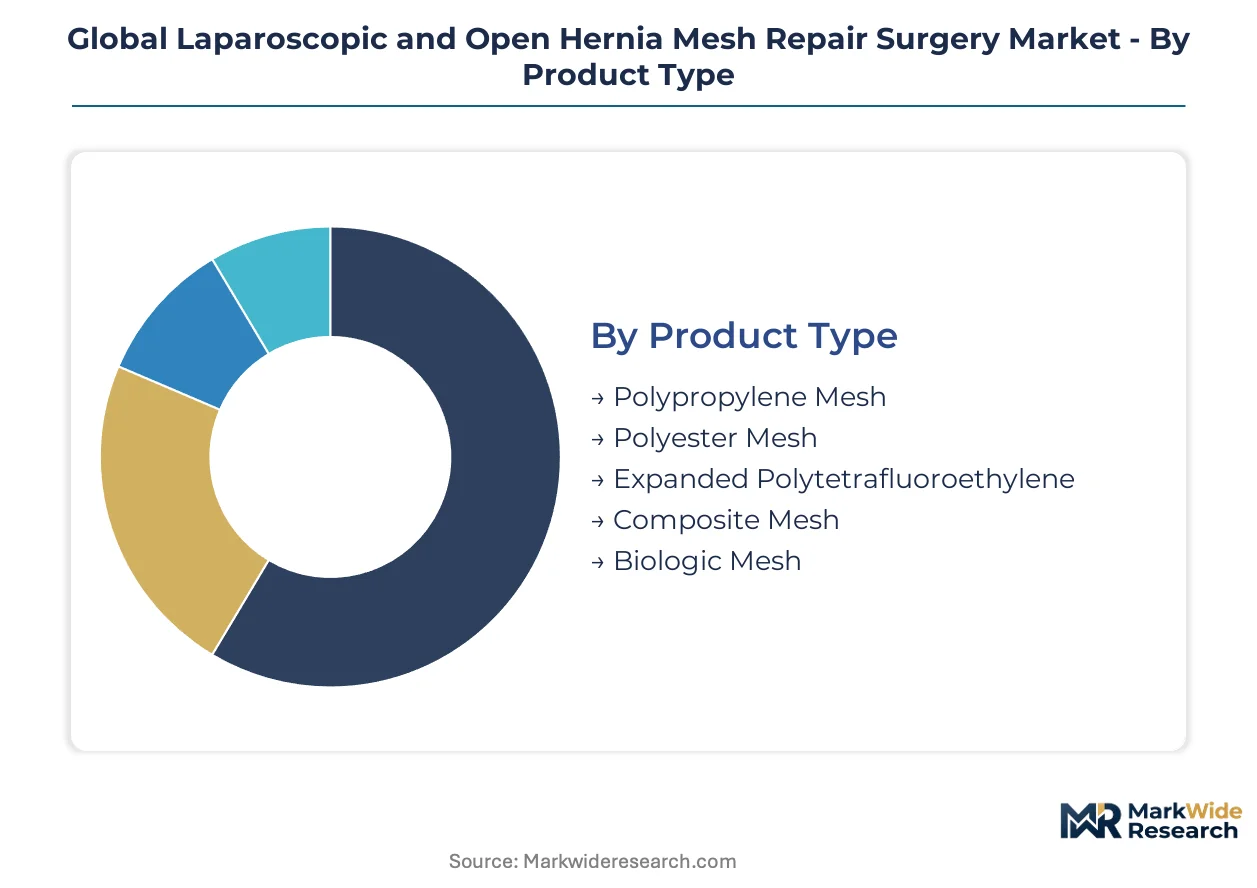
Product Type:
Regulatory scrutiny from agencies like the US Food and Drug Administration (FDA) and the European Union's Medical Device Regulation (MDR) significantly influences the market for various mesh product types, dictating required clinical evidence and post-market surveillance.
- Polypropylene Mesh:These synthetic meshes are widely used due to their strength and durability, offering a cost-effective solution for reinforcing weakened abdominal walls. Demand remains high in general surgical practices across both developed and emerging economies due to established clinical efficacy.
- Polyester Mesh:This synthetic mesh type provides good handling characteristics for surgeons and is often coated to reduce tissue adhesion. Its application is prevalent in various hernia repairs, particularly where a balance of strength and flexibility is desired.
- Expanded Polytetrafluoroethylene:Known for its inertness and biocompatibility, this non-absorbable synthetic mesh minimizes tissue integration, making it suitable for certain types of hernia repair.
- Composite Mesh:Combining synthetic materials with absorbable or biologic components, composite meshes aim to offer both mechanical strength and improved tissue integration over time. These products are increasingly favored for their balanced performance profile, particularly in cases requiring reduced foreign body reaction.
- Biologic Mesh:Derived from animal or human tissue, biologic meshes are designed to promote tissue regeneration and are often used in complex, contaminated, or recurrent hernia cases. Their higher cost restricts their application primarily to specialized surgical centers where tissue integration is critical.
Leading the category by volume: Polypropylene Mesh. Growing fastest: Biologic Mesh.
Technology:
The choice of surgical technology directly impacts procedural efficiency and patient recovery profiles across different hernia repair scenarios, influencing adoption rates in various healthcare settings.
- Laparoscopic Technique:This minimally invasive approach utilizes small incisions and camera guidance for mesh placement, leading to reduced patient discomfort and faster recovery. Adoption is concentrated in ambulatory surgical facilities and general hospitals due to its efficiency benefits.
- Open Surgery:The traditional surgical method involves a larger incision for direct visualization and repair of the hernia defect. This technique remains common for complex or recurrent hernias, or in settings with limited access to advanced equipment.
- Robotic-Assisted Surgery:Employing advanced robotic systems, this technology offers enhanced precision, 3D visualization, and wristed instrumentation for intricate mesh placement. Specialized surgical centers and academic hospitals are rapidly adopting these systems for complex ventral and inguinal hernia repairs.
- Hybrid Procedure:These procedures combine elements of both open and minimally invasive techniques to optimize outcomes for specific patient conditions or hernia complexities.
Robotic-Assisted Surgery is expanding most quickly due to its precision, while Open Surgery maintains significant procedural volume.
Application:
Hernia repair applications vary significantly based on anatomical location and the complexity of the patient's condition, influencing surgical approach and mesh selection across global markets.
- Inguinal Hernia Repair:This procedure addresses hernias in the groin region, which are highly prevalent, especially among men. It represents the dominant application segment, performed across a wide range of surgical settings due to its high incidence rate.
- Incisional Hernia Repair:Correcting hernias that develop at previous surgical incision sites, this application often involves more complex cases requiring robust mesh reinforcement. Demand concentrates in patients with a history of abdominal surgery, often necessitating specialized materials like biologic meshes.
- Umbilical Hernia Repair:This application targets hernias located near the navel, common in both infants and adults.
- Femoral Hernia Repair:Addressing hernias in the upper thigh or groin area, this type of repair is more frequently observed in women.
- Hiatal Hernia Repair:This procedure fixes the protrusion of the stomach through the diaphragm, often performed to alleviate symptoms associated with gastroesophageal reflux disease.
The largest volume of procedures occurs in Inguinal Hernia Repair, with Incisional Hernia Repair growing in complexity and material demand.
End User:
The market's end-user landscape reflects a shift towards optimized care settings, driven by cost-efficiency and patient convenience considerations in numerous countries.
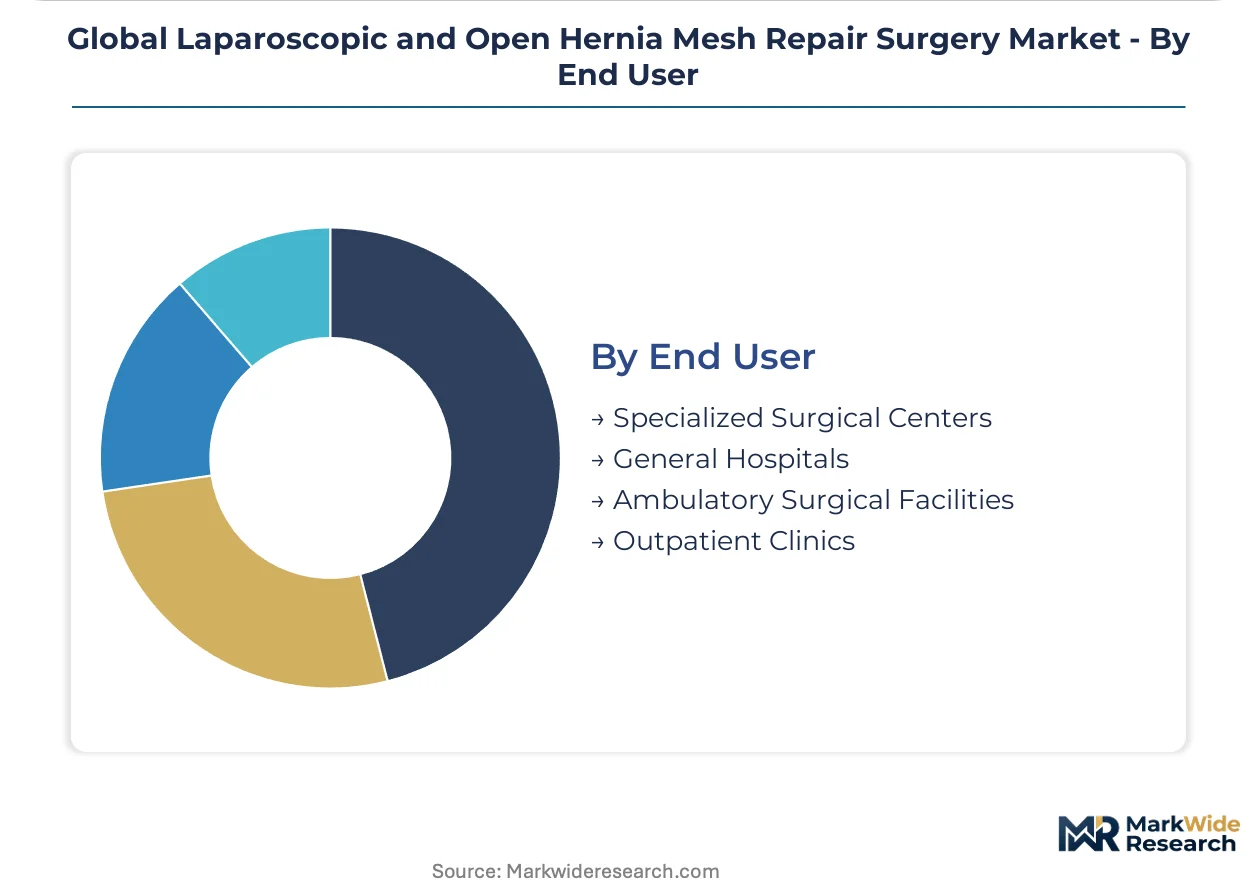
- Specialized Surgical Centers:These facilities focus on specific surgical domains, often performing advanced or complex hernia repair procedures using cutting-edge technologies like robotic systems.
- General Hospitals:As comprehensive medical institutions, general hospitals offer a broad spectrum of surgical services, handling both routine and emergency hernia repairs. They serve as primary providers for complex cases requiring extensive post-operative care.
- Ambulatory Surgical Facilities:Dedicated to outpatient surgeries, these facilities prioritize efficiency and faster patient turnaround for minimally invasive hernia repairs. A procedural migration towards these centers is evident, particularly in the United States, due to reduced costs and shorter recovery times.
- Outpatient Clinics:These clinics primarily provide consultations, diagnostic services, and follow-up care, with limited capacity for advanced surgical interventions.
Ambulatory Surgical Facilities are gaining share due to procedural efficiencies, while General Hospitals remain central for complex interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hernia mesh repair surgery concentrates heavily in developed nations, where an aging populace drives procedural volumes. Emerging economies also present significant growth potential as healthcare infrastructure expands. This global market dynamic shapes investment and market access strategies.
United States
The United States market sees robust demand for hernia repair, driven by an expanding elderly population and a shift to ambulatory surgical facilities. The US Food and Drug Administration (FDA) mandates rigorous device approval and post-market surveillance for mesh products. Major medical hubs like Boston and Houston drive adoption of robotic-assisted surgery.
Germany
Germany exhibits strong demand, fueled by an aging demographic with a higher incidence of hernias and a focus on value-based care. The EU's Medical Device Regulation (MDR) significantly influences market entry and product compliance. Cities like Munich and Berlin host specialized surgical centers that adopt advanced techniques.
China
China's market experiences substantial volume growth as healthcare infrastructure improves and patient access to advanced surgical care increases. The National Medical Products Administration (NMPA) enforces stringent regulatory hurdles for new device approvals. Coastal economic zones, including Shanghai, are seeing significant investment in surgical technology.
India
Underpenetrated markets in India offer substantial volume growth potential as surgeon training and patient access to advanced surgical care expand. The country's national pharmaceutical regulator oversees medical device approvals, focusing on local market access. Metropolitan areas like Mumbai and Delhi are developing specialized surgical facilities to meet rising demand.
Brazil
Brazil represents an emerging economy with considerable potential for hernia mesh repair surgery, driven by expanding healthcare capabilities. ANVISA regulates medical device market access and safety, ensuring compliance with international standards. São Paulo and Rio de Janeiro are centers for advanced surgical training and adoption of new mesh technologies.
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market Key Industry Players
North American producers anchor one tier; European specialists hold another, creating a tiered market structure. This market features large diversified medical device manufacturers, specialized mesh innovators, and comprehensive portfolio providers, each vying for distinct segments. Companies frequently pursue portfolio diversification and geographic expansion as dominant competitive moves to capture market share and access new patient populations.
Within the large diversified medical device manufacturers tier, Medtronic plc and Johnson & Johnson (Ethicon) represent established global players. These companies leverage their scale and broad market reach to serve diverse customer needs, from general hospitals to specialized surgical centers. B. Braun Melsungen AG, a German-based entity, exemplifies a comprehensive portfolio provider, offering both mesh and fixation devices. These entities occupy positions across various surgical segments, from routine to complex interventions. Their long-standing market presence and continuous product development efforts reinforce their competitive standing in the global market.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson (Ethicon) |
| B. Braun Melsungen AG |
| Becton Dickinson and Company |
| W. L. Gore & Associates |
| Cook Group Inc |
| Baxter International Inc. |
| AbbVie Inc. |
| Integra Lifesciences Holdings Corporation |
| Others |
Cost & Logistics Intelligence
The EU's Medical Device Regulation (MDR) significantly gates qualified mesh supply and premium-tier pricing access for manufacturers. This regulation mandates extensive clinical evidence, restructuring market entry costs.
Pricing Analysis
Short lead times for specialized mesh products command premium pricing, while general polypropylene meshes often see spot inventory discounts. The dominant pricing structure is per-unit transactional, influenced by product complexity and regulatory compliance. Price differentiation stems from certification level, particularly ISO 10993 biocompatibility, and bundled after-sales surgical training. Pricing softness reflects intense competition in the established synthetic mesh segment, where ambulatory surgical facilities are highly price-sensitive. Specialized surgical centers prioritize clinical outcomes for complex cases, showing less price sensitivity.
Supply Chain Analysis
Polypropylene mesh supply relies on a few global specialty chemical manufacturers for raw polymer. Supply concentration exists in countries like Germany and the United States for advanced mesh production, alongside China for basic synthetic materials. Key inputs include medical-grade polypropylene, polyester fibers, ePTFE, and animal-derived tissues for biologics. A structural risk is single-source vulnerability for specialized raw materials; distribution runs through established medical device distributors and direct sales forces to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hernia mesh market is a consolidation play, driven by the EU's MDR mandating extensive clinical data. This regulatory pressure disproportionately impacts smaller innovators, forcing market exits or acquisitions.
For Market Incumbents:
Deploy extensive clinical trial resources to meet evolving regulatory demands, particularly for long-term data under the EU's MDR. Consolidate smaller innovators with promising absorbable material technologies to expand product portfolios. This counters the threat of patient litigation and cautious adoption due to post-surgical complications. Invest in advanced manufacturing capacity in the United States and Germany to ensure high-quality mesh production.
For New Entrants and Emerging Players:
China's NMPA regulatory framework in China opens a window for locally manufactured, cost-effective synthetic meshes to address volume demand. Target underpenetrated markets in India and Brazil with basic, clinically proven polypropylene meshes for routine inguinal repairs. Focus on developing personalized mesh solutions using 3D printing, partnering with specialized surgical centers for complex cases.
For Investors and Strategic Acquirers:
Rising robotic-assisted surgery procedural volumes in academic hospitals are the leading indicator that demand for compatible mesh and fixation devices will surge. The market offers long-term viability, driven by aging populations and technological advancements over the next decade. Identify vertically integrated mid-cap specialists in absorbable or composite mesh technologies. Successful reimbursement code approvals for novel mesh materials in the United States signal market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Data Generation for MDR Compliance | Ensures market access in Europe and establishes long-term product credibility for all mesh types. |
| Robotic-Assisted Mesh Product Development | Captures demand from specialized surgical centers adopting advanced precision technologies for complex repairs. |
| Expansion into Emerging Economies | Accesses substantial volume growth potential in countries like India and Brazil with expanding healthcare infrastructure. |
| Absorbable Material R&D Investment | Differentiates product offerings with next-generation meshes that combine synthetic strength with biologic integration. |
| Strategic Acquisition of Biologic Mesh Innovators | Integrates high-value, specialized products for complex incisional hernia cases into existing portfolios. |
Research Approach
FDA filings, EU MDR guidance documents, and surgical society publications formed the secondary backbone for market sizing and trend analysis. This was complemented by primary interviews with hospital purchasing committees, orthopedic surgeons, regulatory affairs leads, and medical device engineers. A bottom-up approach validated market volumes, while a top-down analysis confirmed overall market values.
Historical trendline analysis established baseline growth rates and identified key market shifts across the analysis window. The model segmented the market by product type, technology, application, end-user, and regional regulatory environment. Compound annual growth rates were derived from projected procedural volumes and average selling prices. Key forecast inputs included aging demographic shifts and robotic surgery adoption rates.
Caveats apply where unforeseen regulatory changes or major product recalls could materially shift the outlook. Forecasts reflect assumptions regarding healthcare spending and technological innovation. A small set of named triggers, including new litigation outcomes, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Implantable Port Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
South Africa Minimally Invasive Surgical Devices Market
Medical Devices
MRI Motion Tracking Systems Market