
 Asia-Pacific Arthroscopy Devices Market | 2026-2036
Asia-Pacific Arthroscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Arthroscopy Devices Market Insights
Aftermarket service revenue is reconfiguring margin pools across the Asia-Pacific arthroscopy landscape. Stryker Corp leverages its extensive service network to capture recurring instrument calibration and maintenance contracts. Smith & Nephew PLC anchors its regional position through specialized training programs for surgeons in sports medicine applications. Karl Storz GmbH & Co KG competes on optical precision, sustaining premium positioning for rigid endoscope refurbishment cycles.
Arthroscopy devices encompass minimally invasive surgical instruments designed for joint visualization and intervention, typically employing fiber-optic camera systems with 2.7–4.0 mm outer diameters and high-definition image sensors operating at 1080p or 4K resolution for diagnostic and therapeutic procedures within synovial cavities. Shavers and visualization systems command the dominant product share, with shaver handpieces representing a mature replacement-driven segment while 3D imaging platforms capture accelerated capital expenditure from hospitals upgrading legacy 2D arthroscope towers. Single-use devices are gaining fastest traction in ambulatory surgical centers where reprocessing economics and infection control protocols reshape procurement patterns.
PMDA in Japan, CDSCO in India, and NMPA in China each enforce distinct registration pathways for class II and III arthroscopy instruments, with CDSCO's recent reliance on predicate device harmonization accelerating market entry for established OEMs while NMPA's domestic clinical trial requirements extend timelines for novel visualization technologies. Australia's TGA maintains alignment with EU MDR transition timelines, creating parallel compliance obligations for manufacturers serving both markets. Stakeholders must weigh regulatory divergence against the cost of maintaining separate quality management system documentation across these jurisdictions.
Market Dynamics
Hospital infrastructure modernization across Asia-Pacific is compressing replacement cycles for legacy 2D arthroscopy towers, while regulatory divergence between PMDA, NMPA, and CDSCO is fragmenting approval timelines for novel visualization platforms.
Growth Catalysts
- Japan's PMDA streamlining:Expedited approval pathways for minimally invasive surgical instruments reduce time-to-market for established OEMs, accelerating capital deployment in tertiary hospital networks.
- Ambulatory surgical center expansion:Single-use arthroscopy devices gain procurement priority where reprocessing economics and infection control protocols reshape purchasing decisions.
- China's tier-one hospital upgrades:Orthopedic surgical suite investments concentrate in Beijing, Shanghai, and Guangzhou, driving shaver handpiece and visualization system demand.
Market Restraints
- Domestic clinical trial mandates:NMPA requirements for novel visualization technologies extend registration timelines beyond predicate device pathways available to legacy instruments.
- Optical component supply concentration:High-definition image sensor and fiber-optic cable production clusters in specific East Asian manufacturing zones create input vulnerability.
- Rigid endoscope refurbishment economics:Premium positioning for optical precision systems faces pressure from extended service life cycles and third-party maintenance alternatives.
Strategic Opportunities
- India's CDSCO harmonization:Predicate device reliance accelerates market entry for established OEMs, opening underserved secondary city hospital networks.
- 3D-4K visualization convergence:Integration of three-dimensional imaging with ultra-high-definition sensors creates differentiation in capital equipment replacement cycles.
- Aftermarket service unbundling:Specialized training programs and instrument calibration contracts capture recurring revenue independent of device sales.
Industry Challenges
- Surgeon certification bottlenecks:Sports medicine arthroscopy training program capacity constraints limit procedure volume expansion in expanding hospital departments.
- Multi-jurisdiction quality system documentation:Parallel compliance obligations for Australia's TGA and EU MDR transition timelines strain regulatory affairs resources.
- Legacy tower integration complexity:New visualization platforms face interoperability friction with existing hospital IT infrastructure and surgical workflow systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Arthroscopy Devices Market |
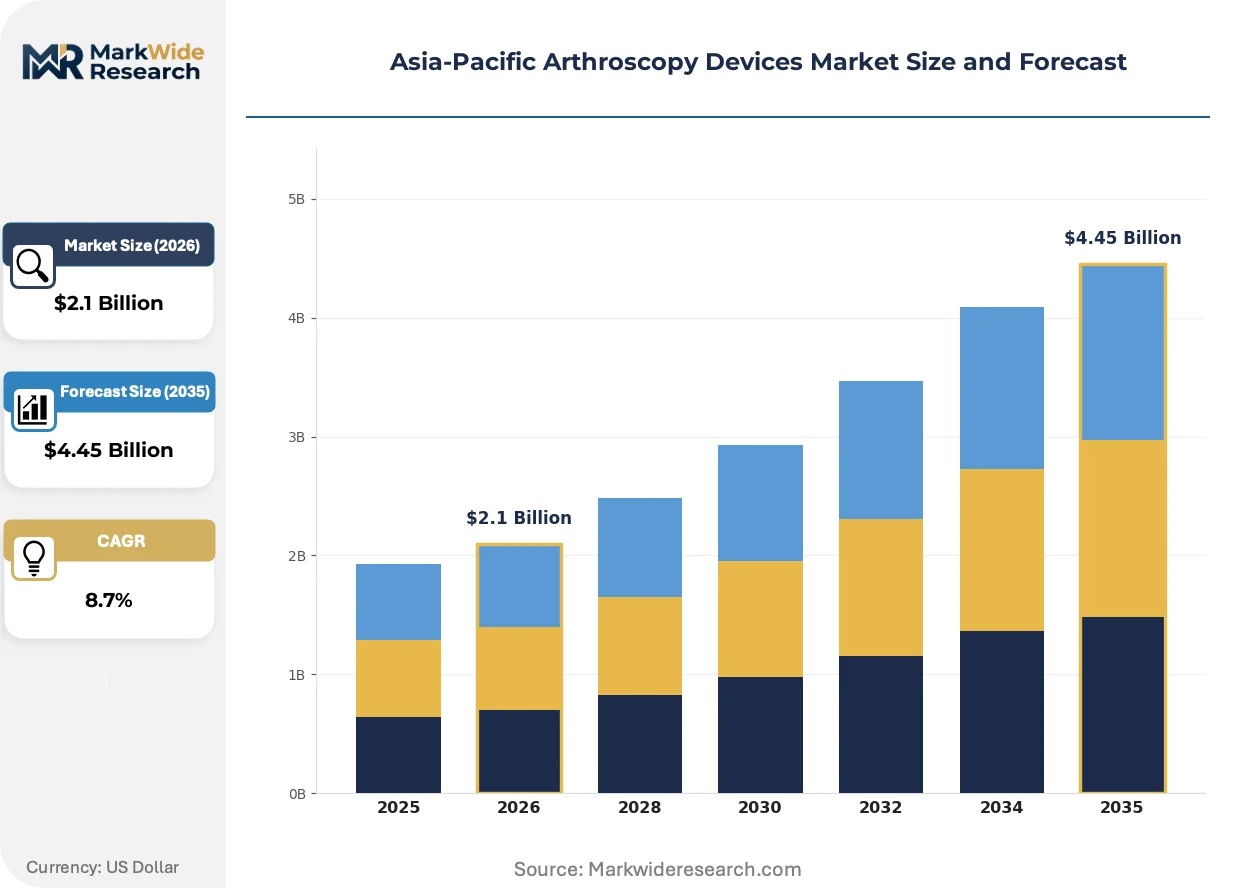
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arthroscopes, Shavers, Fluid Management Systems, Implants End User: Hospitals, Ambulatory Surgical Centers, Clinics, Rehabilitation Centers Technology: 3D Imaging, Robotics, Visualization Systems, Single-Use Devices Application: Joint Surgery, Sports Medicine, Trauma Surgery, Orthopedics |
| Companies Covered | Stryker Corp, Smith & Nephew PLC, Arthrex Inc, Conmed Corp, Zimmer Biomet Holdings Inc, Medtronic PLC, Karl Storz GmbH & Co KG, Johnson & Johnson, Richard Wolf GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Arthroscopy Devices Market Trends and Innovations
Technological convergence between imaging hardware and digital surgical workflows is restructuring capital allocation patterns across Asia-Pacific arthroscopy departments, with regulatory adaptation lagging behind product evolution.
4K resolution arthroscopy systems with integrated three-dimensional visualization capabilities are collapsing the performance gap between diagnostic and therapeutic procedures, enabling outpatient settings to perform interventions previously requiring inpatient admission. Ambulatory surgical centers in Japan and South Korea are adopting these platforms at compressed replacement cycles compared to legacy 2D towers. The technology is collapsing traditional site-of-care boundaries between hospital-based and freestanding surgical facilities.
PMDA's alignment with international harmonization frameworks for software-as-medical-device classification is reshaping regulatory obligations for AI-enabled image analysis modules in arthroscopy towers. Manufacturers must now submit standalone documentation for algorithm-based diagnostic assistance features previously embedded in hardware registrations. Visualization OEMs serving Japan are responding by segregating hardware and software development timelines to manage parallel approval tracks.
Hospital procurement committees are consolidating vendor relationships around full-suite arthroscopy ecosystem providers, displacing the historical pattern of best-of-breed component selection. Single-source contracts covering shavers, scopes, towers, and maintenance services are capturing preference in China's tier-one public hospital tenders. This concentration is most visible in Shanghai and Beijing where centralized purchasing authorities prioritize total cost-of-ownership metrics over upfront capital expenditure minimization.
Asia-Pacific Arthroscopy Devices Market Segmentation
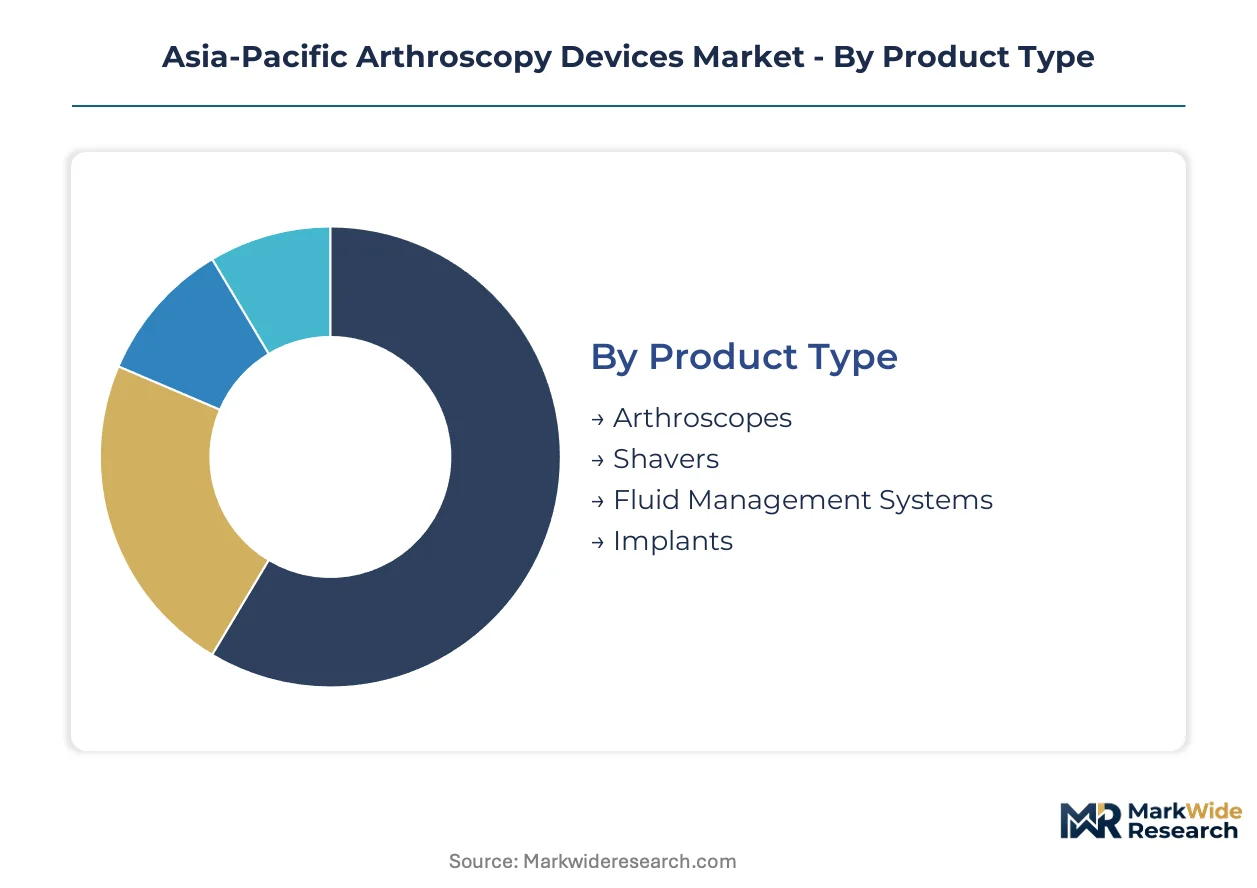
Segmentation in the Asia-Pacific arthroscopy devices market reveals divergent service intensity and margin structures across product categories. Aftermarket revenue potential varies sharply between capital equipment with multi-year calibration cycles and consumables with recurring replacement schedules.
Product Type:
After-sales service intensity separates arthroscopy product categories into distinct margin pools with divergent revenue recognition patterns.
- Shavers:Motorized handpieces with integrated cutting blades and suction channels require quarterly blade cartridge replacement and annual motor refurbishment. China's tier-one hospitals concentrate procurement for these systems as orthopedic surgical suite upgrades accelerate replacement of legacy pneumatic units.
- Visualization Systems:Tower-based platforms integrating camera heads, light sources, and image processing units demand bi-annual calibration contracts and firmware update subscriptions. Japan's PMDA streamlined software-as-medical-device classifications for these systems, compressing approval timelines for AI-enabled diagnostic modules.
- Arthroscopes:Rigid endoscopes with 2.7–4.0 mm outer diameters and rod-lens optical chains face extended refurbishment cycles that pressure premium positioning.
- Fluid Management Systems:Pump and suction units with pressure sensing and automated lavage control represent mature hardware with limited differentiation.
- Implants:Suture anchors and interference screws for ligament reconstruction carry inventory risk from surgeon-specific preference variability.
Shavers hold the largest share; momentum sits with visualization systems as 3D-4K convergence drives capital replacement.
End User:
Procurement authority concentration determines contract structure complexity and vendor relationship durability across customer types.
- Hospitals:Tertiary institutions with centralized purchasing committees negotiate multi-year full-suite contracts covering capital equipment, disposables, and maintenance services. Beijing and Shanghai public hospital networks prioritize total cost-of-ownership metrics over upfront capital minimization in tender evaluations.
- Ambulatory Surgical Centers:Freestanding facilities with streamlined surgical workflows favor single-use devices where reprocessing economics and infection control protocols reshape purchasing decisions. South Korea's ASC expansion is adopting 4K visualization platforms at compressed replacement cycles compared to legacy 2D towers.
- Clinics:Outpatient diagnostic settings with limited procedure volume rely on refurbished equipment and third-party maintenance alternatives.
- Rehabilitation Centers:Post-operative recovery facilities with therapeutic focus represent negligible direct equipment demand.
Hospitals dominate installed base; ambulatory surgical centers are expanding most quickly as site-of-care boundaries collapse.
Technology:
Regulatory documentation burden fragments development timelines across hardware-software boundaries in next-generation platforms.
- Visualization Systems:Integrated tower platforms with 1080p and 4K image sensors anchor capital expenditure patterns in orthopedic department budgets. PMDA's harmonization with international software-as-medical-device frameworks forces manufacturers to segregate hardware and algorithm approval tracks.
- Single-Use Devices:Disposable shaver blades, cannulas, and suction instruments eliminate reprocessing infrastructure requirements. India's CDSCO predicate device harmonization accelerates market entry for established OEMs serving secondary city hospital networks with these products.
- 3D Imaging:Stereoscopic visualization with depth perception enhancement enables outpatient procedures previously requiring inpatient admission.
- Robotics:Computer-assisted navigation and haptic feedback systems face extended NMPA domestic clinical trial mandates that prolong registration timelines.
Visualization systems command the largest share; single-use devices gain share fastest as infection control protocols harden.
Application:
Procedure volume growth rates and reimbursement differentiation separate application segments into distinct investment priorities.
- Sports Medicine:Ligament reconstruction and meniscal repair procedures drive shaver handpiece utilization and suture anchor consumption. Australia's TGA alignment with EU MDR transition timelines creates parallel compliance obligations for manufacturers serving both markets in this high-volume segment.
- Joint Surgery:Diagnostic arthroscopy and therapeutic intervention within synovial cavities concentrates demand in China's tier-one cities where hospital infrastructure upgrades prioritize orthopedic suites.
- Trauma Surgery:Acute injury management with arthroscopic reduction and fixation faces scheduling volatility that complicates equipment utilization planning.
- Orthopedics:General bone and joint intervention spans multiple subspecialties with fragmented purchasing authority.
Sports medicine holds the largest share; joint surgery shows the steepest expansion trajectory as diagnostic-therapeutic boundaries blur.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply between China's centralized hospital procurement and Japan's ASC-driven premium replacement cycles. Tertiary hospital networks in tier-one Chinese cities prioritize full-suite vendor consolidation, while Japanese facilities fragment purchasing across specialized service providers. India's secondary city expansion creates a distinct volume tier where predicate device pathways accelerate established OEM penetration.
China
Orthopedic surgical suite upgrades in Beijing, Shanghai, and Guangzhou concentrate demand for shaver handpieces and visualization systems. NMPA domestic clinical trial mandates for novel visualization technologies extend registration timelines beyond predicate device pathways. The Yangtze River Delta hospital procurement committees now prioritize total cost-of-ownership metrics over upfront capital minimization in tender evaluations.
Japan
Ambulatory surgical centers in Tokyo and Osaka adopt 4K visualization platforms at compressed replacement cycles compared to legacy 2D towers. PMDA streamlining of software-as-medical-device classifications compresses approval timelines for AI-enabled diagnostic modules. Kanto region tertiary hospitals anchor capital deployment through expedited minimally invasive surgical instrument pathways.
India
Secondary city hospital networks in Maharashtra and Karnataka drive single-use device procurement where reprocessing economics reshape purchasing decisions. CDSCO predicate device harmonization accelerates market entry for established OEMs serving previously underserved markets. The Delhi-NCR corridor concentrates sports medicine training program capacity that limits procedure volume expansion.
South Korea
Seoul Capital Area ASC expansion adopts 4K-3D convergence platforms faster than hospital-based facilities. MFDS alignment with international harmonization frameworks shapes regulatory documentation for integrated hardware-software systems. Busan-Ulsan manufacturing zones cluster high-definition image sensor production that feeds regional visualization OEM supply chains.
Australia
Sports medicine procedure volumes in New South Wales and Victoria create parallel compliance obligations with EU MDR transition timelines. TGA maintenance of alignment with European frameworks strains regulatory affairs resources for multi-jurisdiction manufacturers. Sydney and Melbourne hospital networks concentrate procurement authority for full-suite arthroscopy ecosystem contracts.
Asia-Pacific Arthroscopy Devices Market Competitive Landscape
Capability concentration sits with optical precision specialists; scale advantage sits with diversified surgical conglomerates. The vendor base organizes around three tiers: full-suite ecosystem providers capturing centralized hospital tenders, visualization specialists commanding premium refurbishment cycles, and single-use consumables manufacturers serving ASC price sensitivity. Strategic moves center on aftermarket service unbundling and 3D-4K visualization convergence as differentiation vectors.
Among diversified surgical technology conglomerates, Stryker Corp and Smith & Nephew PLC exemplify the full-suite ecosystem archetype. Stryker occupies a position anchored by extensive service networks capturing recurring instrument calibration contracts. Smith & Nephew sits within the premium training and education tier, with specialized surgeon development programs reinforcing regional positioning. Karl Storz GmbH & Co KG represents the optical precision specialist archetype, sustaining premium market presence through rigid endoscope refurbishment expertise.
| Leading Market Players |
|---|
| Stryker Corp |
| Smith & Nephew PLC |
| Arthrex Inc |
| Conmed Corp |
| Zimmer Biomet Holdings Inc |
| Medtronic PLC |
| Karl Storz GmbH & Co KG |
| Johnson & Johnson |
| Richard Wolf GmbH |
| Others |
Pricing and Supply Chain Analysis
High-definition image sensor and fiber-optic cable production clusters in South Korea and Japan's manufacturing zones concentrate upstream optical component supply, anchoring margin capture in tower-based visualization system refurbishment cycles and bi-annual calibration service contracts across Asia-Pacific hospital networks.
Pricing Analysis
Long-term full-suite contracts dominate Asia-Pacific hospital procurement, with Beijing and Shanghai public tenders prioritizing total cost-of-ownership metrics over upfront capital minimization. Price differentiation hinges on optical precision certification tiers and after-sales service bundling intensity. Cost compression in rigid endoscope refurbishment services is intensifying because third-party maintenance alternatives extend equipment life cycles. Ambulatory surgical centers exhibit highest price sensitivity, while tertiary hospital networks in tier-one Chinese cities show lowest sensitivity due to centralized budget authority.
Supply Chain Analysis
Contract manufacturing for arthroscopy handpieces and disposable instruments concentrates in China's Yangtze River Delta and South Korea's Busan-Ulsan zones, with Foxconn Medical and Jabil Healthcare holding significant EMS capacity. Component sourcing draws from Japanese optical glass foundries, German precision motor suppliers, and Taiwanese CMOS sensor fabricators. Single-source vulnerability in 4K image sensor supply creates exposure to logistics chokepoints through Shanghai port congestion. Distribution runs through regional medical device distributors with hospital GPO relationships in each national market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution pressure from single-use disposable platforms that eliminate reprocessing infrastructure requirements and capture ambulatory surgical center procurement preference.
For Market Incumbents: Harden ecosystem lock-in through captive supply of shaver blade cartridges and firmware-locked visualization tower upgrades that raise switching costs. Deepen backward integration into fiber-optic cable production to defend margin position against optical component cost volatility. Prioritize NMPA predicate device pathway investments to compress registration timelines for legacy instrument refreshes. For New Entrants and Emerging Players: Establish a beachhead in India's secondary city hospital networks where CDSCO harmonization accelerates market entry for predicate device portfolios. Target single-use shaver blades and cannulas in Maharashtra and Karnataka where reprocessing economics reshape purchasing decisions. Lead with infection control protocol compliance messaging to differentiate against incumbent reprocessing-dependent offerings. For Investors and Strategic Acquirers: Capital is best deployed toward visualization specialists with 3D-4K convergence capabilities and established PMDA software-as-medical-device registration expertise. The acquisition archetype combines optical precision IP with aftermarket service contract recurring revenue. Watch for inflection signals in ambulatory surgical center 4K platform adoption rates across Tokyo and Seoul.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Registration | Compresses approval timelines for AI-enabled diagnostic modules in Japan's ASC networks. |
| Hospital System Partnership | Secures multi-year full-suite contracts with Beijing and Shanghai centralized purchasing authorities. |
| Single-Use Device Portfolio Expansion | Captures procurement priority in South Korean ambulatory surgical centers with infection control protocols. |
| Aftermarket Service Unbundling | Creates recurring revenue streams from instrument calibration contracts independent of device sales. |
| 3D-4K Visualization Convergence | Enables outpatient procedures previously requiring inpatient admission in Japanese tertiary hospitals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of PMDA registration databases, NMPA clinical trial filings, hospital procurement contract disclosures, and GPO pricing benchmarks. Interviews with orthopedic surgeons, biomedical engineering directors, hospital purchasing committee members, and regional distribution executives informed demand-side validation. Secondary sources include CDSCO predicate device harmonization guidelines, MFDS software classification frameworks, and customs trade data for optical component flows. Bottom-up procedure volume estimates triangulate against top-down capital equipment shipment data.
Forecast inputs span product type segmentation across shavers, visualization systems, and single-use devices; end-user categories from tertiary hospitals to ambulatory surgical centers; and technology tiers distinguishing 2D legacy towers from 3D-4K convergence platforms. CAGRs derive from installed base replacement cycle analysis and procedure volume expansion trajectories. Modeling incorporates regulatory approval timeline differentials between PMDA streamlined pathways and NMPA domestic clinical trial mandates.
Sensitivities concentrate around NMPA registration timeline extensions for novel visualization technologies and optical component supply disruptions from East Asian manufacturing zone logistics constraints. Forecasts reflect assumptions on surgeon training program capacity expansion and ASC site-of-care migration rates. Quarterly review of PMDA software-as-medical-device classification updates and tier-one Chinese hospital tender award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Blood Thawing System Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
C-Arms Devices Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Vascular Guidewires Market
Medical Devices
India Hemostats Market
Medical Devices
Cervical Implants Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market