
 Global Wearable Injector Devices Market | 2026-2036
Global Wearable Injector Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wearable Injector Devices Market Outlook
A capital-intensity divergence between large-platform manufacturers and specialized subsystem suppliers is redrawing competitive boundaries in wearable injectors. Medtronic leverages its vertically integrated pump ecosystem to dominate insulin delivery with captive sensor and algorithm stacks. Enable Injections specializes in large-volume on-body delivery systems, anchoring partnerships with biopharma companies seeking alternatives to intravenous infusion. Ypsomed competes through modular platform architectures that extend across diabetes, fertility, and growth hormone therapy.
Wearable injector devices are electromechanical drug delivery systems worn on the body that administer therapeutic doses over extended periods through subcutaneous cannulas or microneedles, typically incorporating sensors, wireless telemetry, and programmable microprocessors to enable patient-controlled or closed-loop administration. These devices serve primary commercial purposes in chronic disease management by replacing clinic-based injections with ambulatory self-administration, reducing healthcare utilization while improving therapeutic adherence. Insulin pumps occupy the most mature margin pool among product types, though smart injectors with integrated dose verification and connectivity are gaining fastest. Home care dominates end-user demand structurally, while diabetes management remains the largest application segment even as vaccine delivery and hormone therapy applications diversify revenue sources.
The FDA regulates wearable injectors as combination products under its Center for Devices and Radiological Health, requiring human factors validation and software premarket submissions that lengthen development timelines but raise barriers to commoditized entry. EMA's Medical Device Regulation and the EU AI Act impose additional conformity requirements on algorithm-driven dosing systems, shaping R&D investment toward European market access. Japan's PMDA maintains distinct pharmaceutical-medical device interface standards that manufacturers must navigate for reimbursement listing. Stakeholders must monitor how evolving software-as-a-medical-device classifications in major jurisdictions reshape liability frameworks and post-market surveillance obligations.
Market Dynamics
Biologics manufacturers are consolidating drug-device development partnerships, compressing supplier selection timelines from multi-year qualification cycles to 18-month platform commitments that favor modular subsystem providers over turnkey device houses.
Growth Catalysts
- EMA's MDR and EU AI Act convergence:The European regulatory framework for algorithm-driven dosing systems is accelerating investment in closed-loop insulin delivery platforms that demonstrate real-time adaptive control.
- Subcutaneous large-volume biologics:Oncology and immunology drug developers are migrating infusion-compatible therapies to on-body delivery, expanding addressable patient populations beyond clinic-dependent administration.
- Japan's PMDA reimbursement alignment:The national health technology assessment body has streamlined listing pathways for wearable devices demonstrating adherence improvement in diabetes management.
Market Restraints
- Precision molding supply concentration:Medical-grade polymer component fabrication for drug-contact surfaces depends on a narrow base of German and Swiss toolmakers, creating single-source vulnerability for scaled production.
- FDA combination product review timelines:The Center for Devices and Radiological Health's human factors validation requirements extend premarket submission cycles, compressing competitive windows for first-mover advantage.
- Intravenous infusion substitution persistence:Hospital formulary committees retain preference for IV administration in acute care settings, limiting wearable injector penetration in oncology induction therapy.
Strategic Opportunities
- India's PLI scheme for medical devices:The production-linked incentive program is attracting contract manufacturing investment for export-oriented wearable injector assembly, reducing landed cost structures for European and North American markets.
- Closed-loop hormone therapy:Fertility and growth hormone applications are adopting sensor-integrated delivery systems that enable automated dose titration based on biomarker feedback.
- Direct-to-patient distribution channels:Specialty pharmacy networks are bypassing traditional wholesale distribution for chronic disease devices, capturing adherence data that informs payor contracting.
Industry Challenges
- Embedded software validation talent scarcity:Firmware engineering for Class II/III medical devices requires dual competency in IEC 62304 compliance and real-time control systems, constraining development velocity for algorithm-intensive platforms.
- Multi-jurisdiction post-market surveillance fragmentation:Manufacturers must maintain parallel vigilance systems for FDA adverse event reporting, EMA's Eudamed database, and PMDA's pharmaceutical safety monitoring, multiplying compliance overhead.
- Legacy electronic health record integration:Hospital procurement committees demand seamless data exchange with Epic and Cerner systems, forcing device developers to absorb interoperability certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wearable Injector Devices Market |
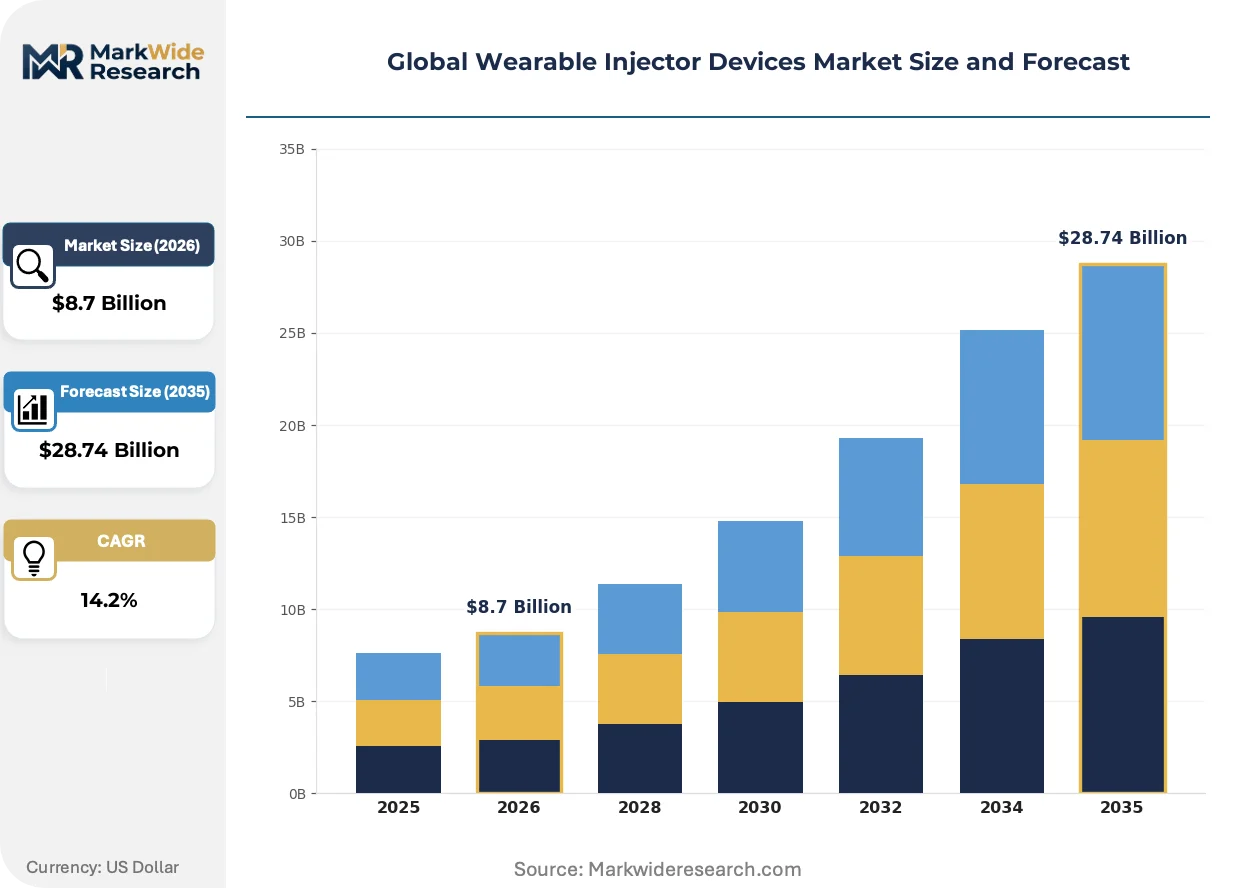
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Autoinjectors, Infusion Pumps, Smart Injectors End User: Home Care, Hospitals, Clinics, Rehabilitation Centers Technology: Microchip Technology, Wireless Connectivity, Smart Sensors, Depot Technology Application: Diabetes Management, Pain Management, Hormone Therapy, Vaccine Delivery |
| Companies Covered | Medtronic, Insulet Corporation, Becton, Dickinson and Company, West Pharmaceutical Services, Inc., Amgen Inc., Enable Injections, Ypsomed, Tandem Diabetes Care, Inc., Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wearable Injector Devices Market Strategic Shifts
Microneedle array technology is compressing the boundary between transdermal patches and active infusion systems, enabling biologics delivery without cannula insertion trauma. This convergence is reshaping patient acceptance metrics and expanding pediatric and needle-phobic populations.
Silicon microneedle fabrication is decomposing the traditional distinction between passive diffusion and active pumping in wearable delivery. Pediatric endocrinology departments are adopting these platforms for growth hormone therapy at threefold the rate of conventional pump adoption. The technology is decomposing incumbent cannula-based architectures by eliminating insertion pain and reducing site rotation requirements.
REACH and RoHS substance restrictions are forcing reformulation of device polymers and electronic components for European market access. Manufacturers are substituting halogen-free flame retardants and bisphenol-A-free housing materials to maintain CE marking eligibility. Diabetes management devices face the steepest compliance burden given their direct skin-contact duration and disposal volume.
Hospital procurement committees are consolidating vendor relationships through multi-year device-and-drug bundled contracts that lock in formulary position. Specialty pharmacy distributors are displacing traditional medical device wholesalers in insulin pump fulfillment, capturing patient data streams that inform pharmaceutical adherence programs. Germany's statutory health insurance funds are most advanced in this consolidation, requiring integrated outcomes reporting for reimbursement continuation.
Global Wearable Injector Devices Market Segmentation
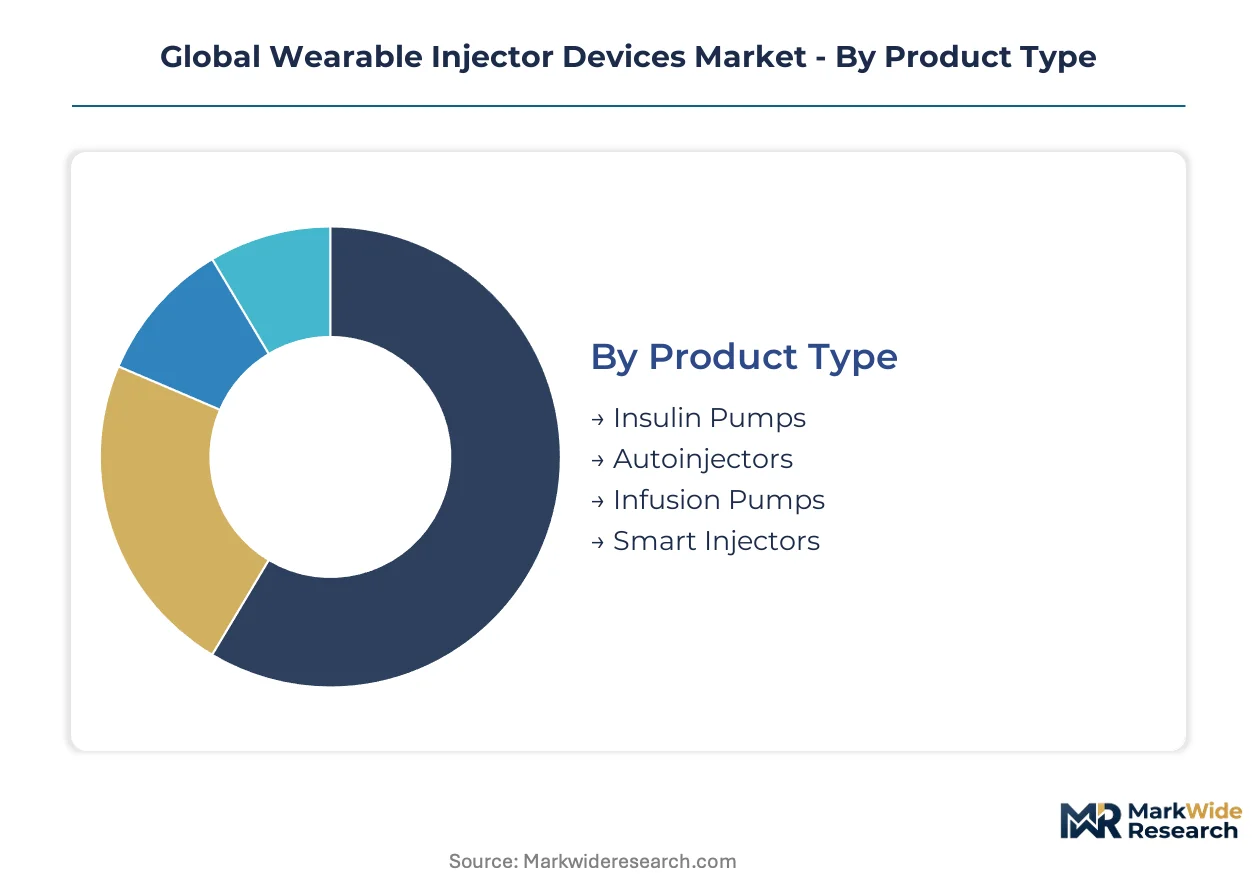
Wearable injector segmentation reflects divergent regulatory pathways across combination product categories. FDA's Center for Devices and Radiological Health applies distinct premarket review intensities based on algorithmic complexity and drug-device integration depth, fragmenting competitive positioning by technical tier.
Product Type:
EMA's MDR classification tiers separate active therapeutic devices from passive delivery systems, reshaping conformity assessment burdens and time-to-market economics across mechanical and electromechanical platforms.
- Insulin Pumps:Closed-loop systems integrate continuous glucose monitors with algorithm-driven basal-bolus automation. Demand concentrates in Germany and the United States where statutory reimbursement covers sensor-augmented pump therapy. FDA's breakthrough device designation pathway accelerates approval for predictive low-glucose suspend features.
- Smart Injectors:Dose-capture devices with Bluetooth telemetry and adherence logging are expanding fastest in Japan's diabetes management protocols. PMDA's streamlined listing for connectivity-enabled devices reduces time-to-reimbursement versus conventional pump categories.
- Autoinjectors:Spring-powered disposable systems dominate biologics self-administration for immunology indications.
- Infusion Pumps:Large-volume on-body reservoirs serve oncology and immunology subcutaneous migration from intravenous protocols.
Established volume favors insulin pumps; emerging adoption favors smart injectors.
End User:
Cost tier stratification separates capital-intensive hospital procurement from recurring home care consumables, with divergent margin structures and sales cycle durations.
- Home Care:Patient-directed administration dominates chronic disease wearable injector demand structurally. Germany's statutory health insurance funds mandate integrated outcomes reporting for reimbursement continuation, favoring devices with adherence telemetry.
- Hospitals:Acute care settings retain preference for intravenous infusion in oncology induction therapy, limiting wearable penetration to step-down protocols. Epic and Cerner interoperability certification requirements absorb significant device development overhead.
- Clinics:Outpatient specialty centers serve as training hubs for patient transition to home-based self-administration.
- Rehabilitation Centers:Post-acute facilities deploy wearable injectors for pain management during recovery protocols.
Recurring revenue concentrates in home care; capital sales concentrate in hospitals.
Technology:
Supply concentration in firmware engineering talent constrains development velocity for algorithm-intensive platforms, segmenting competitive capability by embedded software competency.
- Smart Sensors:Real-time biomarker feedback enables closed-loop dose titration for hormone therapy applications. Pediatric endocrinology departments in the United States adopt sensor-integrated growth hormone platforms at accelerated rates.
- Wireless Connectivity:Bluetooth Low Energy and cellular telemetry transmit adherence data to specialty pharmacy networks. Japan's PMDA reimbursement alignment favors connectivity-enabled devices demonstrating compliance improvement.
- Microchip Technology:Programmable microprocessors govern electromechanical drug delivery timing and volume accuracy.
- Depot Technology:Long-acting formulation compatibility extends dosing intervals for psychiatric and contraceptive applications.
Sensor integration commands premium positioning; wireless modules scale across price tiers.
Application:
Maturity gradients separate decades-established diabetes management from emerging vaccine delivery modalities, with divergent clinical evidence requirements and payor contracting dynamics.
- Diabetes Management:The most established commercial segment with mature reimbursement pathways across United States Medicare, German GKV, and Japanese NHI systems. FDA's human factors validation requirements for pump interfaces extend development timelines but raise competitive barriers.
- Vaccine Delivery:Microneedle array platforms are gaining traction for mass immunization campaigns. India's PLI scheme for medical devices attracts contract manufacturing investment for export-oriented assembly, reducing landed costs for European procurement.
- Pain Management:Opioid-sparing local anesthetic delivery targets post-surgical recovery protocols.
- Hormone Therapy:Fertility and growth hormone applications adopt automated dose titration based on biomarker feedback loops.
Diabetes management anchors revenue scale; vaccine delivery offers steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement generosity creates the widest demand elasticity gaps across national markets. Germany and Japan exhibit low price sensitivity due to statutory coverage, while India and Brazil face acute out-of-pocket pressure that compresses device margins.
United States
Medicare's expanded coverage for continuous glucose monitor-integrated pumps drives volume concentration in diabetes management. FDA's breakthrough device designation pathway accelerates approval timelines for predictive low-glucose suspend features. The Minneapolis-St. Paul corridor anchors insulin pump engineering talent and manufacturing infrastructure.
Germany
Statutory health insurance funds mandate integrated outcomes reporting for reimbursement continuation, favoring adherence-telemetry devices. EMA's MDR classification tiers impose conformity assessment burdens that reshape competitive positioning. Baden-Württemberg hosts precision polymer tooling clusters serving drug-contact surface fabrication.
Japan
PMDA's streamlined listing pathways for connectivity-enabled devices reduce time-to-reimbursement versus conventional pump categories. METI's medical device promotion programs accelerate domestic adoption of closed-loop hormone therapy platforms. The Kansai region concentrates pharmaceutical-medical device interface standards expertise.
India
The PLI scheme for medical devices attracts contract manufacturing investment for export-oriented wearable injector assembly. CDSCO's evolving combination product guidelines shape local regulatory strategy for multinational market entrants. Gujarat's medical device parks offer tariff-advantaged production bases for European and North American supply.
Switzerland
Swissmedic maintains distinct pharmaceutical-medical device interface standards that manufacturers navigate for European market access. REACH and RoHS substance restrictions force reformulation of device polymers for CE marking eligibility. The Basel-Zurich corridor concentrates large-volume biologics delivery system development partnerships.
Global Wearable Injector Devices Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the wearable injector landscape. The market structure consolidates around vertically integrated pump ecosystems and modular subsystem specialists rather than fragmented component vendors. Three archetypes dominate: captive platform operators with sensor-algorithm stacks, large-volume on-body delivery specialists, and modular architecture providers spanning multiple therapeutic areas. Strategic moves concentrate on drug-device partnership compression and European regulatory pre-positioning for MDR-AI Act convergence.
Within the captive platform tier, Medtronic anchors insulin delivery dominance through vertically integrated manufacturing. Enable Injections and Ypsomed occupy positions as modular subsystem anchors for biopharma partnership models. These three exemplify the divergence between electromechanical integration depth and partnership flexibility that defines competitive positioning.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Becton, Dickinson and Company |
| West Pharmaceutical Services, Inc. |
| Amgen Inc. |
| Enable Injections |
| Ypsomed |
| Tandem Diabetes Care, Inc. |
| Gerresheimer AG |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German and Swiss precision polymer toolmakers sits above threshold levels, compressing component availability for drug-contact surfaces while simultaneously elevating price floors for medical-grade device housings. This scale-concentration dynamic tethers pricing power to mold fabrication slots rather than finished device assembly, forcing manufacturers to absorb upfront tooling costs or accept extended lead times that reshape working capital requirements.
Pricing Analysis
Consumables and extended service contracts drive lifetime value in wearable injector economics, with recurring revenue streams from sensor cartridges and adhesive patches exceeding initial device margins by substantial multiples. Three-tier pricing structure across premium closed-loop systems, standard sensor-augmented pumps, and economy disposable autoinjectors segments buyer tiers by reimbursement generosity and clinical indication complexity. Pricing pressure stems from India's PLI scheme attracting export-oriented contract manufacturing, compressing landed costs for European and North American procurement. Hospital procurement committees exhibit lowest price sensitivity due to bundled device-and-drug contracts, while out-of-pocket markets in Brazil and India face acute margin compression.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underscores petroleum-derived polymer feedstock exposure for medical-grade device housings, with halogen-free flame retardant formulations compounding raw material scarcity. Component fabrication concentrates in Germany, Switzerland, and the United States for precision-molded drug-contact surfaces and sensor microelectronics. Supply chain risk centers on single-source dependency for IEC 62304-compliant firmware engineering talent, constraining development velocity for algorithm-intensive platforms. Distribution runs through specialty pharmacy networks displacing traditional medical device wholesalers, capturing patient adherence data streams that inform pharmaceutical partnership terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering competency for Class II/III medical devices represents the critical scarcity constraint, with dual proficiency in IEC 62304 compliance and real-time control systems bottlenecking platform development velocity across incumbent and entrant archetypes alike.
For Market Incumbents: Fortify captive sensor-algorithm stacks through backward integration into continuous glucose monitor fabrication, insulating margin pools from modular subsystem suppliers. Deepen hospital system partnerships by absorbing Epic and Cerner interoperability certification costs, locking in formulary position against emerging connectivity-enabled challengers. EMA's MDR-AI Act convergence threat demands preemptive conformity investment in closed-loop adaptive control documentation. For New Entrants and Emerging Players: Differentiate on microneedle array platforms for pediatric growth hormone therapy, where needle-phobia reduction commands premium positioning and threefold adoption rates versus conventional pumps. Target India's PLI scheme for tariff-advantaged export assembly, leveraging Gujarat medical device parks as production bases for European procurement. Direct-to-patient specialty pharmacy distribution offers the most penetrable go-to-market channel, bypassing entrenched wholesaler relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular subsystem specialists with biopharma partnership pipelines over vertically integrated pump ecosystems facing regulatory renewal cycles. Long-term viability over the coming decade hinges on European market access pre-positioning for algorithm-driven dosing systems. Acquisition target archetype: firmware engineering teams with IEC 62304 Class III validation track records. The signal to watch is FDA breakthrough device designation velocity for predictive low-glucose suspend features as inflection indicator for closed-loop platform competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Accelerates review timelines for predictive low-glucose suspend algorithms against standard PMA pathways. |
| EMA MDR-AI Act Conformity Pre-Positioning | Secures European market access for algorithm-driven dosing systems before regulatory enforcement tightens. |
| Biopharma Drug-Device Partnership Compression | Captures 18-month platform commitments as supplier selection cycles shorten from multi-year qualifications. |
| Specialty Pharmacy Distribution Integration | Bypasses traditional wholesalers to capture adherence telemetry data informing payor contracting leverage. |
| IEC 62304 Firmware Engineering Acquisition | Addresses talent scarcity constraining development velocity for closed-loop adaptive control platforms. |
Study Parameters
The analysis maps insulin pump ecosystems, smart injector platforms, autoinjector systems, and large-volume on-body delivery devices, each validated through regulatory affairs leads at FDA, EMA, and PMDA, biomedical engineers at hospital purchasing committees, and formulary directors at German statutory health insurance funds. Primary interviews with GPO contracts managers and continuous glucose monitor integration specialists combined with secondary validation against FDA 510(k) and PMA filings, EMA MDR technical documentation, PMDA reimbursement listing databases, and hospital procurement contract awards. Bottom-up device shipment modeling and top-down biologics manufacturer partnership analysis provided cross-verification.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including product type tier, end-user setting, connectivity technology level, and therapeutic application area, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from fitted growth curves applied to validated base-year estimates, incorporating biologics pipeline migration to subcutaneous delivery and reimbursement pathway expansion as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough designation velocity, EMA MDR enforcement consistency, and biopharma partnership cycle compression would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline stability and reimbursement generosity continuity. Practitioners should keep alternative scenarios live as algorithm classification standards and software-as-a-medical-device liability frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Medical Thermometer Market
Medical Devices
Low Vision Aids Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Intravascular Warming Systems Market