
 Infusion Catheters Market | 2026-2036
Infusion Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Infusion Catheters Market Foresight
Polyurethane is realigning material economics in infusion catheter manufacturing as device makers shift from PVC toward higher-biocompatibility polymers. Becton Dickinson and Company leverages its vertically integrated polymer compounding to sustain margin control across peripheral and central line portfolios. Terumo Corporation anchors its position through specialized coating technologies that reduce thrombogenicity in long-dwell catheters.
Infusion catheters are flexible, hollow tubes inserted into vascular or neuraxial spaces to deliver fluids, medications, or nutrients directly into the bloodstream or epidural space, typically manufactured via extrusion of medical-grade polymers with luminal diameters ranging from 14 to 24 gauge. Central venous catheters occupy the highest value tier due to intensive care dependency and infection-risk premiums, while home healthcare represents the fastest-expanding end-user channel as payors push ambulatory infusion for chemotherapy and parenteral nutrition. Peripheral catheters dominate unit volume but face commoditization pressure from group purchasing organization contracts.
The FDA regulates infusion catheters as Class II medical devices requiring 510(k) clearance, while ISO 10555 sets dimensional and performance benchmarks for intravascular catheters that manufacturers must meet for CE marking under the EU MDR. These frameworks elevate barriers for new entrants without established quality management systems and compel incumbents to maintain redundant regulatory dossiers across jurisdictions. Stakeholders must monitor how the EU MDR's heightened clinical evidence requirements for vascular access devices will reshape competitive access to European hospital systems.
Market Dynamics
Hospital procurement consolidation in the United States is compressing supplier margins and forcing catheter manufacturers to restructure their commercial operations around group purchasing organization compliance and volume-commitment contracts rather than traditional device-by-device sales.
Growth Catalysts
- EU MDR clinical evidence mandates:The European Union's Medical Device Regulation is elevating barriers for low-quality competitors, creating protected market access for manufacturers with robust clinical dossiers and quality management systems.
- Oncology clinic expansion:Outpatient chemotherapy centers across the United States are scaling catheter-based infusion delivery as first-line care, generating sustained demand for long-dwell central venous access devices.
- Polyurethane material transition:Device makers are abandoning PVC in favor of higher-biocompatibility polymers that reduce thrombogenicity and extend catheter dwell times in intensive care settings.
Market Restraints
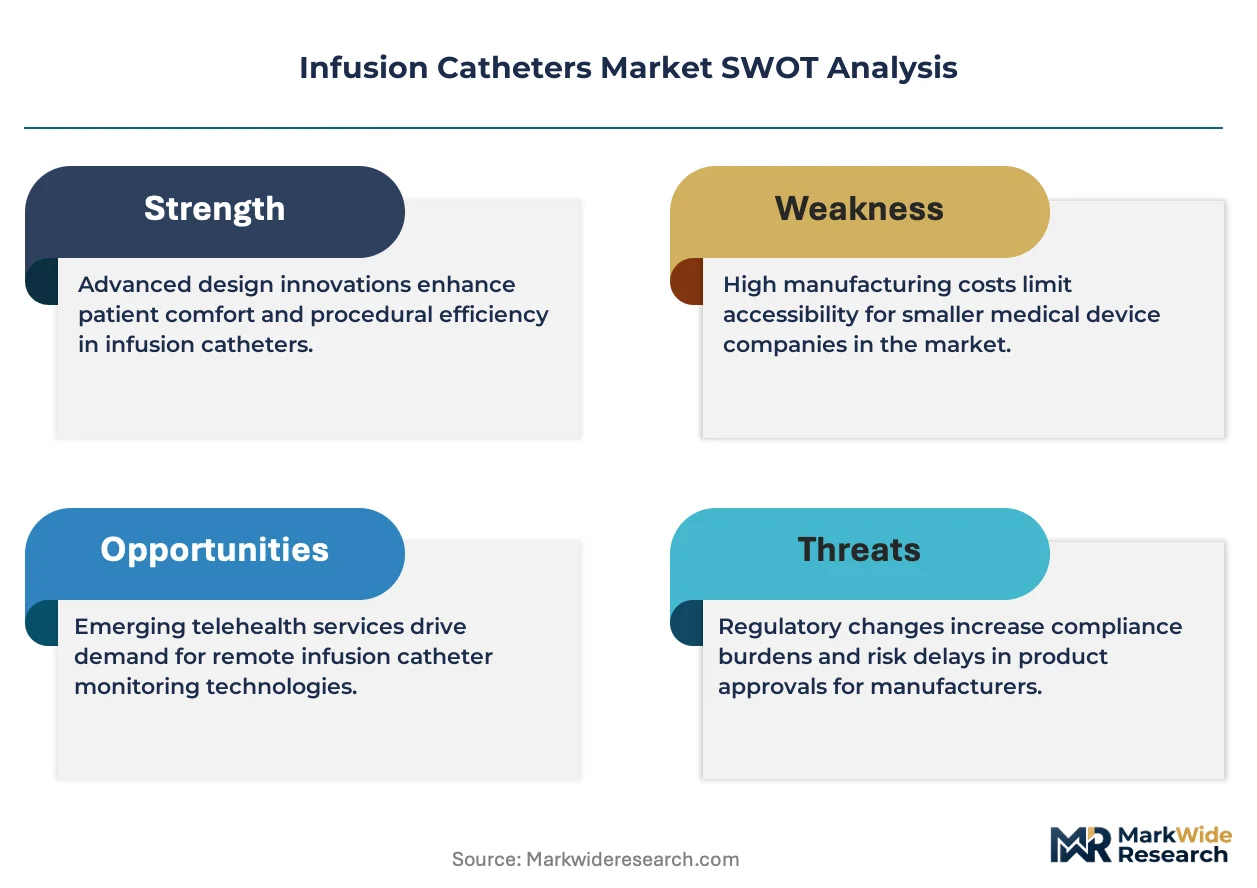
- Medical-grade polymer supply concentration:Specialty polyurethane compounding capacity clusters among a handful of European and North American chemical suppliers, exposing catheter manufacturers to input price volatility and allocation risk.
- FDA 510(k) pathway friction:Novel coating technologies and antimicrobial integrations face extended review timelines as the agency applies heightened scrutiny to predicate device equivalence claims for vascular access products.
- Peripheral catheter commoditization:Standard short-term intravenous catheters face margin erosion from undifferentiated Asian manufacturing and hospital GPO contracts that prioritize unit cost over performance differentiation.
Strategic Opportunities
- Home healthcare channel development:Parenteral nutrition and chemotherapy patients in the United States are transitioning to ambulatory infusion, creating demand for patient-managed vascular access devices with integrated safety features.
- Antimicrobial coating convergence:The intersection of sustained-release pharmaceutical formulations and polymer surface engineering is enabling next-generation infection-resistant catheters that command premium positioning in hospital systems.
- ISO 10555 harmonization:Alignment between FDA clearance requirements and international dimensional standards is streamlining dual-market entry for manufacturers targeting both United States and European Union hospital procurement.
Industry Challenges
- Biocompatibility testing capacity constraints:ISO 10993 cytotoxicity and sensitization studies face bottlenecks at contract research organizations, extending product development timelines for novel material formulations.
- Legacy electronic health record integration:Smart catheter technologies with embedded sensors require costly interoperability engineering to connect with hospital information systems that lack standardized device data protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infusion Catheters Market |
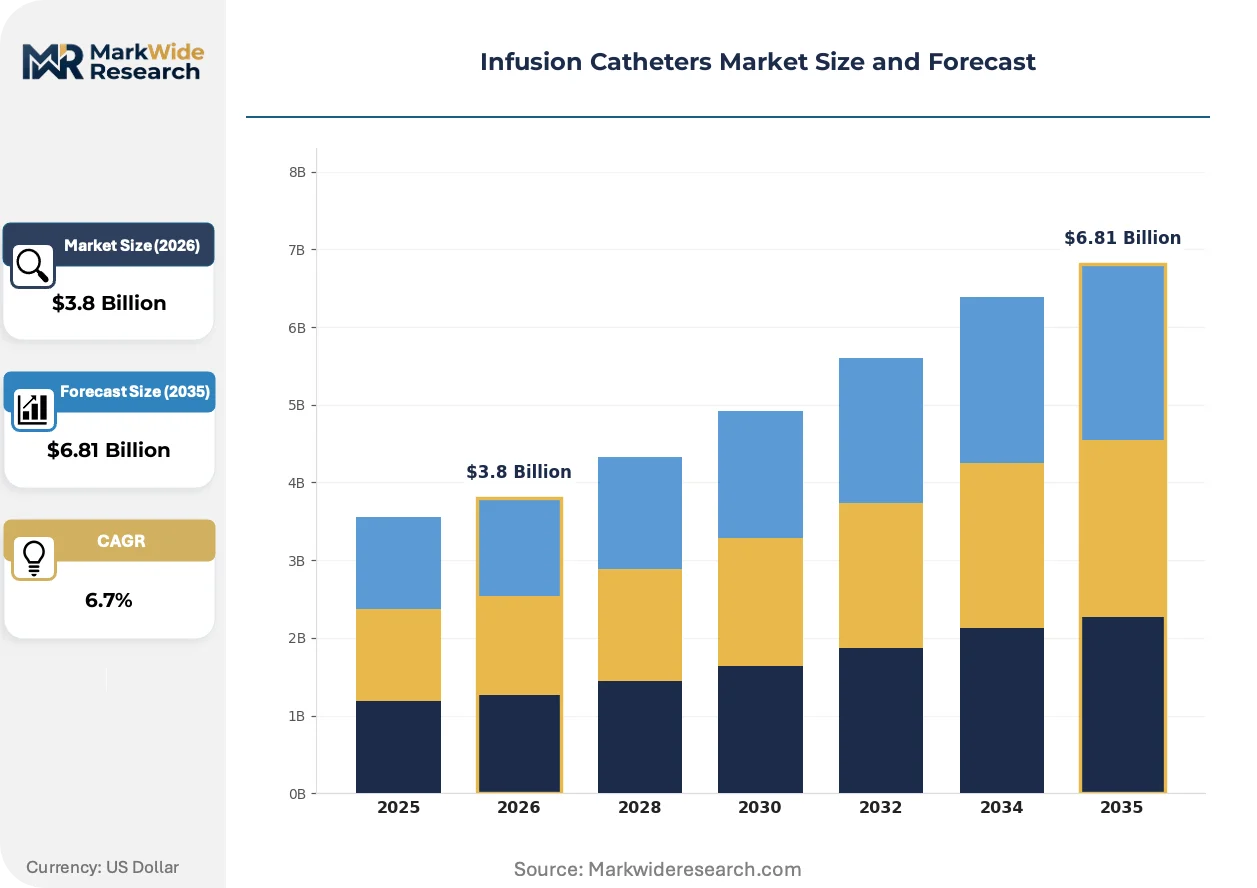
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peripheral Catheters, Central Venous Catheters, Implantable Ports, Epidural Catheters End User: Hospitals, Clinics, Home Healthcare, Ambulatory Surgical Centers Material: Polyurethane, Silicone, PVC, PTFE Application: Complication Treatment, Pain Management, Fluid Administration, Chemotherapy |
| Companies Covered | Becton Dickinson and Company, B. Braun Melsungen AG, ICU Medical, Teleflex, Medtronic, Baxter International, Terumo Corporation, Fresenius Kabi, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infusion Catheters Market Shifts & Advancements
Active material science breakthroughs and regulatory pathway evolution are compressing development cycles for next-generation vascular access devices while simultaneously elevating the clinical evidence threshold for market entry.
Antimicrobial-integrated polymers are unifying infection prevention and mechanical performance in a single catheter substrate. Intensive care units in tertiary hospitals are adopting these dual-function materials ahead of standard care protocols. The technology is unifying previously separate device categories—prophylactic-coated and standard catheters—into a single premium tier that commands higher reimbursement.
The FDA's updated 510(k) paradigm for vascular access devices is accelerating clearance timelines for incremental material improvements while demanding novel clinical data for breakthrough antimicrobial claims. Manufacturers are restructuring regulatory strategies to bifurcate submissions between predicate-reliant line extensions and de novo pathways for differentiated coating technologies. Peripheral catheter suppliers with limited clinical affairs capacity are retreating from novel material development toward established polymer platforms.
Hospital supply chain directors are consolidating infusion system procurement under single-source contracts that bundle catheters, pumps, and disposable sets. This purchasing transformation is displacing standalone catheter vendors who lack complementary device portfolios. The United States exhibits the most pronounced consolidation, with integrated delivery networks in Texas, California, and Florida driving standardization across dozens of affiliated facilities.
Infusion Catheters Market Segmentation
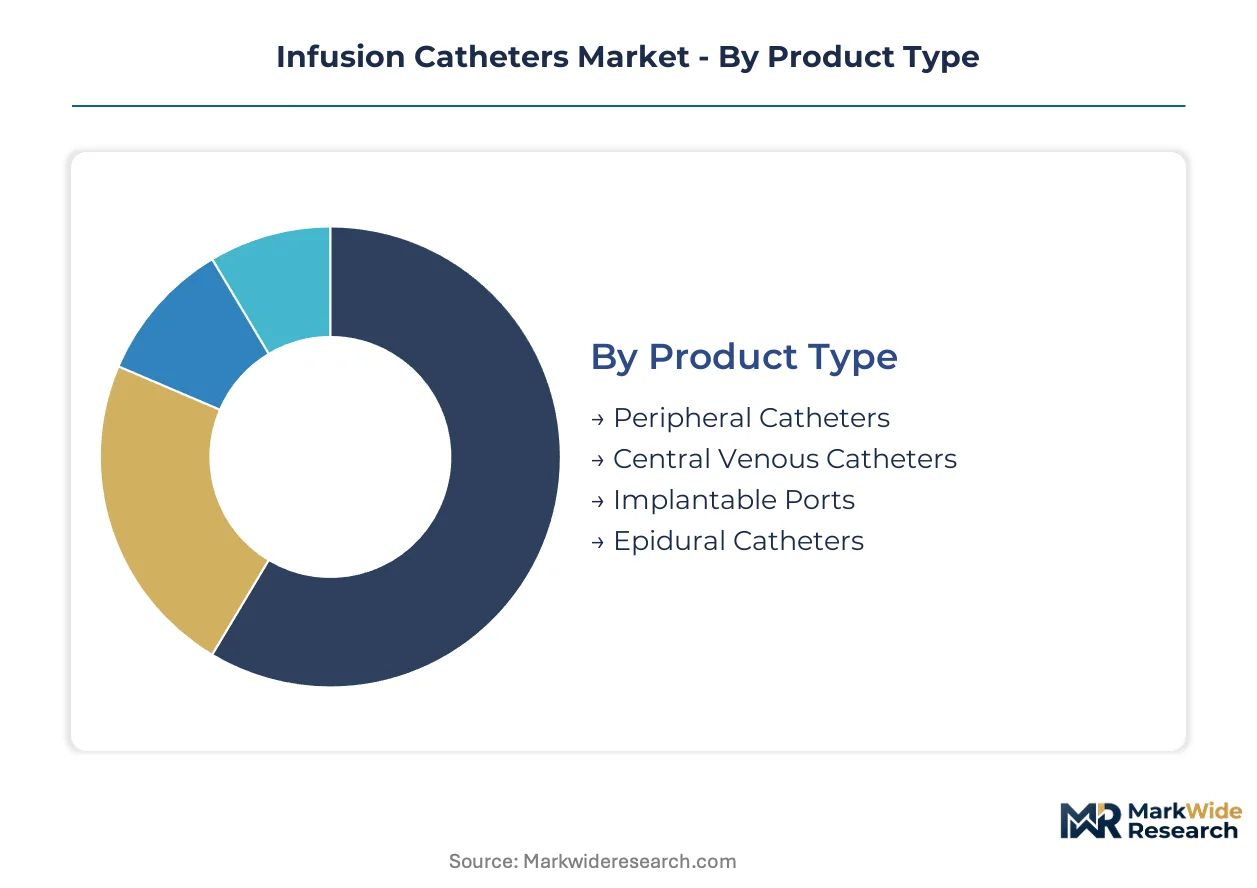
Infusion catheter segmentation reveals stark divergence between high-acuity hospital systems requiring long-dwell central access and the expanding ambulatory channel seeking patient-managed peripheral solutions. Material choices and application specificity determine reimbursement tiers and procurement consolidation vulnerability across each segment cluster.
Product Type:
Standalone vascular access devices dominate acute care workflows, while embedded implantable systems serve recurring therapy cycles in oncology and parenteral nutrition.
- Peripheral Catheters:Short-term intravenous devices manufactured via polymer extrusion in 14-24 gauge configurations. Hospital GPO contracts in the United States compress margins through volume-commitment purchasing, forcing suppliers toward undifferentiated Asian manufacturing or premium safety-engineered alternatives.
- Central Venous Catheters:Multi-lumen polyurethane or silicone constructs designed for intensive care dwell times exceeding seven days. Tertiary hospital systems in Texas and California pay infection-risk premiums for antimicrobial-integrated variants, sustaining the segment's highest value tier despite procurement consolidation pressure.
- Implantable Ports:Subcutaneous reservoir systems connected to central vasculature for recurring chemotherapy cycles.
- Epidural Catheters:Neuraxial delivery constructs for perioperative and chronic pain management.
Volume placements concentrate in Peripheral Catheters; the faster expansion belongs to Implantable Ports.
End User:
Cost tier stratification separates capital-intensive hospital infrastructure from lean ambulatory operators seeking disposable efficiency.
- Hospitals:Integrated delivery networks across Florida and California bundle catheter procurement with infusion pumps and disposable sets under single-source contracts. Safety-engineered designs with needlestick prevention mechanisms command preferential placement in these consolidated purchasing environments.
- Home Healthcare:Patient-managed vascular access for chemotherapy and parenteral nutrition transitions. United States payor pressure toward ambulatory reimbursement creates demand for catheters with integrated safety features and simplified flushing protocols.
- Clinics:Outpatient infusion centers scaling catheter-based chemotherapy delivery.
- Ambulatory Surgical Centers:Short-procedure facilities prioritizing rapid turnover and disposable cost minimization.
Procurement scale peaks in Hospitals; Home Healthcare is climbing the fastest as reimbursement shifts toward ambulatory settings.
Material:
Supply concentration among European and North American polymer compounders elevates input cost volatility and allocation risk across catheter manufacturing.
- Polyurethane:Higher-biocompatibility thermoplastic enabling extended dwell times and reduced thrombogenicity. Device makers leverage vertically integrated compounding to sustain margin control as the industry abandons PVC toward intensive care applications.
- Silicone:Soft, pliable polymer preferred for long-term implantable ports and pediatric applications. Specialized coating technologies from Japanese manufacturers reduce protein adhesion and extend functional catheter lifespan in oncology cycles.
- PVC:Legacy material facing abandonment due to plasticizer leaching concerns and regulatory pressure.
- PTFE:Low-friction fluoropolymer reserved for specialized guidewire-compatible introducer systems.
Manufacturing throughput centers on Polyurethane; Silicone is gaining share fastest in implantable and pediatric segments.
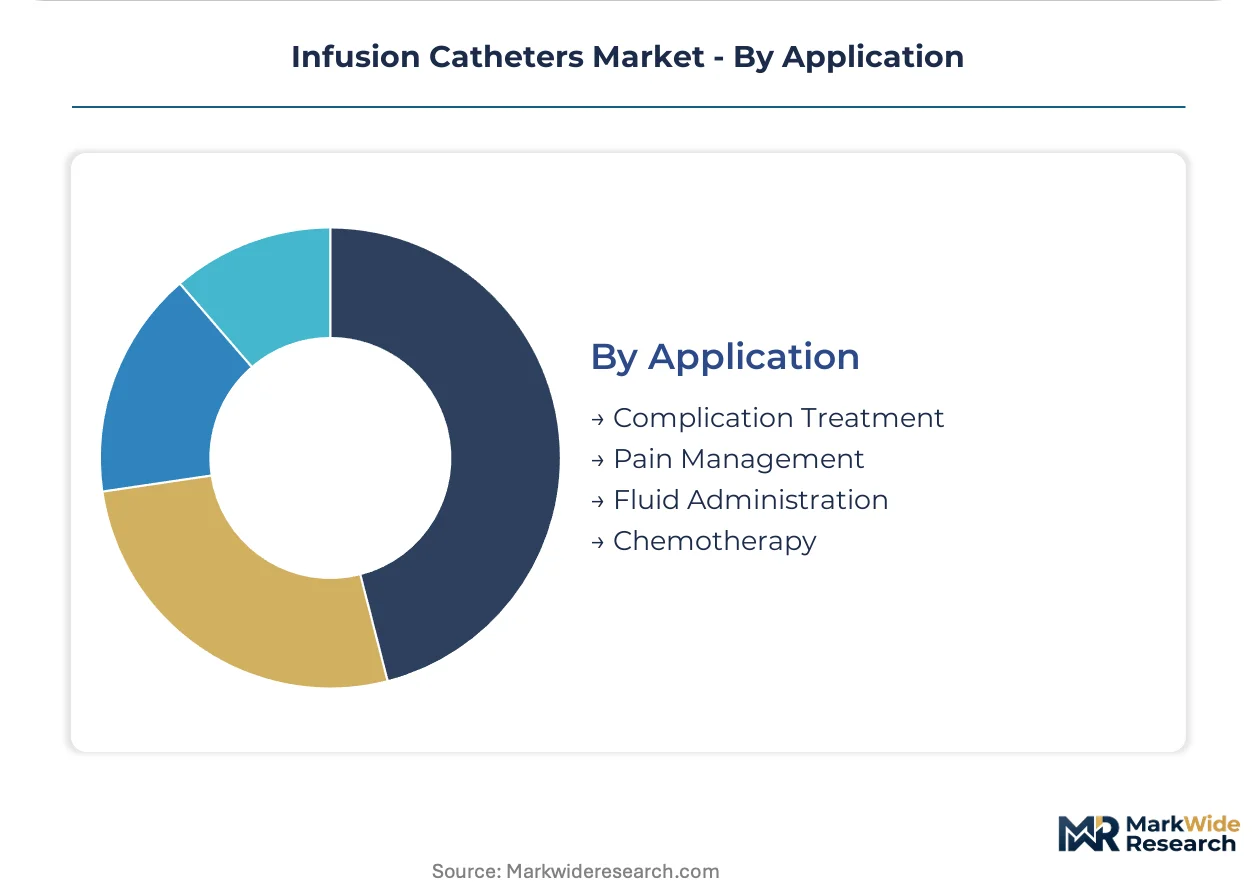
Application:
Clinical outcome specificity determines reimbursement coding and procurement priority across therapy categories.
- Chemotherapy:Long-dwell central access and implantable port systems for cytotoxic drug delivery. Oncology clinic expansion across the United States generates sustained demand for devices with validated compatibility against vesicant agents and pH extremes.
- Fluid Administration:High-volume resuscitation and maintenance intravenous therapy. Emergency departments and surgical suites drive commodity purchasing patterns with minimal performance differentiation beyond flow rate specifications.
- Pain Management:Epidural and peripheral nerve block catheter systems for acute and chronic therapy.
- Complication Treatment:Specialized constructs for thrombolysis, drainage, and rescue vascular access scenarios.
Procedure volume concentrates in Fluid Administration; Chemotherapy shows the steepest expansion trajectory as outpatient oncology scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation in the United States concentrates demand for safety-engineered infusion systems, while European regulatory elevation and Asian manufacturing scale reshape competitive access across major national markets.
United States
Integrated delivery networks in Texas, California, and Florida bundle catheter procurement with infusion pumps under single-source contracts. The FDA's updated 510(k) pathway compresses approval timelines for novel polyurethane materials while extending review for antimicrobial coating claims. Greater Boston anchors specialty coating development for long-dwell central venous devices.
Germany
Tertiary hospital systems in Bavaria and North Rhine-Westphalia pay infection-risk premiums for antimicrobial-integrated catheters in intensive care workflows. The EU MDR's heightened clinical evidence requirements for vascular access devices elevate barriers for low-quality competitors. The Rhine-Main cluster concentrates specialty polyurethane compounding capacity serving catheter manufacturers.
Japan
Long-dwell oncology applications drive demand for silicone-based implantable ports with reduced thrombogenicity. PMDA alignment with ISO 10555 dimensional standards streamlines dual-market entry for domestic manufacturers targeting United States hospital procurement. The Kansai region hosts specialized coating technology development for protein-resistant catheter surfaces.
China
Domestic hospital system expansion generates volume demand for peripheral catheters, while import substitution policies elevate local manufacturing of central venous devices. NMPA regulatory harmonization with international standards accelerates market access for multinational catheter suppliers. The Yangtze River Delta concentrates polymer extrusion capacity for medical-grade device production.
India
Outpatient chemotherapy center expansion in Maharashtra and Karnataka creates sustained demand for long-dwell vascular access devices. CDSCO's phased alignment with ISO 10993 biocompatibility testing standards elevates quality requirements for domestic and imported catheters. The Delhi-NCR corridor clusters contract manufacturing operations serving European and North American hospital procurement.
Infusion Catheters Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement in United States hospital systems favoring full-portfolio suppliers over standalone catheter vendors. The market structure tiers across premium antimicrobial-integrated devices, standard polyurethane platforms, and commodity peripheral lines. Three archetypes dominate: vertically integrated polymer compounders with captive device manufacturing, coating technology specialists licensing surface engineering to multiple OEMs, and scale-driven Asian fabricators serving GPO cost-minimization contracts. Competitive moves concentrate on strategic partnerships with integrated delivery networks and portfolio diversification into smart catheter technologies with embedded sensors.
Among diversified medical device conglomerates, Becton Dickinson and Company, B. Braun Melsungen AG, and Terumo Corporation occupy positions across multiple catheter segments. Becton Dickinson exemplifies the vertically integrated archetype through polymer compounding capabilities. B. Braun Melsungen AG represents European manufacturing scale with broad vascular access portfolios. Terumo Corporation anchors specialized coating expertise for thrombogenicity reduction in long-dwell applications.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| B. Braun Melsungen AG |
| ICU Medical |
| Teleflex |
| Medtronic |
| Baxter International |
| Terumo Corporation |
| Fresenius Kabi |
| Smiths Medical |
| Others |
Supply & Pricing Matrix
Polymer compounding chemists in the Rhine-Main cluster anchor cost structures that widen spreads between antimicrobial-integrated premium catheters and commodity peripheral lines. Labor-cost differentials between German specialty polymer facilities and Asian extrusion operations translate into tiered pricing that separates infection-risk premiums from GPO-driven unit-cost floors.
Pricing Analysis
Volume concentrates in peripheral catheters where margins compress under group purchasing organization contracts, while value accrues to central venous devices commanding infection-risk premiums. Price differentiation rests on antimicrobial coating certification and polyurethane biocompatibility grade. Cost compression in the peripheral tier intensifies because undifferentiated Asian manufacturing floods hospital procurement with interchangeable units. Ambulatory surgical centers exhibit highest price sensitivity; tertiary intensive care units show lowest sensitivity due to outcome-based reimbursement for complication reduction.
Supply Chain Analysis
Workforce availability for medical-grade polymer compounding constrains capacity expansion in Germany, the United States, and Japan where specialized chemist training programs feed catheter manufacturers. Raw material dependencies center on specialty polyurethane resins, silicone elastomers, and pharmaceutical-grade antimicrobial agents. Single-source vulnerability concentrates in European polymer compounders serving multiple catheter OEMs from limited production sites. Distribution runs through integrated delivery networks that bundle catheters with infusion pumps under single-source hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation functions as a consolidation play, forcing standalone catheter vendors without complementary device portfolios toward exit or acquisition by full-line suppliers.
For Market Incumbents:Hedge against peripheral catheter commoditization by deepening captive polyurethane compounding capacity in the Rhine-Main cluster and securing exclusive coating technology licenses from Japanese specialists. Group purchasing organization compliance investments and volume-commitment contract structures defend position against emerging Asian fabricators.
For New Entrants and Emerging Players:Home healthcare distributors represent the most accessible channel partner type for patient-managed vascular access devices with simplified flushing protocols. White-space targets include ambulatory chemotherapy infusion in Maharashtra and Karnataka where outpatient center expansion outpaces established supplier coverage. Reimbursement-aligned device design offers the strongest go-to-market angle.
For Investors and Strategic Acquirers:Re-rating potential sits with coating technology specialists given FDA antimicrobial claim scrutiny extending review timelines for competitors without established clinical dossiers. Long-term viability favors manufacturers with vertically integrated polymer compounding and validated EU MDR technical documentation. Watch antimicrobial-integrated catheter adoption rates in Texas and California integrated delivery networks as inflection indicator for premium-tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Single-source contracts with Texas and California integrated delivery networks lock out standalone competitors. |
| FDA 510(k) Submission | Novel polyurethane materials gain accelerated clearance under updated vascular access pathway guidance. |
| CE Marking Pathway | EU MDR clinical evidence mandates elevate barriers for low-quality competitors in German hospital procurement. |
| Backward Integration into Polymer Compounding | In-house specialty polyurethane production insulates margin control from European supplier allocation risk. |
| Reimbursement Strategy | Outcome-based coding for infection-resistant catheters captures premium positioning in Medicare hospital payments. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and hospital group purchasing organization contract records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee members, and regulatory affairs specialists at catheter manufacturers validated secondary findings. Bottom-up unit demand modeling and top-down revenue triangulation converged on segment-level estimates.
Historical trendline analysis of catheter placement volumes and material cost indices informed projection frameworks across the modeling period. Segmentation dimensions included product type, end-user channel, polymer material grade, and clinical application with regional regulatory cluster overlays. CAGRs derived from curve-fitting procedures applied to validated baseline data. Forecast inputs incorporated FDA review timeline patterns and EU MDR transition compliance rates among incumbent manufacturers.
Several conditions sit outside the modeled scope, including unforeseen polymer supply disruptions, abrupt reimbursement coding changes, and novel catheter-related complication litigation. Forecasts reflect documented assumptions about regulatory pathway stability and hospital procurement consolidation continuity. Material deviation in antimicrobial coating approval timelines or integrated delivery network merger activity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
Global Peripheral Stent Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Cardiac Sutures Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Resuscitation Bags Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Blood Fluid Warming System Market